
 Caprylic/Capric Triglyceride Market | 2026-2036
Caprylic/Capric Triglyceride Market Size, Share, and Industry Trends Forecast 2026-2036
Caprylic/Capric Triglyceride Market Analysis
Capital-intensity divergence between integrated oleochemical producers and specialty chemical blenders is bifurcating competitive returns across the Caprylic/Capric Triglyceride landscape. KLK Oleo leverages backward integration into palm kernel oil sourcing to sustain margin stability against feedstock volatility. Croda International Plc differentiates through pharmaceutical-grade certification and positions its portfolio toward high-purity cosmetic applications. Emery Oleochemicals anchors North American supply with dedicated esterification capacity serving regional personal care formulators.
Caprylic/Capric Triglyceride denotes a mixed triester of glycerol with caprylic (C8) and capric (C10) fatty acids, typically produced via enzymatic or chemical esterification of fractionated coconut or palm kernel oils, yielding a colorless, odorless liquid with low viscosity and excellent oxidative stability. The ingredient functions primarily as an emollient, solvent, and carrier oil across cosmetic, nutritional, and pharmaceutical formulations. Cosmetic-grade production leads volume output due to pervasive use in skincare and sun care, while pharmaceutical-grade commands superior unit economics through stringent purity thresholds and GMP compliance requirements. Food-grade applications retain steady demand from beverage and nutritional supplement manufacturers seeking clean-label lipid carriers.
REACH registration in Europe, FDA food-contact and pharmaceutical excipient standards in the United States, and EMA guidelines for active substance carriers collectively elevate compliance costs and filter sub-scale participants from commercial relevance. BIS quality specifications in India and China's GB standards for food additives further fragment market access requirements across manufacturing geographies. Stakeholders must monitor regulatory convergence between cosmetic and pharmaceutical purity standards to anticipate qualification barriers and capital allocation priorities.
Market Dynamics
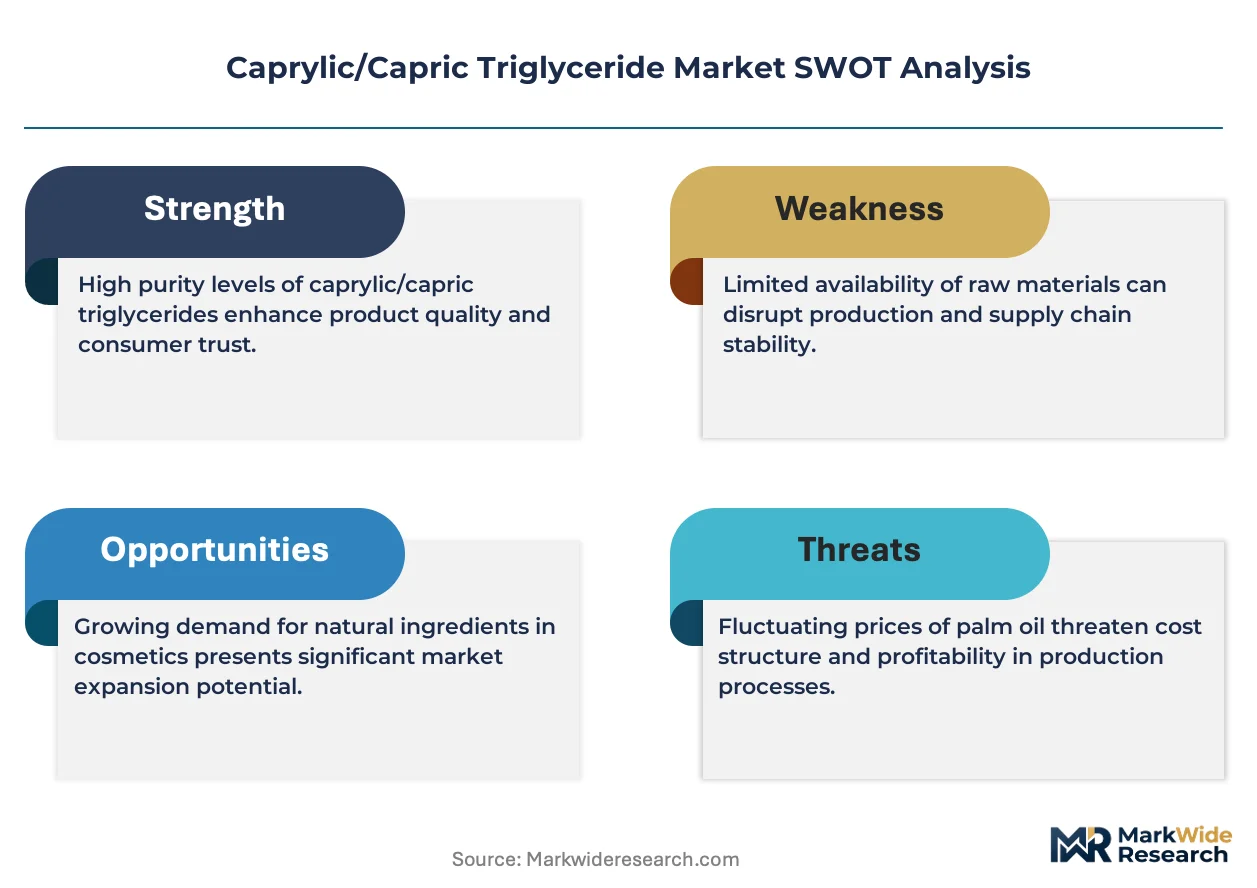
Enzymatic esterification technology is compressing batch cycle times and enabling pharmaceutical-grade purity thresholds that chemical catalysis cannot achieve, forcing capital reallocation across the Caprylic/Capric Triglyceride manufacturing base.
Growth Catalysts
- REACH registration thresholds:European cosmetic formulators are upgrading to pharmaceutical-grade CCT to preempt ECHA substance evaluation deadlines, tightening supply qualification standards.
- Clean-label beverage carriers:Nutritional supplement manufacturers in Germany and Japan are replacing synthetic emulsifiers with food-grade CCT for protein fortification applications.
- South Korean cosmetic R&D clusters:Seoul-based skincare innovators are driving specification intensity for ultra-low peroxide index grades in sun care and barrier repair formulations.
Market Restraints
- Palm kernel oil price volatility:Malaysian and Indonesian feedstock markets transmit cost instability directly to CCT producers lacking backward integration into plantation assets.
- Fractionation capacity concentration:Southeast Asian oleochemical hubs control over 70 percent of C8/C10 fatty acid supply, creating geographic single-point vulnerability.
- Glycerol ester substitution:Medium-chain triglyceride (MCT) oils and propylene glycol esters compete in nutritional and cosmetic solvent applications at lower unit costs.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO and BIS harmonization efforts are opening pathways for imported pharmaceutical-grade CCT in generic drug manufacturing.
- EMA active substance carrier guidelines:Updated EMA quality requirements for lipid-based drug delivery systems are expanding addressable market for high-purity CCT in European oncology formulations.
- Bio-based enzymatic process convergence:Integration of immobilized lipase technology with continuous flow reactor design is reducing solvent use and enabling carbon footprint certification.
Industry Challenges
- Pharmaceutical GMP certification timelines:FDA and EMA facility audits for excipient manufacturing extend 18-24 months, delaying market entry for new production assets.
- Specialized process engineering talent:Scarcity of enzymatic esterification scale-up expertise constrains technology transfer from pilot to commercial volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caprylic/Capric Triglyceride Market |
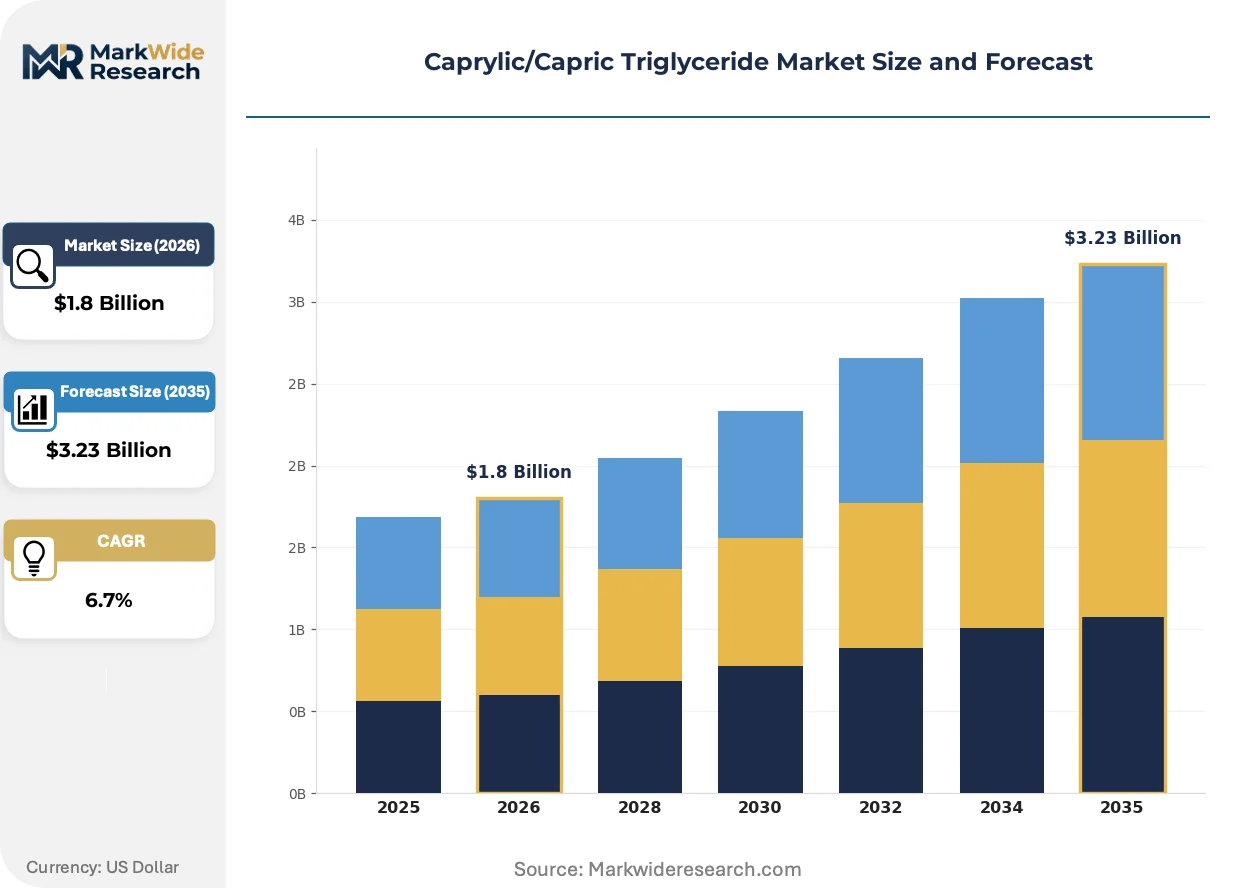
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Cosmetic Grade, Pharmaceutical Grade, Industrial Grade Application: Food & Beverage, Personal Care, Pharmaceuticals, Industrial Applications End User: Cosmetics Manufacturers, Food Manufacturers, Pharmaceutical Companies, Chemical Industry Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | KLK Oleo, Ecogreen Oleochemicals, Croda International Plc, Oxiteno, Emery Oleochemicals, Oleon NV, IOI Oleo GmbH, BERG + SCHMIDT GmbH & Co., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caprylic/Capric Triglyceride Market Emerging Trajectories
Process intensification and regulatory convergence are compressing the gap between cosmetic and pharmaceutical grade specifications, while buyer procurement models favor qualified suppliers with multi-regulatory dossiers.
Immobilized lipase biocatalysis is miniaturizing reactor footprints and enabling continuous processing of CCT with peroxide values below 1.0 meq O2/kg. Pharmaceutical excipient manufacturers in Switzerland and Germany are adopting this technology to meet USP-NF and Ph.Eur. monograph requirements. The shift is compressing capital requirements for entry-grade pharmaceutical production while raising purity barriers for incumbent chemical esterification assets.
REACH Annex XIV authorization procedures for medium-chain chlorinated paraffins are redirecting plasticizer demand toward bio-based alternatives including CCT-derived specialty esters. ECHA regulatory pressure is forcing reformulation across European PVC compounding and metalworking fluid applications. German chemical distributors are building dedicated CCT ester inventories to serve this displacement demand.
Specification-driven procurement is consolidating buyer relationships around suppliers with simultaneous FDA food-contact, USP-NF excipient, and REACH registration status. Large cosmetic formulators in France and the United States are reducing qualified vendor lists from 8-12 to 3-4 strategic partners. The concentration is most visible in premium skincare and dermocosmetic segments where traceability documentation requirements have become non-negotiable.
Caprylic/Capric Triglyceride Market Segmentation
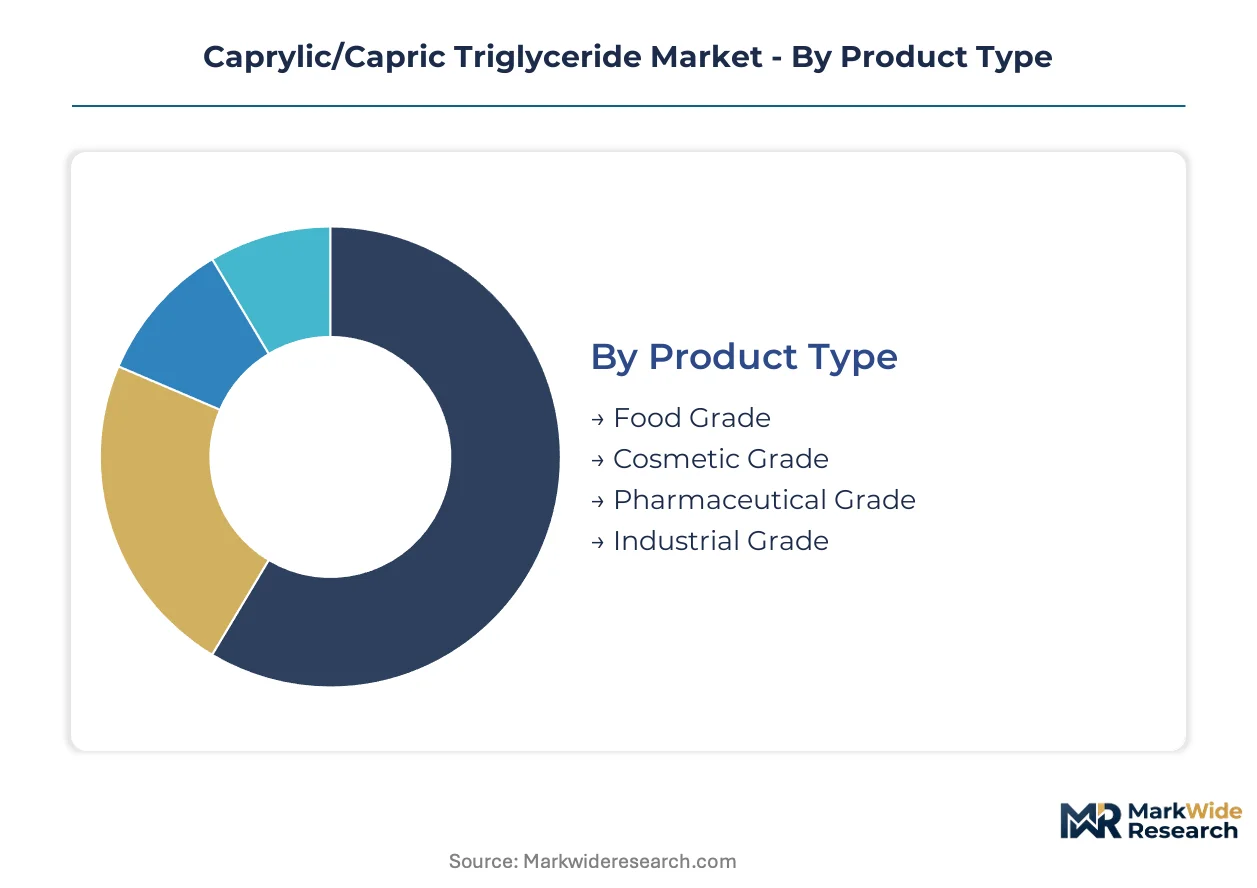
Grade purity thresholds and regulatory certification requirements fragment the Caprylic/Capric Triglyceride market into distinct value tiers. Each segment commands different qualification timelines, margin profiles, and geographic demand concentrations that shape supplier positioning strategies.
Product Type:
Cosmetic-grade production dominates domestic manufacturing volumes across France and the United States, while pharmaceutical-grade output concentrates in export-led facilities serving EMA and FDA-regulated markets. Food-grade capacity spreads across both domestic nutritional supplement producers and international beverage carriers.
- Cosmetic Grade:This segment comprises colorless, odorless triesters with peroxide values typically below 5.0 meq O2/kg, suitable for emollient and solvent applications in skincare formulations. Demand clusters in Seoul-based R&D facilities and Parisian dermocosmetic laboratories seeking ultra-low peroxide specifications for sun care and barrier repair products. South Korean formulators drive specification intensity through continuous batch qualification protocols.
- Pharmaceutical Grade:USP-NF and Ph.Eur. monograph compliance defines this tier, requiring peroxide values below 1.0 meq O2/kg and comprehensive impurity profiling for excipient use. German and Swiss manufacturers anchor production for lipid-based drug delivery systems in oncology applications, with EMA active substance carrier guidelines expanding addressable demand. GMP certification timelines of 18-24 months filter sub-scale participants from commercial relevance.
- Food Grade:Clean-label lipid carriers for protein fortification and beverage emulsification, meeting FDA food-contact standards and FSSAI specifications in India.
- Industrial Grade:Specialty ester feedstock for metalworking fluids and PVC plasticizer applications, gaining displacement demand from REACH-regulated chlorinated paraffin alternatives.
Cosmetic grade holds the largest share; momentum sits with pharmaceutical grade as EMA and FDA qualification barriers steepen.
Application:
Personal care absorption concentrates in domestic European and North American formulator networks, while pharmaceutical applications depend on export-qualified supply chains serving CDSCO-regulated markets in India.
- Personal Care:Emollient and carrier oil functions in skincare, sun care, and color cosmetics, with Seoul and Paris driving premium formulation innovation. South Korean cosmetic R&D clusters specify ultra-low peroxide grades for barrier repair segments.
- Pharmaceuticals:Excipient and active substance carrier roles in lipid-based drug delivery, with German oncology formulations expanding EMA-guided demand. Swiss and German manufacturers adopt immobilized lipase biocatalysis to meet USP-NF purity thresholds.
- Food & Beverage:Nutritional supplement carriers and clean-label beverage emulsifiers, with German and Japanese manufacturers replacing synthetic alternatives.
- Industrial Applications:Metalworking lubricants and PVC compounding plasticizers, with German chemical distributors building dedicated inventories for REACH-driven paraffin displacement.
Personal care generates the highest volume throughput; pharmaceuticals deliver the steepest expansion trajectory as oncology formulation demand climbs.
End User:
Cosmetics manufacturers source predominantly through domestic qualified vendor networks, while pharmaceutical companies require multi-regulatory dossiers that concentrate procurement around export-capable suppliers.
- Cosmetics Manufacturers:Large French and US formulators reduce qualified vendor lists from 8-12 to 3-4 strategic partners, prioritizing simultaneous FDA, USP-NF, and REACH registration status. Traceability documentation requirements have become non-negotiable in premium skincare segments.
- Pharmaceutical Companies:Generic drug manufacturers in India seek CDSCO-harmonized pharmaceutical-grade supply, while European oncology formulators demand EMA-compliant active substance carriers. Specification-driven procurement consolidates relationships around suppliers with multi-regulatory dossiers.
- Food Manufacturers:Nutritional supplement and beverage producers in Germany and Japan adopting food-grade CCT for protein fortification.
- Chemical Industry:PVC compounders and metalworking fluid blenders in Germany redirecting demand from chlorinated paraffins toward bio-based CCT esters.
Cosmetics manufacturers anchor current procurement volumes; pharmaceutical companies are gaining share fastest as excipient qualification pathways mature.
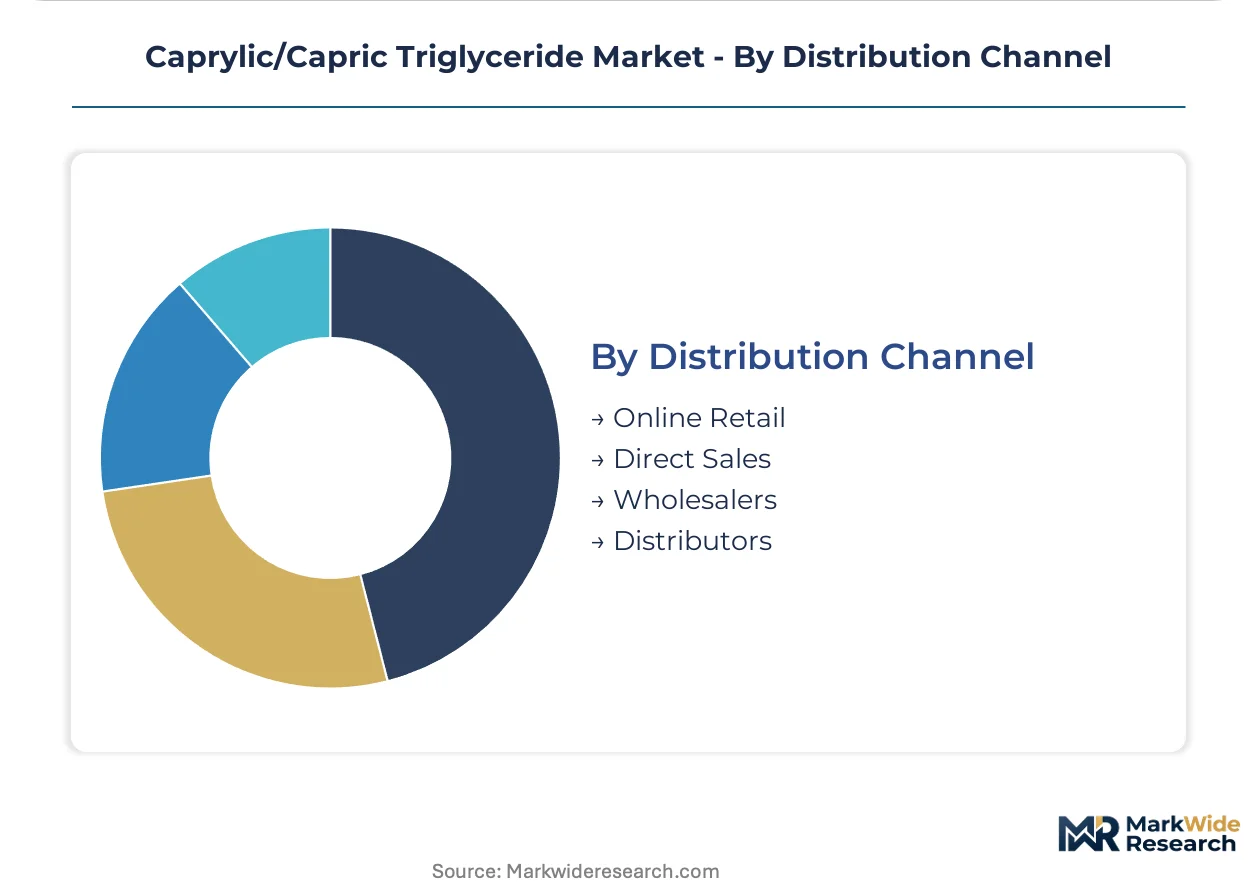
Distribution Channel:
Direct sales relationships dominate pharmaceutical and large cosmetics procurement, while online retail serves fragmented small-batch formulators and regional nutritional supplement producers.
- Direct Sales:Strategic partnerships between integrated oleochemical producers and tier-one formulators, with multi-year qualification protocols and dedicated supply allocations. KLK Oleo leverages backward integration into palm kernel oil sourcing to sustain margin stability through direct channels.
- Distributors:German chemical distributors building dedicated CCT ester inventories to serve REACH-driven displacement demand in PVC and metalworking applications. Regional coverage extends to mid-scale cosmetics manufacturers lacking direct supplier relationships.
- Wholesalers:Volume aggregation for food-grade and industrial-grade segments, with geographic concentration in Southeast Asian oleochemical hubs.
- Online Retail:Small-batch procurement for independent formulators and research-scale pharmaceutical developers, with limited penetration in GMP-certified supply chains.
Direct sales commands the highest value concentration; distributor channels are expanding most quickly as REACH regulatory pressure redirects industrial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward German pharmaceutical-grade producers while Southeast Asian oleochemical hubs absorb feedstock volatility. This asymmetry shapes regional investment patterns and qualification strategies across the Caprylic/Capric Triglyceride value chain.
United States
FDA food-contact and USP-NF excipient standards drive specification intensity for lipid-based drug delivery systems. Domestic formulators in New Jersey and California prioritize suppliers with simultaneous REACH registration for export flexibility. The Midwest personal care manufacturing belt sustains steady demand for cosmetic-grade material.
Germany
EMA active substance carrier guidelines expand addressable demand for high-purity CCT in oncology formulations. ECHA REACH registration thresholds force cosmetic formulators toward pharmaceutical-grade upgrades. The Cologne-Düsseldorf chemical corridor anchors enzymatic esterification capacity serving European pharmaceutical networks.
South Korea
Seoul-based skincare innovators specify ultra-low peroxide index grades for barrier repair and sun care applications. MFDS cosmetic safety regulations align with tightening global purity standards. The Songdo biocluster drives R&D procurement for next-generation emollient formulations.
Japan
Clean-label beverage manufacturers replace synthetic emulsifiers with food-grade CCT for protein fortification. METI industrial standards support bio-based process certification initiatives. Osaka-Kobe chemical processors concentrate pharmaceutical excipient qualification for generic drug exports.
India
CDSCO and BIS harmonization efforts open pathways for imported pharmaceutical-grade CCT in generic drug manufacturing. FSSAI food additive specifications fragment market access requirements. Mumbai-Pune pharmaceutical corridors build excipient qualification capabilities for domestic oncology formulation.
Caprylic/Capric Triglyceride Market Vendor Landscape
Concentration sits with integrated oleochemical producers controlling fractionation assets and specialty chemical blenders commanding pharmaceutical certification. The vendor base stratifies across three tiers: plantation-linked upstream producers, GMP-certified excipient specialists, and regional formulation-grade suppliers. Competitive dynamics revolve around backward integration into palm kernel sourcing and multi-regulatory dossier accumulation.
Among plantation-integrated producers, KLK Oleo exemplifies upstream control over feedstock volatility. Croda International Plc occupies a position within the pharmaceutical-grade certification tier, while Emery Oleochemicals anchors North American regional supply relationships. These three represent distinct competitive archetypes: captive raw material security, regulatory qualification depth, and geographic proximity to formulator clusters.
| Leading Market Players |
|---|
| KLK Oleo |
| Ecogreen Oleochemicals |
| Croda International Plc |
| Oxiteno |
| Emery Oleochemicals |
| Oleon NV |
| IOI Oleo GmbH |
| BERG + SCHMIDT GmbH & Co. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month GMP certification timelines for pharmaceutical-grade production concentrate pricing power with established German and Swiss manufacturers, while Southeast Asian feedstock suppliers absorb palm kernel oil volatility through backward integration into plantation assets. This lead-time asymmetry stratifies the Caprylic/Capric Triglyceride value chain into qualified-premium and commodity-standard tiers.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical-grade batches and standard cosmetic-grade volumes reaches its widest point at the USP-NF certification threshold. Pricing stratifies across premium, standard, and economy tiers driven by peroxide index specifications and multi-regulatory dossier accumulation. Cost compression in standard cosmetic grades intensifies because South Korean formulators consolidate qualified vendor lists from eight-to-twelve to three-to-four strategic partners. Pharmaceutical buyers exhibit the least price sensitivity due to EMA active substance carrier qualification requirements, while industrial plasticizer applications face the highest substitution elasticity from chlorinated paraffin competitors.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore transshipment hubs elevates inbound logistics costs for European and North American formulators sourcing from Malaysian and Indonesian fractionation facilities. Geographic supply concentration centers on Malaysia, Indonesia, and Germany, with the Cologne-Düsseldorf corridor anchoring enzymatic esterification capacity. Raw material dependencies rest on palm kernel oil, glycerol, and immobilized lipase biocatalysts. Single-source vulnerability in Southeast Asian C8/C10 fatty acid fractionation creates geographic chokepoint exposure. Distribution runs through direct sales relationships for pharmaceutical and large cosmetics procurement, with German chemical distributors building dedicated inventories for industrial displacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as large French and US cosmetic formulators reduce qualified vendor lists, consolidating procurement relationships around suppliers with simultaneous FDA, USP-NF, and REACH registration status.
For Market Incumbents: Compound GMP-certified capacity advantages through enzymatic esterification technology adoption and CDSCO qualification pathways for Indian pharmaceutical access. Threats from glycerol ester substitutes and propylene glycol competitors intensify margin pressure in nutritional applications. Capacity addition in the Swiss-German pharmaceutical corridor reinforces excipient positioning against emerging biocatalysis specialists. For New Entrants and Emerging Players: Contract manufacturing service gaps in EMA-compliant active substance carrier production present white-space entry points. The Indian pharmaceutical excipient segment offers the most penetrable geography given CDSCO-BIS harmonization efforts. A go-to-market angle anchored in continuous-flow enzymatic reactor design with carbon footprint certification addresses sustainability-driven procurement criteria. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oleochemical parents seeking to divest non-core specialty ester assets. Long-term viability over the next decade hinges on enzymatic process convergence and multi-regulatory dossier depth. The signal to watch is EMA substance evaluation deadline acceleration forcing cosmetic-grade upgrades toward pharmaceutical thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Kernel Sourcing | KLK Oleo demonstrates how plantation control insulates margins from Malaysian feedstock volatility. |
| Pharmaceutical-Grade Certification Investment | Croda International Plc leverages USP-NF and Ph.Eur. compliance to capture oncology formulation demand. |
| Enzymatic Esterification Technology Adoption | Swiss and German manufacturers deploy immobilized lipase biocatalysis to achieve peroxide values below 1.0 meq O2/kg. |
| EMA Active Substance Carrier Qualification | European oncology formulators expand addressable demand for high-purity CCT in lipid-based drug delivery systems. |
| CDSCO Harmonization Pathway Development | Generic drug manufacturers in India seek imported pharmaceutical-grade supply for domestic excipient qualification. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed oleochemical producers, ECHA REACH registration databases, and USP-NF monograph publications. Plant managers at Southeast Asian fractionation facilities, procurement leads at French dermocosmetic formulators, technical R&D directors in enzymatic biocatalysis, and regulatory affairs specialists at German pharmaceutical excipient manufacturers provided stakeholder perspectives. Bottom-up capacity and demand modeling triangulates against top-down value chain analysis.
Segmentation dimensions modeled include grade purity tier, end-use application, regulatory certification cluster, and geographic production hub across the projection horizon. CAGRs derive from demand elasticity analysis against pharmaceutical formulation growth and cosmetic R&D intensity. Industry-specific forecast inputs incorporate EMA guideline revision timelines and palm kernel oil price volatility indices.
Forecasts assume regulatory continuity in REACH, FDA food-contact, and EMA excipient regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include Malaysian feedstock export restrictions, accelerated ECHA substance evaluation deadlines, and glycerol ester substitution acceleration in nutritional applications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Tallow Amine Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Lipid Rich Powder Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Triisostearyl Citrate Market