
 South America Surface Treatment Chemicals Market | 2026-2036
South America Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Surface Treatment Chemicals Market Analytics
Direct distribution between chemical suppliers and large automotive OEMs is tilting toward technical service partnerships rather than pure product resale. Henkel Corporation leverages its localized application labs in São Paulo to sustain formulation customization for Brazilian assembly plants. BASF anchors regional supply through backward integration into phosphate and zirconium-based pretreatment chemistry. PPG Industries competes via dedicated technical teams embedded at major customer sites across the Mercosur zone.
Surface treatment chemicals encompass formulated solutions that modify metal, polymer, or composite substrates to enhance adhesion, corrosion resistance, electrical conductivity, or aesthetic finish, typically applied through immersion, spray, or brush methods at controlled pH and temperature parameters. These chemistries serve primarily to prepare surfaces for subsequent coating, bonding, or functional performance in demanding industrial environments. Alkali-based cleaners and phosphate conversion coatings occupy the largest volume share among product types, reflecting their entrenched role in automotive pretreatment lines across Brazil and Argentina. Solvent-based formulations retain relevance in aerospace maintenance applications where waterborne alternatives face performance constraints. The biochemical segment shows the fastest trajectory as Brazilian regulators tighten volatile organic compound thresholds for metal finishing operations.
CONAMA, Brazil's national environmental council, shapes effluent discharge limits that directly constrain formulation choices in industrial metal finishing. ANVISA, the Brazilian health regulatory agency, governs worker exposure standards and chemical hazard classification for surface treatment products manufactured or imported into the country. Brazil's ABNT standards alignment with ISO 14001 environmental management systems further structures market access for foreign suppliers. Stakeholders must monitor pending updates to Mercosur's harmonized chemical regulatory framework and assess whether localized formulation registration or regional technical center investment offers the more durable competitive position.
Market Dynamics
Automotive OEMs across Brazil and Argentina are consolidating pretreatment specifications around zirconium-based thin-film chemistries, compressing phosphate conversion coating volumes while demanding localized technical service capabilities from suppliers.
Growth Catalysts
- CONAMA Resolution 430:Brazil's industrial effluent discharge limits are forcing metal finishing operations to replace hexavalent chromium with compliant trivalent alternatives, expanding addressable demand for compliant pretreatment portfolios.
- Automotive pretreatment automation:Robotic spray application lines in São Paulo state's assembly plants are standardizing process control specifications, pulling consistent-volume chemical supply contracts from integrated suppliers.
- Phosphate conversion coating demand:Corrosion resistance mandates for vehicles exported to Mercosur markets sustain immersion line investments across Paraná and Rio Grande do Sul manufacturing corridors.
Market Restraints
- Raw material concentration:Fluorozirconic acid and specialty phosphate salts depend on Chinese intermediate supply, exposing Brazilian formulators to freight cost volatility and import duty fluctuations.
- Technical performance gaps:Waterborne cleaners still fail to match solvent-based degreasing on heavily soiled aluminum engine castings, preserving niche demand for restricted chemistries.
- ANVISA registration timelines:New chemical entity approvals for surface treatment products average 18-24 months, freezing formulation innovation cycles for imported specialty additives.
Strategic Opportunities
- Colombia's emerging automotive cluster:Assembly plant investments around Bogotá lack established pretreatment chemical supply infrastructure, creating first-mover positioning for Brazilian exporters with Mercosur trade credentials.
- Bio-based corrosion inhibitors:CONAMA's pending volatile organic compound thresholds for 2026-2027 are accelerating R&D in plant-derived film-forming chemistries with biodegradability certifications.
- Technical service partnerships:Direct embedding of application engineers at OEM sites is displacing traditional distributor networks, capturing margin and process specification influence.
Industry Challenges
- Process engineering talent scarcity:Brazilian universities produce limited graduates with combined electrochemistry and automotive coating line expertise, forcing suppliers to train internally.
- Legacy system integration:Converting established iron phosphate lines to zirconium thin-film chemistry requires tank material upgrades and rinse cascade reconfiguration, extending payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Surface Treatment Chemicals Market |
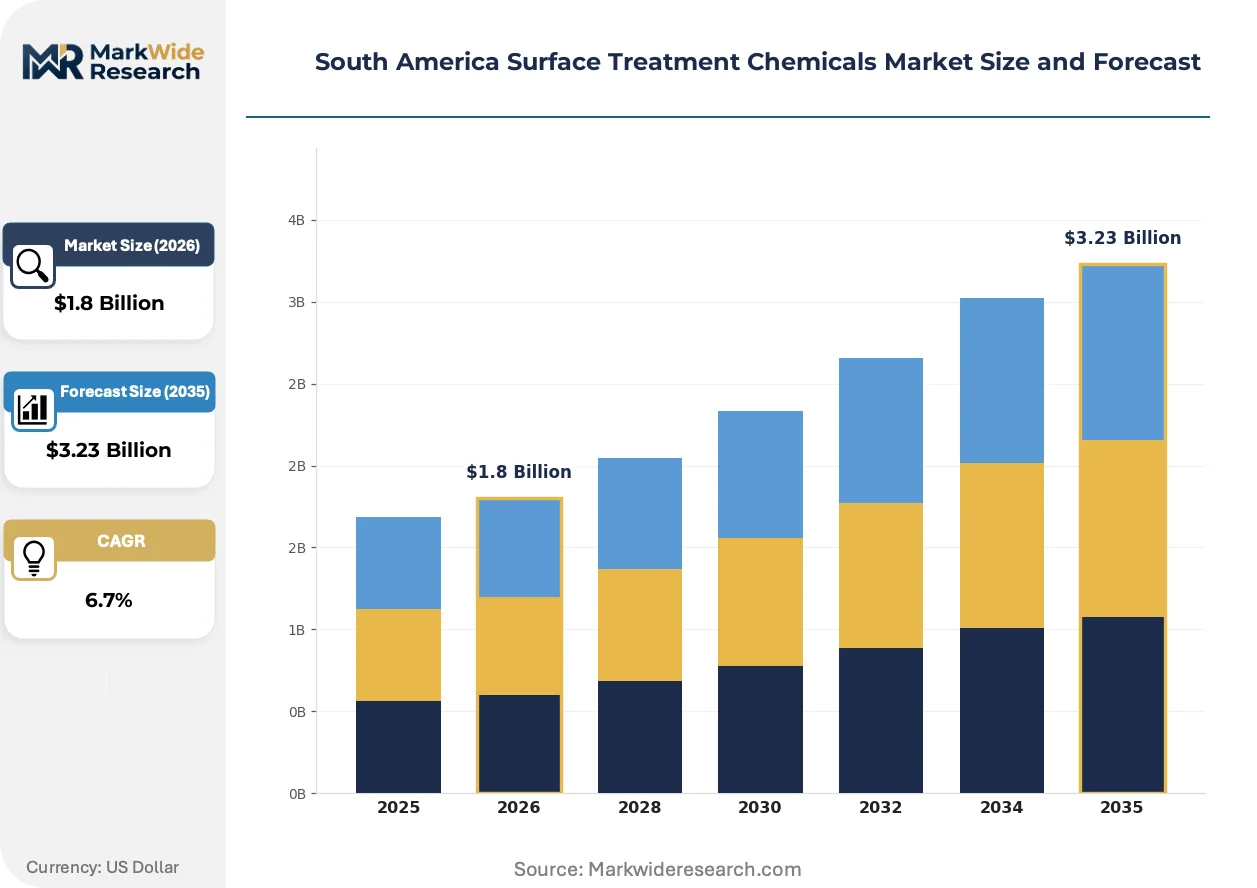
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkali, Acid, Solvent, Biochemical Application: Automotive, Aerospace, Construction, Electronics End User: Manufacturers, Fabricators, Repair Shops, Retailers Distribution Channel: Direct Sales, Online Sales, Wholesale, Distributors |
| Companies Covered | 3M, BASF, Henkel Corporation, PPG Industries, Solvay, Element Solutions Inc., Atotech (MKS Instruments), Evonik, Quaker Chemical Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Surface Treatment Chemicals Market Evolving Landscape
Digital process monitoring and predictive chemistry management are restructuring how surface treatment chemicals are specified, dosed, and replenished in high-volume manufacturing environments.
Real-time conductivity and pH sensors integrated with cloud-based dosing controllers are digitizing chemical consumption tracking in Brazilian automotive pretreatment lines. Tier-1 suppliers in São Paulo state are piloting these systems to reduce bath dump frequencies and extend solution life. The technology is compressing traditional manual titration labor while enabling outcome-based service billing models.
CONAMA's progressive tightening of heavy metal discharge limits is mandating closed-loop rinse water recycling in new metal finishing installations. This regulatory trajectory is elevating capital requirements for process water treatment equipment alongside chemical supply contracts. Argentina's alignment with Mercosur environmental protocols is extending similar compliance obligations to Córdoba's agricultural machinery manufacturers.
Automotive OEM procurement teams are consolidating surface treatment chemical suppliers from multiple regional distributors to single-source technical partnerships with embedded service capabilities. This concentration is displacing traditional resale margins with performance-guaranteed supply agreements. The shift is most visible in Brazil's São Paulo-Paraná automotive corridor where assembly plants now require on-site application laboratories.
South America Surface Treatment Chemicals Market Segmentation
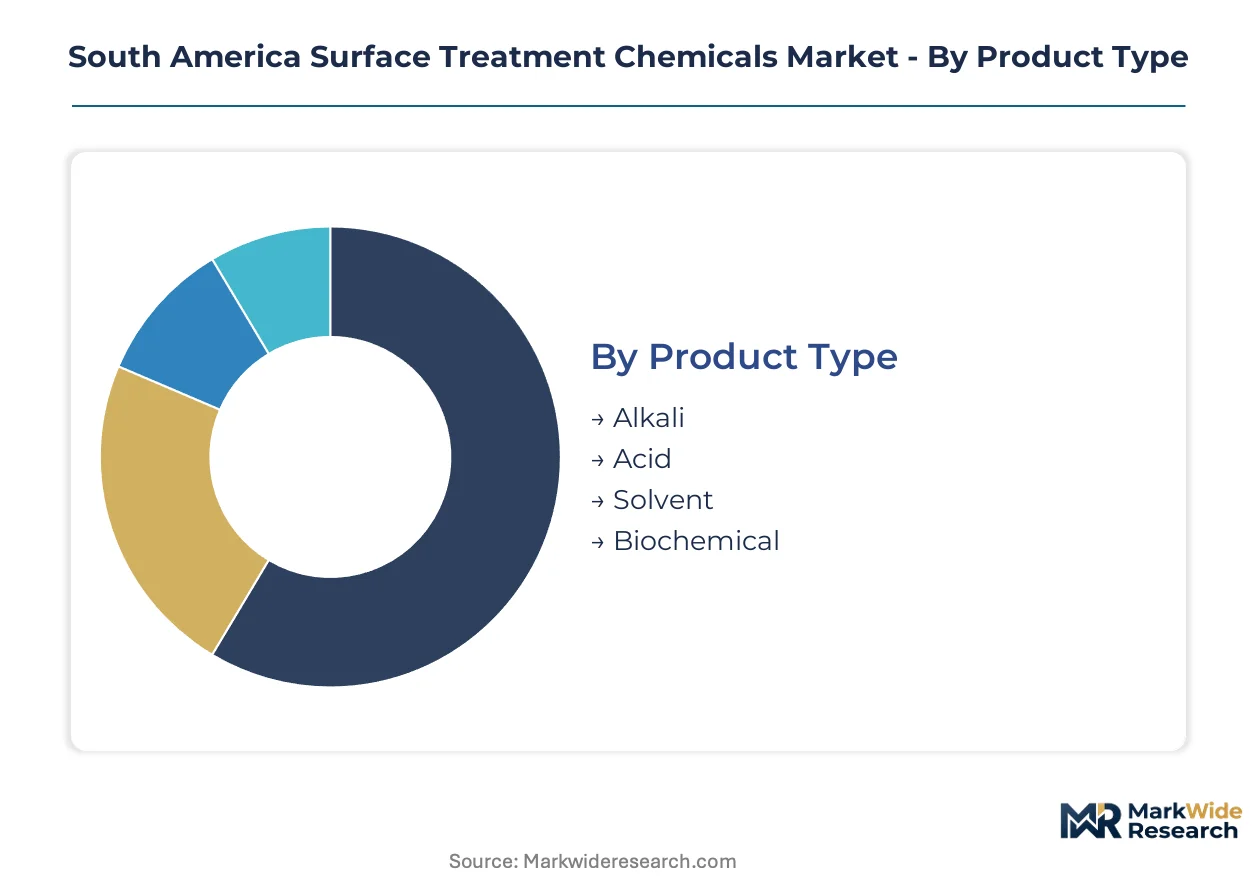
Surface treatment chemical suppliers in South America must align formulation portfolios with distinct technical service requirements across product categories, application environments, and customer scale. Segmentation reveals where localized application laboratories and embedded engineering support command pricing premiums versus transactional supply relationships.
Product Type:
After-sales service intensity varies sharply by chemistry family, with immersion line systems demanding continuous bath monitoring and rapid technical response capabilities.
- Alkali:Caustic and silicated formulations remove heavy soils and oxide layers from steel substrates prior to phosphate conversion coating. Brazilian automotive pretreatment lines in São Paulo state consume alkali cleaners in highest volumes, with suppliers embedding conductivity sensors and automated dosing controllers to minimize manual titration labor. Alkali holds the largest share; momentum sits with biochemical alternatives.
- Acid:Pickling and activation chemistries based on sulfuric, hydrochloric, or phosphoric acids dissolve mill scale and prepare metal surfaces for subsequent coating adhesion. Argentina's Córdoba agricultural machinery fabricators specify acid-based etching systems for heavy-gauge steel components exposed to field corrosion.
- Solvent:Hydrocarbon and chlorinated formulations target precision degreasing of aluminum castings and aerospace components where waterborne alternatives risk hydrogen embrittlement or residue interference.
- Biochemical:Plant-derived surfactants and enzyme-based cleaners address CONAMA volatile organic compound thresholds while matching solvent performance on lightly soiled substrates.
Alkali formulations dominate volume; biochemical chemistries are climbing the fastest as regulatory pressure intensifies.
Application:
Application environment dictates capital intensity of chemical supply contracts, with high-volume automated lines favoring integrated service partnerships over spot purchasing.
- Automotive:Multi-stage pretreatment systems combine cleaning, conversion coating, and sealing chemistries for body-in-white and component finishing. Brazil's São Paulo-Paraná manufacturing corridor generates concentrated demand, with OEMs requiring on-site application laboratories and real-time process monitoring from suppliers.
- Aerospace:Nadcap-certified chemistries for anodizing, passivation, and specialty coatings serve maintenance, repair, and overhaul operations across Brazil and Argentina. Solvent-based formulations retain relevance here given stringent performance specifications and regulatory grandfathering provisions.
- Construction:Galvanizing pretreatment and structural steel coating preparation consume phosphate conversion coatings and alkali cleaners at lower service intensity than automotive applications.
- Electronics:Precision cleaning and surface activation for printed circuit board manufacturing and connector plating drives demand for high-purity acid and solvent formulations with tight ionic contamination controls.
Automotive commands the greatest service investment; aerospace maintains the most stringent certification barriers.
End User:
End user scale determines whether suppliers deploy direct technical teams or rely on distributor networks for formulation support and inventory management.
- Manufacturers:Tier-1 automotive suppliers and original equipment manufacturers in Brazil's industrial south specify long-term chemical supply contracts with embedded application engineers and guaranteed process performance metrics.
- Fabricators:Mid-scale metal processors serving construction and agricultural equipment markets purchase through regional distributors, with technical service delivered remotely or via periodic site visits.
- Repair Shops:Small-scale maintenance operations for automotive refinishing and machinery restoration buy packaged quantities through wholesale channels with minimal formulation customization.
- Retailers:Hardware and industrial supply stores stock consumer-grade conversion coatings and rust inhibitors for hobbyist and light commercial applications.
Manufacturers concentrate premium service investment; fabricators represent the broadest addressable base for distributor-led expansion.
Distribution Channel:
Channel selection reflects customer technical sophistication and purchase scale, with direct relationships displacing traditional resale where process outcomes are contractually guaranteed.
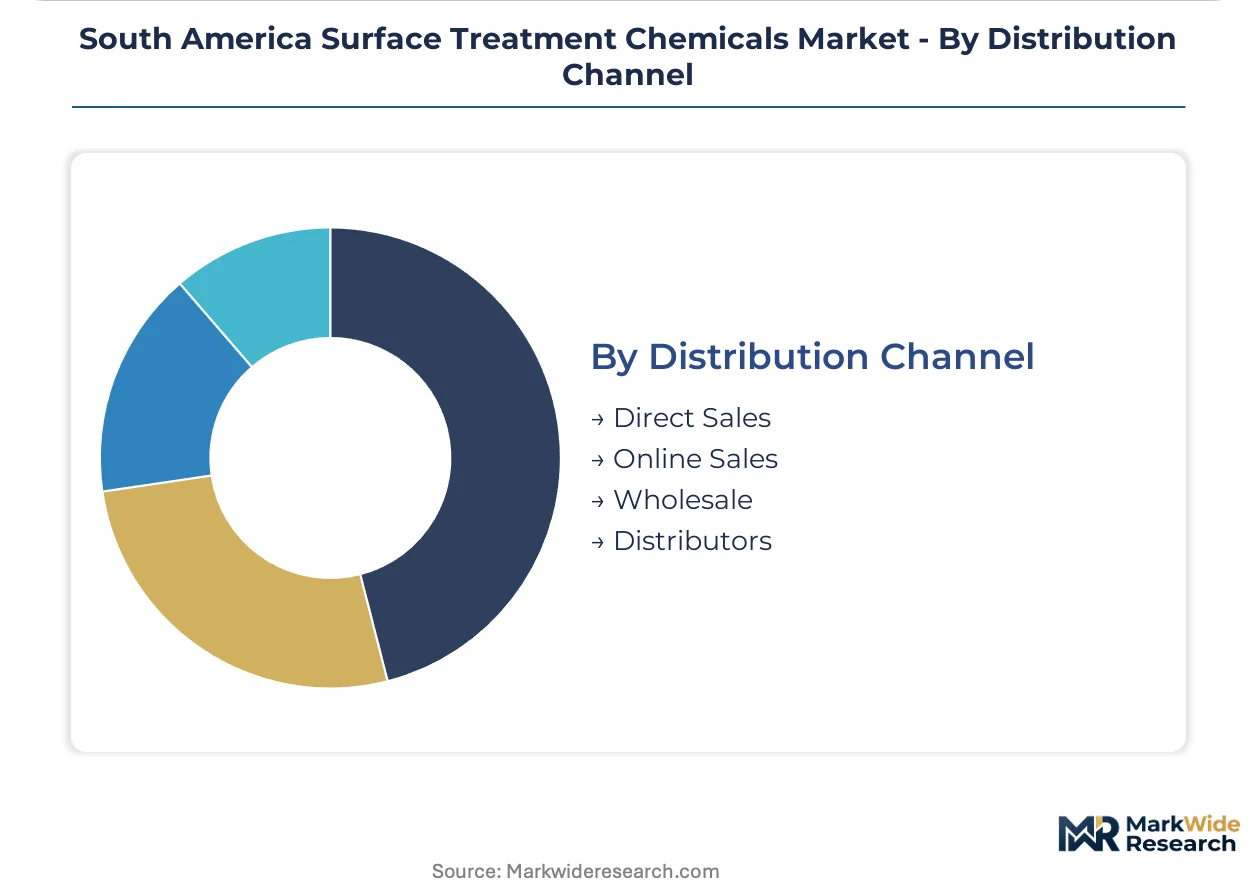
- Direct Sales:Integrated suppliers maintain dedicated account teams and localized application laboratories for large automotive OEMs and Tier-1 component manufacturers across the Mercosur zone.
- Online Sales:E-commerce platforms serve small fabricators and repair shops with standardized formulations, technical documentation, and replenishment scheduling for non-critical applications.
- Wholesale:Industrial supply wholesalers aggregate demand from mid-scale metal finishers, offering credit terms and consolidated logistics for multi-product procurement.
- Distributors:Specialized chemical distributors provide inventory buffering, local regulatory compliance support, and basic technical service for geographic markets outside supplier direct coverage.
Direct sales capture the highest margin relationships; distributor networks retain importance for geographic and customer-scale coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing premiums through embedded technical service requirements, while Argentine buyers negotiate harder on chemical unit costs amid currency volatility.
Brazil
Automotive OEMs across São Paulo and Paraná states specify zirconium-based thin-film pretreatment chemistries for corrosion resistance compliance. CONAMA Resolution 430 mandates industrial effluent discharge limits that prohibit hexavalent chromium, forcing metal finishing operations toward trivalent alternatives. The São Paulo-Paraná manufacturing corridor concentrates demand, with assembly plants requiring on-site application laboratories from chemical suppliers.
Argentina
Agricultural machinery fabricators in Córdoba province sustain phosphate conversion coating demand for heavy-gauge steel components exposed to field corrosion. Argentina's alignment with Mercosur environmental protocols extends discharge compliance obligations to regional manufacturers. Córdoba's metalworking cluster lacks localized pretreatment chemical production, creating import dependency on Brazilian and international suppliers.
Chile
Mining equipment maintenance operations in Antofagasta and Santiago drive demand for solvent-based degreasing and corrosion protection chemistries. The country's national environmental regulator enforces volatile organic compound thresholds that constrain formulation choices in coastal industrial zones. Santiago's aerospace maintenance sector retains grandfathered solvent formulations where waterborne alternatives fail performance specifications.
Colombia
Emerging automotive assembly investments around Bogotá lack established pretreatment chemical supply infrastructure, creating first-mover positioning opportunities. The national environmental authority is drafting industrial discharge standards modeled on Brazilian CONAMA frameworks. Bogotá's manufacturing corridor represents an untapped demand node for Mercosur-qualified chemical exporters with regional trade credentials.
Uruguay
Small-scale metal finishing operations serving Brazilian automotive component supply chains consume standardized phosphate and alkali formulations. Uruguay's regulatory alignment with Mercosur chemical classification systems simplifies cross-border formulation registration for established suppliers. Montevideo's industrial free zone hosts toll manufacturing operations that re-export surface treatment chemicals to Argentine and Paraguayan fabricators.
South America Surface Treatment Chemicals Market Competitive Landscape
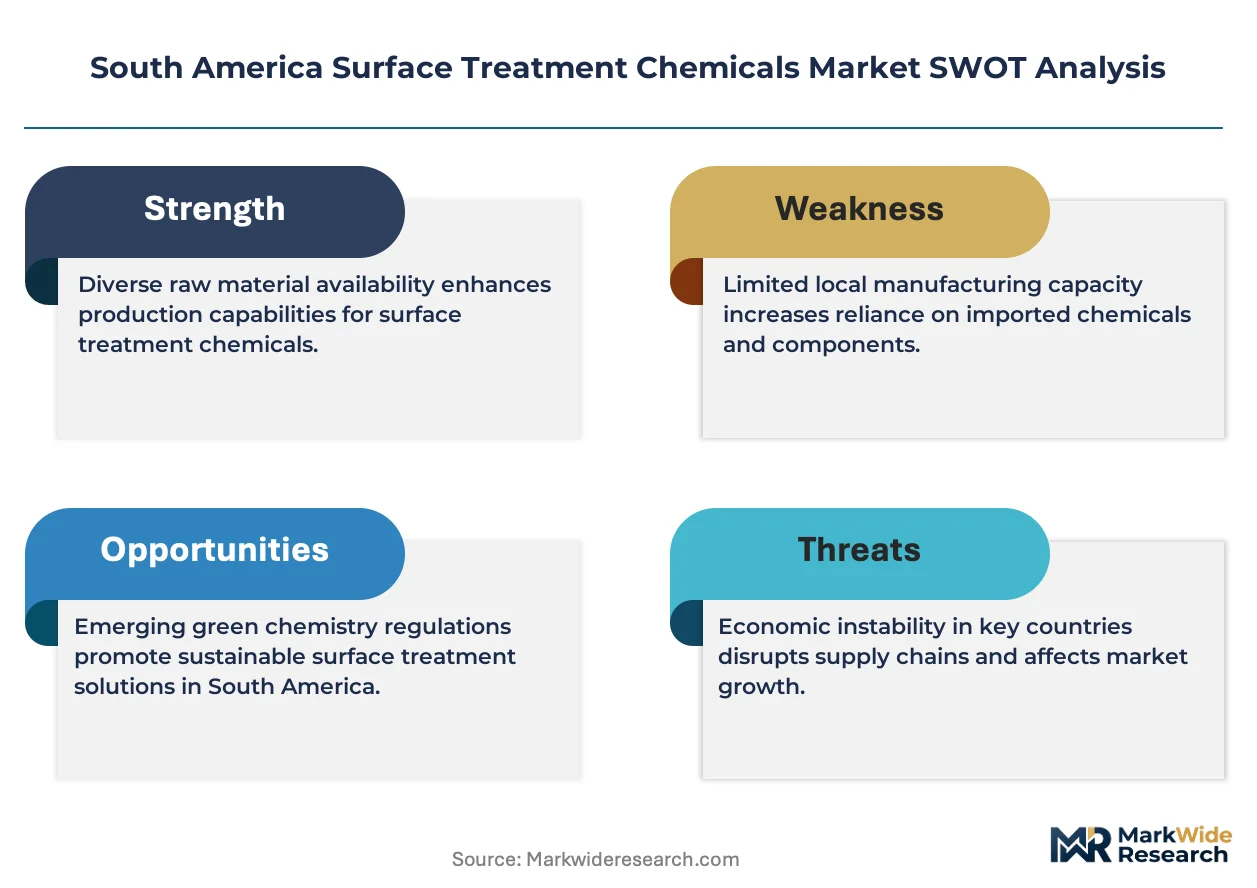
Platform integrators command the system tier; component specialists sit upstream with narrower formulation portfolios. The South American surface treatment chemicals market structures around three to five integrated suppliers with localized application laboratories, flanked by regional distributors and import-dependent specialists. Strategic archetypes include: integrated multinationals with backward integration into phosphate and zirconium chemistry; regional distributors with regulatory compliance and inventory buffering capabilities; and niche specialists focused on aerospace or electronics certification requirements. Competitive moves concentrate on embedding technical teams at OEM sites and securing long-term performance-guaranteed supply contracts.
Among integrated multinational suppliers, Henkel Corporation and BASF exemplify the technical service partnership model, while PPG Industries occupies a position emphasizing embedded engineering support across the Mercosur zone. These three companies represent divergent approaches to the regional imperative for localized application laboratories and real-time process monitoring capabilities. Henkel's São Paulo-based facilities anchor its customization capabilities for Brazilian automotive assembly plants. BASF's upstream control over phosphate and zirconium-based pretreatment chemistry secures supply chain leverage. PPG Industries differentiates through dedicated technical teams positioned at major customer sites rather than centralized laboratory service.
| Leading Market Players |
|---|
| 3M |
| BASF |
| Henkel Corporation |
| PPG Industries |
| Solvay |
| Element Solutions Inc. |
| Atotech (MKS Instruments) |
| Evonik |
| Quaker Chemical Corporation |
| Others |
Value Network & Pricing Analysis
São Paulo state's concentrated automotive chemical production anchors regional supply capacity, translating upstream formulation expertise into pricing leverage over Argentine and Colombian buyers lacking comparable technical infrastructure.
Pricing Analysis
The customization-premium spread separates configured-to-order zirconium thin-film systems from standardized phosphate conversion coatings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and embedded technical service intensity. Price differentiation stems from ANVISA registration status and on-site application laboratory access. Pricing pressure stems from Chinese intermediate supply volatility affecting fluorozirconic acid costs. Tier-1 automotive OEMs show lowest price sensitivity; mid-scale fabricators negotiate hardest on unit chemistry costs.
Supply Chain Analysis
Contract-manufacturing concentration in Montevideo's industrial free zone and São Paulo's dedicated application facilities holds regional blending capacity. Geographic supply concentration centers on Brazil, Argentina, and Uruguay for formulation finishing, with Chinese and German sources for specialty phosphate salts and fluorozirconic acid. Raw material dependencies rest on imported zirconium intermediates, phosphoric acid derivatives, and plant-derived surfactants for biochemical alternatives. Supply chain risk hinges on Mercosur tariff exposure for non-regional chemical inputs. Distribution runs through direct technical partnerships for automotive OEMs and specialized chemical distributors for geographic coverage gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of electrochemistry-trained process engineers with automotive coating line experience constrains supplier expansion and sustains premium pricing for embedded technical service capabilities.
For Market Incumbents: Harden technical service moats by expanding São Paulo application laboratory capacity and securing long-term performance-guaranteed contracts with Paraná assembly plants. Threaten new entrant displacement through regulatory compliance bundling. Prioritize backward integration into phosphate and zirconium chemistry to buffer Chinese intermediate volatility. For New Entrants and Emerging Players: Colombia's Bogotá automotive corridor offers first-mover positioning where established pretreatment infrastructure remains absent. Target biochemical formulation segments where CONAMA's pending VOC thresholds create substitution windows. Enter through technical partnership proposals rather than commodity resale to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated suppliers with embedded application engineers and multi-year OEM contracts. Five-to-ten year viability favors platforms with regulatory registration depth across Mercosur jurisdictions. Acquisition target archetype: regional distributors with ANVISA compliance capabilities and established automotive channel access. Monitor CONAMA effluent standard updates as inflection signal for compliant chemistry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Chemistry | Captive supply of pretreatment intermediates buffers Brazilian formulators against Chinese import volatility. |
| Technical Service Partnership Expansion | Embedded application engineers at São Paulo-Paraná OEM sites displace traditional distributor margins. |
| Biochemical R&D Acceleration | Plant-derived film-forming chemistries address CONAMA's pending VOC thresholds for metal finishing operations. |
| Colombia Market Entry | Bogotá's emerging automotive cluster lacks established pretreatment supply infrastructure. |
| Digital Process Monitoring Deployment | Real-time pH and conductivity sensors enable outcome-based service billing in Brazilian pretreatment lines. |
Research Methodology
The analysis maps alkali cleaners, phosphate conversion coatings, zirconium thin-film systems, and biochemical alternatives, each validated through plant managers, OEM procurement leads, distribution channel partners, and technical R&D directors. Primary interviews combined with secondary validation from customs and trade data, ABNT regulatory filings, SEC disclosures of multinational suppliers, and automotive production databases. Bottom-up volume modeling and top-down market sizing triangulated segment estimates.
Assumptions held CONAMA regulatory trajectories and Mercosur trade frameworks fixed while varying automotive production forecasts and raw material cost scenarios. Segmentation dimensions modeled include chemistry family, application environment, end-user scale, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory and forward-looking demand elasticity across the projection horizon. Industry-specific inputs incorporated phosphate salt price indices and automotive pretreatment line automation rates.
Practitioners should monitor regulatory revision triggers including CONAMA effluent standard updates and Mercosur chemical harmonization proposals for early signals of demand inflection. Forecasts reflect documented assumptions regarding automotive OEM consolidation patterns and Chinese intermediate supply stability. Quarterly review of ANVISA registration timelines and raw material freight cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Allyl Chloride Market
Chemicals
Power Plant Chemicals Market
Chemicals
Global Amines Market
Chemicals
Betaine Market
Chemicals
Guaiazulene Market
Chemicals
Tin Chemicals Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
6 Hexanediol Market
Chemicals
Japan Methanol Market
Chemicals
US Methanol Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Scouring Agents Market
Chemicals
Tromethamine Market
Chemicals
Copper Oxychloride Market