
 Global Photoresist Chemicals Market | 2026-2036
Global Photoresist Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photoresist Chemicals Market Analysis
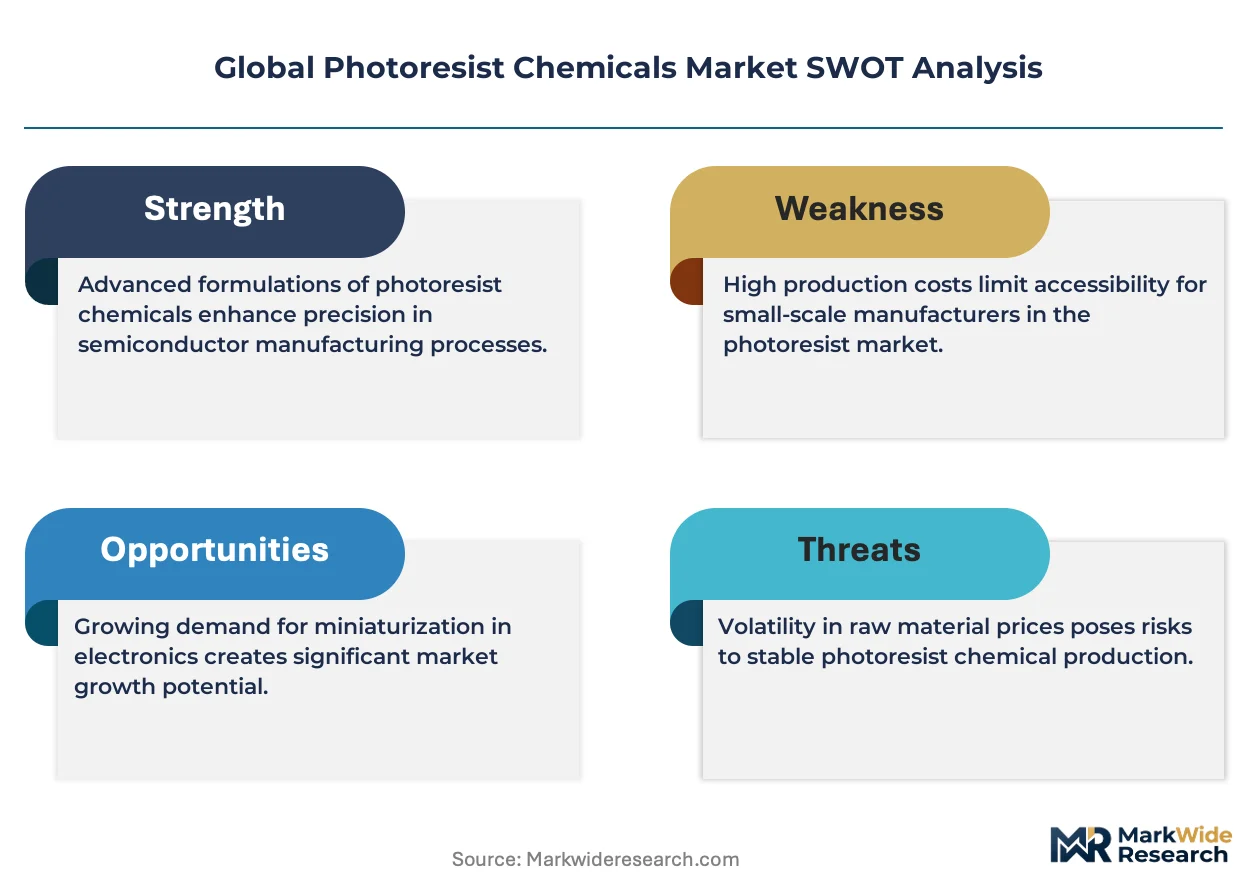
REACH is decoupling European supply chains from legacy solvent formulations, forcing reformulation investments that smaller blenders cannot absorb. Fujifilm Corporation leverages captive resin synthesis to sustain margin control across EUV and DUV product lines. JSR Corporation anchors its position through deep partnerships with Tokyo Electron and ASML in advanced node development. DuPont de Nemours, Inc. competes on fluoropolymer expertise for 193nm immersion layers.
Photoresist chemicals comprise photosensitive polymer formulations—typically novolac, polyhydroxystyrene, or metal oxide resins combined with photoacid generators and solvents—that undergo solubility changes upon exposure to specific wavelengths, enabling precise pattern transfer onto silicon wafers during semiconductor fabrication. Positive photoresist dominates volume consumption in leading-edge logic and memory production where sub-7nm resolution demands molecular precision. Specialty photoresists for EUV wavelengths represent the fastest-expanding margin pool as foundries transition from multi-patterning DUV. Among end users, advanced packaging applications for chiplets and 3D integration are outpacing traditional wafer-level demand growth.
EPA oversight of per- and polyfluoroalkyl substances in the United States is pressuring suppliers to eliminate fluorinated surfactants from rinse formulations. ECHA's evolving SVHC candidate list in Europe demands granular substance tracking across multi-tier chemical supply chains. China's MEE enforces stricter volatile organic compound limits on coating operations near Yangtze River manufacturing corridors. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify alternative chemistries before node transitions lock in formulation choices.
Market Dynamics
EUV lithography adoption at sub-7nm nodes is compressing demand for multi-patterning DUV resins while concentrating procurement power among Taiwan and South Korea foundries.
Growth Catalysts
- Node transition acceleration:Logic foundries in Hsinchu and Pyeongtaek are qualifying metal oxide EUV resins for 2nm production ramps, pulling formulation volumes from legacy 193nm immersion layers.
- REACH solvent reformulation:ECHA's SVHC candidate list expansion is forcing blenders to qualify bio-based propylene glycol methyl ether acetate alternatives, creating first-mover advantages for compliant suppliers.
- Advanced packaging expansion:Chiplet integration and 3D stacking at OSAT facilities are outpacing traditional wafer-level photoresist consumption in die-attach and redistribution layer applications.
Market Restraints
- Resin supply concentration:Polyhydroxystyrene and novolac precursor synthesis concentrates among Japanese chemical majors, exposing formulators to allocation risk during semiconductor cycle upturns.
- PFAS regulatory friction:EPA oversight of per- and polyfluoroalkyl substances is pressuring elimination of fluorinated surfactants from rinse formulations, requiring multi-year qualification cycles for replacements.
- Technical resolution ceiling:Chemically amplified resist platforms face stochastic defect limits below 13nm half-pitch, constraining single-exposure EUV throughput at leading-edge nodes.
Strategic Opportunities
- India semiconductor corridor:Gujarat and Karnataka fabs under the country's PLI scheme will require localized photoresist blending capacity for 28nm and above mature nodes.
- Photoresist recycling infrastructure:Spent resist collection and solvent recovery systems represent an emerging service layer as MEE volatile organic compound limits tighten across Yangtze River manufacturing zones.
- High-NA EUV material stack:New metal oxide platforms with enhanced absorption at 0.55 numerical aperture wavelengths enable single-patterning at 8nm resolution, collapsing multi-exposure process complexity.
Industry Challenges
- Formulation chemist scarcity:Expertise in photoacid generator synthesis and dissolution inhibitor design concentrates among retiring specialists in Japan and Germany, constraining R&D pipeline velocity.
- Cleanroom qualification timelines:New resist platforms require 12-18 month particle and metal contamination validation cycles at ASML and Tokyo Electron before foundry adoption, locking in formulation choices across node transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photoresist Chemicals Market |
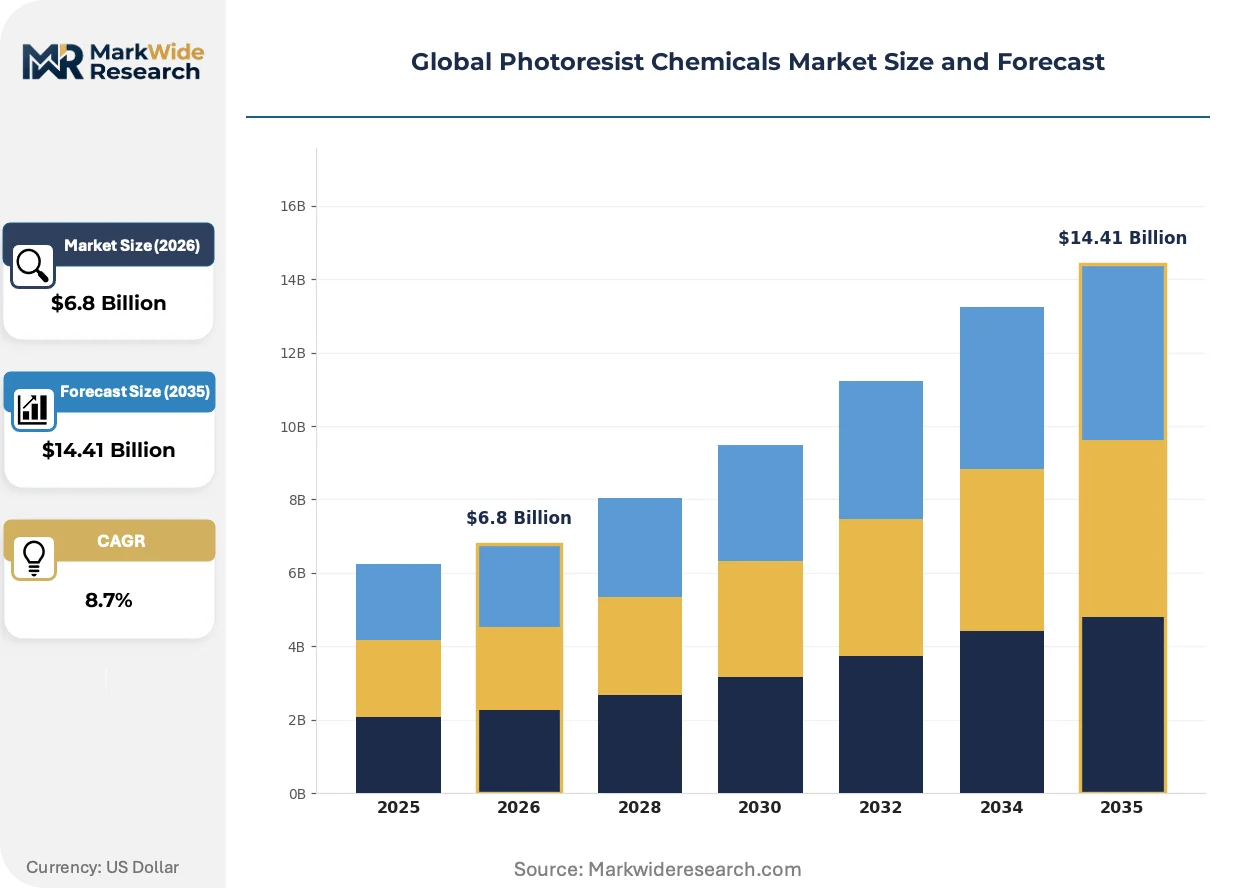
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Photoresist, Negative Photoresist, Anti-Reflective Coatings, Specialty Photoresists End User: Semiconductors, Flat Panel Displays, Advanced Packaging, MEMS Technology: Photolithography, Electron Beam Lithography, X-ray Lithography, Nanoimprint Lithography Application: Microelectronics, Optoelectronics, PCB Fabrication, Automotive |
| Companies Covered | Fujifilm Corporation, Sumitomo Chemical Co., Ltd., Tokyo Ohka Kogyo Co., Ltd., Mitsui Chemicals, Inc., Merck KGaA, JSR Corporation, DuPont de Nemours, Inc., Nagase & Co., Ltd., Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photoresist Chemicals Market Emerging Trajectories
Patterning technology is bifurcating between extreme ultraviolet single exposure and directed self-assembly alternatives, while regulatory pressure on fluorinated chemistries forces molecular redesign across the supply base.
Metal oxide EUV resists incorporating tin-oxo clusters are absorbing the patterning load at 3nm and 2nm logic nodes. Samsung and TSMC process teams are qualifying these platforms for high-volume manufacturing in 2025-2026 ramps. The technology is absorbing capital allocation that previously funded multi-patterning DUV equipment, compressing demand for 193nm immersion resist volumes.
ECHA's evolving SVHC candidate list is decoupling European supply chains from legacy N-methyl-2-pyrrolidone solvent formulations. Industrial consequence includes forced reformulation investments that smaller blenders cannot absorb, consolidating formulation supply among integrated resin producers. Specialty photoresist lines for automotive and industrial semiconductor applications face the steepest compliance timelines.
Direct contracting between foundry procurement teams and resin synthesis houses is displacing traditional chemical distributor intermediaries in Taiwan and South Korea. Samsung's Materials Development Center and TSMC's Supply Chain Management now negotiate multi-year supply agreements with captive synthesis units. This channel compression is most visible in EUV-grade product categories where lot-to-lot consistency requirements exceed distributor technical capabilities.
Global Photoresist Chemicals Market Segmentation
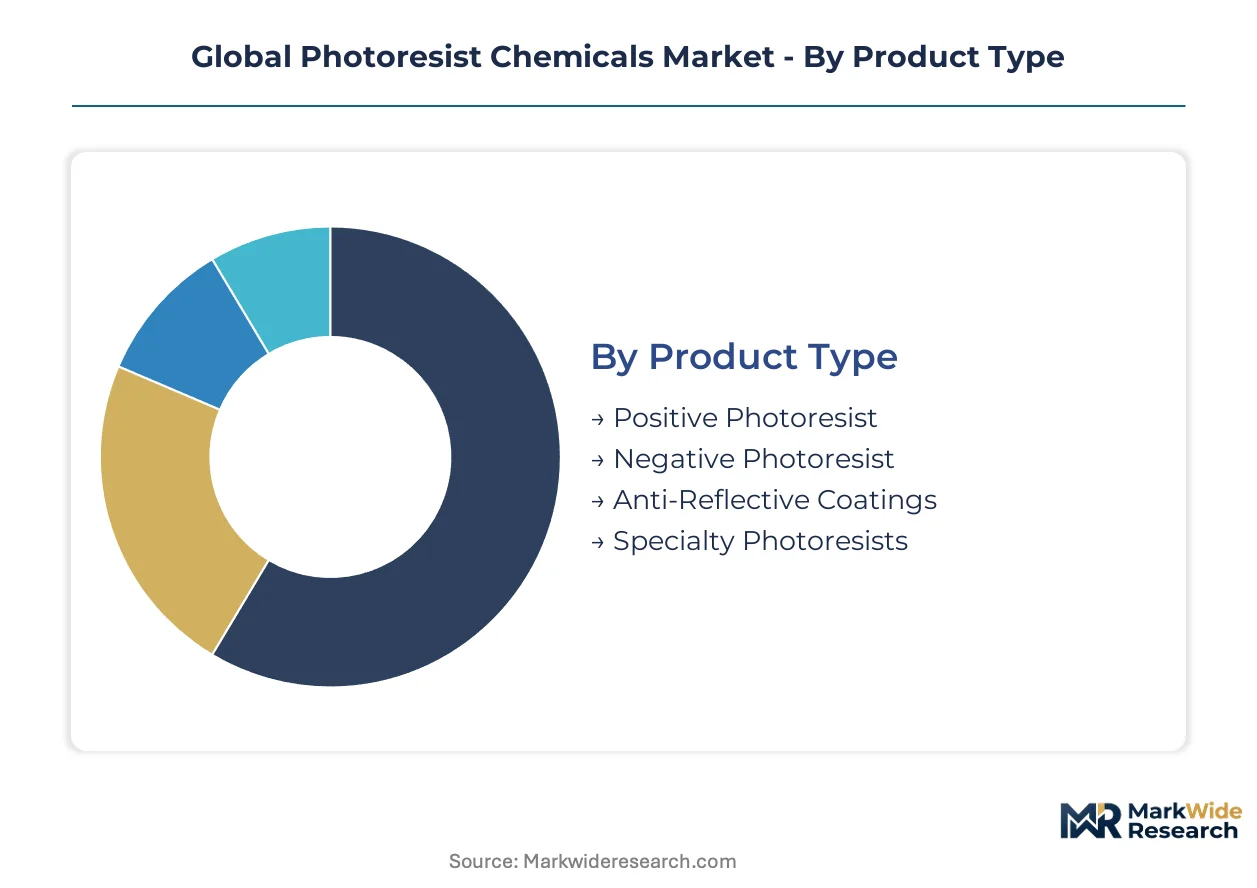
Photoresist chemicals fragment across four critical dimensions that determine procurement patterns and margin structures. Product type dictates formulation complexity and regulatory burden. End-user concentration in East Asian foundry clusters shapes volume allocation and technical qualification timelines.
Product Type:
Buyers prioritize resolution capability and line-edge roughness specifications when selecting resist platforms for node-specific patterning.
- Positive Photoresist:Chemically amplified formulations undergo solubility inversion upon acid-catalyzed deprotection, enabling sub-7nm resolution in EUV single-exposure processes. TSMC and Samsung foundries in Hsinchu and Pyeongtaek are pulling volumes for 2nm logic ramps, displacing multi-patterning DUV layers.
- Specialty Photoresists:Metal oxide platforms incorporating tin-oxo clusters deliver enhanced absorption at EUV wavelengths, collapsing process complexity for high-NA lithography. These formulations command premium positioning as ASML's 0.55NA systems enter qualification.
- Negative Photoresist:Crosslinking polymer systems dominate MEMS and automotive sensor applications where thick-film patterning tolerates lower resolution.
- Anti-Reflective Coatings:Bottom and top-layer formulations suppress standing wave interference in 193nm immersion stacks, sustaining relevance in mature node production.
Positive photoresist leads on scale; specialty photoresists lead on momentum.
End User:
Volume concentration tracks capital expenditure cycles in semiconductor fabrication, with packaging applications expanding fastest.
- Semiconductors:Logic and memory fabs consume the majority of EUV-grade formulations, with procurement consolidating among Taiwan and South Korea foundries. Node transition acceleration is compressing demand for legacy DUV resins while concentrating supplier qualification power.
- Advanced Packaging:Redistribution layer and die-attach applications for chiplet integration are outpacing traditional wafer-level consumption. OSAT facilities in Malaysia and Vietnam are driving formulation demand for 2.5D and 3D stacking processes.
- Flat Panel Displays:Large-area photolithography for OLED backplanes requires distinct viscosity and coating uniformity specifications compared to semiconductor applications.
- MEMS:Microelectromechanical systems utilize thicker resist films for deep silicon etch masking, with automotive pressure and inertial sensors representing stable demand.
Semiconductor fabs anchor volume; advanced packaging climbs the fastest.
Technology:
Equipment-wavelength compatibility locks resist formulations into specific lithography platforms, creating technology-specific supply relationships.
- Photolithography:Optical patterning across DUV and EUV wavelengths dominates commercial volume, with wavelength-specific resin synthesis determining supplier positioning.
- Electron Beam Lithography:Mask writing and direct-write applications for prototyping and photomask fabrication require distinct sensitivity and resolution characteristics.
- Nanoimprint Lithography:Mechanical pattern transfer offers cost advantages for high-volume optical components and storage media.
- X-ray Lithography:Synchrotron-based systems retain niche positioning for specialized MEMS and packaging applications requiring extreme aspect ratios.
Photolithography commands installed base; nanoimprint lithography gains share fastest in non-semiconductor applications.
Application:
Performance requirements diverge sharply between leading-edge microelectronics and cost-sensitive PCB fabrication.
- Microelectronics:Silicon wafer patterning for logic, memory, and power devices demands the tightest particle and metal contamination controls. REACH solvent reformulation is forcing qualification of bio-based propylene glycol methyl ether acetate alternatives in European supply chains.
- Automotive:Functional safety requirements for ADAS and powertrain semiconductors are tightening resist purity standards. EPA PFAS oversight is pressuring elimination of fluorinated surfactants from rinse formulations, requiring multi-year qualification cycles.
- Optoelectronics:LED and photonic device fabrication utilizes resist platforms optimized for compound semiconductor substrates.
- PCB Fabrication:Printed circuit board photoresists prioritize throughput and cost over resolution, with dry film formulations dominating multilayer board production.
Microelectronics leads on specification intensity; automotive climbs fastest on safety-driven qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists concentrate in Japanese industrial corridors and Taiwanese science parks, anchoring the technical workforce that supplies leading-edge semiconductor fabrication worldwide. Their expertise in photoacid generator synthesis and dissolution inhibitor design shapes regional competitive positioning. Migration patterns of this talent pool influence where new blending capacity emerges.
Japan
Polyhydroxystyrene and novolac precursor synthesis clusters among chemical majors in the Kanto and Kansai regions. METI's semiconductor materials strategy prioritizes domestic sourcing resilience for EUV-grade resins. Osaka-based synthesis houses supply captive resin streams to integrated formulators serving Tokyo Electron equipment installations.
South Korea
Samsung's Materials Development Center in Suwon and SK Hynix procurement teams are qualifying metal oxide EUV platforms for 2nm production ramps. The country's national industrial regulator enforces stricter volatile organic compound limits on coating operations near Pyeongtaek manufacturing corridors. Foundry procurement teams negotiate multi-year supply agreements directly with Japanese resin synthesis units, compressing distributor channels.
Taiwan
TSMC's Supply Chain Management in Hsinchu anchors the densest concentration of EUV resist consumption globally. The Hsinchu Science Park hosts dedicated blending facilities serving 3nm and 2nm logic production. Local environmental authorities align enforcement with MEE-style VOC limits as the Yangtze River regulatory model influences regional standards.
United States
EPA oversight of per- and polyfluoroalkyl substances pressures suppliers to eliminate fluorinated surfactants from rinse formulations used in Arizona and Oregon fabs. Intel's Oregon operations and emerging Texas facilities require multi-year qualification cycles for replacement chemistries. Domestic blending capacity concentrates around legacy DUV supply relationships rather than EUV-grade production.
China
Yangtze River Delta manufacturing corridors face tightening MEE volatile organic compound limits on photoresist coating operations. Domestic formulators in Shanghai and Suzhou prioritize 28nm and above mature node supply as leading-edge EUV equipment access remains restricted. The country's dual carbon goals accelerate demand for spent resist collection and solvent recovery infrastructure.
Global Photoresist Chemicals Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where integrated resin producers capture margin from captive synthesis while independent blenders face reformulation cost pressures. The vendor base separates into three strategic archetypes: integrated chemical majors controlling upstream resin supply, equipment-aligned formulators with cleanroom qualification advantages, and regional blenders serving mature node demand. Competitive dynamics center on backward integration into precursor synthesis and direct contracting relationships with foundry procurement teams.
Among Japan-based integrated suppliers, Fujifilm Corporation, JSR Corporation, and Tokyo Ohka Kogyo Co., Ltd. exemplify the equipment-aligned archetype through deep qualification partnerships with lithography tool manufacturers. These entities occupy positions where lot-to-lot consistency requirements exceed distributor technical capabilities, enabling direct multi-year supply negotiations with Hsinchu and Pyeongtaek foundries. Their geographic proximity to Tokyo Electron and ASML development centers reinforces formulation lock-in across node transitions.
| Leading Market Players |
|---|
| Fujifilm Corporation |
| Sumitomo Chemical Co., Ltd. |
| Tokyo Ohka Kogyo Co., Ltd. |
| Mitsui Chemicals, Inc. |
| Merck KGaA |
| JSR Corporation |
| DuPont de Nemours, Inc. |
| Nagase & Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
REACH solvent reformulation mandates in Europe gate qualified supply access for EUV-grade photoresist formulators, compressing premium-tier pricing power among integrated resin producers while excluding smaller blenders from high-margin procurement pools.
Pricing Analysis
Bundled technical service contracts dominate EUV-grade procurement, while unbundled commodity spot transactions persist for mature-node DUV formulations. Price differentiation separates metal oxide platforms with ASML qualification from standard chemically amplified resists. Pricing pressure stems from foundry consolidation in Hsinchu and Pyeongtaek, where Samsung and TSMC procurement teams negotiate multi-year supply agreements. Mature node blenders exhibit highest price sensitivity; leading-edge formulators with captive resin synthesis capture least.
Supply Chain Analysis
Cleanroom qualification protocols at Tokyo Electron and ASML gate supply chain entry, requiring 12-18 month validation cycles. Polyhydroxystyrene and novolac precursor synthesis concentrates in Japan's Kanto and Kansai regions, while formulation blending clusters around Hsinchu and Pyeongtaek. Supply chain risk centers on single-source vulnerability for tin-oxo cluster metal oxide platforms. Distribution runs through direct contracting between foundry procurement teams and Japanese resin synthesis houses, displacing traditional chemical distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in EUV-grade metal oxide platforms as foundry node transitions displace multi-patterning DUV volumes, while cost-down pressure intensifies for legacy immersion resist supply.
For Market Incumbents: Acquire captive photoacid generator synthesis capacity to defend formulation margins against resin supply allocation risk during semiconductor cycle upturns. Deepen equipment-alignment partnerships with ASML and Tokyo Electron to lock in cleanroom qualification advantages across 2nm node ramps. Prioritize REACH-compliant solvent reformulation investments before ECHA SVHC list expansion strands legacy inventory. For New Entrants and Emerging Players: Direct-to-foundry digital procurement platforms offer channel compression opportunities for qualified EUV resist suppliers seeking to bypass traditional chemical distributor markups. Target India's Gujarat and Karnataka semiconductor corridors under the PLI scheme, where localized 28nm blending capacity faces limited incumbent presence. Pursue spent resist collection and solvent recovery service contracts as MEE VOC enforcement tightens across Yangtze River manufacturing zones. For Investors and Strategic Acquirers: Roll-up economics work for regional photoresist blenders with established foundry qualification relationships because cleanroom validation timelines create insurmountable barriers to organic entry. Platform consolidation around integrated resin synthesis capabilities offers 5-10 year viability as node transitions concentrate procurement power. Watch for EPA PFAS enforcement acceleration as the signal indicating multi-year replacement chemistry qualification cycles and stranded asset risk in fluorinated surfactant-dependent formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Fujifilm and JSR sustain margin control through captive polyhydroxystyrene production. |
| REACH-Compliant Solvent Reformulation | ECHA SVHC expansion forces qualification of bio-based propylene glycol methyl ether acetate alternatives. |
| Direct Foundry Contracting | Samsung Materials Development Center and TSMC Supply Chain Management displace distributor intermediaries. |
| India PLI Localization | Gujarat and Karnataka fabs require domestic blending capacity for 28nm mature node supply. |
| Spent Resist Recovery Infrastructure | MEE VOC limits across Yangtze River corridors create emerging service layer opportunities. |
Methodological Framework
Multiple input streams — technical interviews with photoresist formulation chemists, procurement discussions at Taiwan and South Korea foundries, and regulatory filings with ECHA and EPA — were reconciled against trade flow data and SEC disclosures from integrated chemical majors. Primary engagement encompassed plant managers at Japanese resin synthesis facilities, R&D directors at equipment-aligned formulators, and supply chain executives at Hsinchu and Pyeongtaek manufacturing clusters. Secondary validation drew from customs records, METI semiconductor materials strategy documents, and ASML equipment shipment disclosures. Bottom-up formulation volume estimates and top-down semiconductor capital expenditure patterns were triangulated to anchor market sizing.
Data-stream reconciliation across product type, end user, technology, and application dimensions generated segment-level projections throughout the forecast period. Analytical modeling incorporated node transition timelines, EUV lithography adoption curves, and regulatory compliance cost burdens as industry-specific forecast inputs. CAGRs were derived from fitted growth curves calibrated to foundry capital expenditure cycles and photoresist consumption intensity per wafer layer.
The model assumes a particular technology adoption path; alternative pathways for high-NA EUV lithography at 0.55 numerical aperture would alter the outlook for metal oxide resist demand and DUV displacement rates. Forecasts reflect assumptions regarding REACH enforcement timelines, EPA PFAS regulatory scope, and China EUV equipment access restrictions. A model refresh is warranted upon material change in foundry node ramp schedules or ECHA SVHC candidate list expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Mercuric Chloride Market
Chemicals
Calcium Methoxide Market
Chemicals
Morpholine Market
Chemicals
Xanthates Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Pinoxaden Market
Chemicals
Ethanolamine Market
Chemicals
Paint Stripper Market
Chemicals
Brazil Methanol Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Lime Sulfur Market
Chemicals
United States Construction Chemicals Market
Chemicals
Triethanolamine Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Acetic Ether Market
Chemicals
Polyphosphoric Acid (PPA) Market