
 Triazole Fungicides Market | 2026-2036
Triazole Fungicides Market Size, Share, and Industry Trends Forecast 2026-2036
Triazole Fungicides Market Analytics
The capital-intensity divergence between integrated manufacturers and formulation-only players is unwinding competitive stability in triazole fungicides. BASF SE leverages its backward integration into propiconazole intermediates to sustain margin resilience against raw material volatility. Bayer AG anchors its position through captive synthesis of difenoconazole technical, while Syngenta AG competes via proprietary micro-emulsion delivery systems that extend field persistence.
Triazole fungicides are synthetic azole compounds containing a five-membered ring with three nitrogen atoms, typically applied at 125–500 grams of active ingredient per hectare to inhibit fungal ergosterol biosynthesis. These chemistry platforms protect yield in cereals, oilseeds, and specialty crops by disrupting cell membrane integrity in target pathogens. Difenoconazole formulations command premium positioning in high-value horticultural applications where resistance management justifies elevated pricing. Tebuconazole dominates volume in broad-acre grain production across North America and Eastern Europe, while propiconazole maintains entrenched share in turf and ornamental segments where curative activity requirements are less stringent.
The EPA's pesticide registration review process and the EU's REACH authorization requirements shape active ingredient availability and reformulation timelines for triazole manufacturers. China's MEE enforces discharge standards on triazole technical production facilities, tightening supply elasticity for global formulators. Brazil's ANVISA residue tolerance protocols determine import acceptance thresholds for soybean and corn exports, directly influencing product selection by South American distributors. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate formulation re-registration costs and prioritize markets with stable approval pathways.
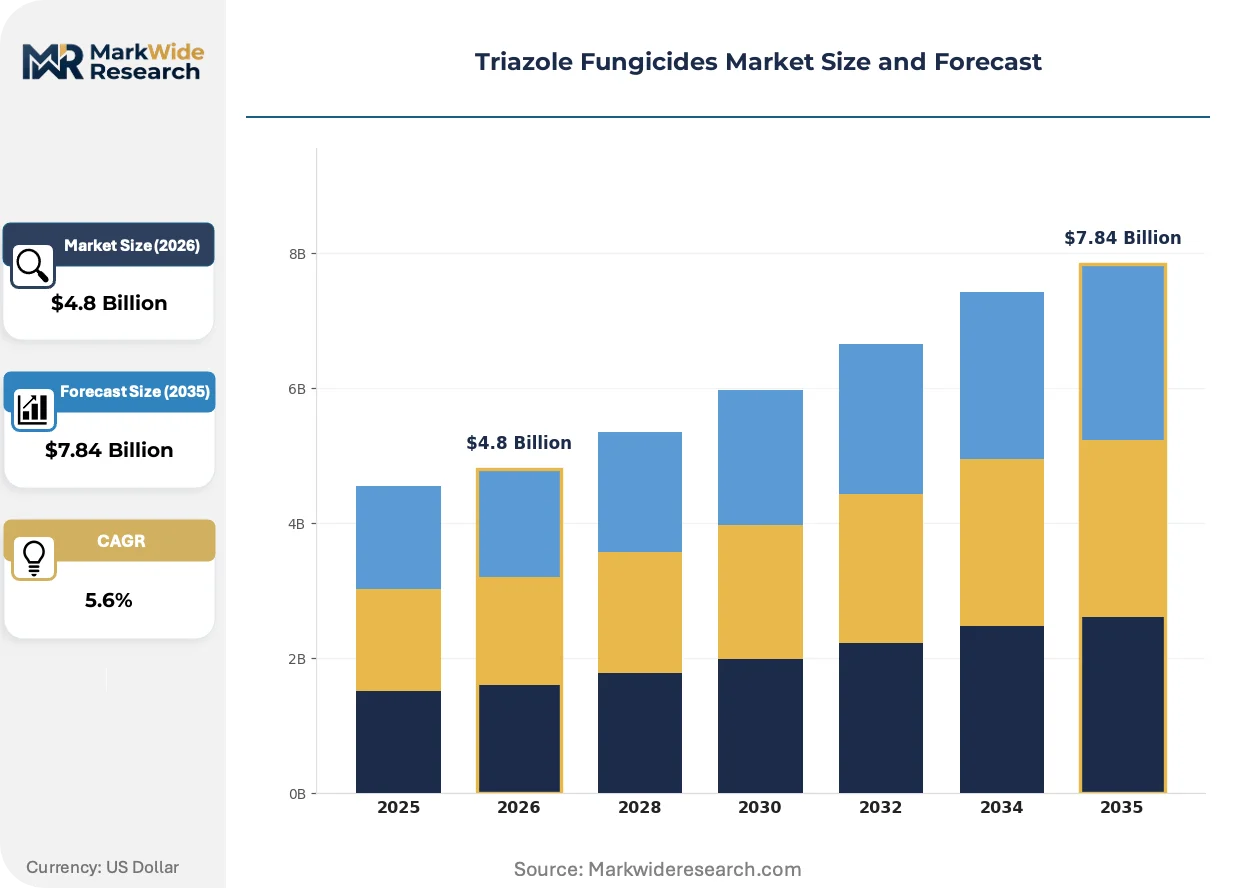
Market Dynamics
The EU Green Deal pesticide reduction mandates are forcing active ingredient reformulation cycles while Brazil's ANVISA residue protocols reshape export-oriented product selection across South American distribution networks.
Growth Catalysts
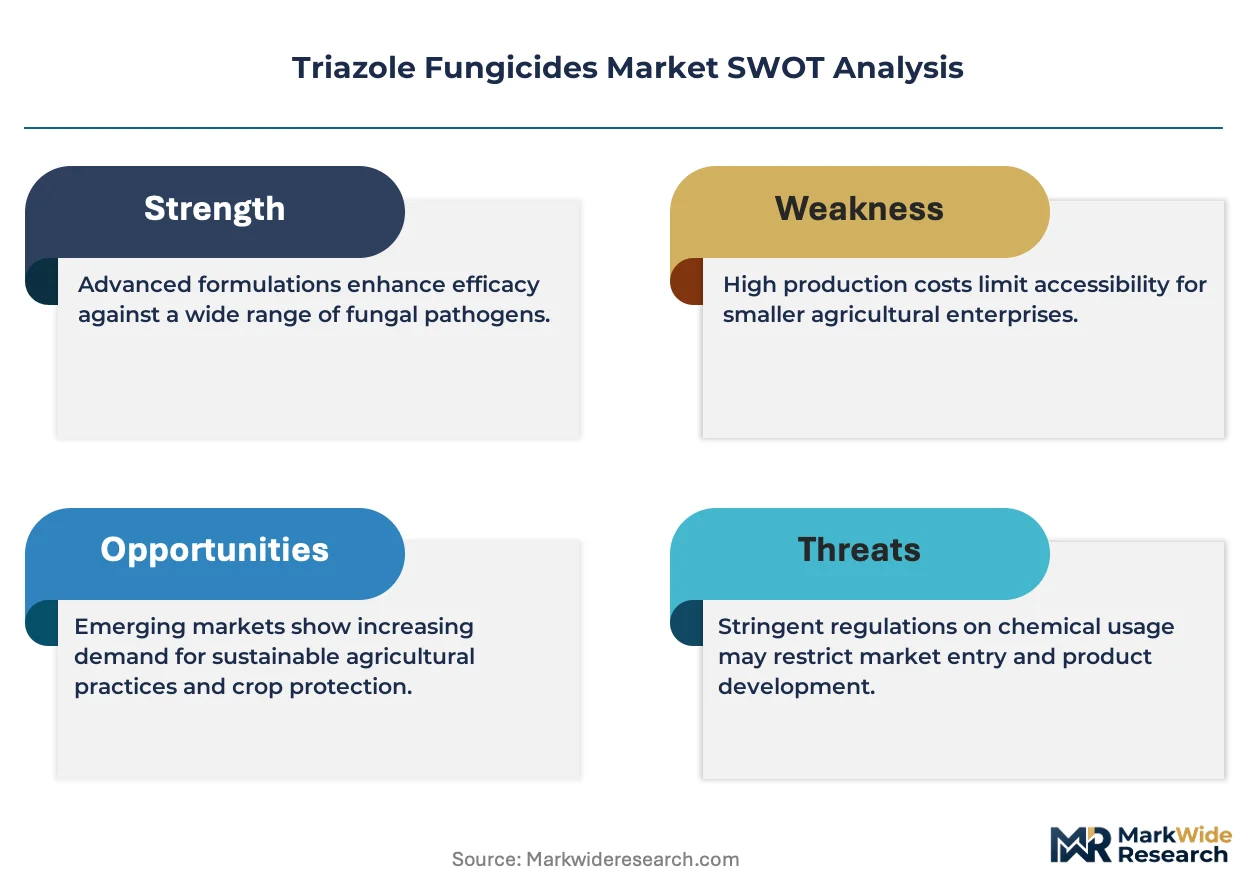
- Asian Soybean Rust Pressure:Brazil's Mato Grosso and Paraná soybean belts sustain elevated tebuconazole and trifloxystrobin consumption as pathogen resistance to strobilurins drives triazole rotation requirements.
- REACH Authorization Pathways:The EU's staggered substance review timeline creates predictable re-registration windows that favor incumbents with dedicated regulatory affairs infrastructure over smaller formulators.
- Cereal Fusarium Complex:North American spring wheat and barley programs are expanding prothioconazole seed treatment adoption as vomitoxin management becomes a grain elevator acceptance criterion.
Market Restraints
- Technical-Grade Concentration:China's Jiangsu and Zhejiang provinces host over 60 percent of difenoconazole and propiconazole technical synthesis capacity, exposing formulators to MEE environmental enforcement volatility.
- Biological Fungicide Substitution:Bacillus subtilis and Trichoderma harzianum formulations are capturing organic-certified horticultural acreage where residue-free harvest premiums justify efficacy trade-offs.
- Intermediates Cost Volatility:Triazole ring construction depends on ortho-chloroaniline and epichlorohydrin feedstocks whose pricing tracks benzene and propylene commodity cycles with limited hedging instruments.
Strategic Opportunities
- Precision Application Convergence:Drone-mounted variable-rate sprayers combined with real-time disease detection algorithms enable site-specific triazole deployment that reduces hectare-level active ingredient rates.
- Ukraine Black Soil Recovery:Post-conflict winter wheat and rapeseed replanting programs will require comprehensive fungicide packages as farmers rebuild soil health and pathogen management infrastructure.
- India FPO Aggregation:Farmer producer organizations in Maharashtra and Madhya Pradesh are consolidating procurement volumes that justify branded triazole formulations over unorganized generic alternatives.
Industry Challenges
- Resistance Monitoring Infrastructure:Field pathologists capable of fungicide sensitivity testing are concentrated in university extension services, creating diagnostic bottlenecks for regional resistance surveillance networks.
- Multi-Site Stewardship Complexity:Integrating triazoles into FRAC-mandated rotation protocols with SDHIs and QoIs requires agronomic training that distributor technical staff often lack in remote growing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triazole Fungicides Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Difenoconazole, Tebuconazole, Propiconazole, Triadimefon Application: Agricultural, Horticultural, Forestry, Turf End User: Farmers, Commercial Growers, Landscape Professionals, Research Institutions Formulation Type: Liquid, Powder, Granular, Emulsifiable Concentrate |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, Corteva Agriscience, FMC Corporation, ADAMA Agricultural Solutions Ltd., Dow, Sumitomo Chemical Co., Ltd., Nufarm Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triazole Fungicides Market Evolving Landscape
Nano-delivery systems and biological-triazole hybrid platforms are compressing application rates while regulatory pressure on residue limits accelerates formulation innovation cycles across major agricultural economies.
Micro-emulsion and nano-suspension carriers are miniaturizing active ingredient particle sizes to sub-micron scales that improve cuticular penetration and rainfastness. Brazilian soybean operators are adopting these formulations at 15-20 percent annual expansion rates as application windows compress between weather events. The technology is miniaturizing the effective dose threshold for tebuconazole and prothioconazole, enabling manufacturers to maintain revenue per hectare despite regulatory pressure to reduce environmental loading.
The EU's Farm to Fork Strategy 50 percent pesticide reduction target is accelerating substance-specific hazard assessments that disqualify certain triazole metabolites from renewal authorization. Formulators are responding by advancing prothioconazole-desthio metabolite management and accelerating registration of reduced-risk successor molecules. Horticultural exporters in Spain and Italy face the most acute compliance pressure as residue tolerances tighten for premium export markets including Switzerland and the United Kingdom.
Consolidated grain elevator networks are unbundling agronomic advice from product procurement, forcing manufacturers to rebuild technical service relationships directly with farm operations. Channel restructuring is most advanced in Iowa, Illinois, and Indiana where cooperative-owned elevators now specify fungicide programs by active ingredient rather than brand. This disintermediation compresses manufacturer margins while elevating the strategic value of proprietary formulation performance data and digital agronomy platforms.
Triazole Fungicides Market Segmentation
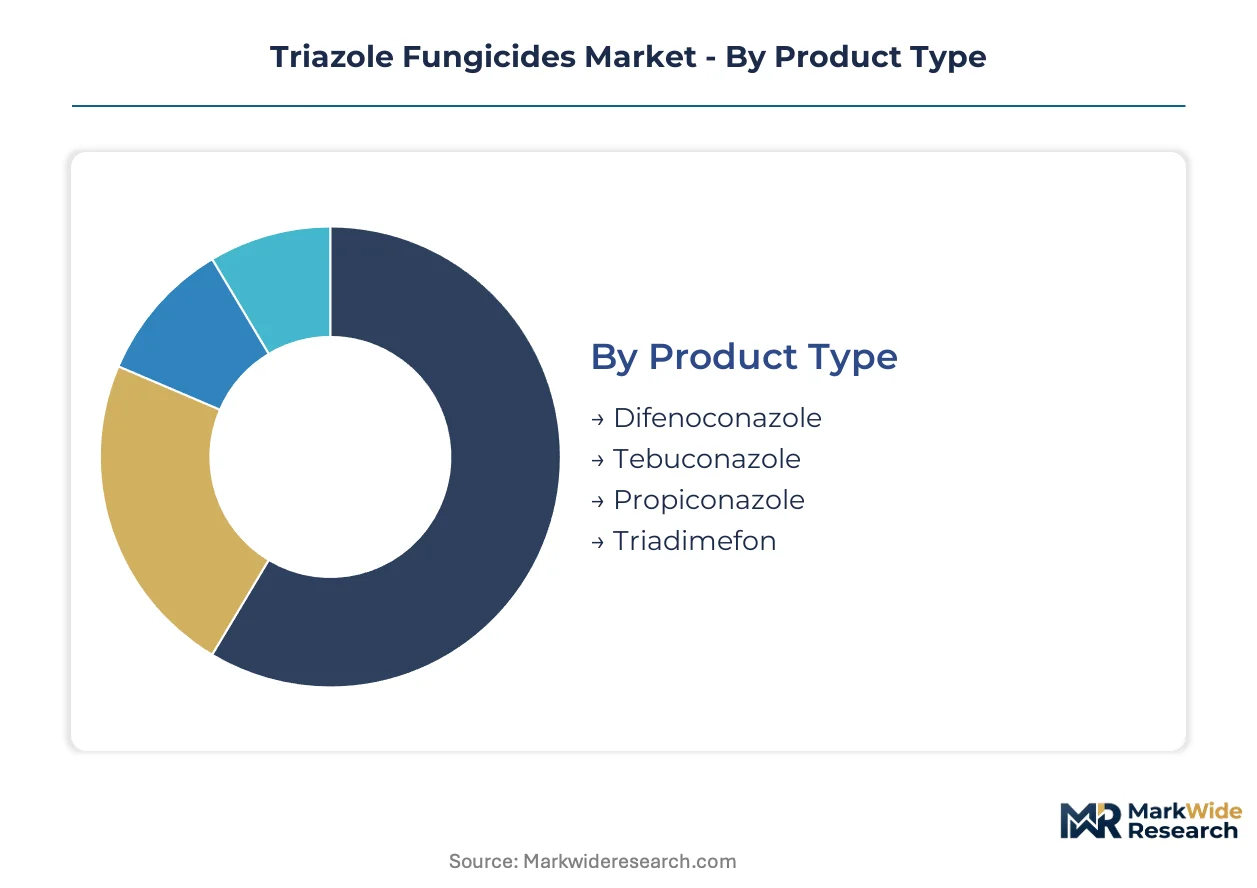
Triazole fungicide segmentation reveals how formulation chemistry and application context determine substitution vulnerability. Product type stratification exposes which active ingredients face the steepest biological fungicide displacement pressure.
Product Type:
Tebuconazole and propiconazole face the most acute biological substitution threats in organic-certified horticulture, while difenoconazole maintains defensible positioning in high-value export crops.
- Tebuconazole:A broad-spectrum triazole with systemic movement through plant vascular tissues, applied at 125-250 grams active ingredient per hectare. Brazil's Mato Grosso soybean belt sustains heavy consumption as Asian soybean rust management mandates rotation with strobilurin chemistry.
- Difenoconazole:A dual-mode triazole combining protective and curative activity with extended residual control. Spanish and Italian horticultural exporters prioritize this molecule for pome fruit and grape programs where residue tolerances for Swiss and UK markets demand precision application.
- Propiconazole:Turf and ornamental segments rely on this cost-effective systemic for dollar spot and brown patch management in North American golf course maintenance.
- Triadimefon:Cereal rust programs in Ukraine and Russia historically deployed this molecule, though regulatory non-renewal in EU jurisdictions has compressed its addressable market.
Tebuconazole retains volume leadership; difenoconazole holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity grain protection from premium horticultural programs where per-hectare spending multiples justify specialized formulation investment.
- Agricultural:Broad-acre cereal and oilseed production across Iowa, Illinois, and Indiana drives formulation standardization. Cooperative grain elevator networks now specify active ingredient rather than brand, compressing manufacturer margins while elevating technical service demands.
- Horticultural:High-value protected cultivation in Spain's Almería and Italy's Emilia-Romagna requires micro-emulsion carriers that improve cuticular penetration. EU Farm to Fork Strategy residue limits accelerate nano-suspension adoption at 15-20 percent annual expansion rates.
- Forestry:Conifer nursery and plantation management in Scandinavia and the Pacific Northwest applies triazoles for needle cast and rust complex suppression.
- Turf:Golf course superintendents in Florida, Arizona, and California balance curative efficacy against playability disruption from extended re-entry intervals.
Agricultural applications dominate volume consumption; horticultural programs command the highest revenue per hectare.
End User:
Customer type fragmentation determines channel strategy complexity, with procurement consolidation among farmer producer organizations altering distributor economics.
- Farmers:Individual operators in India's Maharashtra and Madhya Pradesh states increasingly aggregate through FPO structures that justify branded formulation procurement over unorganized generic alternatives.
- Commercial Growers:Corporate farming operations in Brazil's Paraná soybean belt maintain direct manufacturer relationships for resistance monitoring and customized rotation protocols.
- Landscape Professionals:Municipal and institutional grounds maintenance contracts in Germany and France specify reduced-risk formulations that satisfy public procurement sustainability criteria.
- Research Institutions:University extension services in the US and Brazil concentrate field pathologists capable of fungicide sensitivity testing, creating diagnostic bottlenecks for regional resistance surveillance networks.
Farmers represent the largest addressable population; commercial growers exhibit the strongest procurement consolidation momentum.
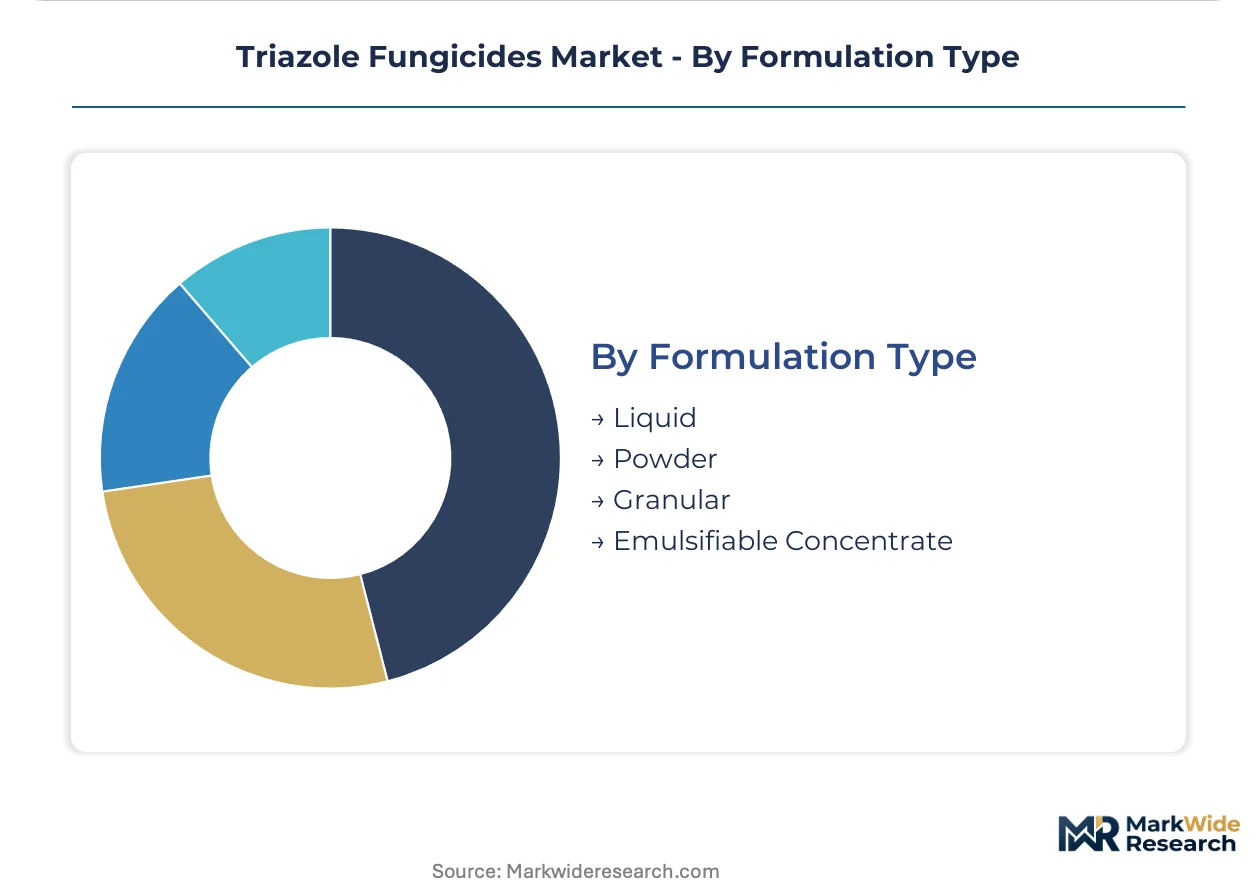
Formulation Type:
Supply concentration in Chinese technical synthesis shapes formulation economics, with environmental enforcement volatility from MEE discharge standards altering active ingredient availability.
- Liquid:Ready-to-use solutions dominate drone-mounted variable-rate application systems. Brazilian operators adopt these formats as weather window compression between rainfall events limits traditional ground sprayer deployment.
- Emulsifiable Concentrate:Oil-in-water systems remain standard for broad-acre grain programs where tank-mix compatibility with herbicides and insecticides simplifies operational logistics.
- Powder:Wettable powder formats persist in smallholder markets where storage stability and transport economics outweigh application convenience trade-offs.
- Granular:Controlled-release granules target specialty applications including plantation forestry and sod farm establishment where extended protection intervals justify higher per-hectare material costs.
Liquid formulations are gaining share fastest; emulsifiable concentrates maintain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean operators show the lowest price elasticity for triazole fungicides, absorbing premium formulations for Asian soybean rust resistance management. Indian smallholders exhibit the highest sensitivity, defaulting to unorganized generic alternatives unless FPO aggregation justifies branded procurement. European horticultural exporters occupy a middle tier, paying formulation premiums for residue compliance but negotiating aggressively on volume.
Brazil
Mato Grosso and Paraná soybean belts sustain heavy tebuconazole consumption as strobilurin resistance drives rotation mandates. ANVISA residue tolerance protocols determine export acceptance thresholds for soybean and corn shipments to the EU and China. São Paulo-based distribution networks are consolidating procurement volumes that favor direct manufacturer relationships over traditional agrochemical dealers.
United States
Iowa, Illinois, and Indiana grain elevators now specify fungicide programs by active ingredient rather than brand, compressing manufacturer margins. EPA registration review timelines shape reformulation investment cycles for prothioconazole seed treatments. The Pacific Northwest conifer nursery cluster applies triazoles for needle cast suppression in plantation forestry establishment programs.
Germany
EU Green Deal pesticide reduction mandates force active ingredient reformulation cycles for difenoconazole-based horticultural exports. ECHA REACH authorization requirements create predictable re-registration windows that favor incumbents with dedicated regulatory infrastructure. Bavaria's golf course maintenance sector specifies propiconazole for dollar spot management under municipal sustainability procurement criteria.
China
Jiangsu and Zhejiang provinces host over sixty percent of difenoconazole and propiconazole technical synthesis capacity, exposing formulators to MEE environmental enforcement volatility. The dual carbon goals tighten discharge standards on triazole production facilities, constraining supply elasticity for global formulators. Shandong Peninsula agrochemical clusters are upgrading wastewater treatment infrastructure to maintain export license eligibility.
India
Maharashtra and Madhya Pradesh farmer producer organizations aggregate procurement volumes that justify branded triazole formulations over unorganized alternatives. FSSAI residue monitoring for domestic food grain consumption shapes product selection in wheat and rice protection programs. Gujarat's cotton belt sustains propiconazole demand for leaf spot complex management in Bt cotton cultivation systems.
Triazole Fungicides Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into triazole ring intermediates determining margin resilience against ortho-chloroaniline and epichlorohydrin feedstock volatility. The upper tier commands captive synthesis capabilities for difenoconazole and propiconazole technical, while formulation-only players depend on Chinese Jiangsu and Zhejiang supply clusters. Three archetypes dominate: integrated agrochemical conglomerates with multi-crop portfolios, regional specialists focused on single-crop resistance management, and generic manufacturers competing on price in unbranded channels. Capacity consolidation and proprietary delivery system licensing represent the dominant competitive vectors.
Among integrated agrochemical conglomerates, BASF SE, Bayer AG, and Syngenta AG occupy positions that exemplify the backward-integration archetype. BASF SE represents European-based integrated manufacturing with captive intermediate supply chains. Bayer AG anchors German-origin technical synthesis capabilities for premium horticultural formulations. Syngenta AG exemplifies Swiss-headquartered innovation in proprietary micro-emulsion delivery systems that extend field persistence against generic competition.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| Corteva Agriscience |
| FMC Corporation |
| ADAMA Agricultural Solutions Ltd. |
| Dow |
| Sumitomo Chemical Co., Ltd. |
| Nufarm Limited |
| Others |
Value Network & Pricing Analysis
Biological fungicide substitution in organic-certified horticulture simultaneously redraws procurement geography toward Indian FPOs and Brazilian commercial growers while compressing premium pricing power for legacy tebuconazole formulations.
Pricing Analysis
After-sales service bundling with resistance monitoring and customized rotation protocols drives lifetime value for commercial growers in Brazil's Paraná soybean belt. Three-tier pricing structure across premium micro-emulsion, standard emulsifiable concentrate, and economy generic wettable powder levels separates formulation performance tiers. Cost compression in standard-grade tebuconazole is intensifying because cooperative grain elevators in Iowa, Illinois, and Indiana now specify active ingredient rather than brand. Indian smallholders exhibit the highest price sensitivity, defaulting to unorganized generic alternatives, while Brazilian soybean operators show the lowest elasticity for Asian soybean rust management.
Supply Chain Analysis
China's Jiangsu and Zhejiang provinces anchor over sixty percent of difenoconazole and propiconazole technical synthesis capacity for global formulators. Ortho-chloroaniline and epichlorohydrin feedstocks rest on benzene and propylene commodity cycles with limited hedging instruments. Single-source vulnerability concentrates in MEE environmental enforcement volatility that constrains supply elasticity. Distribution runs through São Paulo-based consolidating networks and cooperative-owned grain elevators that disintermediate traditional agrochemical dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: REACH authorization timelines and EPA registration reviews create multi-year barriers that favor incumbents with dedicated regulatory affairs infrastructure over smaller formulators.
For Market Incumbents: Secure captive synthesis of difenoconazole and propiconazole technical to sustain margin resilience against Chinese MEE discharge enforcement volatility. Deepen backward integration into triazole ring intermediates to hedge ortho-chloroaniline and epichlorohydrin feedstock cycles. Channel control through direct technical service relationships with farm operations counters cooperative elevator disintermediation in North American grain markets.
For New Entrants and Emerging Players: Differentiate on nano-delivery system licensing for drone-mounted variable-rate application systems in Brazilian soybean operations. Target Ukraine's post-conflict winter wheat replanting programs where comprehensive fungicide packages will rebuild pathogen management infrastructure. Pursue white-space acquisition in India's Maharashtra and Madhya Pradesh FPO aggregation channels that justify branded formulations over generics.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive intermediate supply chains and proprietary micro-emulsion delivery platforms rather than formulation-only players dependent on Chinese technical sourcing. Long-term viability over a multi-year horizon hinges on regulatory approval pathway breadth across EPA, REACH, and ANVISA jurisdictions. Watch ANVISA residue tolerance protocol shifts as the inflection indicator for South American product selection and export market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Triazole Intermediates | Captive ortho-chloroaniline supply shields BASF and Bayer from Chinese MEE enforcement volatility. |
| Nano-Delivery System Licensing | Proprietary micro-emulsion platforms extend field persistence against generic competition in Brazilian soybean belts. |
| Direct Technical Service Deployment | Manufacturer-to-farm relationships counter cooperative elevator disintermediation in Iowa, Illinois, and Indiana grain networks. |
| Regulatory Affairs Infrastructure Expansion | Dedicated REACH and EPA teams accelerate prothioconazole-desthio metabolite management for EU renewal authorization. |
| FPO Channel Partnership Development | Aggregation alliances in Maharashtra and Madhya Pradesh displace unorganized generic procurement in Indian smallholder markets. |
Research Methodology
The analysis maps tebuconazole, difenoconazole, propiconazole, and prothioconazole product segments, each validated through interviews with plant managers at technical synthesis facilities, procurement leads at downstream formulators, distribution channel partners in São Paulo and Iowa cooperative networks, and technical R&D directors developing nano-suspension carriers. Secondary validation draws from EPA registration databases, ECHA REACH authorization filings, ANVISA residue tolerance protocols, and customs trade data on ortho-chloroaniline and epichlorohydrin flows. Bottom-up volume builds triangulate against top-down market sizing across active ingredient and formulation value chains.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions including active ingredient chemistry, formulation type, application context, and regional regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves for nano-delivery systems and biological substitution rates in organic-certified horticulture. Industry-specific forecast inputs include Asian soybean rust resistance rotation mandates and EU Farm to Fork Strategy pesticide reduction compliance timelines.
Forecasts assume regulatory continuity in EPA, REACH, and ANVISA regimes; material policy shifts such as accelerated EU substance disqualification or Brazilian export tolerance tightening would require re-modeling. Specific risk factors include MEE environmental enforcement intensity in Jiangsu and Zhejiang provinces and biological fungicide efficacy improvements in high-value horticultural segments. Recalibration cycles align with material shifts in resistance monitoring infrastructure deployment and precision application technology adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
North America Feed Phytogenics Market