
 Trawler Boat Market | 2026-2036
Trawler Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Trawler Boat Market Outlook
CE certification under the Recreational Craft Directive is unwinding competitive access across European waters, forcing smaller yards into costly conformity upgrades. Nordhavn leverages its full-displacement hull expertise to sustain premium positioning in offshore-capable segments. Bering Yachts anchors its growth in steel-hulled expedition trawlers built for ice-class endurance. Selene Yachts Group differentiates through semi-custom interior configurations that command higher builder margins.
A trawler boat is a motor vessel engineered for long-range displacement cruising, typically featuring full-keel hull forms, diesel propulsion systems rated for continuous-duty operation, and fuel capacities exceeding 1,000 nautical miles of range; its primary commercial purpose spans commercial fish harvesting, marine tourism operations, and offshore research support. Commercial trawlers dominate volume demand from industrial fishing cooperatives seeking refrigerated hold capacity, while recreational trawlers attract affluent owner-operators prioritizing liveaboard comfort and ocean-crossing autonomy. Custom builds concentrate margin pools among semicustom yards serving expedition buyers, whereas standard models compete on production efficiency for fleet operators.
The International Maritime Organization enforces MARPOL Annex VI emission tiers that compel engine repowers or scrubber installations on commercial trawlers operating beyond territorial waters. The EPA regulates diesel exhaust standards for vessels in US navigable waters, while the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in onboard fish preservation systems. Stakeholders must monitor how impending carbon-intensity indexing for maritime transport reshapes propulsion technology bets and yard investment timelines.
Market Dynamics
The International Maritime Organization's Tier III nitrogen oxide emission standards are forcing a fleet-wide transition to selective catalytic reduction systems and alternative fuels, compressing yard margins while redrawing competitive boundaries between engine suppliers.
Growth Catalysts
- Refrigerated Seawater Systems:Southeast Asian commercial fishing cooperatives are installing onboard RSW units to preserve catch quality during extended voyages, driving new hull demand with integrated cooling infrastructure.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating replacement cycles for fish preservation equipment aboard European-registered vessels, creating retrofit demand for compliant systems.
- Da Nang Shipbuilding Cluster:Vietnamese regional processors are expanding fleet capacity to serve export markets, concentrating newbuild orders among yards with refrigerated hold expertise.
Market Restraints
- Steel Price Volatility:Expedition trawler builders dependent on ice-class steel plate face input cost swings that compress fixed-price contract margins and deter speculative hull construction.
- Engine Supply Concentration:Tier III-compliant marine diesel production concentrates among a handful of European and Japanese powertrain suppliers, creating delivery bottlenecks for midsize yards.
- CE Certification Burden:The Recreational Craft Directive's conformity assessment requirements impose fixed costs that disproportionately burden small European yards serving the sub-24-meter segment.
Strategic Opportunities
- Hybrid-Electric Propulsion:Convergence of lithium-ion battery systems with continuous-duty diesel generators enables silent operation modes for marine tourism operators in noise-sensitive marine protected areas.
- Expedition Charter Demand:Affluent owner-operators in Australia and New Zealand are converting private trawlers into crewed charter assets, expanding addressable market beyond pure retail sales.
- Carbon-Intensity Indexing:The IMO's developing CII framework for maritime transport will reward hull efficiency investments, creating competitive differentiation for yards optimizing displacement-to-power ratios.
Industry Challenges
- Marine Electrical Systems Integration:The shift to DC-based hotel loads and battery banks requires skill sets scarce among traditional diesel mechanics, forcing yards to retrain or outsource specialized installation work.
- Scrubber Retrofit Coordination:Commercial operators face drydock scheduling conflicts and space constraints when installing exhaust gas cleaning systems to meet emission deadlines without vessel downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trawler Boat Market |
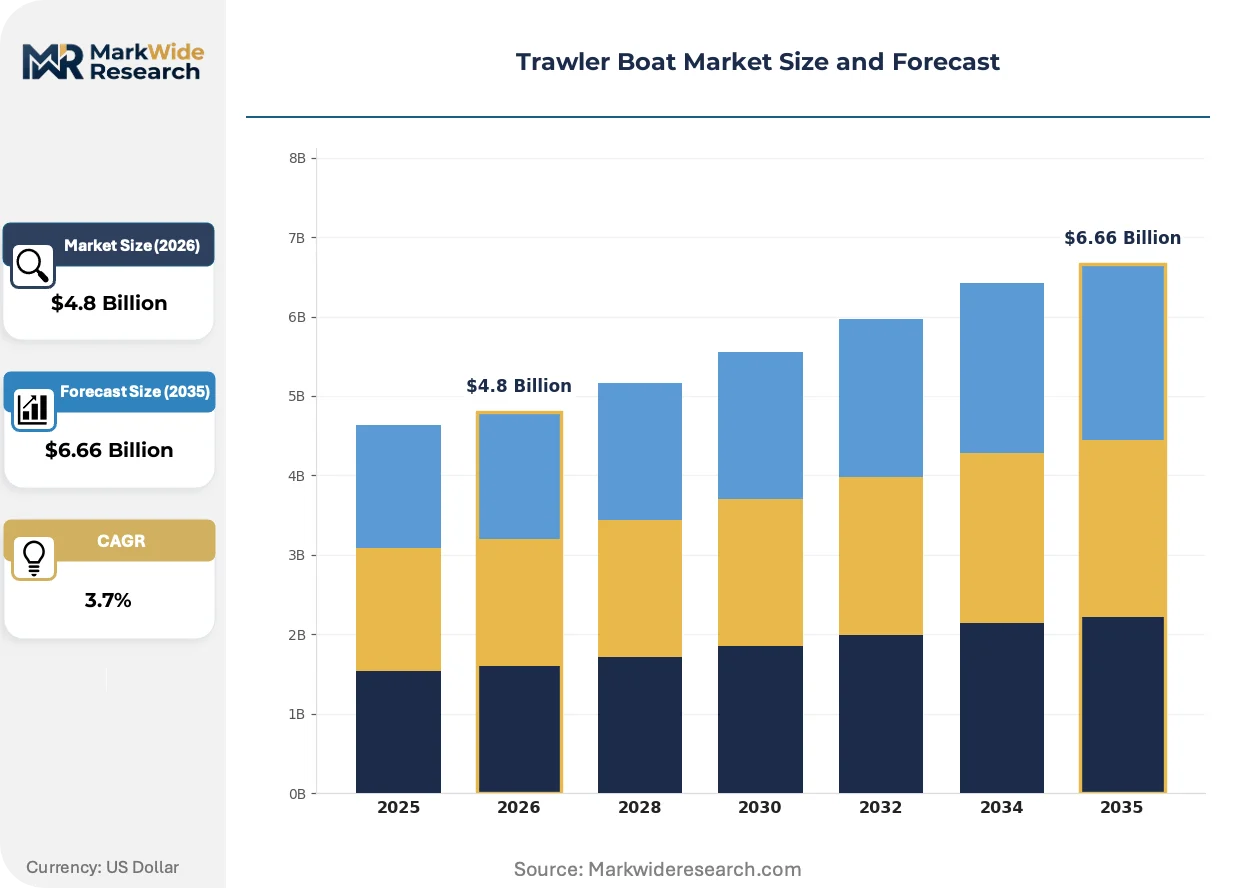
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
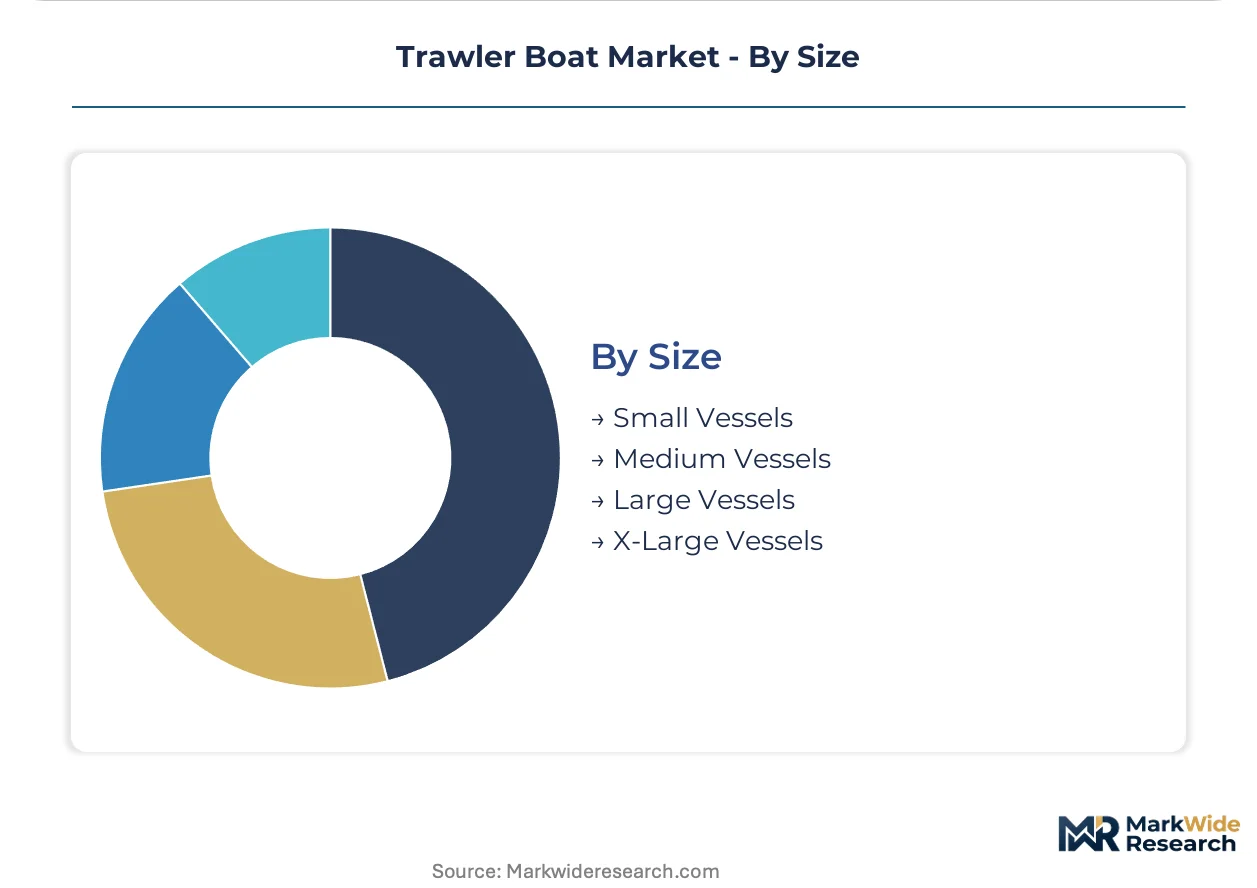
| Segmentation | Product Type: Commercial Trawlers, Recreational Trawlers, Longliners, Shrimp Boats End User: Fishermen, Tour Operators, Research Institutions, Government Agencies Installation: Onboard Manufacturing, Custom Builds, Refurbished Boats, Standard Models Size: Small Vessels, Medium Vessels, Large Vessels, X-Large Vessels |
| Companies Covered | Groupe Beneteau, Nordhavn, Helmsman Trawlers, Bering Yachts, Nordic Tugs, Kadey-Krogen Yachts, Selene Yachts Group, Marlow Hunter, Mirage Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trawler Boat Market Strategic Shifts
Propulsion technology and regulatory compliance frameworks are fragmenting the trawler market into distinct performance tiers, with divergent investment patterns separating expedition builders from commercial fleet suppliers.
Hull construction material is bifurcating between aluminum alloys for weight-sensitive coastal operators and steel plate for ice-class endurance buyers. Southeast Asian fishing cooperatives favor welded aluminum for corrosion resistance in tropical waters, while Arctic-capable expedition builders specify high-tensile steel for impact resistance. This material divergence is compressing mid-market fiberglass production as buyers sort into distinct performance-price tiers.
The EPA's diesel exhaust standards for Category 3 marine engines are compelling US-flagged commercial operators to repower with Tier 4-certified systems or install scrubber alternatives. Engine manufacturers are reallocating production capacity toward compliant powertrains, while yards in the Pacific Northwest and Gulf Coast face compressed installation windows before enforcement deadlines. Smaller operators are responding by concentrating vessel replacement rather than retrofitting aging hulls.
Charter management companies are consolidating vessel procurement under multi-hull fleet agreements, displacing individual owner-operator purchases in the 50-70 foot recreational segment. This buyer concentration shifts specification authority from retail customers to professional fleet managers prioritizing standardized maintenance protocols and residual value predictability. The pattern is most visible in the Mediterranean and Caribbean charter hubs where operators seek hull commonality for crew interchangeability.
Trawler Boat Market Segmentation
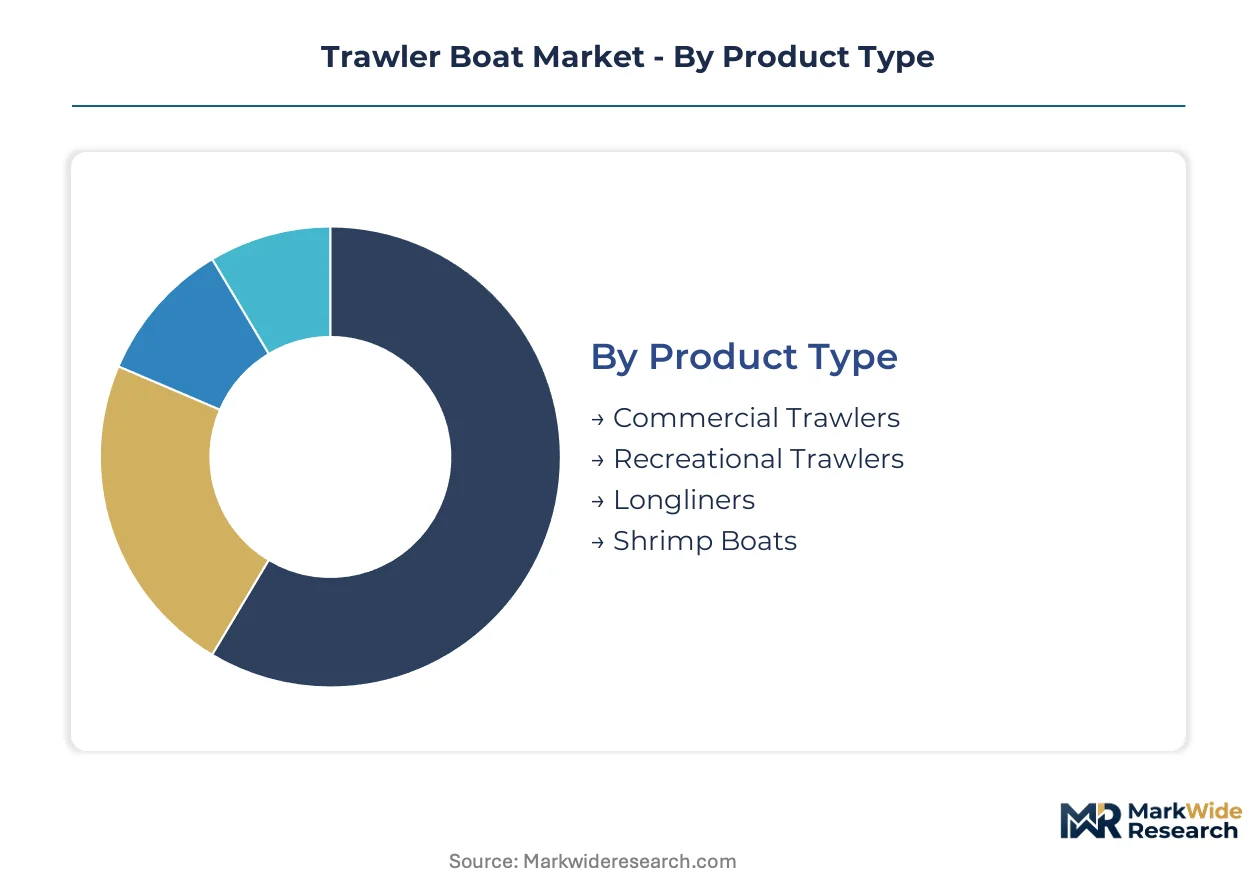
Segmentation in the trawler boat market reveals how margin pools fragment between industrial fleet operators and affluent owner-operators. Hull specifications, propulsion systems, and regulatory compliance tiers create distinct competitive battlegrounds across each dimension.
Product Type:
Margin concentration favors vessels engineered for continuous-duty operation with integrated preservation systems.
- Commercial Trawlers:Full-displacement steel hulls rated for 24-hour engine operation carry refrigerated seawater systems and processing decks. Southeast Asian fishing cooperatives in Vietnam's Da Nang cluster are specifying these hulls for export-oriented catch preservation.
- Recreational Trawlers:Semi-custom interiors with liveaboard accommodations command builder premiums through owner-operator personalization. Expedition buyers in Australia and New Zealand are converting these assets into crewed charter operations.
- Longliners:Specialized gear handling equipment for pelagic line fishing.
- Shrimp Boats:Shallow-draft configurations with outrigger stabilization systems.
Commercial Trawlers hold installed capacity. Recreational Trawlers is rotating up the share rankings.
End User:
Procurement authority is shifting from individual owners toward fleet managers and institutional buyers.
- Fishermen:Industrial cooperatives and independent operators prioritize refrigerated hold capacity and fuel efficiency for extended voyages. Vietnamese regional processors are expanding fleet orders to serve export market demand.
- Tour Operators:Charter management companies are consolidating multi-hull fleet agreements for standardized maintenance protocols. Mediterranean and Caribbean hubs seek hull commonality for crew interchangeability.
- Research Institutions:Ice-class endurance specifications for polar and deep-ocean survey work.
- Government Agencies:Patrol and fisheries enforcement configurations with extended range requirements.
Fishermen dominate current order books. Tour Operators is climbing the fastest among end-use categories.
Installation:
Build methodology determines yard exposure to steel price volatility and engine supply bottlenecks.
- Onboard Manufacturing:Hull fabrication at dedicated yard facilities with captive supply chains for ice-class steel plate. Fixed-price contracts face margin compression when input costs swing.
- Custom Builds:Semi-custom expedition trawlers with owner-specified interior configurations. Bering Yachts and Selene Yachts Group serve this tier through steel-hulled ice-class endurance models.
- Refurbished Boats:Tier III engine repowers and scrubber retrofits for existing hulls.
- Standard Models:Production efficiency for fleet operators with minimal specification variance.
Onboard Manufacturing anchors yard revenue. Custom Builds is gaining share fastest among installation modes.
Size:
Hull length dictates regulatory compliance tier and propulsion technology options.
- Small Vessels:Sub-24-meter fiberglass and aluminum hulls for coastal operators. CE certification under the Recreational Craft Directive imposes fixed costs that burden European yards serving this segment.
- Medium Vessels:The 50-70 foot range where charter management companies are consolidating fleet procurement. Standardized specifications displace individual owner-operator purchases in Mediterranean and Caribbean hubs.
- Large Vessels:Ocean-crossing displacement hulls with 1,000+ nautical mile range.
- X-Large Vessels:Expedition platforms with ice-class steel construction and hybrid-electric propulsion options.
Medium Vessels carries current volume concentration. X-Large Vessels shows the steepest expansion trajectory among size tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal expansion underwrites Southeast Asia's export reach for Vietnamese processors. Da Nang's refrigerated seawater infrastructure connects Pacific catch to Atlantic markets. This maritime corridor shapes regional fleet investment patterns.
United States
Commercial operators in the Pacific Northwest and Gulf Coast prioritize Tier 4-certified engine repowers. The EPA's diesel exhaust standards for Category 3 marine engines compress installation timelines. Seattle-Tacoma yards coordinate scrubber retrofits for Alaska-bound fishing fleets.
Vietnam
Regional processors in the Da Nang shipbuilding cluster expand refrigerated hold capacity for export markets. The government's fisheries modernization program subsidizes hull upgrades with integrated cooling systems. Vietnamese cooperatives specify welded aluminum construction for tropical corrosion resistance.
Germany
Engine suppliers concentrate Tier III-compliant marine diesel production for European fleet operators. The EU F-Gas Regulation accelerates refrigerant system replacement cycles. Hamburg-Bremen port complexes coordinate retrofit scheduling for North Sea fishing cooperatives.
Australia
Affluent owner-operators convert private expedition trawlers into crewed charter assets. The country's marine park noise regulations drive hybrid-electric propulsion interest. Sydney-Perth operators expand fleet agreements for standardized maintenance protocols.
Japan
Domestic builders face supply bottlenecks for continuous-duty diesel generators. METI efficiency standards reshape hull displacement-to-power optimization. Nagoya-Osaka manufacturing corridors concentrate ice-class steel fabrication for Arctic-capable vessels.
Trawler Boat Market Competitive Environment
Listed leaders compete with private specialists across hull fabrication and propulsion integration. The vendor base separates into scale-driven production yards, semi-custom expedition builders, and regional fleet suppliers. Three archetypes dominate: full-displacement steel specialists, aluminum coastal fabricators, and hybrid-electric system integrators. Consolidation pressures concentrate among engine suppliers while yard-level competition fragments across material specializations and geographic proximity to fishing clusters.
Within the expedition-builder tier, Nordhavn and Bering Yachts exemplify full-displacement hull expertise for offshore-capable segments. Selene Yachts Group occupies a position in semi-custom interior configurations that command builder premiums. Among European-listed manufacturers, Groupe Beneteau represents scale-driven production efficiency for standardized fleet models. These three anchors illustrate how competitive positioning fragments between premium endurance specifications and volume production economics.
| Leading Market Players |
|---|
| Groupe Beneteau |
| Nordhavn |
| Helmsman Trawlers |
| Bering Yachts |
| Nordic Tugs |
| Kadey-Krogen Yachts |
| Selene Yachts Group |
| Marlow Hunter |
| Mirage Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Aluminum substitution for steel in Southeast Asian coastal hulls simultaneously redraws supplier geography toward Chinese smelters and compresses pricing premiums for ice-class builders locked into European plate contracts. This material divergence concentrates margin pressure on yards without flexible sourcing while rewarding aluminum-integrated fabricators with cost advantages in tropical corrosion environments.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement from individual owner-operator purchases, with commercial cooperatives extracting scale concessions unavailable to expedition buyers. Price differentiation hinges on CE certification grade and refrigerated hold integration depth, with Tier III engine bundling commanding premiums. Pricing pressure stems from steel input volatility eroding fixed-price contract margins. Fleet operators exhibit highest price sensitivity, while expedition buyers prioritize specification over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites Vietnamese hull exports to Atlantic markets, creating logistics dependencies that concentrate delivery risk. Manufacturing draws from Chinese aluminum processing, Japanese diesel generator production, and German engine component fabrication. Single-source vulnerability concentrates in Tier III-compliant powertrain suppliers. Distribution runs through Da Nang shipbuilding cluster coordination with regional processor fleet managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where IMO emission tier compliance creates switching costs that lock fleet operators into established yard relationships.
For Market Incumbents: Secure captive supply arrangements for ice-class steel plate to insulate margins from input volatility. Deepen certification investment in hybrid-electric system integration before EPA enforcement windows compress. The threat of aluminum coastal fabricators eroding mid-market share demands backward integration into welding capacity. For New Entrants and Emerging Players: CE certification fast-tracks through notified body partnerships in Hamburg-Bremen corridors unlock European recreational access. White-space concentrates in sub-24-meter aluminum coastal builds for Vietnamese fishing cooperatives. Charter management procurement consolidation creates fleet-agreement entry paths. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed expedition builders holding ice-class steel expertise but lacking hybrid-electric integration. Long-term viability favors yards with displacement-to-power optimization capabilities and refrigerated hold engineering depth. Watch IMO carbon-intensity indexing implementation as fleet replacement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Tier III Engine Repower Program | EPA enforcement deadlines compress installation windows for Alaska-bound Pacific Northwest fleets. |
| Hybrid-Electric System Integration | Lithium-ion battery convergence with diesel generators enables silent operation in Australian marine parks. |
| Aluminum Hull Fabrication Scale-Up | Welded aluminum construction captures Vietnamese cooperative demand for tropical corrosion resistance. |
| Refrigerated Seawater Retrofit | EU F-Gas Regulation accelerates replacement cycles for European-registered fish preservation systems. |
| Charter Fleet Management Partnership | Mediterranean and Caribbean hub consolidation shifts procurement authority toward standardized maintenance protocols. |
Study Parameters
Operator-level perspectives from shipyard production managers, fishing cooperative fleet directors, charter company procurement officers, and marine engine technical specialists anchored the qualitative base. Primary interview findings triangulated against customs trade databases, IMO regulatory filing repositories, SEC vessel manufacturer disclosures, and regional fisheries modernization program documentation. Bottom-up hull delivery tallies reconciled with top-down fleet capacity estimates.
Sensitivity analysis tested demand elasticity across product type, hull material, propulsion architecture, end-use category, and regional regulatory cluster dimensions. CAGRs derived from segmented growth trajectory modeling incorporating refrigerated hold installation rates, emission compliance retrofit cycles, and charter fleet expansion patterns. Industry-specific inputs included Da Nang shipbuilding cluster order backlogs and Tier III engine supplier delivery lead times.
Underlying assumptions cover stable steel-aluminum price spreads and IMO enforcement timeline adherence, with deviation risk concentrated in supply bottlenecks for compliant powertrains and drydock scheduling conflicts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Marine Fuel Injection System Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Yacht Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Sea-Based Vehicle Carrier Market