
 Small Boats Market | 2026-2036
Small Boats Market Size, Share, and Industry Trends Forecast 2026-2036
Small Boats Market Intelligence
Customer concentration in the small boats market is shifting from traditional private ownership towards fractional ownership and boat club models. Brunswick Corporation leverages its extensive dealer network and brand portfolio, including Sea Ray Boats Inc, to capture diverse consumer segments. Beneteau Group SA specializes in both sail and powerboats, differentiating through European design aesthetics and innovation. Yamaha Motor Co Ltd dominates the outboard engine segment, providing propulsion systems to numerous boat builders.
Small boats are defined as recreational or utility watercraft typically under 26 feet in length, constructed from materials like fiberglass, aluminum, or composite polymers. Their primary purpose is to provide access to near-shore and inland waterways for activities ranging from fishing to water sports. Outboard engines remain the dominant propulsion choice due to their power-to-weight ratio, though electric motors represent the fastest-growing category. Within applications, leisure cruising and fishing command the largest share, using popular configurations like bowriders and center console boats.
Regulations from the United States Environmental Protection Agency (EPA) on engine emissions and the European Union's CE marking requirements for safety and design are critical for market access. These standards directly influence engine technology choices and hull construction methods, forcing manufacturers to adopt cleaner and safer designs. Stakeholder success will depend on navigating the divergent paths of electrification adoption rates and regional consumer preferences for specific boat types.
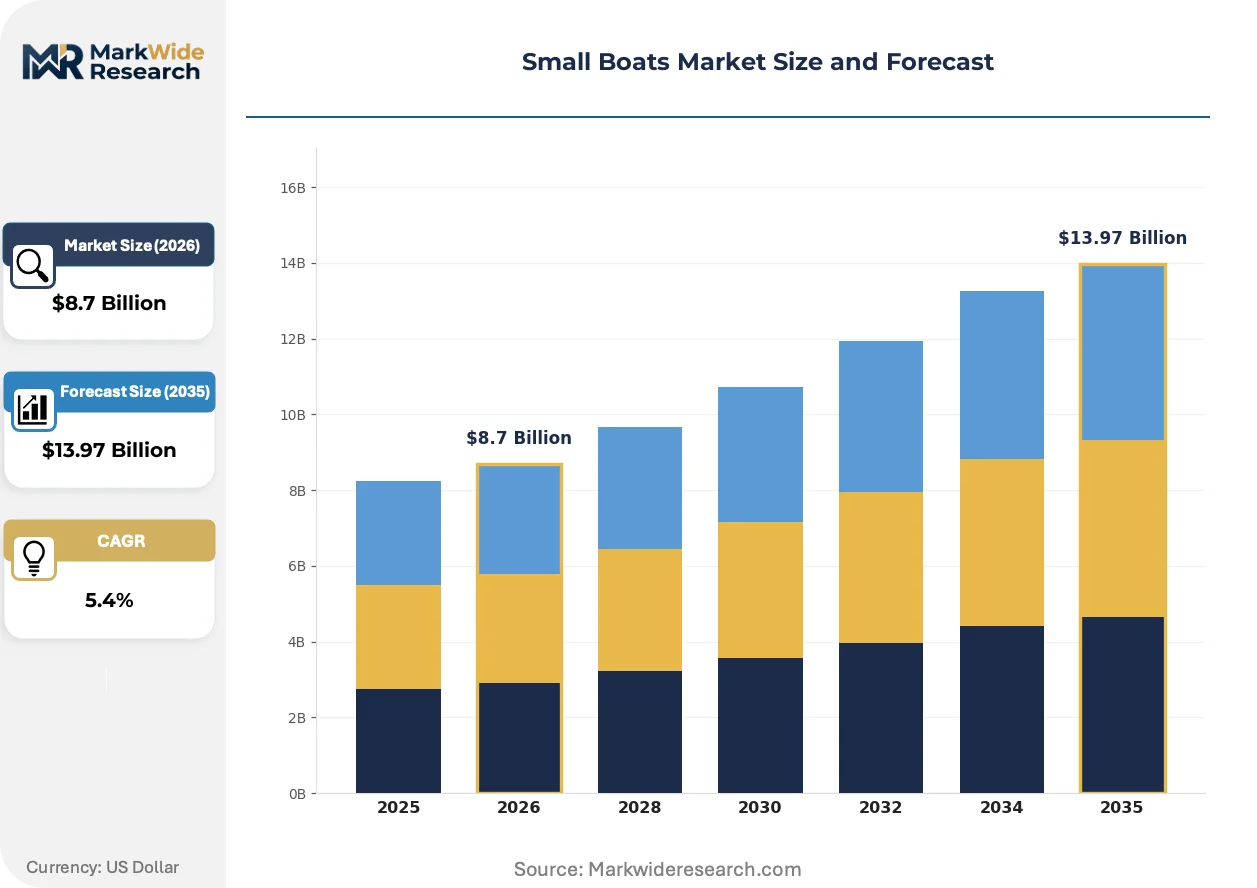
Market Dynamics
The central structural force shaping the small boats market is the tension between rising consumer demand for recreational water access and intensifying global regulatory pressure for decarbonization, compelling a fundamental shift in propulsion technology and hull design.
Growth Catalysts
- Leisure and Tourism Expansion:A surge in domestic and coastal tourism, particularly in markets like the United States and Australia, drives demand for recreational watercraft for activities such as fishing and cruising.
- Government Electrification Support:Policy frameworks like the EU Green Deal and incentives within the US Inflation Reduction Act encourage the transition to electric mobility, which extends to the marine sector.
- Material Science Advances:The development of lighter, more durable composite polymers and advanced aluminum alloys enables manufacturers to build more fuel-efficient and higher-performance boat hulls for all propulsion types.
Market Restraints
- Input Material Price Volatility:Unpredictable costs for essential raw materials, including petroleum-based fiberglass resins and aluminum, directly impact manufacturing margins and final product pricing.
- Fragmented Regulatory Landscapes:Manufacturers face high compliance costs navigating differing standards, such as engine emission limits from the US EPA and design safety rules for the EU's CE marking.
- Electric Boating Infrastructure Deficit:The slow rollout of high-speed marine charging infrastructure outside of select premium marinas acts as a significant barrier to the widespread adoption of all-electric boats.
Strategic Opportunities
- Subscription and Fractional Models:Offering boat club memberships and fractional ownership schemes can attract a wider customer base, especially in urban areas where cost and storage are barriers to sole ownership.
- Autonomous and Assisted Docking:Integrating advanced sensor suites and joystick piloting systems to simplify the difficult task of docking appeals to new and less experienced boaters, creating a valuable feature upgrade. *Sustainable Boat Construction: Commercializing watercraft built from recyclable thermoplastics or bio-composites can capture a growing segment of environmentally conscious consumers and create brand differentiation.
Industry Challenges
- Marine Technician Scarcity:A persistent shortage of skilled technicians trained in modern marine engine diagnostics, electrical systems, and composite repair slows service and limits aftermarket support capacity.
- Complex Component Sourcing:Managing a diverse global supply chain for everything from specialized marine-grade electronics to propulsion systems exposes builders to significant logistical risks and potential delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Boats Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Inflatable Boats, Jon Boats, Bowriders, Cabin Cruisers, Center Console Propulsion: Outboard Engines, Inboard Engines, Electric Motors, Sail Powered, Manual Paddling Application: Fishing, Leisure Cruising, Water Sports, Search and Rescue, Patrol Operations End User: Private Owners, Rental Services, Government Agencies, Maritime Trainers, Research Institutes |
| Companies Covered | Brunswick Corporation, Yamaha Motor Co Ltd, Bombardier Recreational Products Inc, Beneteau Group SA, Malibu Boats Inc, Sea Ray Boats Inc, MasterCraft Boat Company LLC, Grady-White Boats Inc, Marine Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Boats Market Strategic Shifts & Innovations
Electrification and digitalization are fundamentally altering boat design, operation, and ownership models. These forces are creating new product categories and service opportunities while pushing manufacturers to re-evaluate traditional hull construction and propulsion systems to meet new performance and environmental expectations.
Digital helm technology provides centralized control over a boat's navigation, engine, and onboard systems through integrated multi-function displays. The primary adopters are builders of premium center console and bowrider boats seeking to offer a more intuitive, car-like user experience. This onboard connectivity is converging with telematics to enable remote diagnostics and over-the-air software updates, shifting value towards lifecycle services.
Regulatory mandates from bodies like the United States Environmental Protection Agency (EPA) are setting stricter limits on exhaust and evaporative emissions for marine gasoline engines. This action is forcing engine manufacturers to invest heavily in catalyst technologies and more efficient fuel injection systems. The outboard engine category is most affected, accelerating development of cleaner internal combustion options and four-stroke models to replace older two-stroke technologies.
A notable behavioral shift involves consumers moving from sole ownership toward access-based consumption. This pattern disrupts the traditional dealer-to-private-buyer sales channel, creating space for professionally managed boat clubs and peer-to-peer rental platforms to flourish. This trend is most visible in high-demand coastal markets within the United States and the Mediterranean, where slip and mooring scarcity makes shared access a practical alternative.
Small Boats Market Segmentation
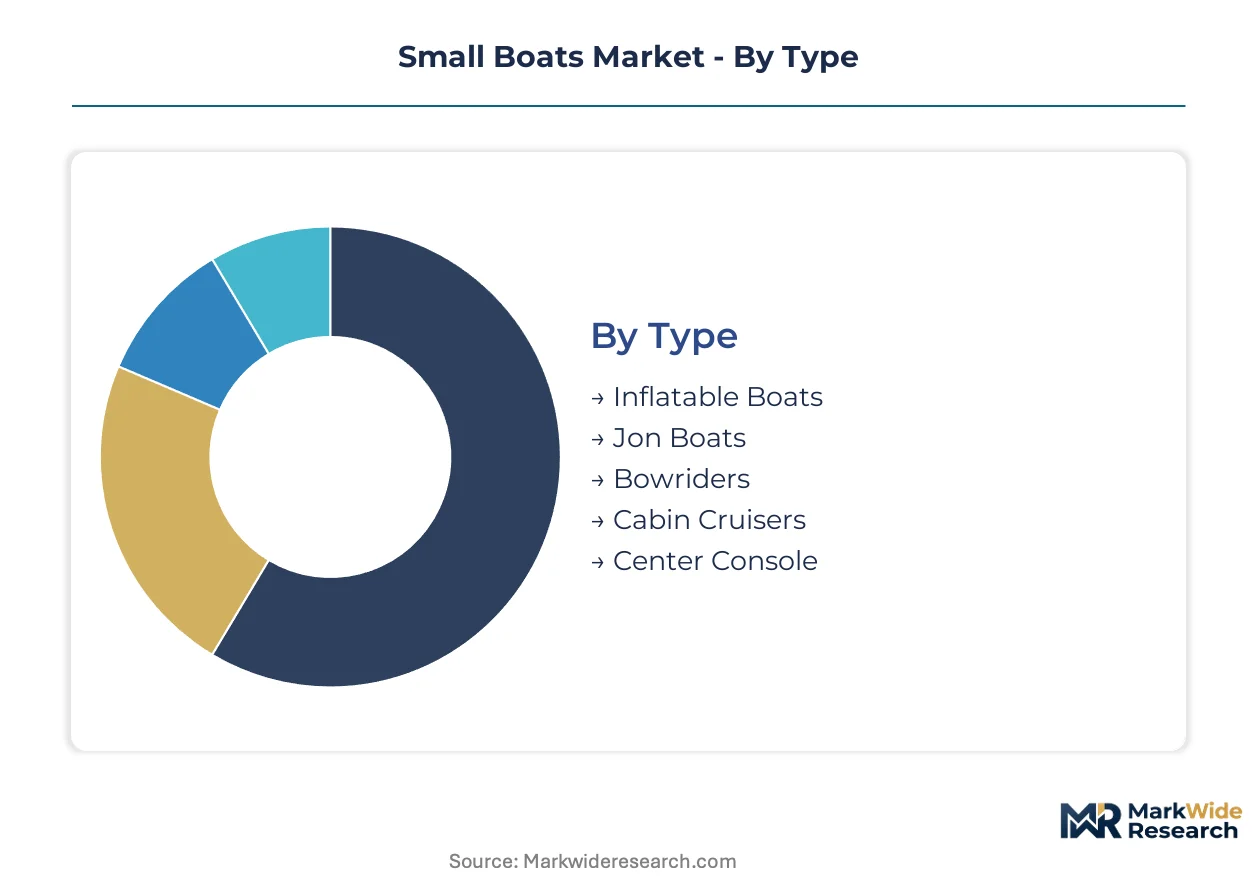
Understanding the small boats market through its core segments reveals how manufacturers align product offerings with diverse consumer needs and operational demands. This segmentation provides clarity on where investment in new materials and propulsion technologies yields the greatest commercial returns. Market dynamics are heavily influenced by the interplay between recreational desires and regulatory pressures.
Type:
The manufacturing base for small boats exhibits varying degrees of specialization, with certain production hubs concentrating on specific hull designs to optimize material flow and assembly.
- Bowriders:These open-bow recreational vessels feature seating forward of the helm, often constructed from fiberglass. Demand concentrates in coastal tourism hubs within the United States, driven by family cruising and water sports.
- Center Console:Characterized by a central helm and open deck, these boats are typically built with robust fiberglass hulls for offshore performance. Utility in fishing drives demand along the US Gulf Coast.
- Inflatable Boats:Lightweight, portable vessels with rigid inflatable hulls, serving as tenders or for shallow-water exploration.
- Jon Boats:Flat-bottomed aluminum boats, favored for stability in calm, shallow inland waterways and fishing applications.
- Cabin Cruisers:Enclosed cabin boats offer overnight accommodation and protection from elements for longer leisure cruising.
Center Console absorbs the bulk of installed capacity; Bowriders is expanding most quickly.
Propulsion:
Propulsion choices for small boats are primarily dictated by the intended application, balancing factors like speed, range, and environmental impact across waterborne activities.
- Outboard Engines:These self-contained units mount on the transom, integrating engine, gearbox, and propeller, predominantly four-stroke gasoline models. Demand remains strong for fishing and water sports in the United States, valued for power-to-weight ratio.
- Electric Motors:Operating on battery power, these motors offer quiet, emissions-free propulsion for sensitive areas and short-range cruising. Adoption accelerates in European inland waterways due to stricter regulations.
- Inboard Engines:Fixed within the hull, inboard engines connect to a propeller shaft, offering a lower center of gravity and higher horsepower.
- Sail Powered:Using wind as primary propulsion, sail-powered boats offer a sustainable and quiet experience for recreational cruising.
- Manual Paddling:Requiring human effort with paddles or oars, manual propulsion is common for kayaks, canoes, and small tenders.
Demand for Outboard Engines remains strong across leisure cruising, while Electric Motors show consistent growth.
Application:
The volume of small boat usage varies significantly by activity, with recreational pursuits consistently driving the highest numbers of watercraft deployed.
- Fishing:This application uses small boats for recreational or subsistence fishing, requiring features like rod holders and livewells. Demand is high in North American inland lakes and coastal regions.
- Leisure Cruising:Encompassing general recreational boating, this application focuses on relaxation, sightseeing, and enjoying time on the water. Growth is pronounced in Australia's Gold Coast as private owners seek more recreational water activities.
- Water Sports:Activities like waterskiing and wakeboarding utilize small boats with powerful engines to tow participants in recreational lakes.
- Search and Rescue:Government agencies and volunteer organizations deploy specialized small boats for emergency response and safety operations.
- Patrol Operations:Law enforcement and border security agencies use small, agile boats for surveillance and enforcement duties in coastal waters.
Fishing accounts for the majority of market activity, with Leisure Cruising showing significant expansion in specific regions.
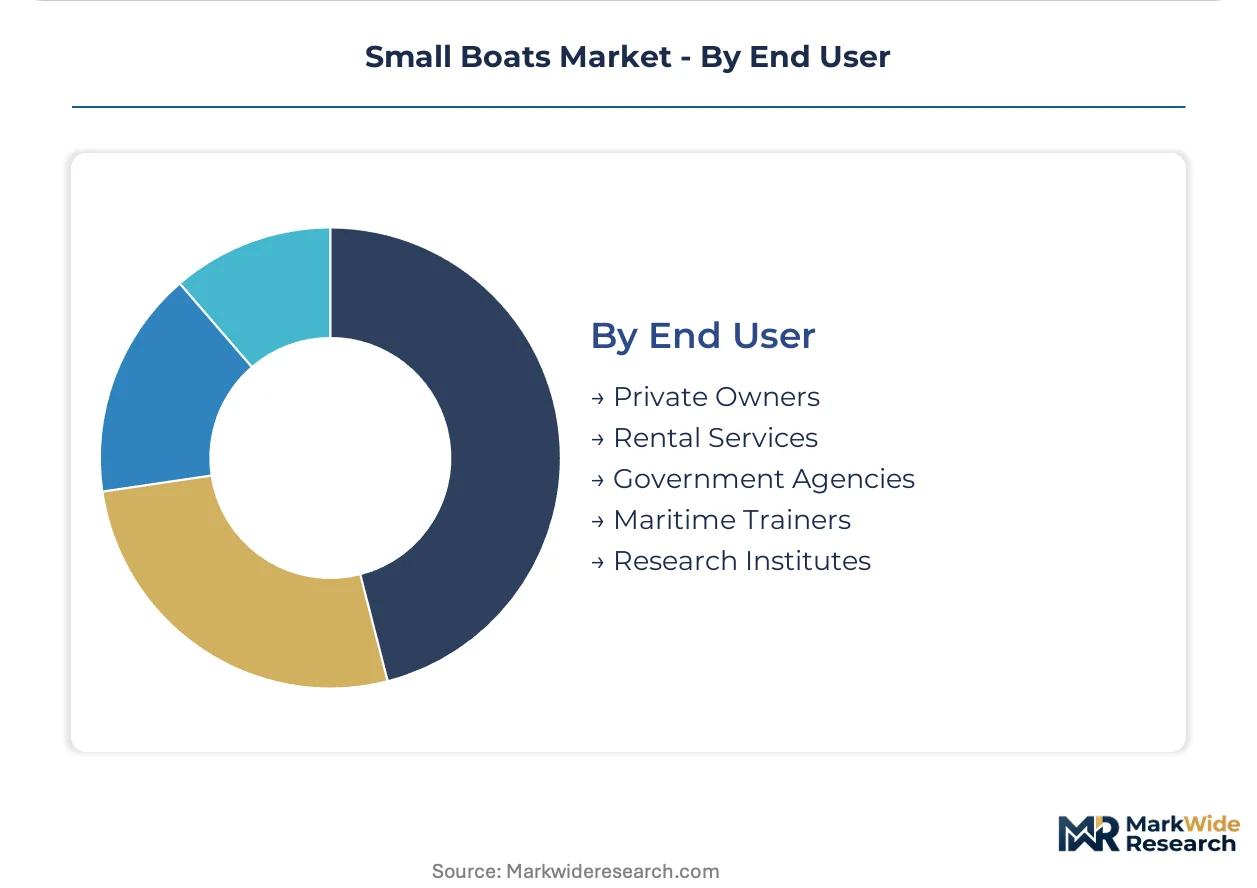
End User:
Different customer types exhibit distinct purchasing behaviors and operational requirements, influencing design specifications and service models within the market.
- Private Owners:Individual consumers purchase small boats for personal recreational use, including fishing and cruising, often seeking customization. The United States remains a strong market for private ownership.
- Rental Services:Businesses offer small boats for short-term hire, catering to tourists and individuals seeking water access without ownership. This segment gains traction in high-demand Mediterranean coastal markets.
- Government Agencies:Authorities like coast guards and environmental protection agencies acquire small boats for patrol and scientific missions.
- Maritime Trainers:Educational institutions utilize small boats for teaching navigation, seamanship, and safety procedures to aspiring mariners.
- Research Institutes:Scientific organizations employ small boats for marine biology studies, hydrological surveys, and environmental monitoring.
The shift towards Rental Services ownership models is reshaping the market, complemented by steady demand from Private Owners operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for small boats primarily centers on coastal and inland water tourism hubs, particularly within the United States and Australia. These regions exhibit robust consumer interest in recreational water activities, driving significant market expansion for various boat types and propulsion systems. European markets also show distinct patterns, influenced by stringent environmental regulations.
United States
Consumer interest in fishing and leisure cruising drives substantial demand across North American inland lakes and coastal regions. Regulations from the United States Environmental Protection Agency (EPA) on engine emissions influence propulsion technology choices for manufacturers. Florida's extensive coastline and numerous waterways serve as a significant hub for boat manufacturing and sales, supporting a dense network of marinas and service providers.
Australia
Leisure cruising and water sports are particularly popular, especially along the country's extensive coastline. The Australian Maritime Safety Authority (AMSA) sets standards for vessel safety and environmental protection, influencing local design and construction. The Gold Coast in Queensland is a prominent center for recreational boating, attracting private owners and rental services for water-based activities.
France
European design aesthetics and sustainable boating initiatives shape consumer preferences, particularly for sail and electric-powered vessels. The European Union's CE marking requirements ensure safety and environmental compliance for market access. Coastal areas like the French Riviera and Brittany host active boating communities, with boat clubs and rental services gaining traction to provide water access.
Canada
Recreational fishing and cruising drive demand across Canada's vast network of lakes and coastal waters. Transport Canada regulates marine safety and environmental protection, impacting boat design and engine specifications. The Great Lakes region, shared with the United States, supports a significant recreational boating industry, with manufacturers and dealers serving both domestic and cross-border markets.
Japan
Fishing and marine leisure activities sustain demand, particularly for compact and efficient small boats suitable for coastal waters. The Ministry of Land, Infrastructure, Transport and Tourism (MLIT) oversees marine regulations and safety standards. Coastal cities like Shizuoka and Hamamatsu are recognized centers for marine engine manufacturing and boat building, supporting both domestic use and export markets.
Small Boats Market Key Industry Players
North American producers anchor one tier, focusing on broad product portfolios and extensive dealer networks, while European specialists hold another, emphasizing design and niche segment innovation. The market structure exhibits a tiered consolidation, with a few large entities dominating specific segments. Strategic archetypes include diversified marine conglomerates and specialized engine manufacturers. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand market reach.
Within the diversified marine conglomerate archetype, Brunswick Corporation leverages a broad brand portfolio and extensive dealer network to reach diverse consumer segments. Yamaha Motor Co Ltd, a Japanese multinational, exemplifies a specialist in propulsion systems, dominating the outboard engine segment. Beneteau Group SA, based in France, occupies a position emphasizing European design aesthetics and innovation across both sail and powerboat categories, appealing to discerning consumers.
| Leading Market Players |
|---|
| Brunswick Corporation |
| Yamaha Motor Co Ltd |
| Bombardier Recreational Products Inc |
| Beneteau Group SA |
| Malibu Boats Inc |
| Sea Ray Boats Inc |
| MasterCraft Boat Company LLC |
| Grady-White Boats Inc |
| Marine Products Corporation |
| Others |
Cost & Logistics Intelligence
Skilled marine technician scarcity, particularly in the United States and Europe, drives labor-cost differentials that significantly influence pricing-tier spreads across small boat segments. These specialized labor costs impact both initial boat pricing and long-term maintenance expenses.
Pricing Analysis
Volume-driven segments like bowriders and center consoles operate on thinner margins, while custom cabin cruisers command higher profit percentages. The dominant pricing structure remains per-unit transactional, with price differentiation stemming from European design aesthetics and advanced propulsion system integration. Pricing softness in the utility segment reflects input material price volatility. Private owners exhibit less price sensitivity for premium features compared to rental services focused on fleet costs.
Supply Chain Analysis
Reverse-logistics flows for small boats are nascent, primarily focused on component repair and end-of-life recycling for materials like fiberglass. Geographic supply concentration includes manufacturing hubs in the United States and France, alongside engine production in Japan. Raw material dependencies include petroleum-based fiberglass resins, aluminum, and advanced composite polymers. Complex component sourcing, particularly for marine-grade electronics, poses a structural risk due to logistical chokepoints. Distribution runs through extensive dealer networks and emerging direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The small boats market presents a supply-constrained story, with a persistent shortage of skilled marine technicians acting as a critical capacity bottleneck propping up service and maintenance pricing. This labor constraint impacts both new boat delivery and aftermarket support.
For Market Incumbents: Anchor extensive dealer networks by integrating digital helm technology and remote diagnostic capabilities to counter emerging rental platforms. Diversify product portfolios with electric motor options, leveraging existing manufacturing capacity to meet stricter EPA emissions standards. Invest in training programs for marine technicians to mitigate labor scarcity, safeguarding aftermarket service revenue against new entrants.
For New Entrants and Emerging Players: Launch via subscription and fractional ownership models in high-demand coastal markets within the United States and Mediterranean regions. Target the leisure cruising segment with sustainable boat construction using bio-composites, offering brand differentiation to environmentally conscious consumers. Focus on simplified, easy-to-operate electric models to appeal to new and less experienced boaters.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with strong intellectual property in electric propulsion or advanced materials. Long-term viability over a five-to-ten-year window depends on securing expertise in autonomous docking systems and sustainable manufacturing processes. Target acquisition archetypes include innovative electric motor developers or composite hull manufacturers. Practitioners should monitor government electrification support policies for early signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Marine Technician Training | Addresses the critical labor shortage impacting service capacity and customer satisfaction. |
| Develop Bio-Composite Hull Materials | Captures environmentally conscious consumers and aligns with sustainable manufacturing trends. |
| Integrate Autonomous Docking Systems | Appeals to new boaters, simplifies operation, and enhances user experience for all. |
| Expand Electric Propulsion R&D | Meets stringent emissions regulations and capitalizes on the fastest-growing market segment. |
| Form Fractional Ownership Partnerships | Attracts wider customer base by lowering entry barriers and optimizing asset utilization. |
Research Approach
Independent corroboration across industry reports, company financial filings, and regulatory body publications underwrites the qualitative findings and quantitative projections. Primary interviews with boat builders, engine manufacturers, marine technicians, and rental service operators provided critical market insights. This analysis employed a rigorous bottom-up and top-down triangulation approach, cross-referencing data points for accuracy.
Comparable historical periods anchored the forecast window, establishing baseline performance metrics for small boat demand. The analytical framework modeled segmentation dimensions including boat type, propulsion, application, and end-user, alongside regional regulatory clusters. Compound annual growth rates were derived through a proprietary algorithm, integrating inputs such as consumer disposable income and raw material price forecasts across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cells or advanced battery chemistries would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and consumer preference shifts. Practitioners should monitor marine charging infrastructure development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Yacht Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Amphibious Vehicle Market