
 Global Inland Waterways Vessels Market | 2026-2036
Global Inland Waterways Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inland Waterways Vessels Market Analysis
Hybrid-electric propulsion is reshaping vessel design priorities across inland fleets. Damen Shipyards Group leverages its modular shipbuilding platform to deliver standardized hybrid platforms at scale. Kirby Corporation anchors North American liquid bulk transport through its extensive towboat and barge fleet on the Mississippi River system. Rhenus Group dominates European container barge services with integrated logistics control across the Rhine and Danube corridors.
Inland waterways vessels comprise flat-bottomed or shallow-draft craft engineered for rivers, canals, and lakes, typically constructed from welded steel plate with cargo capacities ranging from several hundred to over ten thousand tonnes depending on lock dimensions and channel depth. These vessels serve commercial freight movement, passenger transport, and specialized services where waterborne logistics reduce per-tonne energy consumption compared with road or rail alternatives. Barges and towboats command the largest share of fleet investment due to persistent bulk cargo volumes, while ferries generate disproportionate margin pools through fixed-route contracts and municipal subsidies. The tourism application segment is expanding fastest as river cruise operators scale capacity on European and Asian waterways.
The European Commission's EU Green Deal and the F-Gas Regulation are tightening emissions standards for marine engines operating on Community waterways, compelling fleet operators to retrofit or replace diesel propulsion. The US EPA and Coast Guard enforce parallel ballast water and engine tier standards on domestic routes, raising compliance costs for operators like American Commercial Barge Line. Stakeholders must monitor how carbon pricing mechanisms and alternative fuel certification schemes redistribute operating economics across vessel size classes and route networks.
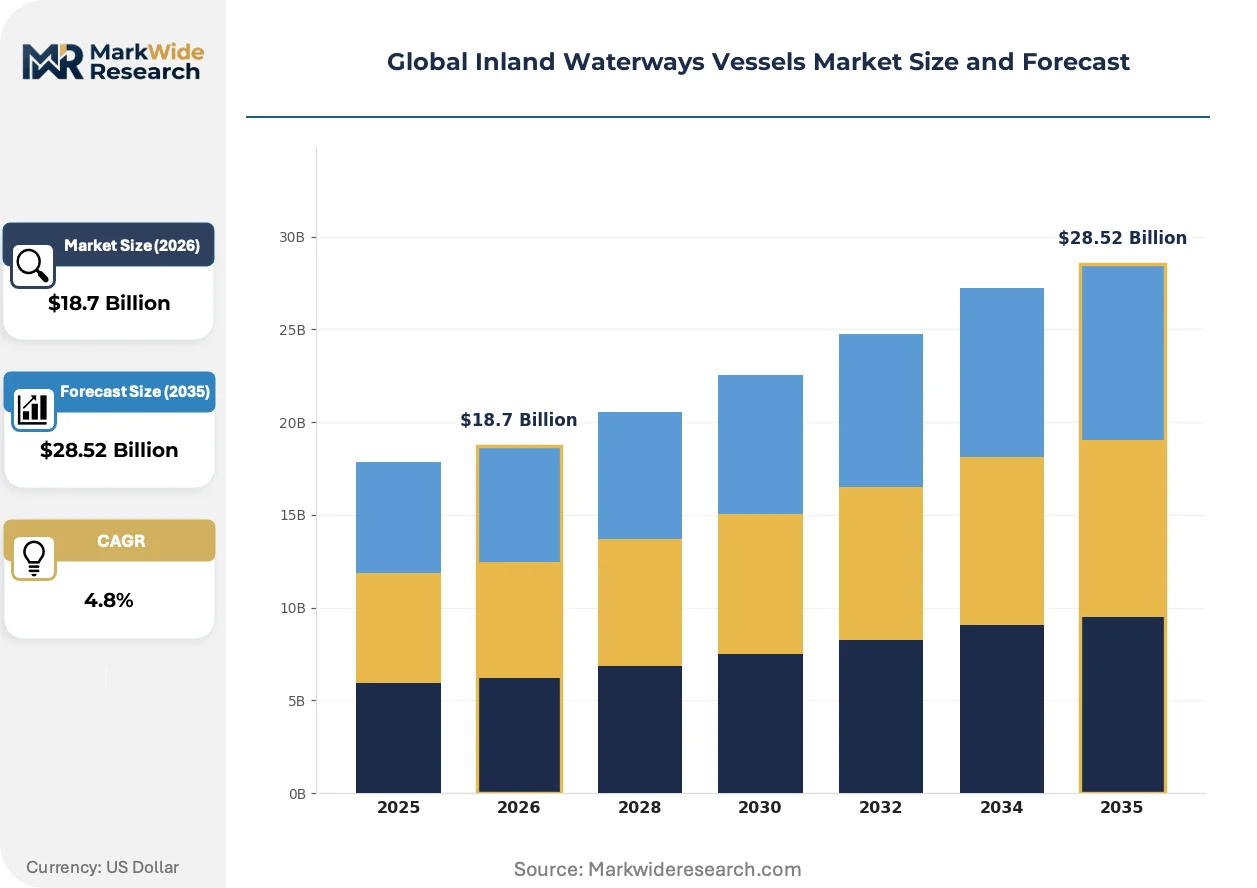
Market Dynamics
Hybrid-electric propulsion is forcing fleet operators to reconfigure capital allocation across vessel lifecycles, as battery density improvements and shore-charging infrastructure create viable alternatives to diesel-mechanical systems on major corridors.
Growth Catalysts
- EU Green Deal modal shift mandates:Binding targets for freight transfer from road to waterborne transport are accelerating barge fleet renewal along the Rhine and Danube corridors.
- Containerized cargo expansion:Logistics integrators are routing intermodal freight onto European river networks to secure lower-emission transport credentials.
- Lithium-ion battery cost curves:Declining cell prices are compressing payback periods for hybrid retrofits on existing towboats and push boats.
Market Restraints
- Steel plate price volatility:Hull construction costs fluctuate with commodity cycles, squeezing margins for small-scale builders in Eastern European shipyards.
- Lock dimension constraints:Fixed infrastructure on the Mississippi and Illinois waterway systems limits vessel scale economies regardless of demand growth.
- Diesel engine Tier 4 compliance costs:US EPA exhaust after-treatment requirements add capital burden without proportional fuel efficiency gains.
Strategic Opportunities
- Methanol-ready newbuilds:Shipyards in the Netherlands and Germany are designing dual-fuel hulls to capture future e-methanol supply chains.
- Asian river cruise expansion:Yangtze and Mekong basin tourism routes remain underdeveloped relative to European benchmarks.
- EU F-Gas Regulation retrofit incentives:Refrigerated cargo barge operators can access transition funding for climate-friendly cooling system upgrades.
Industry Challenges
- Marine electrical technician scarcity:Fleet maintenance departments lack personnel trained in high-voltage battery management and power electronics.
- Port charging infrastructure gaps:Inconsistent shore-power standards across Belgian, Dutch, and German terminals fragment route planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inland Waterways Vessels Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Barges, Towboats, Push Boats, Ferries Application: Transportation, Tourism, Cargo Handling, Research End User: Logistics Companies, Government Agencies, Tour Operators, Private Operators Capacity: Small Vessels, Medium Vessels, Large Vessels, Super Large Vessels |
| Companies Covered | Kirby Corporation, Damen Shipyards Group, CMA CGM Group, Ingram Barge Company, American Commercial Barge Line, Viking River Cruises, Rhenus Group, Hyundai Heavy Industries, Fincantieri S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inland Waterways Vessels Market Emerging Trajectories
Digital twin technology is virtualizing vessel performance optimization, while regulatory pressure on emissions intensifies propulsion experimentation and logistics buyers rewrite procurement criteria around carbon intensity.
Digital twin platforms are virtualizing hull hydrodynamics and engine load profiles for fuel optimization. Rhine corridor operators deploy these systems to simulate voyage efficiency before committing to route changes. The technology is virtualizing traditional sea-trial methodologies, compressing newbuild commissioning timelines and reducing physical prototype requirements.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in marine transport refrigeration units. Reefer barge operators must retrofit cooling systems or face operational restrictions on Community waterways. German and Dutch cold-chain logistics providers are accelerating ammonia and CO2-based system adoption ahead of mandated deadlines.
Carbon intensity clauses are rewriting freight procurement contracts on European corridors. Shippers now specify maximum CO2 per tonne-kilometer, displacing price-only tendering. Belgian retail distribution centers and German automotive plants are embedding these metrics into multi-year barge service agreements.
Global Inland Waterways Vessels Market Segmentation
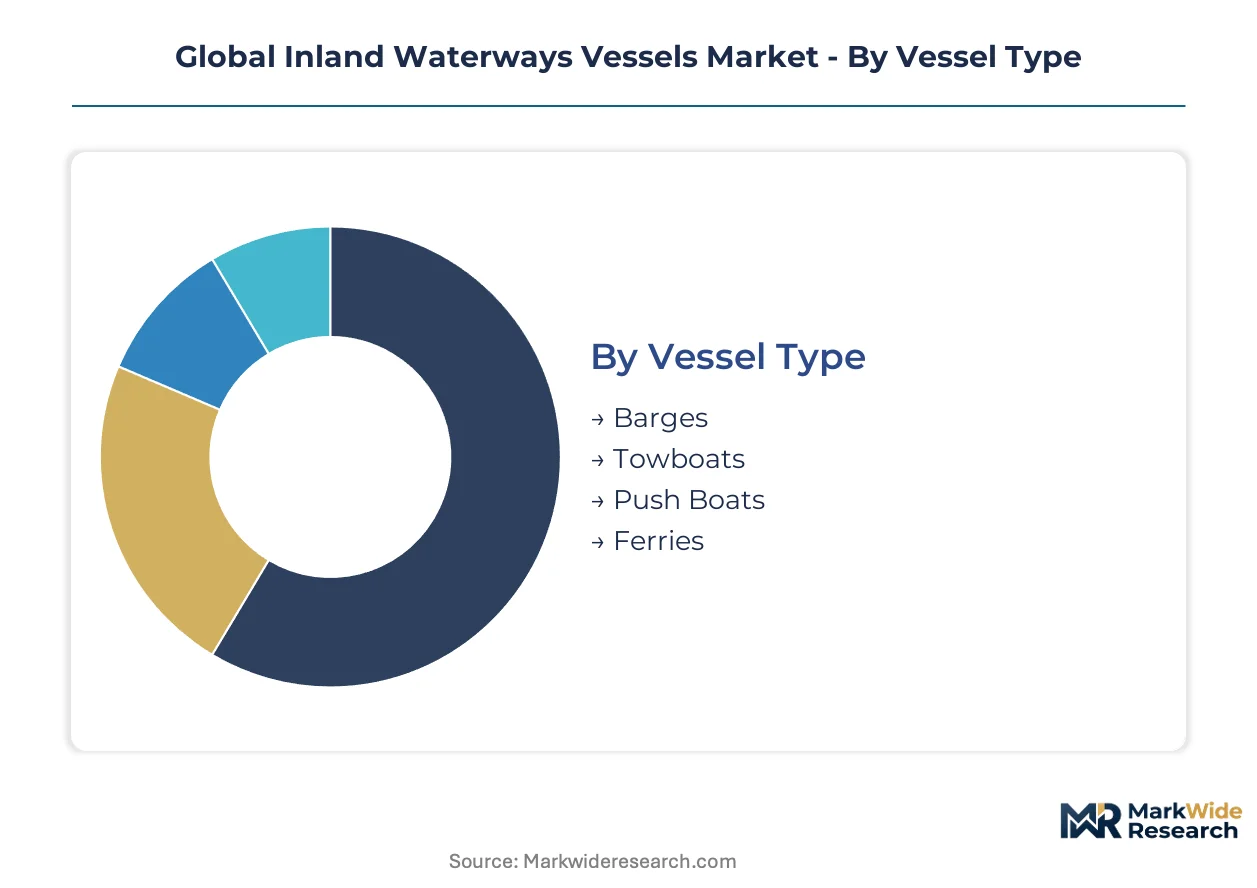
Vessel classification determines capital intensity, regulatory exposure, and route eligibility across inland waterway networks. Operators select configurations based on lock dimensions, cargo density, and shore infrastructure availability.
Vessel Type:
The use-case spectrum spans bulk commodity movement to passenger ferry services, each demanding distinct hull geometries and propulsion architectures.
- Barges:Flat-bottomed cargo platforms with welded steel construction and open or covered holds. Rhine corridor logistics integrators favor 135-meter European Class Vb designs for containerized automotive parts moving between German plants and Dutch ports. EU Green Deal modal shift mandates are accelerating barge fleet renewal versus aging road fleets.
- Towboats:Propulsion units with elevated wheelhouses for pushing barge flotillas through constrained channels. Mississippi River liquid bulk operators deploy 6,000-horsepower towboats to move petroleum product strings between Louisiana refineries and Midwest distribution terminals. Tier 4 diesel compliance costs are compressing margins for independent operators on US inland routes.
- Push Boats:Compact maneuvering vessels optimized for confined European canals and dense port environments.
- Ferries:Passenger and vehicle carriers operating fixed municipal routes with scheduled frequency requirements.
The dominant share belongs to Barges, while Ferries are closing the gap fastest on tourism corridor expansion.
Application:
Commercial utility ranges from freight efficiency to experiential services, with divergent margin structures and contract durations.
- Transportation:Scheduled passenger services on urban waterways and cross-river connections. Budapest and Bangkok operators run high-frequency ferry networks feeding metro systems during peak congestion periods.
- Tourism:River cruise vessels with hotel-grade accommodations and shallow-draft hulls for scenic corridor access. Danube and Yangtze operators are expanding capacity most quickly as experiential travel demand climbs post-pandemic.
- Cargo Handling:Dedicated freight movement including container, bulk, and liquid transport between inland ports and coastal hubs.
- Research:Specialized platforms for environmental monitoring, hydrographic survey, and academic data collection on freshwater ecosystems.
Cargo Handling commands the largest revenue pool, though Tourism is expanding most quickly on Asian route development.
End User:
Procurement authority varies between commercial fleet operators, state entities, and private owners with distinct tendering protocols.
- Logistics Companies:Integrated freight operators managing multi-modal supply chains. Rhenus Group and similar European integrators control container barge scheduling across Rhine-Danube corridors to secure lower-emission transport credentials for retail and automotive clients.
- Government Agencies:Public authorities responsible for infrastructure maintenance, patrol, and emergency response vessels. German federal waterway administration contracts Damen for standardized patrol craft on federal canal networks.
- Tour Operators:Specialized hospitality firms chartering or owning cruise vessels for packaged experiential travel.
- Private Operators:Independent owners of small cargo fleets, recreational craft, and specialized service vessels.
Logistics Companies hold the dominant procurement volume, while Government Agencies are closing the gap fastest on fleet electrification mandates.
Capacity:
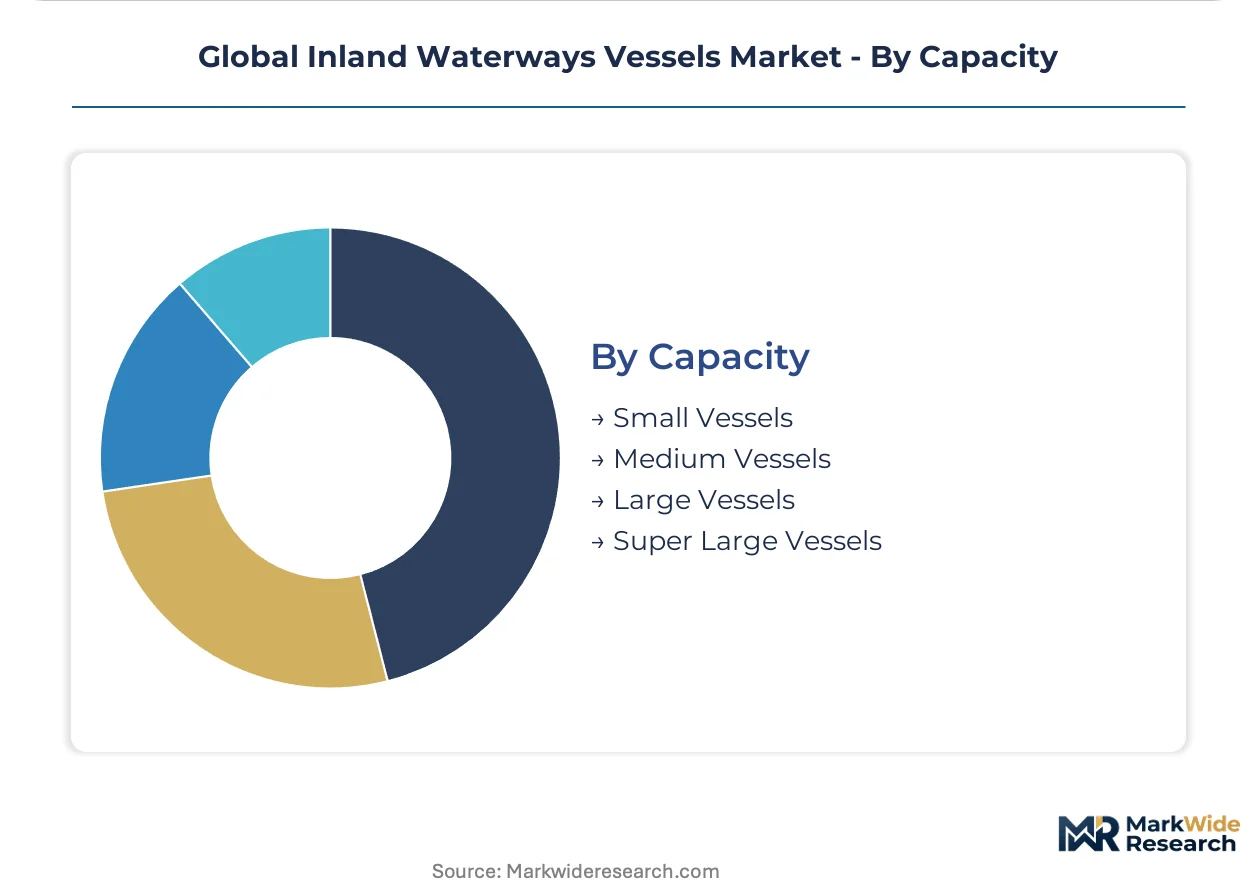
Scale economies confront infrastructure constraints as lock dimensions and channel depth fix maximum vessel dimensions.
- Small Vessels:Craft under 600 tonnes displacement for secondary canals and shallow tributaries. French and Belgian canal networks rely on these dimensions for agricultural product collection from regions lacking rail siding.
- Medium Vessels:Mid-range platforms balancing payload and route flexibility. Illinois Waterway grain operators favor this scale to navigate lock chambers while achieving viable per-tonne economics.
- Large Vessels:Maximum dimension designs for primary corridor deployment. Rhine mainline container barges exploit 11.4-meter beam limits to stack nine containers abreast on 135-meter hulls.
- Super Large Vessels:Specialized bulk platforms for specific high-volume routes with compatible infrastructure.
Large Vessels dominate mainline freight economics, though Small Vessels are gaining share fastest on last-mile logistics integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics companies and government fleet operators concentrate procurement authority along the Rhine corridor and Mississippi River system, with modal shift mandates and infrastructure renewal programs redistributing vessel demand across specific national waterways.
Germany
The EU Green Deal drives barge fleet renewal along the Rhine and Danube corridors, with logistics integrators securing lower-emission transport credentials for automotive and retail supply chains. The F-Gas Regulation compels refrigerated cargo operators to retrofit cooling systems before mandated deadlines. Duisburg and Cologne anchor container barge traffic, with 135-meter European Class Vb designs stacking nine containers abreast on maximum-dimension hulls.
United States
Liquid bulk transport dominates Mississippi River economics, with petroleum product strings moving between Louisiana refineries and Midwest distribution terminals. The EPA enforces Tier 4 diesel compliance costs through exhaust after-treatment requirements that compress margins for independent operators. St. Louis and Memphis cluster towboat deployment, where 6,000-horsepower propulsion units push barge flotillas through constrained Illinois Waterway channels.
Netherlands
Rotterdam port integration accelerates containerized cargo movement onto European river networks, with shore-charging infrastructure expanding at Belgian and German terminals. The EU Green Deal modal shift targets bind freight transfer from road to waterborne transport. Amsterdam and Utrecht concentrate hybrid-electric propulsion trials, where Damen Shipyards delivers standardized modular platforms at scale.
China
Yangtze River tourism routes expand capacity as experiential travel demand climbs post-pandemic, with river cruise operators scaling hotel-grade accommodations on shallow-draft hulls. The Ministry of Ecology and Environment advances dual carbon goals through emissions monitoring on domestic waterways. Chongqing and Wuhan anchor cruise vessel construction, while the Three Gorges Dam system constrains maximum vessel dimensions regardless of demand growth.
Belgium
Antwerp port logistics embed carbon intensity clauses into multi-year barge service agreements, with shippers specifying maximum CO2 per tonne-kilometer to displace price-only tendering. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in marine transport refrigeration units. Ghent and Liège concentrate last-mile logistics integration, where small vessels under 600 tonnes displacement serve secondary canals lacking rail siding.
Global Inland Waterways Vessels Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated logistics operators and government fleet managers anchor procurement volume. The market fragments between large-scale builders delivering standardized platforms and regional fabricators serving specialized shallow-draft requirements. Two strategic archetypes dominate: corridor-controlling fleet operators managing multi-modal scheduling, and modular shipbuilders compressing commissioning timelines through digital twin virtualization. Competitive moves concentrate on hybrid propulsion partnerships and methanol-ready newbuild design licensing.
Within the integrated logistics tier, Rhenus Group and Kirby Corporation exemplify corridor-controlling archetypes, with the former anchoring European container barge services and the latter commanding North American liquid bulk transport. Among specialized builders, Damen Shipyards occupies a position representing modular platform standardization. These three entities sit within distinct competitive vectors—continental logistics integration, river system liquid bulk dominance, and scalable hybrid vessel delivery—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Kirby Corporation |
| Damen Shipyards Group |
| CMA CGM Group |
| Ingram Barge Company |
| American Commercial Barge Line |
| Viking River Cruises |
| Rhenus Group |
| Hyundai Heavy Industries |
| Fincantieri S.p.A. |
| Others |
Supply Flow & Price Mechanics
Steel plate commodity volatility functions as the primary risk vector, compressing margins for European and Asian hull fabricators while simultaneously widening pricing spreads between standardized barge platforms and custom shallow-draft vessels. This input-cost instability forces fleet operators to index long-term charter rates against metal futures, fundamentally reshaping both procurement contract structures and supplier relationship architectures across the inland waterway vessel sector.
Pricing Analysis
Cost-plus contracts with London Metal Exchange steel indexation dominate newbuild procurement between Rhine corridor operators and Dutch-German shipyards. Price differentiation separates EU Green Deal-certified hybrid vessels from legacy diesel platforms, with certification tier and battery system scale driving tiered quotations. Pricing pressure stems from Tier 4 compliance costs on US inland routes, where exhaust after-treatment requirements compress margins without proportional efficiency gains. Independent towboat operators on the Mississippi exhibit highest price sensitivity, while integrated logistics firms securing multi-year automotive contracts demonstrate lowest sensitivity due to carbon intensity clause pass-through mechanisms.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities anchor supplier relationships, with Korean and Chinese battery cell manufacturers offering 180-day structures to European shipyards integrating lithium-ion systems. Hull fabrication concentrates in the Netherlands, Germany, and Poland, while propulsion system assembly draws from South Korean and Japanese component suppliers. Raw material dependencies include marine-grade steel plate, copper busbar for electrical distribution, and nickel-manganese-cobalt cathode materials. Single-source vulnerability characterizes high-voltage inverter supply, where German and Austrian specialists control niche power electronics. Distribution runs through integrated logistics operators managing fleet deployment across Rhine-Danube and Mississippi-Illinois corridor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across propulsion technology standards and regional regulatory clusters creates niche entry points for specialized players. Demand-side procurement shifts toward carbon-intensity-based contracting reward operators capable of certifying lower-emission voyage profiles.
For Market Incumbents: Entrench corridor control through captive shore-charging infrastructure deployment along Belgian and German terminals, countering independent operators' access to electrified routes. Deepen backward integration into battery system refurbishment capabilities, addressing marine electrical technician scarcity that threatens fleet uptime. Prioritize methanol-ready newbuild licensing to Dutch and German yards, securing first-mover positioning as e-methanol supply chains mature. For New Entrants and Emerging Players: Asian river cruise expansion on Yangtze and Mekong basins represents the most penetrable entry point, with hotel-grade vessel demand outpacing European yard capacity. Small-vessel last-mile logistics in French and Belgian secondary canals offers secondary white-space, where agricultural product collection lacks rail siding competition. Pursue partnership-based go-to-market structures with established European tour operators seeking local construction partnerships to bypass import tariff exposure. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors modular platform specialists with hybrid-electric commissioning experience over legacy diesel-mechanically focused operators. Long-term viability over a five-to-ten-year window hinges on securing corridor-specific charging infrastructure concessions and methanol bunkering agreements. Acquisition targets should demonstrate integrated logistics control across multi-modal nodes. Monitor EU F-Gas Regulation enforcement timing as inflection indicator, with retrofit incentive activation likely to accelerate refrigerated barge fleet consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Platform Standardization | Damen Shipyards leverages modular architecture to compress commissioning timelines for Rhine corridor operators. |
| Corridor Charging Infrastructure Partnership | Belgian and Dutch terminal operators coordinate shore-power standards to fragment route planning barriers. |
| Methanol-Ready Newbuild Licensing | Netherlands and Germany shipyards design dual-fuel hulls to capture future e-methanol supply chains. |
| Refrigerated Cargo Retrofit Consolidation | German cold-chain logistics providers accelerate ammonia and CO2 cooling adoption ahead of F-Gas deadlines. |
| Digital Twin Performance Virtualization | Rhine operators deploy simulation platforms to optimize hull hydrodynamics without physical prototype requirements. |
Methodological Framework
The analysis maps barge, towboat, push boat, and ferry sub-sectors, each validated through fleet operations directors, shipyard procurement managers, port authority infrastructure planners, and logistics integrators responsible for modal shift implementation. Primary interviews with marine electrical technicians and battery system engineers cross-reference against secondary validation from EU Green Deal implementation reports, US EPA Tier 4 compliance filings, customs trade data on hull steel imports, and SEC disclosures from listed fleet operators. Bottom-up vessel count and capacity data triangulate against top-down freight volume estimates from inland waterway administration statistics.
Analytical frameworks hold regulatory enforcement timelines and commodity price baselines fixed while varying modal shift adoption rates and battery cost decline curves across the projection horizon. Segmentation dimensions modeled include vessel type, application category, end-user procurement authority, and capacity tier alongside corridor-specific infrastructure constraint profiles. CAGRs derive from fitted growth curves calibrated to historical fleet renewal patterns and announced newbuild orderbooks. Industry-specific forecast inputs incorporate lock dimension expansion schedules and shore-charging infrastructure deployment pipelines.
Macroeconomic conditions sit as an overlay; deviation in steel plate pricing, marine battery cell availability, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology cost reduction continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Seats Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Airboats Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Yacht Market
Marine Vehicles
LNG Marine Engine Market