
 Global Luxury Boat Market | 2026-2036
Global Luxury Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Luxury Boat Market Outlook
Modular yacht configuration is expanding buyer choice across the Global Luxury Boat Market. Ferretti Group leverages its integrated design-to-delivery pipeline to control specification timelines. Sunseeker International anchors its competitiveness through deep specialization in performance motor yacht hull architecture. Azimut Benetti Group sustains Mediterranean production dominance with vertically controlled shipyard capacity.
A luxury boat denotes a privately operated vessel exceeding 24 meters in length, typically constructed from advanced composites or aluminum alloys with bespoke interior fit-out, designed for leisure cruising, entertaining, or long-range expedition use. Yachts occupy the dominant revenue position within product type segmentation, while catamarans represent the fastest-expanding configuration due to stability preferences among charter operators. Hybrid systems within technology segmentation concentrate margin pools as regulatory pressure intensifies on conventional diesel propulsion across European and Middle Eastern cruising grounds.
The EU Green Deal and IMO decarbonization frameworks are tightening emissions standards for vessels operating in European waters, directly shaping new-build specification requirements. The US Coast Guard and EPA jointly govern safety and environmental compliance for imported luxury vessels, influencing market access conditions for European and Asian builders. Stakeholders must monitor regulatory divergence between Mediterranean emissions zones and Gulf state sustainability mandates to align product development and charter fleet investment cycles.
Market Dynamics
Hybrid-electric propulsion architectures are compressing specification cycles across new-build programs as IMO decarbonization mandates and EU Green Deal emissions zones force fleet operators to reconfigure charter assets ahead of compliance deadlines.
Growth Catalysts
- EU Green Deal maritime extensions:Emissions Control Areas in Mediterranean cruising corridors are compelling charter fleet operators to accelerate hybrid retrofit schedules and new-build orders.
- Ultra-high-net-worth leisure demand:Private owners in the Persian Gulf marina network are expanding multi-vessel fleets with expedition-configured yachts for extended Red Sea and Indian Ocean itineraries.
- Advanced composite hull fabrication:Carbon fiber infusion techniques are reducing displacement-to-length ratios, enabling larger interior volumes without draft penalties for shallow-water Caribbean and Southeast Asian anchorages.
Market Restraints
- Marine-grade aluminum sheet volatility:Aerospace and defense procurement competition is constraining supply availability for superyacht superstructure fabrication, extending delivery timelines.
- Italian and Turkish shipyard concentration:Over half of Mediterranean new-build capacity sits within two coastal clusters, creating bottleneck risk during peak specification seasons.
- Lithium-ion marine battery certification gaps:Flag-state approval timelines for high-capacity energy storage systems lag propulsion integration schedules, freezing some hybrid configurations.
Strategic Opportunities
- Saudi Arabia's Red Sea Project:Giga-project marina infrastructure investment is creating virgin charter demand for expedition vessels with shallow-draft capabilities.
- IMO 2025 carbon intensity indicators:Compliance-driven fleet renewal cycles are opening specification windows for integrated sail-assist hybrid systems on motor yacht platforms.
- Digital twin sea-trial protocols:Convergence of computational fluid dynamics and virtual reality commissioning is compressing owner acceptance timelines and reducing warranty exposure.
Industry Challenges
- Naval architecture talent scarcity:Specialized hydrodynamicists with composite structural expertise command premium compensation, constraining design house expansion.
- Classification society harmonization delays:Divergent Lloyd's Register, RINA, and ABS rule sets for hybrid-electric installations complicate multi-flag fleet standardization.
- Subcontractor quality variance:Interior fit-out specialists in emerging build locations require extended supervision cycles to meet bespoke craftsmanship standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Luxury Boat Market |
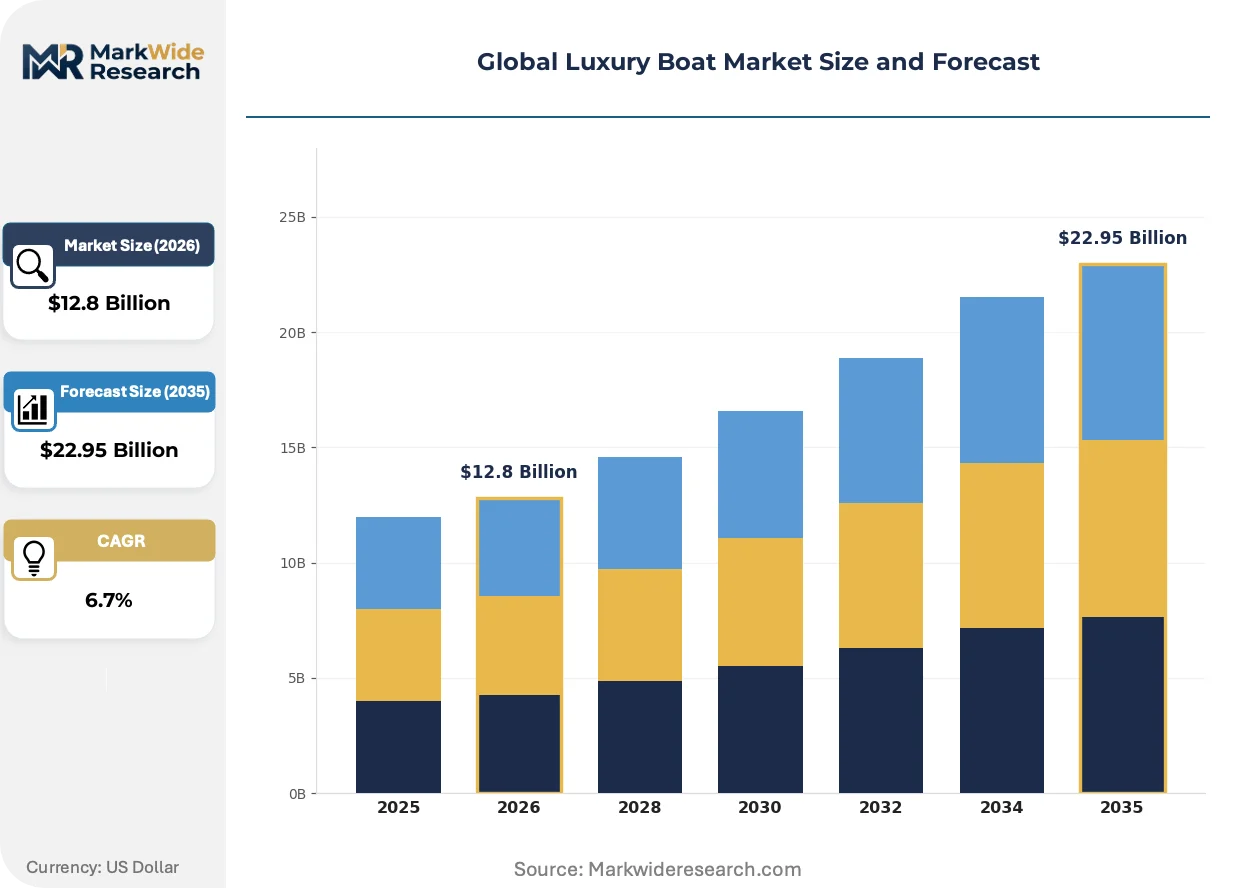
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yachts, Catamarans, Sailboats, Motorboats End User: Private Owners, Charter Companies, Resorts, Corporations Technology: Hybrid Systems, Autonomous Navigation, Eco-friendly Materials, High-performance Engines Application: Leisure, Racing, Tourism, Research |
| Companies Covered | Ferretti Group, Feadship, Fincantieri, Azimut Benetti Group, Sanlorenzo, Lürssen, Princess Yachts, Sunseeker International, Groupe Beneteau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Luxury Boat Market Strategic Shifts
Propulsion electrification and digital design workflows are compressing development cycles while fragmenting specification authority between owners, brokers, and build captains.
Integrated battery-diesel-electric architectures are consolidating powertrain decision-making around energy management software rather than mechanical engineering dominance. Charter operators with multi-vessel fleets are adopting these systems fastest, prioritizing operational flexibility over maximum range. The technology is consolidating vendor relationships around integrated system suppliers capable of unified warranty coverage across mechanical and electrical subsystems.
EU Green Deal maritime extensions and IMO carbon intensity frameworks are tightening emissions verification protocols for vessels over 400 gross tons. Shipyards now embed emissions monitoring hardware during hull construction rather than retrofitting post-delivery. Mediterranean-flagged charter fleets face the steepest compliance ramps, with Italian and French registry vessels accelerating hybrid adoption to maintain zone access.
Build-captain procurement models are displacing traditional broker-mediated specification processes for vessels exceeding 40 meters. Experienced technical managers now contract directly with naval architects and equipment suppliers, unbundling yard-provided design services. This pattern concentrates most visibly in Northern European owner segments, where technical literacy supports direct vendor negotiation and compressed decision chains.
Global Luxury Boat Market Segmentation
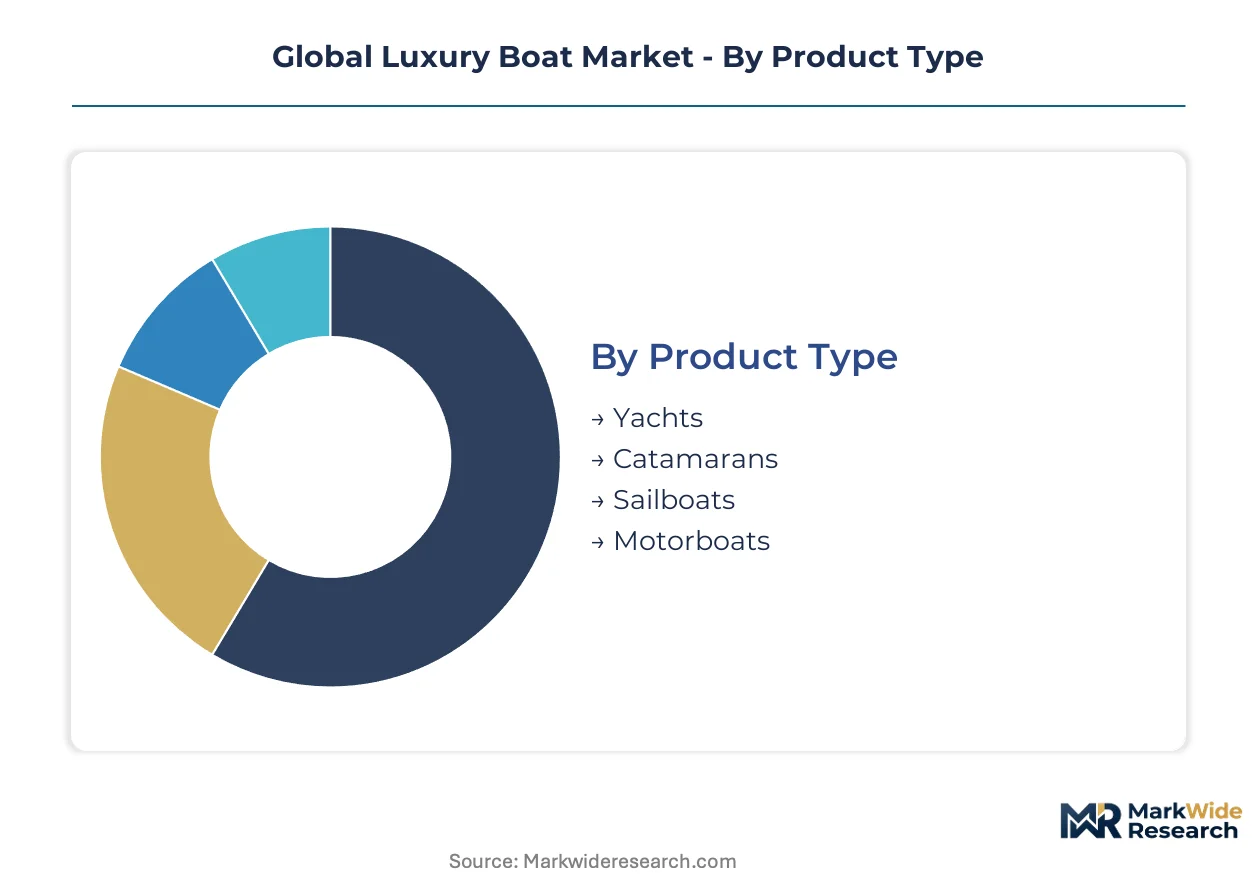
Segmentation in the Global Luxury Boat Market reveals how capital deployment, regulatory exposure, and operational intensity vary across vessel configurations and ownership models. Buyers face fundamentally different specification cycles, crewing requirements, and compliance burdens depending on which segment they target.
Product Type:
Capital intensity varies sharply across hull configurations, with displacement tonnage and composite engineering complexity driving upfront investment tiers.
- Yachts:Monohull vessels exceeding 24 meters dominate new-build order books through bespoke interior fit-out and extended range architectures. Persian Gulf private owners and Mediterranean charter fleets concentrate demand here, though EU Green Deal emissions zones now force hybrid powertrain premiums on conventional diesel specifications.
- Catamarans:Twin-hull stability profiles attract shallow-draft expedition requirements and high-density charter operations. Red Sea Project marina infrastructure and Caribbean anchorages drive fastest-expanding configuration demand as operators prioritize guest capacity per meter of berth length.
- Sailboats:Wind-assisted propulsion retains niche positioning among racing circuits and environmentally positioned private owners.
- Motorboats:Day-cruiser and weekender formats serve entry-luxury transitions with lower crewing thresholds.
Yachts absorb the bulk of installed capacity; catamarans are expanding most quickly.
End User:
Procurement authority and specification complexity diverge based on whether vessels serve personal use or commercial return-on-asset models.
- Private Owners:Individual buyers with direct naval architect relationships specify expedition-configured hulls for extended Indian Ocean and Southeast Asian itineraries. Build-captain procurement models now displace traditional broker mediation for vessels above 40 meters, compressing decision chains but intensifying technical literacy requirements.
- Charter Companies:Fleet operators with multi-vessel programs prioritize operational flexibility and emissions compliance ahead of maximum range. Mediterranean-flagged fleets face steepest EU Green Deal compliance ramps, accelerating hybrid adoption to maintain zone access.
- Resorts:Integrated hospitality operators acquire shallow-draft day vessels for guest experience programming.
- Corporations:Executive entertainment and client hospitality functions drive specification for stabilized platforms with minimal crew visibility.
Private owners command the highest per-vessel specification values; charter companies are gaining share fastest through fleet standardization.
Technology:
Regulatory pressure is fragmenting specification authority between mechanical engineering traditions and energy management software vendors.
- Hybrid Systems:Battery-diesel-electric architectures consolidate vendor relationships around integrated suppliers capable of unified warranty coverage. IMO carbon intensity frameworks and EU Green Deal maritime extensions embed emissions monitoring hardware during hull construction rather than post-delivery retrofit.
- Autonomous Navigation:Sensor fusion and collision-avoidance algorithms reduce crewing requirements for long-range passages.
- Eco-friendly Materials:Recycled composite feedstocks and bio-based resins respond to owner sustainability positioning.
- High-performance Engines:Conventional diesel propulsion retains dominance in non-European registry fleets with less stringent emissions timelines.
Hybrid systems capture the deepest margin pools; autonomous navigation is climbing the fastest as classification societies harmonize approval protocols.
Application:
Operational tempo and utilization patterns determine amortization schedules and resale value trajectories.
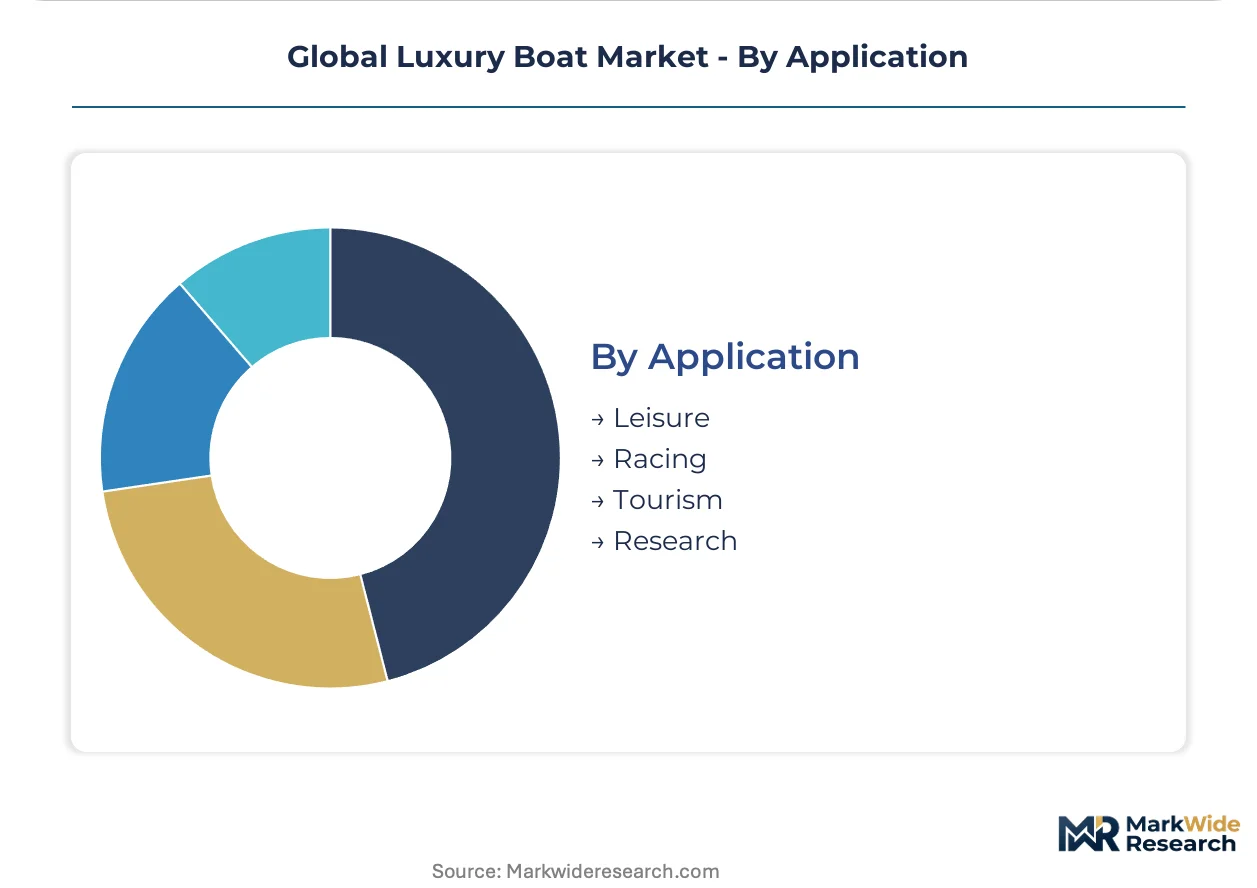
- Leisure:Private cruising and entertaining functions dominate volume through Mediterranean and Persian Gulf marina networks. Expedition-configured specifications with extended range and shallow-draft capabilities command premium positioning for Red Sea and Indian Ocean itineraries.
- Racing:Performance-optimized hulls with minimal interior volume serve competitive circuits with intense seasonal utilization.
- Tourism:High-frequency day-trip operations in Caribbean and Southeast Asian anchorages prioritize passenger capacity and boarding efficiency.
- Research:Scientific expedition platforms with laboratory fit-out and submersible deployment capabilities serve institutional and philanthropic owners.
Leisure absorbs the bulk of installed capacity; research vessels are expanding most quickly through philanthropic and institutional capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's yacht manufacturing tax incentives under the 2020 Growth Decree concentrate production capacity around Viareggio and Ancona. This fiscal architecture anchors European supply while Persian Gulf sovereign wealth deploys parallel marina infrastructure.
Italy
Viareggio and Ancona clusters host vertically integrated shipyards serving Mediterranean charter demand. EU Green Deal maritime extensions force hybrid powertrain adoption for Italian-flagged fleets. The Ligurian coast concentrates superyacht finishing operations where Ferretti Group and Azimut Benetti Group maintain captive production capacity.
United States
Florida's yacht brokerage corridor and Pacific Northwest custom builders serve domestic ultra-high-net-worth demand. US Coast Guard and EPA joint regulations govern safety and environmental compliance for imported vessels. Fort Lauderdale anchors the Americas' largest marina network with concentrated refit and specification services.
United Arab Emirates
Dubai Maritime City Authority incentives attract European yard satellite operations for Gulf-based owners. MOHAP and federal maritime regulators coordinate safety standards with EU Green Deal alignment pressures. Jumeirah and Dubai Harbour marinas concentrate multi-vessel private fleets for Red Sea and Indian Ocean expedition cruising.
Germany
Northern European owners drive build-captain procurement models for vessels exceeding 40 meters. KBA and Lloyd's Register classification protocols influence hybrid-electric certification timelines. Hamburg and Bremen clusters concentrate naval architecture talent and specialized equipment suppliers serving Baltic and North Sea cruising requirements.
Turkey
Antalya and Istanbul shipyards capture mid-size yacht construction with competitive labor arbitrage against Italian benchmarks. Turkish flag-state regulators harmonize with EU Green Deal emissions zones for Mediterranean market access. The Aegean coast concentrates aluminum superstructure fabrication serving European builder subcontract demand.
Global Luxury Boat Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across specification tiers. Italian and Northern European yards anchor premium new-build capacity while Turkish and Asian fabricators capture mid-market volume. Three archetypes dominate: vertically integrated design-to-delivery houses, naval-architecture-led custom builders, and fleet-standardization specialists serving charter operators. Competitive moves concentrate on hybrid propulsion integration partnerships and direct-to-owner procurement channel development.
Within the vertically integrated tier, Ferretti Group and Azimut Benetti Group exemplify design-to-delivery control over specification timelines. Sunseeker International occupies a position emphasizing performance motor yacht hull architecture. These entities represent contrasting approaches to Mediterranean production concentration and owner-direct relationship models.
| Leading Market Players |
|---|
| Ferretti Group |
| Feadship |
| Fincantieri |
| Azimut Benetti Group |
| Sanlorenzo |
| Lürssen |
| Princess Yachts |
| Sunseeker International |
| Groupe Beneteau |
| Others |
Value Chain & Pricing Dynamics
Mediterranean charter fleet operators concentrate procurement authority and compress decision cycles around hybrid powertrain specifications. Their aggregate demand patterns anchor a contract-based long-term offtake model where yard slot scarcity translates directly into specification premiums and extended deposit structures.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers with expedition-configured hulls commanding premiums for sub-24-month delivery slots. Price differentiation hinges on EU Green Deal compliance certification level and carbon fiber composite grade, with Italian-registry vessels facing steepest cost compression due to emissions hardware mandates. Margins are tightening in mid-size aluminum superstructure segments as aerospace procurement competition constrains marine-grade sheet availability. Charter companies exhibit highest price sensitivity through fleet standardization programs, while Persian Gulf private owners demonstrate lowest sensitivity through build-captain direct negotiation models.
Supply Chain Analysis
Heavy-lift yacht transport from Italian and Turkish production clusters to Persian Gulf and Caribbean delivery points absorbs disproportionate freight cost share in landed vessel economics. Geographic supply concentration centers on Italy, Turkey, and Germany for hull fabrication, with Northern European equipment suppliers providing hybrid-electric powertrain components. Raw material dependencies draw from carbon fiber prepregs, marine-grade aluminum alloys, and high-capacity lithium-ion energy storage systems. Single-source vulnerability runs through Italian and Turkish coastal shipyard clusters where over half of Mediterranean new-build capacity faces bottleneck risk during peak specification seasons. Distribution runs through direct owner-yard contracts above 40 meters and broker-mediated channels below that threshold.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Luxury Boat Market sits in a propulsion technology transition where battery-diesel-electric architectures displace conventional mechanical engineering dominance. Hybrid system integration capability now separates viable competitors from legacy-dependent yards facing compliance-driven obsolescence.
For Market Incumbents: Cement hybrid powertrain partnerships with integrated system suppliers capable of unified warranty coverage across mechanical and electrical subsystems. Capture in-house production of carbon fiber hull components to defend margin position against aerospace material competition. Prioritize build-captain relationship development in Northern European owner segments where technical literacy supports direct vendor negotiation and compressed specification cycles. For New Entrants and Emerging Players: Build-captain technical managers represent the most accessible channel partner type for unbundling yard-provided design services and inserting direct equipment supply relationships. Target shallow-draft catamaran configurations for Saudi Arabia's Red Sea Project marina infrastructure where virgin charter demand lacks established supplier relationships. Pursue digital twin sea-trial protocols as a service-based entry angle that compresses owner acceptance timelines without captive shipyard investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor naval-architecture-led custom builders in Germany and Northern Europe where specialized hydrodynamicist talent scarcity constrains design house expansion. Long-term viability over the next decade rests on hybrid-electric certification capabilities and direct-to-owner procurement channel control. Monitor classification society harmonization progress between Lloyd's Register, RINA, and ABS rule sets as the critical inflection signal for multi-flag fleet standardization investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Integration Partnership | Consolidates vendor relationships around unified warranty coverage for EU Green Deal compliance. |
| Carbon Fiber Hull Production Expansion | Reduces displacement-to-length ratios for shallow-water Red Sea and Caribbean anchorages. |
| Build-Captain Direct Channel Development | Bypasses traditional broker mediation in Northern European technical-literate owner segments. |
| Digital Twin Sea-Trial Protocol Deployment | Compresses owner acceptance timelines through CFD and virtual reality commissioning convergence. |
| Red Sea Project Marina Infrastructure Alignment | Positions expedition-configured shallow-draft vessels for Saudi sovereign wealth giga-project demand. |
Study Parameters
Document review covered IMO regulatory filings, EU Green Deal maritime extension protocols, shipyard production disclosures, and customs trade data, complemented by interviews with naval architects, charter fleet operators, build-captain technical managers, and marine equipment procurement leads. Secondary validation drew from Lloyd's Register classification records, RINA certification databases, and Mediterranean marina berth utilization statistics. Bottom-up vessel specification tracking and top-down fleet investment flow analysis provided triangulation across data sources.
Cross-referencing historical order book patterns against expert panel input on hybrid adoption timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include hull configuration, ownership model, propulsion technology tier, and regional regulatory cluster. CAGRs were derived from weighted scenario outputs incorporating EU Green Deal compliance ramp schedules and Persian Gulf sovereign wealth infrastructure deployment pacing. Forecast inputs integrated aluminum sheet supply constraints and lithium-ion marine battery certification timeline variability.
Caveats apply where classification society rule harmonization delays or lithium-ion energy storage flag-state approval gaps could materially shift the outlook for hybrid configuration availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Marine Reciprocating Engine Market
Marine Vehicles
Sea-Based Vehicle Carrier Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Marine Propulsion Systems Market