
 Construction Waste Market | 2026-2036
Construction Waste Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Waste Market Analysis
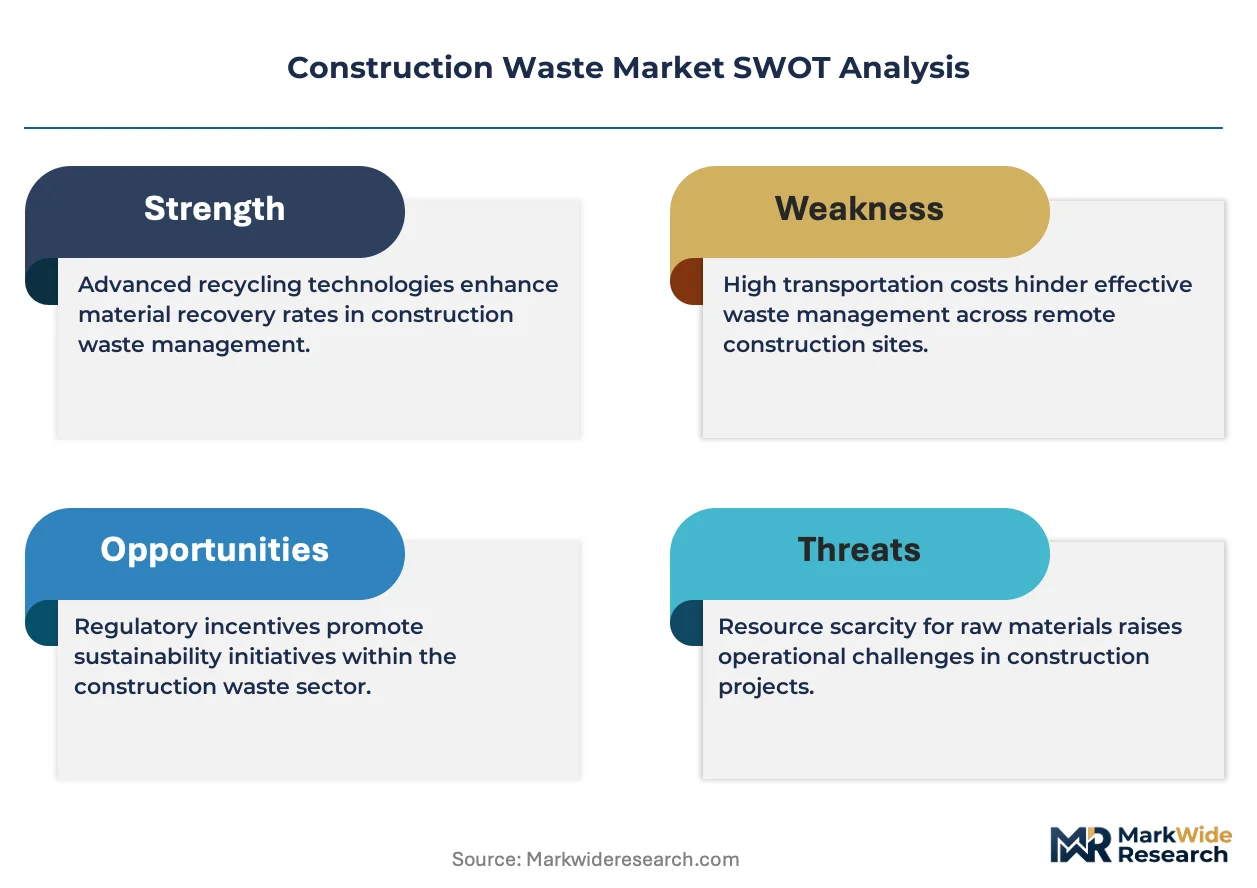
High-grade recycled aggregate specification is rotating toward the center of procurement decisions across European infrastructure programs. Waste Management leverages its North American landfill network to anchor tipping fee revenue while expanding sorting infrastructure. Veolia Environment S.A. competes through integrated collection-to-recycling contracts with municipal authorities. Republic Services differentiates via automated materials recovery facilities that reduce contamination rates in processed concrete streams.
Construction waste comprises debris generated during building, renovation, and demolition activities, including concrete fragments, timber offcuts, ferrous and non-ferrous metals, and asphalt shingles with particle sizes ranging from fine dust to monolithic structural elements. Its primary industrial purpose is to serve as feedstock for recycled aggregates, biomass fuel, or recovered metal ingots that displace virgin extraction. Concrete recycling dominates volume flows across the waste type dimension, while thermal processing of wood waste captures the fastest expansion in energy recovery applications. Collection services retain the largest revenue pool in service type, though recycling margins are compressing landfill-dependent disposal operators.
The EU Green Deal and national transpositions through France's AGEC law and Germany's KrWG impose mandatory separation and recycling quotas on demolition contractors. EPA Subtitle D regulations in the United States govern municipal solid waste landfill design and leachate controls that shape disposal economics. Stakeholders must monitor tightening contamination thresholds for processed aggregate certification, as these standards will determine which sorting technologies justify capital deployment.
Market Dynamics
The EU Green Deal's circular economy mandates are compelling demolition contractors to divert concrete and masonry waste from landfill toward certified recycling streams, fundamentally restructuring material flows across European construction value chains.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and national transpositions through France's AGEC law impose mandatory separation and recycling quotas on demolition contractors, creating enforceable demand for processed aggregate.
- Urban redevelopment intensity:Redevelopment projects across Germany, France, and the United Kingdom are accelerating demand for processed recycled aggregates in road base and structural fill applications.
- Thermal processing expansion:Thermal processing of wood waste captures the fastest expansion in energy recovery applications, diversifying revenue streams beyond aggregate sales.
Market Restraints
- Contamination threshold tightening:Processed aggregate certification standards impose rising purity requirements that render legacy sorting infrastructure economically obsolete.
- Landfill tipping fee dependency:Waste Management's North American landfill network anchors revenue on disposal fees, creating stranded asset risk as diversion mandates tighten.
- Input quality volatility:Demolition debris composition varies by building vintage and construction method, complicating consistent output specification for high-grade recycled concrete.
Strategic Opportunities
- Automated sorting penetration:Republic Services' automated materials recovery facilities reduce contamination rates in processed concrete streams, opening premium specification markets previously closed to recycled feedstock.
- Integrated municipal contracts:Veolia Environment S.A. competes through collection-to-recycling contracts with municipal authorities, locking in long-term feedstock security.
- Biomass fuel pathway expansion:Timber offcuts and wood waste diversion toward biomass fuel displaces virgin extraction in energy applications, capturing carbon credit value.
Industry Challenges
- Certification timeline compression:EPA Subtitle D regulations and EU aggregate certification protocols demand simultaneous compliance across multiple jurisdictions, stretching technical documentation capacity.
- Sorting technology capex intensity:Near-infrared and X-ray fluorescence sorting systems require capital deployment that squeezes margins for mid-scale operators without landfill revenue buffers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Waste Market |
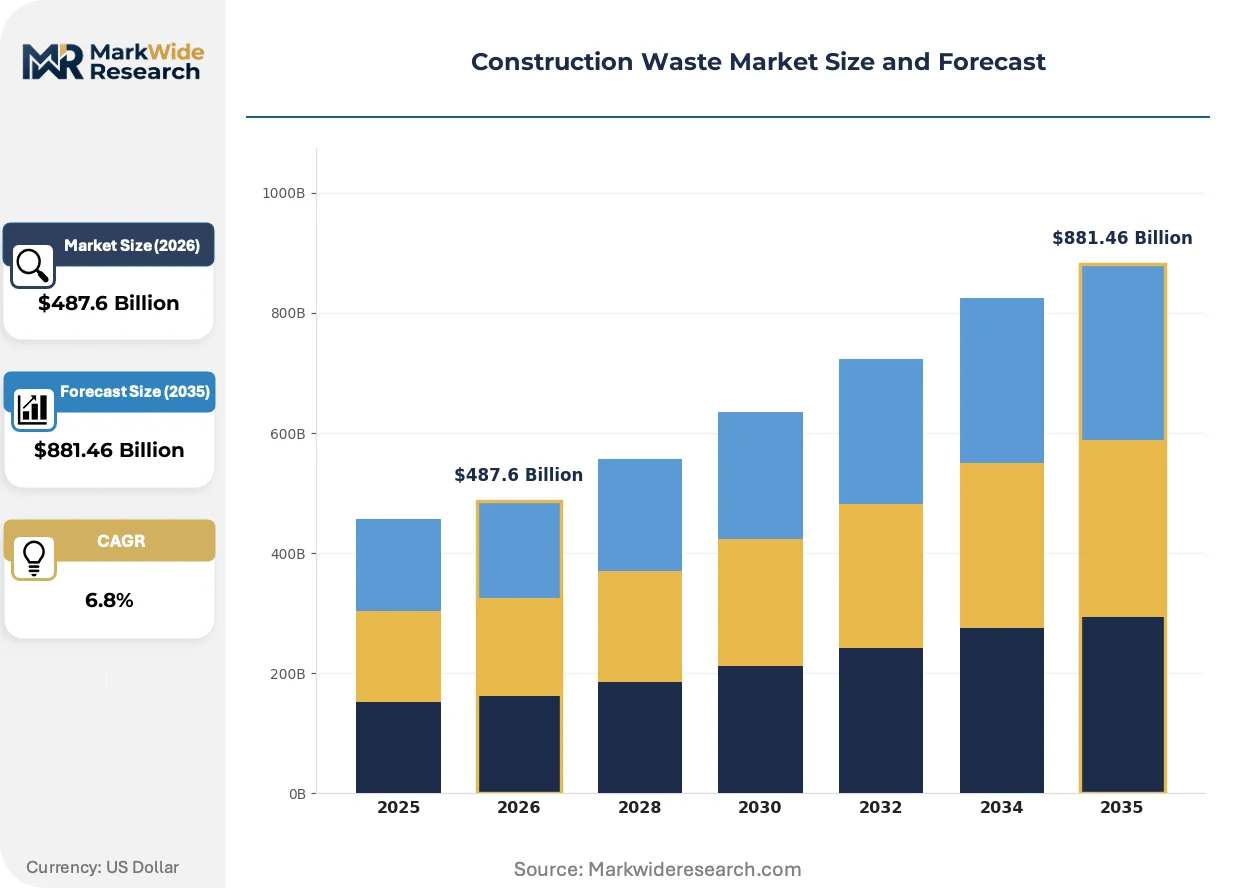
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Concrete, Wood, Metals, Roofing Service Type: Collection, Recycling, Disposal, Treatment End User: Contractors, Subcontractors, Demolition Companies, Developers Processing Technology: Mechanical, Thermal, Biological, Chemical |
| Companies Covered | Veolia Environment S.A., Republic Services, Waste Management, Casella Waste Systems, Inc., Clean Harbors, Inc., Remondis, Waste Connections, GFL Environmental Inc., Cleanaway Waste Management Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Waste Market Emerging Trajectories
Digital traceability systems and advanced sorting technologies are converging to transform waste from a cost center into a specification-grade feedstock, compressing the gap between virgin and recycled material performance claims.
Near-infrared spectroscopy combined with robotic pickers is decomposing traditional manual sorting bottlenecks in concrete recycling facilities. Major infrastructure contractors in Germany and the Netherlands are specifying NIR-sorted aggregate for structural applications. This technology is decomposing the historical price premium commanded by virgin quarried stone in road base markets.
France's AGEC law and Germany's KrWG impose mandatory pre-demolition audits that inventory recoverable materials before wrecking permits issue. Contractors must now separate concrete, metals, and timber on-site rather than commingling for landfill. Demolition specialists in Paris and Berlin are restructuring crews around material recovery logistics rather than disposal efficiency.
Public procurement guidelines in the United Kingdom now award contract points for recycled content verification through digital chain-of-custody platforms. Tier-one contractors are unbundling aggregate supply contracts to favor certified recyclers over traditional quarries. This preference rotation is most visible in Transport for England road maintenance frameworks and Greater London Authority commercial development mandates.
Construction Waste Market Segmentation
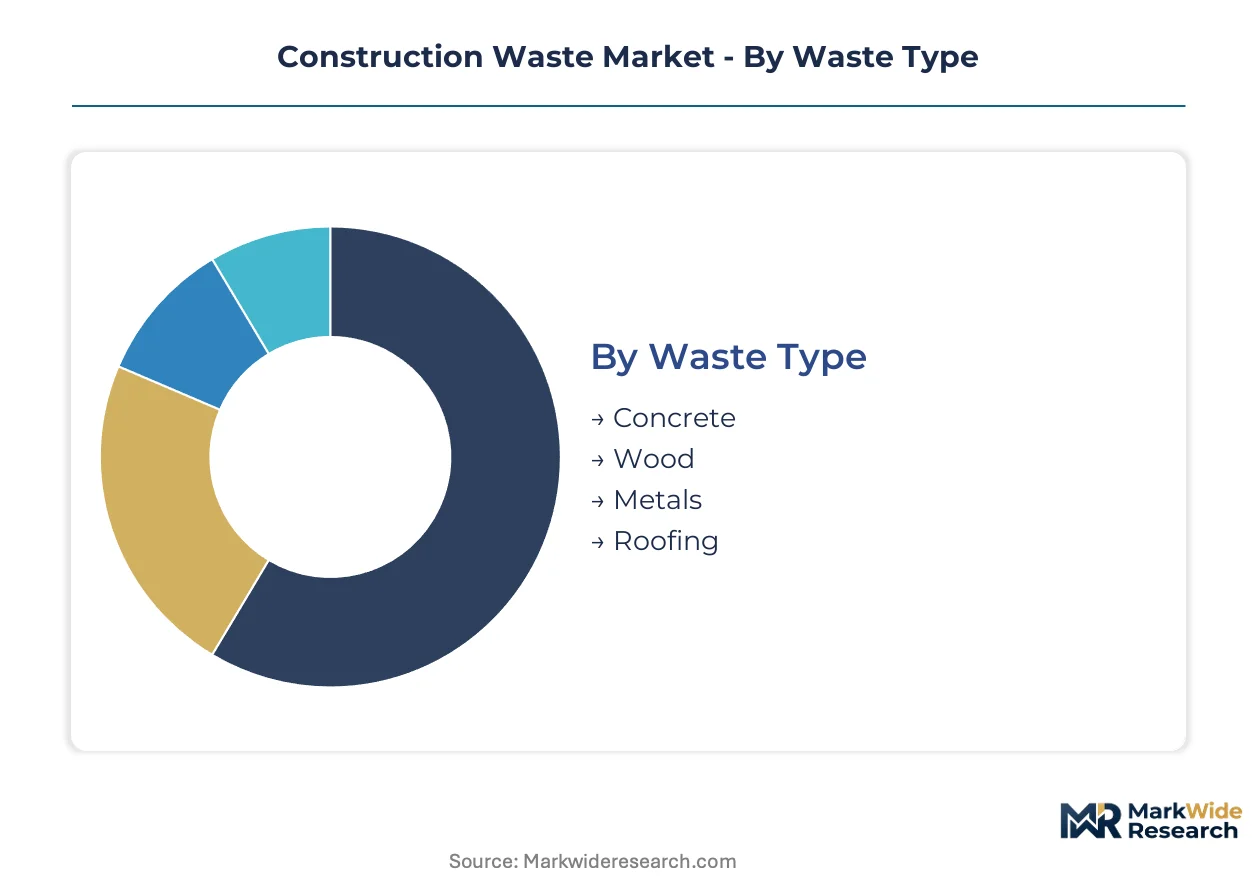
Construction waste segmentation reveals distinct margin profiles and capital intensity requirements across material streams and service layers. Waste type and processing technology dimensions command the steepest technology differentiation premiums, while service type and end user categories determine contract duration and feedstock security.
Waste Type:
Concrete and wood segments dominate domestic volume flows across European and North American markets, while metal recovery maintains stronger export linkages to Asian smelting capacity.
- Concrete:Comprising reinforced fragments, precast elements, and masonry debris with particle sizes from fines to monolithic structural units. Demand concentrates in German and British road base specifications where EU Green Deal mandates displace virgin aggregate; contamination thresholds from ECHA REACH protocols constrain legacy processing infrastructure.
- Wood:Encompassing timber offcuts, dimensional lumber scraps, and engineered wood products with variable moisture and treatment chemical loads. Energy recovery applications in French and German biomass facilities are expanding most quickly as AGEC and KrWG laws divert material from landfill; carbon credit monetization improves project economics.
- Metals:Ferrous rebar, structural steel, and non-ferrous copper, aluminum, and zinc fractions with high salvage value density.
- Roofing:Asphalt shingles, clay tiles, and synthetic membrane debris with complex polymer-bitumen separation requirements.
Concrete holds the largest share; momentum sits with wood as thermal processing capacity scales.
Service Type:
Collection services anchor revenue stability through long-term municipal contracts, while recycling and treatment layers concentrate margin expansion opportunity.
- Collection:Roll-off container logistics, site hauling, and transfer station aggregation with high asset utilization dependency. Contractors in United Kingdom urban redevelopment zones are consolidating haulage contracts to secure feedstock pipelines for integrated recycling investments; Transport for England frameworks favor bundled service providers.
- Recycling:Aggregate crushing, metal recovery, and wood chip processing with specification-grade output certification. Near-infrared sorting deployment in Dutch and Belgian facilities is reducing contamination rates below 2% for structural concrete applications; automated materials recovery justifies capital deployment previously uneconomic at mid-scale.
- Disposal:Landfill tipping and engineered cell placement with leachate management under EPA Subtitle D or EU Waste Framework Directive compliance.
- Treatment:Hazardous material stabilization, asbestos encapsulation, and contaminated soil remediation with specialized permitting requirements.
Collection commands the deepest revenue pool; recycling delivers the steepest margin expansion trajectory.
End User:
Demolition companies and tier-one contractors drive specification-grade aggregate demand, while subcontractors and developers concentrate procurement of commoditized disposal services.
- Contractors:General construction firms managing new build and renovation waste with fragmented procurement authority across project sites.
- Subcontractors:Specialized trades generating discrete waste streams with limited on-site sorting infrastructure.
- Demolition Companies:Controlled demolition specialists with pre-wrecking audit obligations under France's AGEC law and Germany's KrWG. Paris and Berlin operators are restructuring crews around material recovery logistics; mandatory separation quotas create enforceable demand for certified recycling capacity.
- Developers:Real estate owners and project sponsors with sustainability reporting obligations under EU CSRD and Greater London Authority mandates.
Demolition companies concentrate the fastest-growing procurement volume; developers are gaining contractual influence through green building certification requirements.
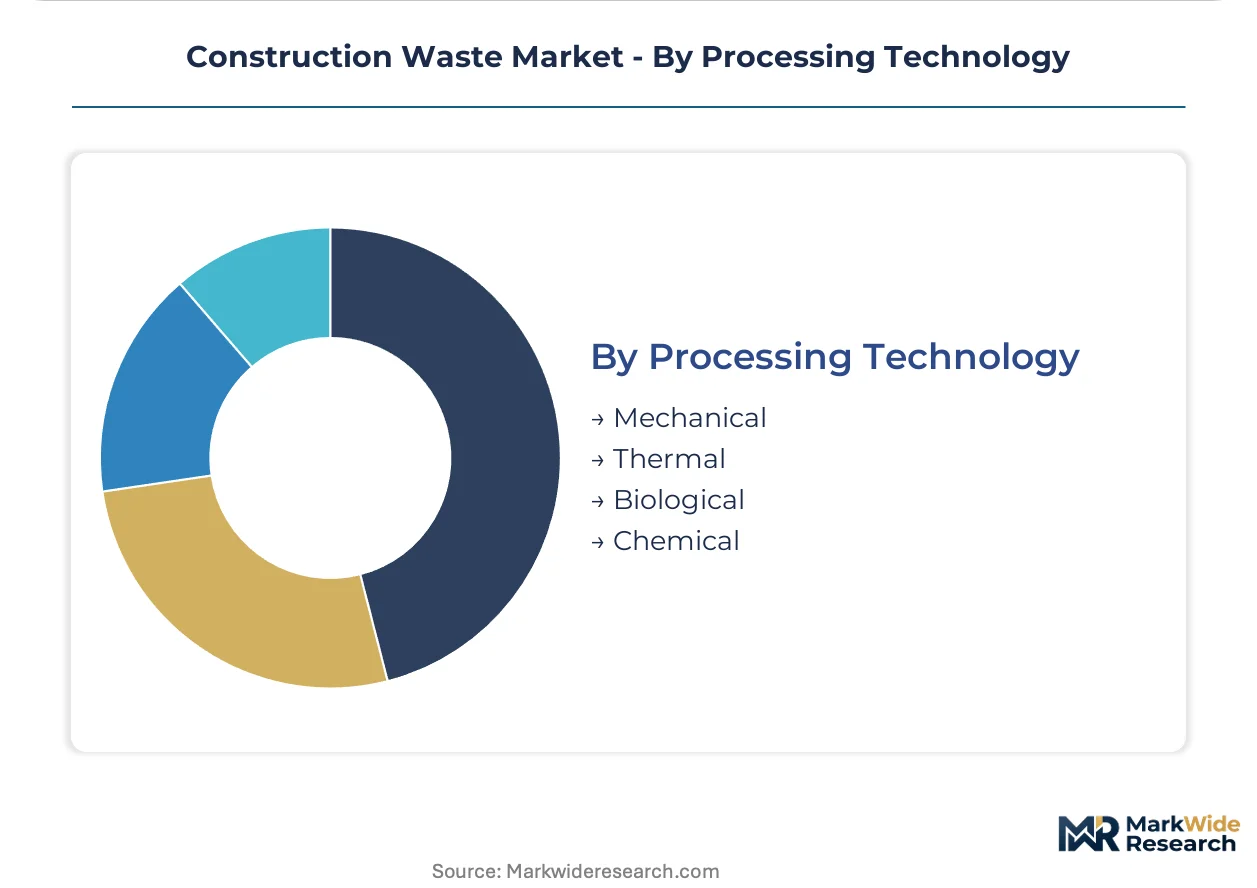
Processing Technology:
Mechanical processing dominates installed capacity with lowest unit economics, while thermal and biological pathways capture technology premium pricing.
- Mechanical:Crushing, screening, magnetic separation, and air classification with mature equipment supply chains. German aggregate processors are deploying X-ray fluorescence sorting to meet rising purity thresholds for structural concrete certification; legacy jaw crusher configurations face economic obsolescence.
- Thermal:Pyrolysis, gasification, and combustion systems for wood waste and contaminated soil with energy recovery integration. Dutch biomass facilities are accepting construction timber at premium gate fees; carbon accounting under EU ETS improves project returns.
- Biological:Composting and anaerobic digestion for organic fractions with limited construction waste applicability.
- Chemical:Solvent extraction, leaching, and precipitation for metal recovery and hazardous treatment with highest regulatory compliance burden.
Mechanical retains the largest installed base; thermal processing climbs the fastest as energy recovery economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sorting infrastructure concentrates in jurisdictions with enforceable diversion mandates. Germany, France, the United Kingdom, the United States, and China anchor processing capacity through distinct regulatory mechanisms and urban redevelopment intensity.
Germany
Urban densification in Berlin and Hamburg drives demolition volume for recycled aggregate feedstock. The Kreislaufwirtschaftsgesetz (KrWG) mandates pre-demolition audits and 70% recycling quotas for construction debris. Bavarian processors near Munich deploy X-ray fluorescence sorting to meet rising purity thresholds for structural concrete certification.
France
Greater Paris Authority commercial mandates and Transport for England-style frameworks in Lyon accelerate specification-grade procurement. The AGEC law imposes mandatory on-site separation of concrete, metals, and timber before wrecking permits issue. Demolition contractors in Paris are restructuring crews around material recovery logistics rather than disposal efficiency.
United Kingdom
Transport for England road maintenance frameworks and Greater London Authority development mandates award contract points for recycled content verification. Public procurement guidelines favor certified recyclers over traditional quarries through digital chain-of-custody platforms. Midlands-based processors supply road base specifications for national highway renewal programs.
United States
EPA Subtitle D regulations govern landfill design and leachate controls that shape disposal economics across state jurisdictions. Waste Management leverages its North American landfill network to anchor tipping fee revenue while expanding automated sorting infrastructure. Republic Services differentiates through materials recovery facilities that reduce contamination rates in processed concrete streams.
China
Dual carbon goals and urban renewal campaigns in Shanghai and Shenzhen accelerate demand for processed recycled aggregates. The Ministry of Ecology and Environment (MEE) tightening standards on construction waste landfill disposal push contractors toward certified recycling streams. Yangtze River Delta processors scale mechanical crushing capacity for road base applications.
Construction Waste Market Vendor Landscape
Concentration sits with integrated environmental services conglomerates possessing landfill network buffers and municipal contract portfolios. Mid-scale operators face margin compression from rising sorting technology capital intensity without disposal revenue anchors. Two strategic archetypes dominate: vertically integrated waste-to-resource platforms and automated materials recovery specialists. Competitive moves center on municipal contract bundling and near-infrared sorting deployment for premium aggregate certification.
Within the integrated services tier, Veolia Environment S.A. and Waste Management occupy positions that exemplify landfill-anchored diversification into recycling infrastructure. Republic Services represents the automated sorting archetype with contamination-reduction positioning. Among North American specialists, Casella Waste Systems and Waste Connections sit within regional consolidation strategies targeting municipal contract density. Clean Harbors anchors hazardous construction waste treatment with specialized permitting capabilities. Remondis and GFL Environmental exemplify European-North American cross-border operational scale.
| Leading Market Players |
|---|
| Veolia Environment S.A. |
| Republic Services |
| Waste Management |
| Casella Waste Systems, Inc. |
| Clean Harbors, Inc. |
| Remondis |
| Waste Connections |
| GFL Environmental Inc. |
| Cleanaway Waste Management Limited |
| Others |
Supply Flow & Price Mechanics
EU Green Deal circular economy mandates gate both aggregate supply qualification and price differentiation simultaneously, forcing processors to invest in certification-grade sorting infrastructure before accessing premium road base contracts in Germany, France, and the United Kingdom.
Pricing Analysis
EU Green Deal mandates dictate the pricing tier structure across processed aggregate markets. Three-tier pricing stratifies across structural certification, road base specification, and non-specified fill grades. Price differentiation centers on contamination thresholds and digital chain-of-custody verification. Cost compression in mid-grade segments is intensifying because legacy mechanical sorting cannot meet rising ECHA REACH purity requirements. Municipal authorities and tier-one contractors show lowest price sensitivity; small demolition subcontractors remain most exposed to gate fee volatility.
Supply Chain Analysis
Near-infrared spectroscopy component supply anchors processing capacity expansion in Dutch and Belgian facilities. Germany, France, and the United States concentrate demolition feedstock generation and aggregate processing infrastructure. Equipment supply draws from Italian crushing manufacturers, German sensor technology providers, and Chinese steel fabrication. Single-source vulnerability sits with specialized X-ray fluorescence detector supply. Distribution runs through municipal contract bundling and integrated collection-to-recycling service agreements rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virgin quarried aggregate substitution threatens recycled material market share unless certification-grade processors demonstrate performance parity in structural applications.
For Market Incumbents: Shield landfill-anchored revenue by accelerating automated sorting deployment before diversion mandates strand disposal assets. Backward integration into demolition contracting secures feedstock pipelines in United Kingdom urban redevelopment zones. Investment in X-ray fluorescence and near-infrared certification capacity defends premium pricing against virgin aggregate price erosion. For New Entrants and Emerging Players: Lead with biomass fuel pathway specialization in French and German markets where AGEC and KrWG laws divert wood waste from landfill. Target thermal processing capacity gaps in energy recovery applications. Position around carbon credit monetization and municipal energy off-take agreements rather than commodity aggregate sales. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate environmental services divisions lacking integrated demolition-to-recycling infrastructure. Long-term viability favors operators with municipal contract density and landfill revenue buffers to fund sorting technology capex. Watch EU aggregate certification threshold tightening as inflection indicator for technology obsolescence risk in legacy mechanical processing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Deployment | Near-infrared and X-ray fluorescence systems unlock structural aggregate certification previously closed to recycled feedstock. |
| Integrated Municipal Contracting | Collection-to-recycling agreements with Paris and Berlin authorities lock in long-term feedstock security against competitors. |
| Biomass Fuel Pathway Expansion | Thermal processing of timber offcuts in French biomass facilities captures carbon credit value under EU ETS. |
| Digital Chain-of-Custody Investment | Blockchain verification platforms satisfy Transport for England and Greater London Authority procurement point requirements. |
| Pre-Demolition Audit Capability | AGEC and KrWG compliance services command premium fees from demolition contractors restructuring around material recovery logistics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with demolition contractors, municipal waste officers, aggregate processors, and biomass facility operators. Secondary validation drew from EPA Subtitle D filings, EU Waste Framework Directive transpositions, ECHA REACH protocols, and national construction waste statistics. Bottom-up volume modeling triangulated against top-down regulatory mandate impact assessments.
Across the analysis window, forecasts segmented by waste type, service layer, processing technology, and end-user category. Modeled dimensions included concrete grade certification, wood moisture content bands, and contamination threshold tiers. CAGRs derived from regulatory mandate enforcement timelines and urban redevelopment project pipelines. Industry-specific inputs incorporated EU Green Deal implementation schedules and biomass capacity expansion in France and Germany.
Forecasts assume regulatory continuity in EU Green Deal, AGEC, and KrWG regimes; material policy shifts would require re-modeling diversion quota trajectories. Practitioners should keep alternative scenarios live as aggregate certification threshold evolution and virgin quarry price volatility reshape substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market