
 Road Transport Refrigeration Equipment Market | 2026-2036
Road Transport Refrigeration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Road Transport Refrigeration Equipment Market Intelligence
The phase-out of high-GWP hydrofluorocarbons (HFCs) in favor of natural refrigerants like carbon dioxide (CO2) and hydrofluoroolefins (HFOs) is repositioning product design and component sourcing. Carrier Transicold leverages its global R&D network to develop next-generation, low-emission systems. Thermo King differentiates through its extensive service network and advanced telematics integration for fleet management. Meanwhile, Mitsubishi Heavy Industries Thermal Systems specializes in high-efficiency, electrically driven units for specific light commercial vehicle applications.
Road transport refrigeration equipment comprises self-contained systems designed to maintain specific temperature-controlled environments within trucks, trailers, and vans. These units, often operating between -25°C and +25°C, are essential for preserving the quality and safety of perishable goods during transit. Trailer units command a significant share due to their use in long-haul logistics, while van units see accelerated adoption for last-mile urban delivery. The food and beverage application remains the dominant end-use, though the pharmaceuticals segment offers higher-margin opportunities due to stringent validation requirements.
Regulations such as the EU's F-Gas Regulation and the US EPA's Significant New Alternatives Policy (SNAP) program dictate the pace of refrigerant transition. Global standards from organizations like the ISO ensure equipment performance and interoperability across international cold chains. Key strategic decisions for equipment manufacturers will revolve around balancing investment in all-electric systems versus improving the efficiency of traditional diesel-powered units.
Market Dynamics
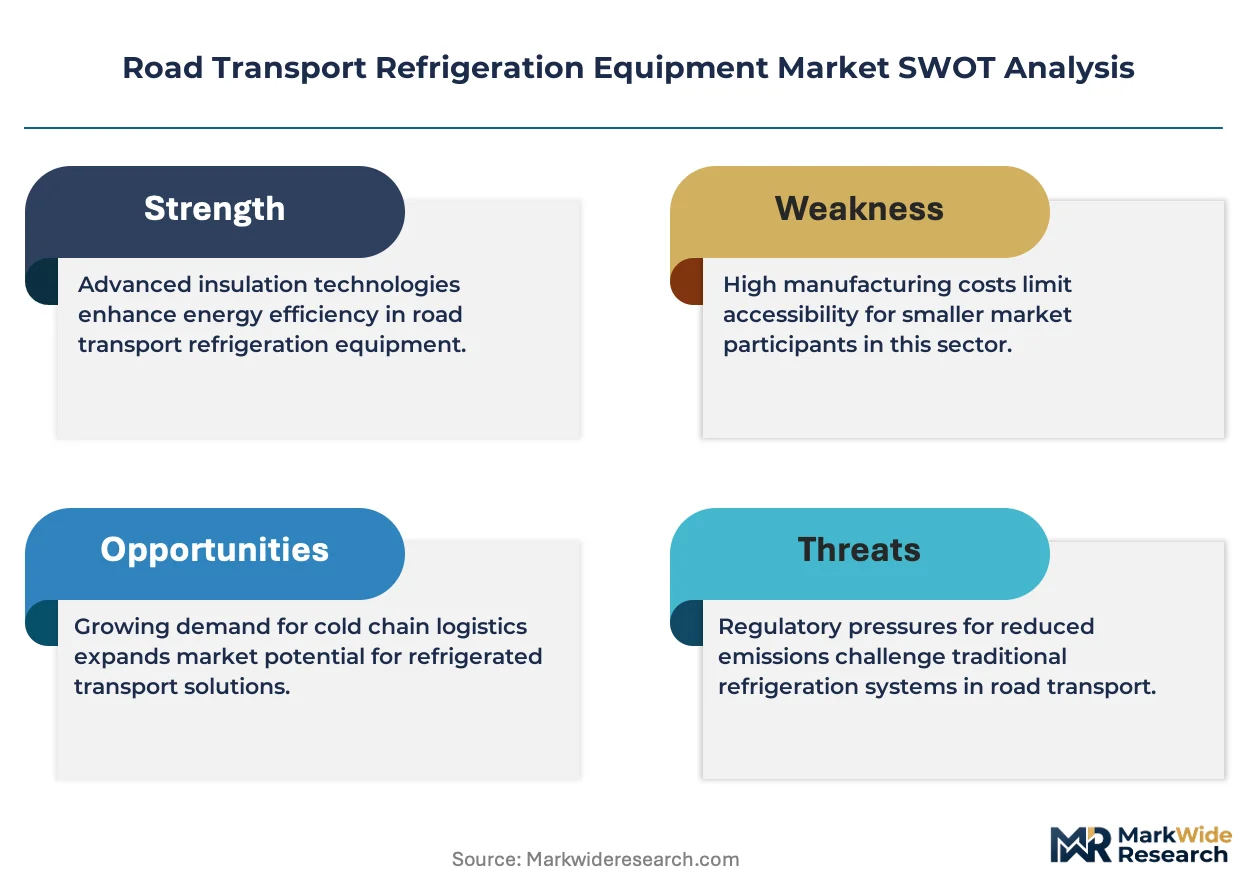
The transition away from high-GWP refrigerants, driven by regulations like the EU's F-Gas rules, is the central force compelling a complete redesign of refrigeration units, impacting everything from component selection to service technician training and equipment lifecycle costs.
Growth Catalysts
- Pharmaceutical Cold Chain Expansion:Heightened demand for temperature-controlled logistics for biologics and vaccines, which require strict and validated temperature ranges, stimulates investment in high-performance refrigeration units.
- Refrigerant Regulations:Mandates such as the EU F-Gas Regulation and the US EPA's SNAP program accelerate the replacement cycle of older equipment, forcing fleets to adopt systems using low-GWP alternatives like CO2 or HFOs.
- Food Supply Chain Modernization:In regions like Southeast Asia, the development of formal retail and food service sectors increases the need for refrigerated transport to reduce spoilage and connect agricultural producers with urban centers.
Market Restraints
- Higher Initial Capital Outlay:Systems utilizing natural refrigerants like CO2 or advanced HFOs often carry a significant price premium over traditional HFC-based units, delaying adoption among cost-sensitive fleet operators.
- Component Sourcing Constraints:The specialized compressors, heat exchangers, and control systems required for next-generation, low-GWP refrigeration units are subject to supply chain bottlenecks and are produced by a limited number of suppliers.
- Technical Hurdles of Alternatives:Natural refrigerants like CO2 operate at much higher pressures, while some HFO blends have mild flammability, creating engineering challenges and requiring more robust system designs and safety protocols.
Strategic Opportunities
- Telematics and IoT Integration:Embedding advanced sensors and connectivity provides opportunities for new service-based revenue models, including predictive maintenance, remote temperature monitoring, and automated compliance reporting for pharmaceutical clients.
- Last-Mile Delivery Solutions:The growth of e-commerce for groceries and meal kits creates a new market for smaller, lightweight, and often all-electric refrigeration units specifically designed for vans and light commercial vehicles in urban environments.
- Cold Chain Development in Africa:Investing in fit-for-purpose and robust refrigeration equipment for emerging markets in Africa addresses significant post-harvest food loss and opens a vast, underpenetrated market for cold chain infrastructure.
Industry Challenges
- Technician Skill Gaps:A shortage of service personnel trained to safely handle and maintain systems with new-generation refrigerants, which have different operating pressures and handling requirements, creates a significant operational bottleneck.
- Fleet Integration Complexity:Integrating new all-electric refrigeration units with a diverse range of existing truck and trailer chassis, each with different power systems and mounting configurations, poses a substantial engineering challenge.
- ATP Certification Delays:The lengthy and rigorous process for obtaining ATP certification for new equipment designs can slow market entry and add considerable R&D expense, particularly for smaller manufacturers.
Report Scope
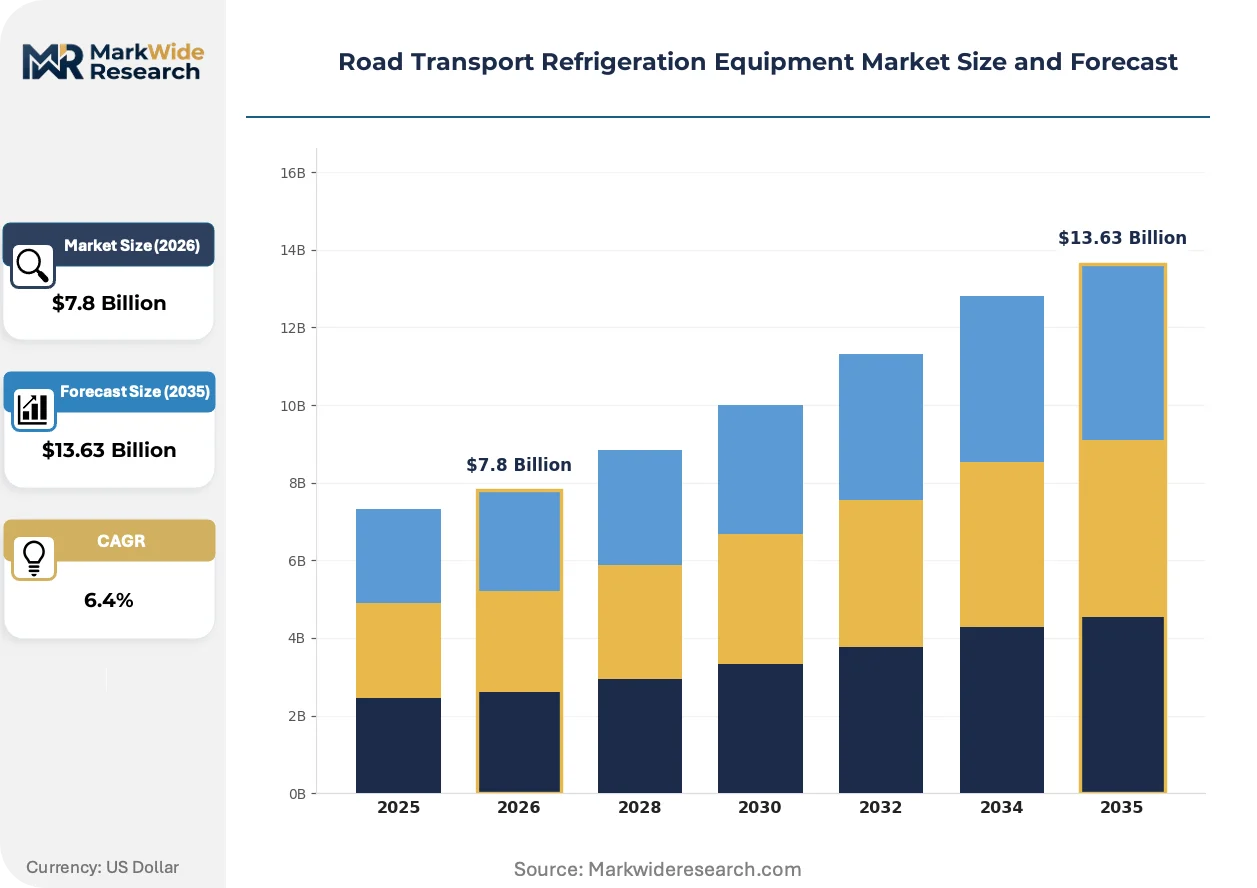
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Transport Refrigeration Equipment Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck-Mounted Units, Trailer Units, Van Units, Container-Integrated Units Technology: Vapor Compression, Thermoelectric, Absorption, Cryogenic Application: Food & Beverage, Pharmaceuticals, Chemicals, Floral Transport, Cosmetics End User: Cold Chain Operators, Freight Forwarders, Logistics Providers, Third-Party Warehouses, E-commerce Distributors |
| Companies Covered | Carrier Transicold, Thermo King, Mitsubishi Heavy Industries Thermal Systems, Trane Technologies plc, Daikin Industries, G.A.H. Refrigeration, Danfoss, Hwasung Thermo, Songz Automobile Air Conditioning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Transport Refrigeration Equipment Market Strategic Shifts & Innovations
The market's trajectory is defined by a dual technological push: the shift to sustainable, low-GWP refrigerants to meet climate regulations and the integration of digital technologies to transform equipment from standalone hardware into connected, data-generating assets.
Electrification of Power Sources
All-electric and hybrid-electric refrigeration units provide a direct alternative to conventional diesel-powered systems. Fleet operators focused on urban and last-mile delivery are the primary adopters, driven by local emissions standards and noise abatement zones. In these specific applications, battery-electric architecture is overtaking the traditional dominance of diesel-driven units for vans and light-duty trucks.
Regulatory-Driven Technology Adoption
The US EPA’s Significant New Alternatives Policy (SNAP) program continues to phase out high-GWP HFCs, compelling manufacturers to innovate. This regulatory pressure accelerates the commercialization of systems using approved low-GWP refrigerants. The long-haul trailer segment is particularly impacted, facing substantial capital decisions regarding fleet replacement or retrofitting to ensure compliance.
Shift to Service-Based Models
A transition from one-time equipment sales toward comprehensive service-level agreements that guarantee temperature uptime is gaining momentum. This model, enabled by telematics and remote diagnostics, replaces the conventional break-fix maintenance approach. This trend is most pronounced within the pharmaceutical and high-value food logistics sectors, where auditable temperature compliance is a critical procurement requirement.
Road Transport Refrigeration Equipment Market Segmentation
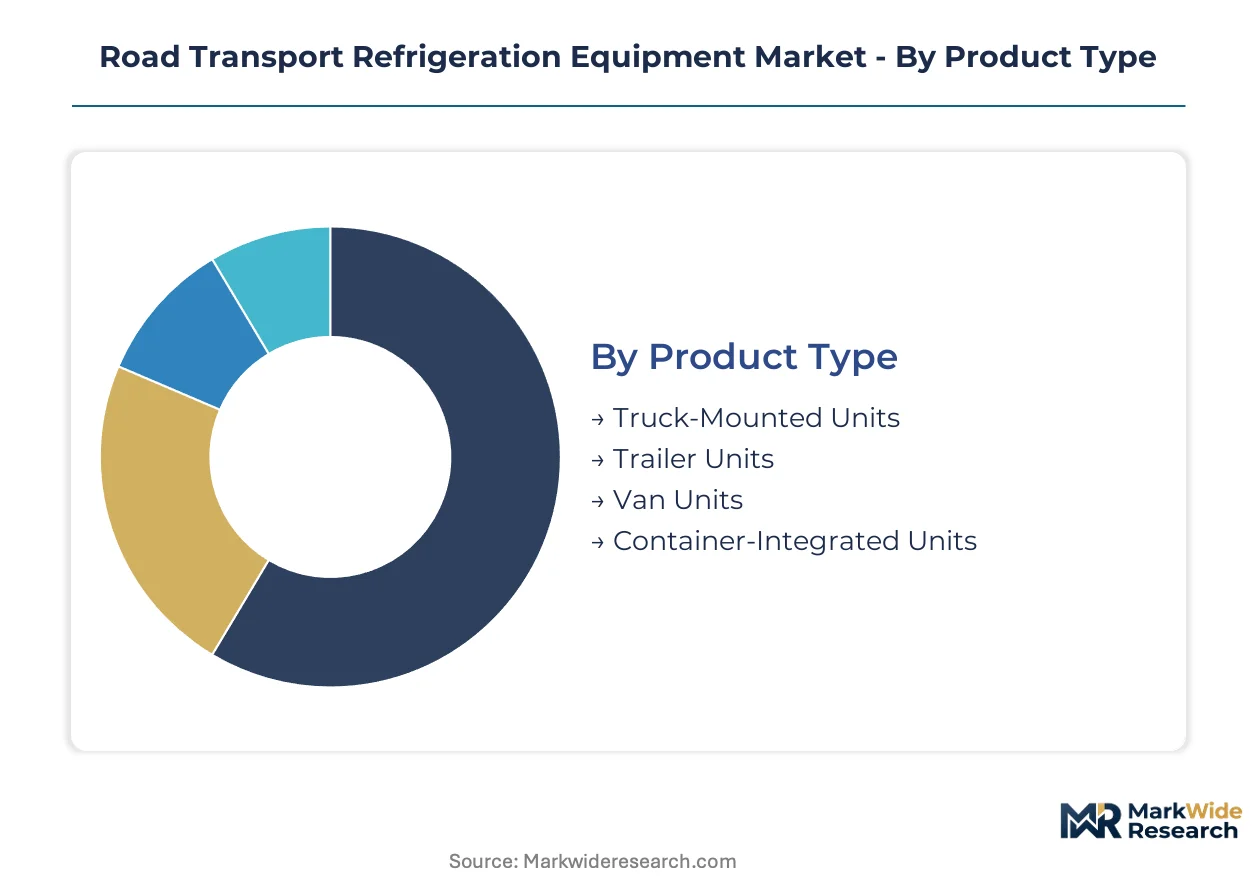
The road transport refrigeration equipment market segments define distinct operational requirements and regulatory compliance pathways. Understanding these divisions helps manufacturers align product development with specific logistical demands and end-user needs. Each segment presents unique challenges regarding temperature precision and power source integration.
Product Type:
The type of refrigeration unit often dictates the complexity of certification processes, with larger, more specialized units requiring stringent ATP certification for international transit. Different product types also face varying regulatory scrutiny regarding refrigerant leakage and noise emissions.
- Trailer Units:These large, self-contained systems are designed for semi-trailers, maintaining temperatures for long-haul logistics. Demand concentrates in established cold chain markets like Europe and North America, driven by the need for high-capacity, multi-temperature transport for perishable goods.
- Van Units:Smaller, often electrically driven units integrate into light commercial vehicles for urban and last-mile delivery. Adoption accelerates in densely populated areas such as Southeast Asia, where e-commerce growth for groceries and meal kits requires efficient, quiet transport solutions.
- Truck-Mounted Units:These units are installed directly onto the chassis of rigid trucks, providing temperature control for regional distribution routes.
- Container-Integrated Units:Specialized systems built into intermodal containers facilitate seamless cold chain transitions across different transport modes.
Leading the category by volume: Trailer Units. Growing fastest: Van Units.
Technology:
Technology choices directly influence the initial capital outlay and operational costs of refrigeration systems, with advanced, low-GWP solutions often commanding a price premium. The selection impacts energy consumption, maintenance requirements, and overall lifecycle expenses for fleet operators.
- Vapor Compression:This traditional and most common technology relies on a refrigerant circulating through compression, condensation, expansion, and evaporation cycles. It dominates the market due to its proven reliability and efficiency across a wide range of temperature requirements for diverse perishable goods.
- Cryogenic:These systems use liquefied gases like nitrogen or carbon dioxide to provide rapid and precise temperature control, particularly for ultra-low temperature applications. Demand for cryogenic solutions is significant within the pharmaceutical sector for transporting sensitive biologics and vaccines.
- Thermoelectric:Utilizing the Peltier effect, these solid-state devices offer compact, vibration-free cooling, primarily for small-scale and specialized applications.
- Absorption:These systems use heat to drive the refrigeration cycle, often suitable for stationary or hybrid applications where waste heat is available.
The dominant technology is Vapor Compression, with Cryogenic experiencing significant expansion.
Application:
Applications are defined by the specific types of goods transported, influencing the required temperature precision, validation protocols, and cargo handling procedures. Different applications cater to distinct customer types, from large-scale food distributors to specialized pharmaceutical logistics providers.
- Food & Beverage:This segment encompasses the vast transport of fresh produce, dairy, meat, and frozen foods, requiring consistent temperature maintenance to prevent spoilage. It represents the largest end-use segment, particularly important for modernizing supply chains in regions like Southeast Asia.
- Pharmaceuticals:This high-value segment demands ultra-precise temperature control, often within narrow ranges, for vaccines, biologics, and other temperature-sensitive drugs. Stringent validation and monitoring protocols are critical, making this a higher-margin opportunity globally.
- Chemicals:Transport of temperature-sensitive industrial chemicals and hazardous materials requires robust and often explosion-proof refrigeration systems.
- Floral Transport:Maintaining specific humidity and temperature conditions is essential for preserving the freshness and appearance of cut flowers during transit.
- Cosmetics:Certain cosmetic products require temperature-controlled environments to prevent degradation and maintain product integrity.
This category is led by Food & Beverage, while Pharmaceuticals is showing the steepest expansion trajectory.
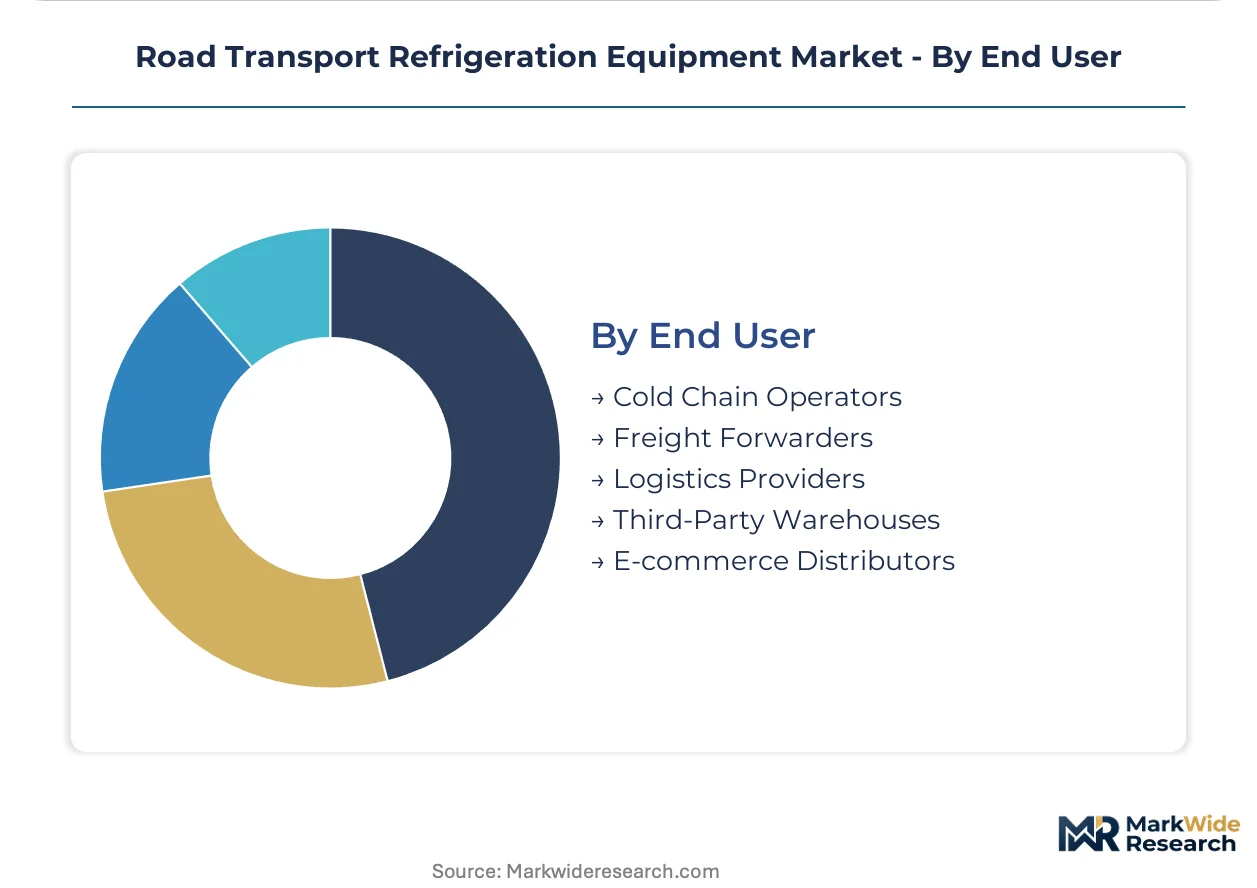
End User:
End-user segments reflect varying operational scales and logistical complexities, from large fleet operators managing thousands of units to smaller e-commerce players. The volume of goods transported often dictates the size and sophistication of the refrigeration equipment deployed by these entities.
- Cold Chain Operators:These specialized logistics companies manage temperature-controlled transport, warehousing, and distribution as their core business. They invest in diverse fleets of refrigeration units, integrating telematics for comprehensive oversight and compliance across their extensive networks.
- E-commerce Distributors:Companies focused on online grocery and meal kit delivery increasingly utilize refrigerated vans and light commercial vehicles for last-mile urban logistics. This segment drives demand for compact, often all-electric refrigeration solutions to meet rapid delivery schedules.
- Freight Forwarders:These entities arrange the transport of goods, often subcontracting to specialized cold chain providers for refrigerated cargo.
- Logistics Providers:Broader logistics companies offer temperature-controlled services as part of their comprehensive supply chain management offerings.
- Third-Party Warehouses:These facilities provide storage and distribution services, often requiring refrigerated transport for inbound and outbound goods.
The largest end-user group is Cold Chain Operators, with E-commerce Distributors climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for road transport refrigeration equipment is concentrating across diverse global markets, driven by evolving food supply chains and stringent pharmaceutical logistics. Established cold chain networks in developed economies continue to upgrade, while emerging markets expand infrastructure. This global expansion reflects both regulatory pressures and consumer expectations for fresh and safe perishable goods.
United States
The United States experiences heightened demand for high-performance refrigeration units, particularly for pharmaceutical biologics and last-mile grocery delivery. The US EPA's SNAP program accelerates the transition away from high-GWP HFCs, compelling fleet operators to upgrade. In California's agricultural regions, robust refrigerated transport ensures fresh produce reaches distant markets efficiently.
Germany
Germany drives significant investment in trailer units for long-haul logistics, supporting its extensive food and beverage industry. The EU F-Gas Regulation compels a rapid shift towards low-GWP refrigerants, impacting equipment design across the nation. The Rhine-Ruhr metropolitan region, a key distribution hub, sees continuous innovation in multi-temperature transport solutions.
Indonesia
Indonesia leads in the adoption of van units, fueled by the modernization of its food and beverage supply chains and rapid e-commerce expansion. National food safety standards encourage investment in reliable refrigeration for perishable goods. In Jakarta and other major urban centers, efficient last-mile refrigerated delivery is becoming critical for consumer satisfaction.
India
India's growing pharmaceutical sector and the expansion of organized retail are stimulating demand for validated temperature-controlled logistics. The CDSCO guidelines for drug storage and transport necessitate precise and reliable refrigeration solutions for biologics. Hyderabad's pharmaceutical hub is experiencing a surge in demand for specialized cold chain equipment to support vaccine and drug distribution.
Road Transport Refrigeration Equipment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, influencing competitive dynamics. The market exhibits a tiered structure, with established global players alongside regional niche providers. Strategic archetypes include integrated solution providers, technology innovators, and cost-focused mass producers. Dominant competitive moves involve strategic partnerships to enhance technological capabilities and geographic expansion into high-growth emerging markets.
On the premium-tier vector, Carrier Transicold and Thermo King represent integrated solution providers, leveraging extensive research and development networks for advanced low-emission systems. These entities occupy a significant position in established cold chain markets, offering comprehensive telematics and service networks. Their global presence and broad product portfolios allow them to address diverse customer needs from long-haul trailers to urban delivery vans. Meanwhile, Mitsubishi Heavy Industries Thermal Systems exemplifies a specialized technology innovator, focusing on high-efficiency, electrically driven units for specific light commercial vehicle applications. These companies anchor market development through their continuous innovation in refrigerant technologies and power sources, adapting to evolving regulatory landscapes.
| Leading Market Players |
|---|
| Carrier Transicold |
| Thermo King |
| Mitsubishi Heavy Industries Thermal Systems |
| Trane Technologies plc |
| Daikin Industries |
| G.A.H. Refrigeration |
| Danfoss |
| Hwasung Thermo |
| Songz Automobile Air Conditioning |
| Others |
Cost & Logistics Intelligence
Global industrial conglomerates and specialized manufacturers shape the road transport refrigeration market, with their ownership structures influencing both component supply behavior and the discipline of equipment pricing.
Pricing Analysis
Volume sales often prioritize cost-effectiveness, while higher-margin opportunities exist in specialized segments demanding advanced features. The dominant pricing model is per-unit transactional, augmented by premium tiers for systems with enhanced telematics integration or ATP certification. Pricing softness reflects the higher initial capital outlay for low-GWP systems, particularly impacting cost-sensitive fleet operators. Pharmaceutical clients, however, demonstrate lower price sensitivity due to stringent validation requirements and high-value cargo.
Supply Chain Analysis
Skilled technician availability in key manufacturing hubs such as Germany and Japan directly influences the production capacity of advanced refrigeration units. The supply chain draws from specialized component manufacturers concentrated in Germany, Japan, and China for items like high-pressure compressors and HFOs. Single-source vulnerability for these specialized components presents a structural risk. Equipment distribution typically occurs through established dealer networks and direct sales channels to large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The road transport refrigeration equipment market is poised for consolidation, driven by the escalating costs of regulatory compliance for low-GWP refrigerants, which pressure smaller players.
For Market Incumbents:
Extend R&D investment into all-electric systems to counter the threat of new electrification-focused entrants. Consolidate market share by acquiring regional specialists with strong service networks in emerging markets like Southeast Asia. Leverage vertical integration into specialized component manufacturing to mitigate supply chain bottlenecks for critical parts.
For New Entrants and Emerging Players:
Telematics and IoT integration offer a technology-first wedge for new entrants. Target the last-mile delivery segment in rapidly urbanizing areas, particularly in Southeast Asia, with compact, all-electric van units. Develop subscription-based service models for predictive maintenance and automated compliance reporting for pharmaceutical clients.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor well-capitalized private equity firms in Europe, where F-Gas regulations are accelerating equipment replacement cycles. The market offers long-term viability over the next decade due to persistent demand for cold chain logistics. Target acquisition profiles include mid-sized manufacturers specializing in low-GWP componentry or telematics solutions. Watch for regulatory enforcement intensity as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in All-Electric System R&D | This initiative prepares manufacturers for stringent urban emission standards and noise abatement zones. |
| Develop Low-GWP Refrigerant Componentry | This move mitigates supply chain bottlenecks for specialized compressors and heat exchangers. |
| Expand Telematics and IoT Offerings | This enhances remote monitoring capabilities for pharmaceutical clients and enables predictive maintenance. |
| Acquire Regional Service Networks | This strengthens after-sales support for complex low-GWP systems, particularly in emerging markets. |
| Standardize Van Unit Integration | This simplifies the integration of compact refrigeration units across diverse light commercial vehicle chassis. |
Research Approach
Document review covered regulatory filings from US EPA and EU F-Gas, industry association reports, and company annual disclosures, complemented by interviews with industry stakeholders. Primary research involved discussions with fleet operators, equipment manufacturers' R&D leads, cold chain logistics managers, and service technicians. This approach enabled bottom-up data collection and top-down validation.
Historical market data was cross-referenced with expert panel input to construct the forecast framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory impact. Compound annual growth rates were derived from projected shifts in refrigerant technology adoption and fleet modernization. Forecast inputs included evolving F-Gas phase-down schedules and e-commerce penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant shifts in refrigerant policy or economic downturns. The forecasts reflect assumptions regarding technological development and supply chain stability. Material deviation in regulatory timelines or component availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Malaysia Domestic CEP Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Germany Road Freight Transport Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
UAE Cold Chain Logistics Market