
 United States Short Haul Road Freight Transport Market | 2026-2036
United States Short Haul Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
United States Short Haul Road Freight Transport Market Analytics
Driver availability is unwinding capacity expansion plans across the short haul sector. Knight-Swift Transportation Holdings Inc. sustains competitive density through its dedicated contract carriage model. FedEx leverages integrated ground networks to compress transit times on regional lanes. J.B. Hunt anchors intermodal short haul with rail-adjacent drayage operations.
United States Short Haul Road Freight Transport covers commercial cargo movement typically under 500 miles using Class 3-8 vehicles operating on fixed or dynamic routing schedules. Fleet specifications emphasize diesel, natural gas, and battery-electric powertrains with gross vehicle weight ratings from 10,001 to 80,000 pounds serving just-in-time manufacturing and omnichannel retail replenishment. Full Truckload service dominates revenue capture on high-volume corridors while Less-than-Truckload networks aggregate fragmented shipper demand through hub-and-spoke terminal systems. Refrigerated Truck configurations command premium positioning in temperature-controlled agriculture and foodservice verticals.
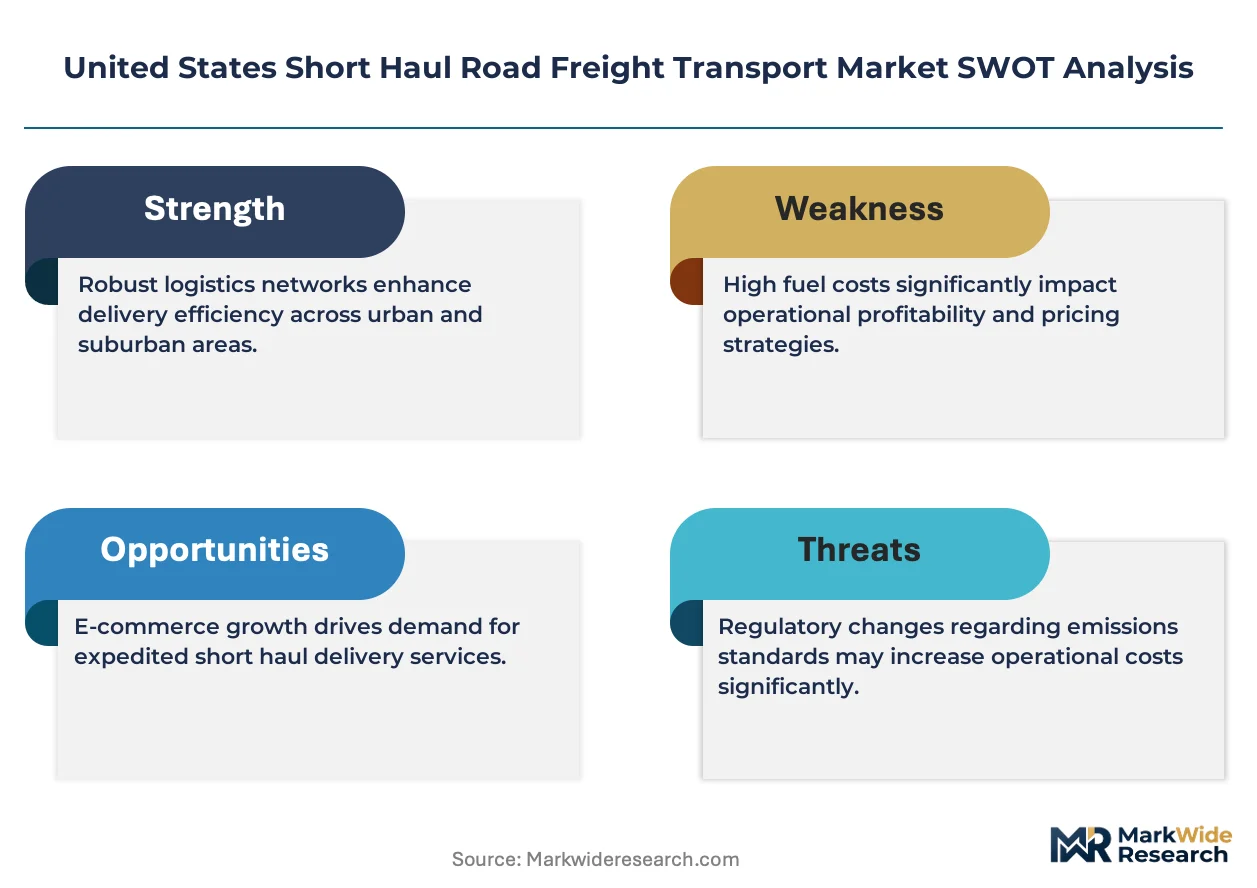
FMCSA hours-of-service regulations constrain operational design by limiting daily driving windows and mandating electronic logging device compliance across interstate commerce. EPA Phase 3 standards and NHTSA fuel economy rules jointly elevate powertrain investment requirements while California Air Resources Board waivers create bifurcated compliance obligations for national fleet operators. Stakeholders must weigh electrification capital deployment against route-specific charging infrastructure readiness and state-level incentive programs.
Market Dynamics
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are forcing fleet operators to accelerate powertrain diversification while driver shortages compress available capacity across regional corridors. This regulatory-pressure combination is restructuring operational economics and equipment procurement timelines.
Growth Catalysts
- E-commerce fulfillment density:Warehouse-to-last-mile gaps are widening as distribution centers cluster near population centers, creating dedicated freight circuits for short haul carriers serving omnichannel retail replenishment.
- FMCSA electronic logging device mandates:ELD compliance has standardized hours-of-service tracking, enabling route optimization software to maximize asset utilization within federally constrained driving windows.
- Midwest manufacturing belt concentration:Automotive and industrial machinery production clusters in Michigan, Ohio, and Indiana generate predictable, high-frequency freight loops that support dedicated contract carriage models.
Market Restraints
- Diesel price volatility:Fuel represents 25-35% of operating costs for Class 8 fleets, with price spikes immediately eroding margins on contracted lanes lacking fuel surcharge mechanisms.
- California Air Resources Board bifurcation:CARB waivers create compliance complexity for national operators running interstate routes, forcing dual equipment specifications or geographic fleet segmentation.
- Charging infrastructure gaps:Battery-electric truck deployment stalls on corridor-specific charging deserts, particularly on Texas-to-California lanes where 500-mile range requirements exceed current infrastructure.
Strategic Opportunities
- Intermodal drayage expansion:Rail-adjacent short haul connecting inland ports to distribution centers offers volume growth as shippers seek modal flexibility on volatile lanes.
- Refrigerated vertical premium capture:Temperature-controlled agriculture and foodservice segments command rate premiums, with California Central Valley produce corridors representing underserved dedicated capacity opportunities.
- IRA commercial vehicle tax credits:Inflation Reduction Act incentives for zero-emission trucks reduce electrification capital barriers for fleet operators with depot-charging capabilities.
Industry Challenges
- Commercial driver license pipeline collapse:Training school capacity constraints and demographic shifts limit qualified operator inflows, forcing wage inflation and retention program investments.
- Depot electrification capex intensity:Megawatt-scale charging infrastructure requires utility coordination, transformer upgrades, and land acquisition that extend payback periods beyond traditional equipment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Short Haul Road Freight Transport Market |
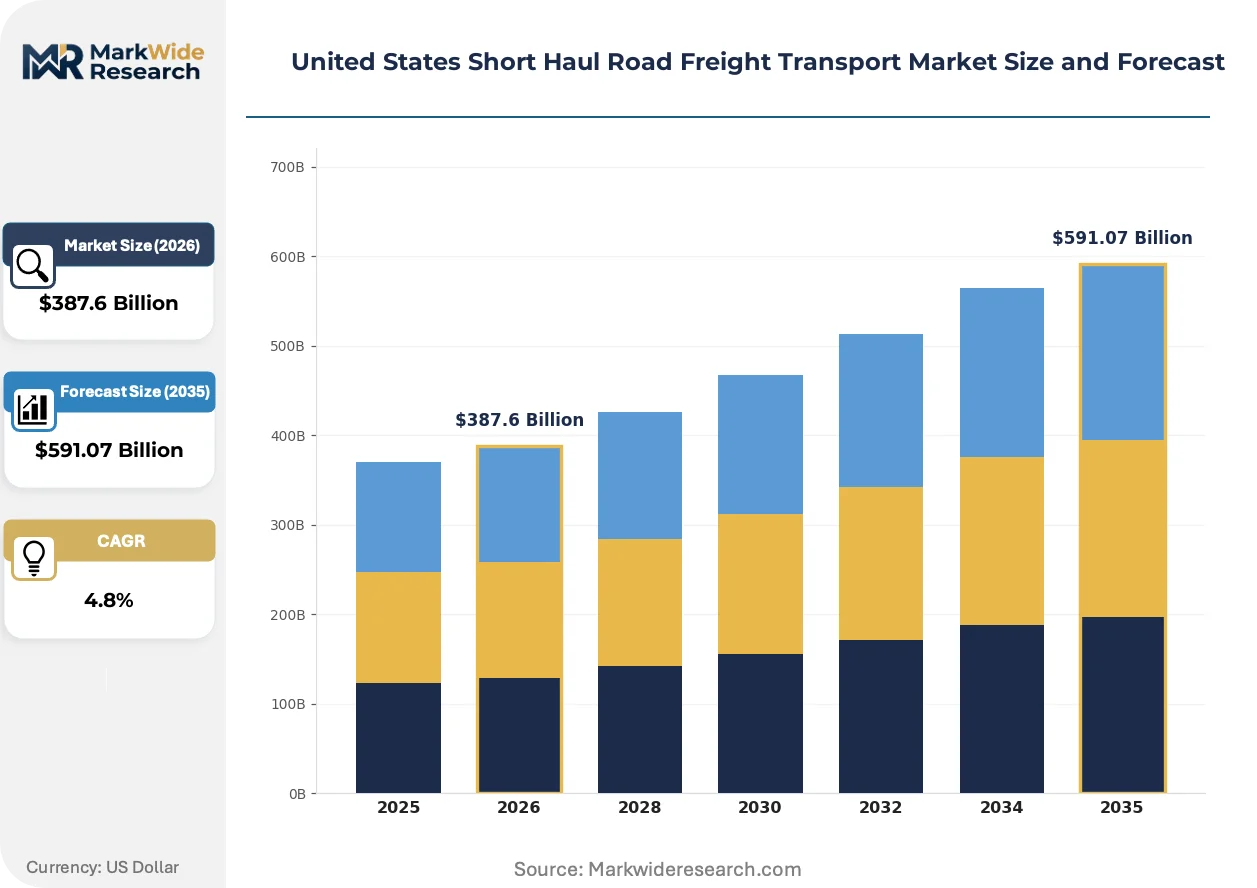
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Less-than-Truckload, Full Truckload, Intermodal, Dedicated Freight Vehicle Type: Box Truck, Flatbed Truck, Van Truck, Refrigerated Truck Industry Vertical: Retail, Agriculture, Manufacturing, Construction Delivery Mode: Direct Delivery, Scheduled Routes, Last-Mile, Consolidated Service |
| Companies Covered | FedEx, United Parcel Service of America, Inc., XPO, Inc., Schneider National, Inc., Knight-Swift Transportation Holdings Inc., Landstar System Inc., DHL Group, Ryder System, Inc., J.B. Hunt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Short Haul Road Freight Transport Market Evolving Landscape
Powertrain electrification and autonomous assist technologies are compressing operational cost structures while reshaping fleet procurement priorities. These shifts are accelerating equipment replacement cycles and redefining competitive differentiation in regional freight markets.
Battery-electric Class 6-8 trucks with 200-300 mile range are displacing diesel units on predictable urban and suburban distribution loops. Grocery and parcel carriers with return-to-depot operations are deploying these vehicles fastest, with charging infrastructure concentrated at distribution centers eliminating public charging dependency. This displacement is compressing total cost of ownership calculations and narrowing the payback gap against conventional powertrains.
EPA Phase 3 standards tighten CO2 emissions thresholds for heavy-duty vehicles through model year 2032, with interim targets beginning 2027. Fleet operators must demonstrate compliance through powertrain mix shifts, aerodynamic improvements, or low-rolling-resistance tires. California-based carriers face additional CARB Advanced Clean Trucks mandates requiring increasing zero-emission vehicle sales percentages, forcing accelerated procurement timelines.
Shippers are consolidating carrier relationships around dedicated contract carriage models that guarantee capacity over spot market volatility. Large retailers and manufacturers are displacing transactional freight procurement with multi-year agreements embedding service level guarantees. This concentration is most visible in Texas and Southeast corridors where manufacturing reshoring has intensified volume predictability requirements.
United States Short Haul Road Freight Transport Market Segmentation
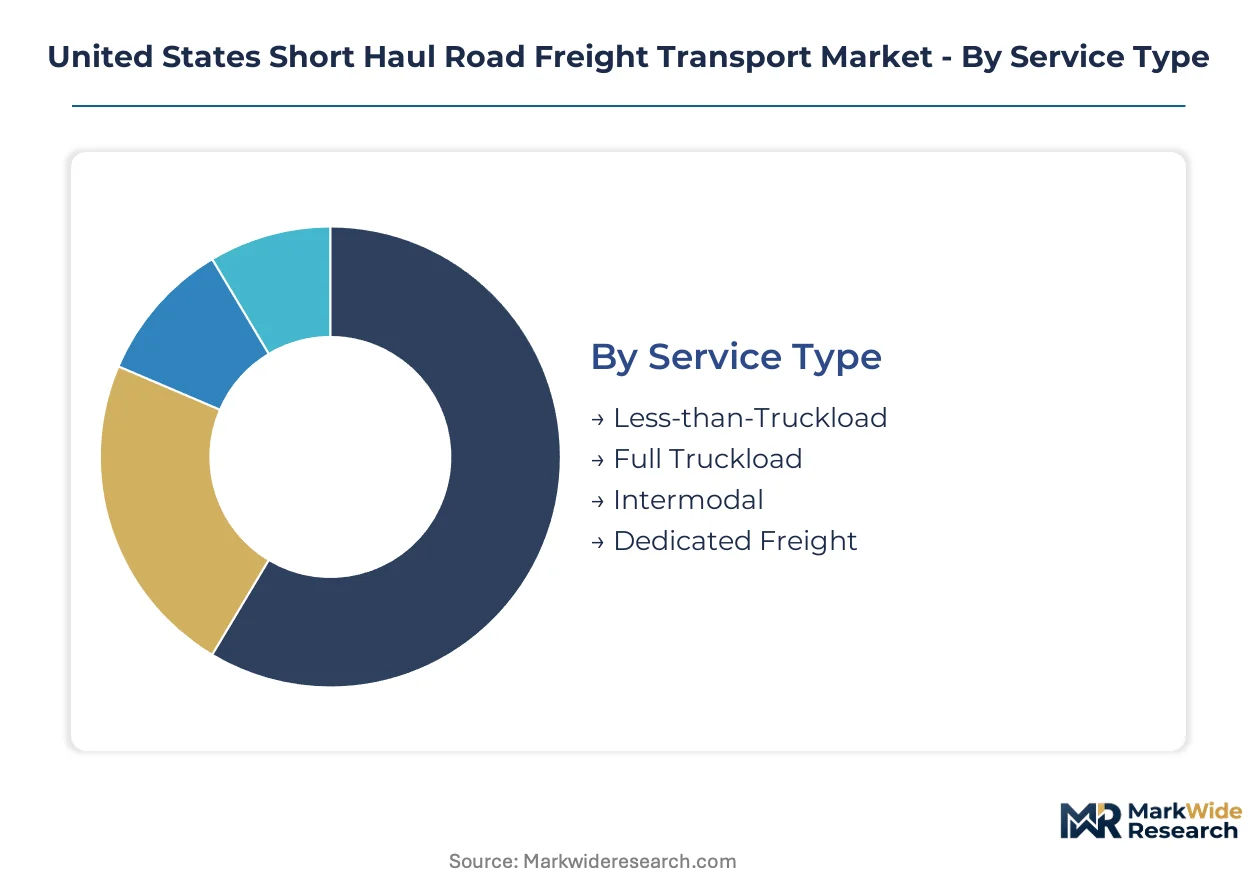
Service configuration determines capital intensity and margin structure across short haul operations. Fleet operators align equipment specifications and routing protocols to match customer replenishment cadences and cargo characteristics.
Service Type:
Channel flow splits between transactional spot markets and contracted dedicated lanes, with each service model demanding distinct asset deployment strategies and driver management frameworks.
- Full Truckload:Single-shipper cargo fills entire vehicle capacity on point-to-point routing. Texas-to-California manufacturing corridors and Midwest automotive circuits concentrate demand where shippers prioritize transit time reliability over cost minimization.
- Less-than-Truckload:Freight from multiple shippers aggregates through hub-and-spoke terminal networks for cost-efficient consolidation. E-commerce replenishment and small-batch manufacturing in urban clusters drive density, though terminal handling costs erode margins on low-weight shipments.
- Intermodal:Rail-adjacent drayage connects inland ports to distribution centers using standardized containers. Shippers seeking fuel cost hedging on volatile lanes favor this mode, particularly on Texas and Southeast corridors with strong rail infrastructure.
- Dedicated Freight:Exclusive vehicle and driver assignment for single-shipper accounts under multi-year contracts. Large retailers securing warehouse-to-last-mile circuits dominate procurement, accepting premium rates for guaranteed capacity.
Full Truckload dominates installed base. Dedicated Freight is where expansion concentrates.
Vehicle Type:
Equipment selection tracks cargo protection requirements and loading efficiency, with powertrain choices increasingly constrained by EPA Phase 3 compliance timelines.
- Box Truck:Enclosed cube bodies protect general freight from weather and theft on urban distribution loops. Parcel and grocery carriers with return-to-depot operations deploy these units fastest for battery-electric conversion.
- Refrigerated Truck:Insulated bodies with integrated cooling systems maintain temperature-controlled environments for perishables. California Central Valley produce corridors and foodservice distribution into Texas metropolitan areas command rate premiums for this specialized capacity.
- Flatbed Truck:Open decks accommodate oversized or irregularly shaped cargo using tie-down systems. Construction materials and industrial machinery moving across Midwest manufacturing belts rely on this configuration.
- Van Truck:Light-duty enclosed bodies handle final-mile parcel delivery and small-format retail replenishment. Dense urban zones with congestion pricing favor these smaller footprints.
Box Truck represents the largest fleet population. Refrigerated Truck is gaining share fastest.
Industry Vertical:
End-use concentration shapes seasonal demand patterns and service level requirements, with vertical specialization enabling rate premiums.
- Retail:Omnichannel replenishment demands flexible capacity scaling around promotional calendars and inventory velocity targets. Distribution center clustering near population centers creates predictable short haul circuits.
- Manufacturing:Just-in-time production schedules require precise delivery windows and dedicated contract carriage relationships. Automotive and industrial machinery clusters in Michigan, Ohio, and Indiana generate high-frequency loops.
- Agriculture:Seasonal harvest windows compress volume into narrow timeframes requiring surge capacity. Temperature-controlled equipment and expedited scheduling command premium positioning.
- Construction:Project-based demand fluctuates with housing starts and infrastructure spending cycles. Flatbed configurations dominate material transport to job sites.
Retail anchors volume throughput. Manufacturing is where contract carriage penetration deepens.
Delivery Mode:
Routing architecture determines asset utilization rates and driver hour consumption under FMCSA regulatory constraints.
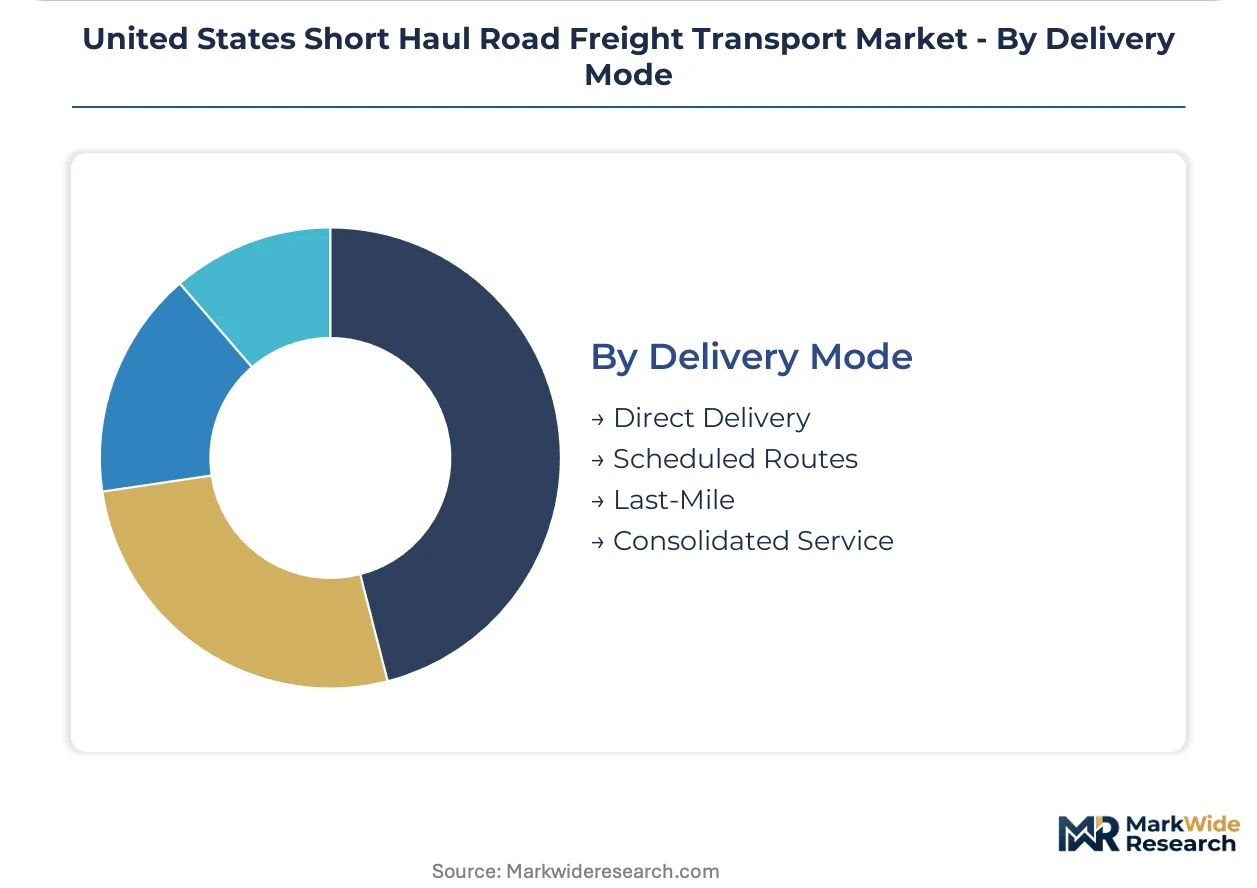
- Scheduled Routes:Fixed circuits between known origins and destinations maximize planning efficiency. Grocery and parcel networks with daily replenishment cadences rely on this predictability.
- Last-Mile:Final delivery leg from distribution center to consumer or commercial recipient. E-commerce fulfillment density in suburban zones drives dedicated fleet deployment for time-definite service.
- Direct Delivery:Point-to-point transport without intermediate handling or consolidation. High-value manufacturing components and time-sensitive perishables favor this mode.
- Consolidated Service:Multiple shipments combined into single vehicle movements through terminal aggregation. Cost-sensitive shippers accept longer transit times for freight savings.
Scheduled Routes dominates operational deployment. Last-Mile is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 standards and CARB waivers anchor regulatory complexity across the dominant United States geography, forcing fleet operators to navigate bifurcated compliance obligations while capitalizing on regional demand concentration.
Texas
Interstate manufacturing corridors connecting Houston, Dallas-Fort Worth, and San Antonio generate high-frequency freight loops for automotive and petrochemical shippers. The Texas Commission on Environmental Quality administers state-level emissions programs that complement federal EPA standards. The I-35 corridor from Laredo through Dallas anchors cross-border trade volume with dedicated drayage circuits serving inland port expansion.
California
Central Valley agriculture and Los Angeles-Long Beach port complex demand temperature-controlled and intermodal short haul capacity with strict delivery windows. CARB Advanced Clean Trucks mandates require accelerating zero-emission vehicle procurement timelines for fleets operating statewide. The Inland Empire distribution center cluster creates dense warehouse-to-last-mile circuits for omnichannel retail replenishment.
Michigan
Detroit-area automotive assembly plants and just-in-time supplier networks sustain dedicated contract carriage relationships with precise scheduling requirements. The Michigan Department of Environment, Great Lakes, and Energy coordinates with federal EPA on heavy-duty vehicle emissions enforcement. The I-75 corridor through Flint and Saginaw concentrates Tier 1 and Tier 2 supplier freight loops.
Ohio
Columbus and Cleveland distribution hubs serve as mid-Atlantic and Midwest consolidation points for Less-than-Truckload networks. The Ohio Environmental Protection Agency implements state diesel retrofit programs affecting fleet equipment specifications. The I-71 corridor connecting Cincinnati through Cleveland anchors manufacturing freight for industrial machinery and consumer goods.
Illinois
Chicago metropolitan rail intermodal terminals generate substantial drayage demand connecting inland ports to regional distribution centers. The Illinois Environmental Protection Agency administers diesel emissions testing programs for commercial vehicle fleets. The I-55 corridor through Joliet and Bloomington concentrates refrigerated freight for foodservice distribution into the upper Midwest.
United States Short Haul Road Freight Transport Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with national LTL networks and dedicated contract carriage operators commanding density advantages on high-volume corridors. The upper tier consolidates around asset-heavy carriers with intermodal capabilities and refrigerated specializations, while mid-tier players compete on regional lane expertise and shipper relationship depth. Strategic archetypes include integrated parcel-ground networks, dedicated contract carriage specialists, and intermodal drayage operators. Competitive moves center on fleet electrification partnerships with charging infrastructure providers and multi-year dedicated capacity agreements with large retail shippers.
Within the integrated parcel-ground tier, FedEx and United Parcel Service of America, Inc. anchor national networks with dense last-mile capabilities, while Knight-Swift Transportation Holdings Inc. exemplifies the dedicated contract carriage archetype through its asset-heavy regional positioning. These operators occupy positions that reflect divergent capital intensity models: parcel networks emphasizing facility automation against truckload carriers prioritizing driver retention and equipment standardization.
| Leading Market Players |
|---|
| FedEx |
| United Parcel Service of America, Inc. |
| XPO, Inc. |
| Schneider National, Inc. |
| Knight-Swift Transportation Holdings Inc. |
| Landstar System Inc. |
| DHL Group |
| Ryder System, Inc. |
| J.B. Hunt |
| Others |
Value Network & Pricing Analysis
Long-term dedicated contract carriage locks in both supply access and price visibility for large retail shippers navigating volatile regional corridors. This structure insulates carriers from spot market erosion while committing shippers to premium rates for guaranteed capacity on warehouse-to-last-mile circuits.
Pricing Analysis
Contract-based long-term offtake dominates pricing structure, with three-tier pricing separating dedicated freight from standard full truckload and spot market tiers. Price differentiation rests on service level guarantees and equipment specialization, with refrigerated verticals commanding premiums over dry van operations. Cost compression in standard full truckload is intensifying because diesel price volatility erodes margins on lanes lacking fuel surcharge mechanisms. Small-batch manufacturers and cost-sensitive regional distributors exhibit highest price sensitivity, while large omnichannel retailers accept premium positioning for capacity certainty.
Supply Chain Analysis
Inventory cycles compress to 24-48 hour replenishment windows across grocery and parcel networks, forcing carriers to stage equipment near distribution centers. Class 8 truck manufacturing concentrates in Michigan, Ohio, and Mexico, while battery cell production for electric powertrains draws from South Korea and China. Single-source vulnerability in semiconductor-based telematics and electronic logging devices creates procurement risk for fleet operators. Distribution runs through hub-and-spoke terminal networks for less-than-truckload, with dedicated contract carriage bypassing intermediate handling entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 standards are forcing fleet operators toward electrification investments that will reshape competitive economics across regional corridors. This regulatory inflection compresses payback calculations and accelerates equipment replacement cycles.
For Market Incumbents: Shield core density positions through backward integration into depot charging infrastructure, securing utility interconnection priority for megawatt-scale installations. Consolidate driver retention programs with wage premiums and guaranteed route assignments to counter commercial driver license pipeline collapse. Prioritize dedicated contract carriage expansion in Texas and Southeast corridors where manufacturing reshoring intensifies volume predictability. For New Entrants and Emerging Players: Temperature-controlled agriculture corridors represent underserved capacity where incumbent refrigerated fleets lack dedicated contract carriage penetration. Target California Central Valley produce loops and foodservice distribution into Texas metropolitan areas with asset-light brokerage models before scaling to owned equipment. Pursue shipper-direct relationships bypassing traditional freight broker networks to capture margin compression. For Investors and Strategic Acquirers: Capital is best deployed toward regional dedicated contract carriage specialists with established shipper relationships and depot-charging real estate. Long-term viability hinges on electrification readiness and regulatory compliance positioning rather than pure scale. Monitor EPA Phase 3 interim target announcements as the critical inflection signal for accelerated fleet procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Electrification Partnership | Megawatt-scale charging infrastructure secures utility interconnection priority for battery-electric fleet deployment. |
| Dedicated Contract Carriage Expansion | Multi-year shipper agreements embed service level guarantees that insulate revenue from spot market volatility. |
| Driver Retention Program Investment | Wage premiums and guaranteed route assignments counter demographic shifts limiting qualified operator inflows. |
| Refrigerated Vertical Specialization | Temperature-controlled equipment captures rate premiums in California agriculture and Texas foodservice corridors. |
| Intermodal Drayage Network Buildout | Rail-adjacent short haul connects inland ports to distribution centers with modal flexibility on volatile lanes. |
Research Methodology
The analysis maps full truckload, less-than-truckload, intermodal drayage, and dedicated freight segments, each validated through fleet operations directors, shipper procurement managers, and regulatory compliance officers. Primary interviews with EPA and CARB policy specialists, combined with FMCSA enforcement data and carrier equipment procurement disclosures, anchor demand-side validation. Secondary sources include DOT freight flow databases, ATA driver shortage indices, and utility interconnection queue filings. Bottom-up carrier capacity modeling triangulates against top-down shipper spend estimates.
Consistency checks validated volume and value outputs against external benchmarks including DOT freight analysis framework data and carrier-reported revenue per tractor. The analytical framework segments by service type, vehicle configuration, industry vertical, and delivery mode across the projection horizon. CAGRs derive from equipment replacement cycle modeling, regulatory compliance timeline assumptions, and e-commerce fulfillment density projections. Key inputs include EPA Phase 3 compliance cost curves and CARB waiver enforcement patterns.
Underlying assumptions cover regulatory adherence timelines, charging infrastructure deployment rates, and driver supply recovery trajectories, with deviation risk concentrated in EPA rulemaking delays or utility interconnection bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Mexico Customs Brokerage Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Spain Road Freight Transport Market