
 Refrigerated Transport Market | 2026-2036
Refrigerated Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Transport Market Analysis
Electrification of transport refrigeration units is reshaping fleet procurement strategies across the cold-chain industry. Thermo King leverages its battery-electric portfolio to anchor technology leadership in zero-emission trailer refrigeration. Carrier Transicold sustains competitive pressure through deep R&D investment in cryogenic and hybrid systems. Daikin Industries differentiates with compressor efficiency gains that reduce energy draw on electric chassis.
Refrigerated transport encompasses temperature-controlled vehicles, containers, and auxiliary cooling equipment engineered to maintain cargo between -25°C and +25°C through vapor-compression or absorption cycles, with insulation panels typically achieving thermal conductivity below 0.02 W/mK. Its primary purpose is to preserve perishable commodities across the supply chain from production through last-mile delivery. Refrigerated trailers dominate installed base value due to pharmaceutical and fresh-food volume, while electric fuel type categories represent the fastest-expanding segment as fleet operators face emission zone restrictions. Multi-temperature systems command premium positioning by enabling simultaneous transport of frozen and chilled goods within a single vehicle, reducing trip frequency for logistics providers serving retail chains.
The US EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency rules are tightening compliance costs for diesel-powered refrigerated fleets, while Europe's F-Gas Regulation and EU Green Deal carbon-border adjustments push operators toward electric and cryogenic alternatives. India's BIS energy-efficiency labeling for transport refrigeration and the country's PLI scheme for electric vehicle manufacturing are creating localized supply-chain incentives for domestic fleet conversion. Stakeholders must weigh total-cost-of-ownership timelines against regulatory compliance deadlines as subsidy structures and emission-zone expansions redefine competitive economics.
Market Dynamics
Fleet electrification is compressing diesel-equipment residual values while simultaneously fragmenting supplier power across battery-electric, cryogenic, and hybrid architectures. Operators now face parallel compliance deadlines from EPA Phase 3 standards and Europe's F-Gas Regulation, forcing simultaneous technology transitions rather than sequential upgrades.
Growth Catalysts
- EU Green Deal carbon-border adjustments:German pharmaceutical distributors are accelerating trailer procurement to lock in zero-emission compliance before 2030 phase-in deadlines.
- mRNA vaccine cold-chain protocols:Biologics manufacturers require validated -70°C transport corridors, expanding demand for cryogenic systems and multi-temperature trailers.
- India's PLI scheme for electric vehicles:Domestic fleet conversion subsidies are building localized refrigerated chassis assembly capacity for South Asian food exporters.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack costs for electric transport refrigeration units remain tethered to Chinese cathode processing capacity, exposing fleet operators to raw material volatility.
- F-Gas refrigerant phase-down schedules:Europe's quota system is compressing hydrofluorocarbon availability before cost-competitive natural refrigerant alternatives achieve scale deployment.
- Electric chassis payload penalties:Battery weight on heavy-duty platforms reduces net cargo capacity by 8-12% versus diesel equivalents, eroding per-trip economics for bulk food haulers.
Strategic Opportunities
- Brazil's ANVISA temperature-mapping mandates:Latin American pharmaceutical distribution is opening to validated cold-chain infrastructure as regulatory enforcement tightens.
- Last-mile frozen grocery delivery:Urban consolidation centers are creating demand for compact electric refrigerated vans serving 15-minute delivery windows.
- Telematics-integration premiums:Real-time cargo monitoring is enabling outcome-based service contracts that monetize temperature assurance rather than equipment uptime alone.
Industry Challenges
- Dual-credential technician scarcity:Fleet maintenance requires simultaneous HVAC certification and high-voltage electrical training, constraining service network expansion.
- Retrofit integration complexity:Legacy diesel trailers demand structural reinforcement and wiring harness replacement to accommodate electric refrigeration units, extending downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Transport Market |
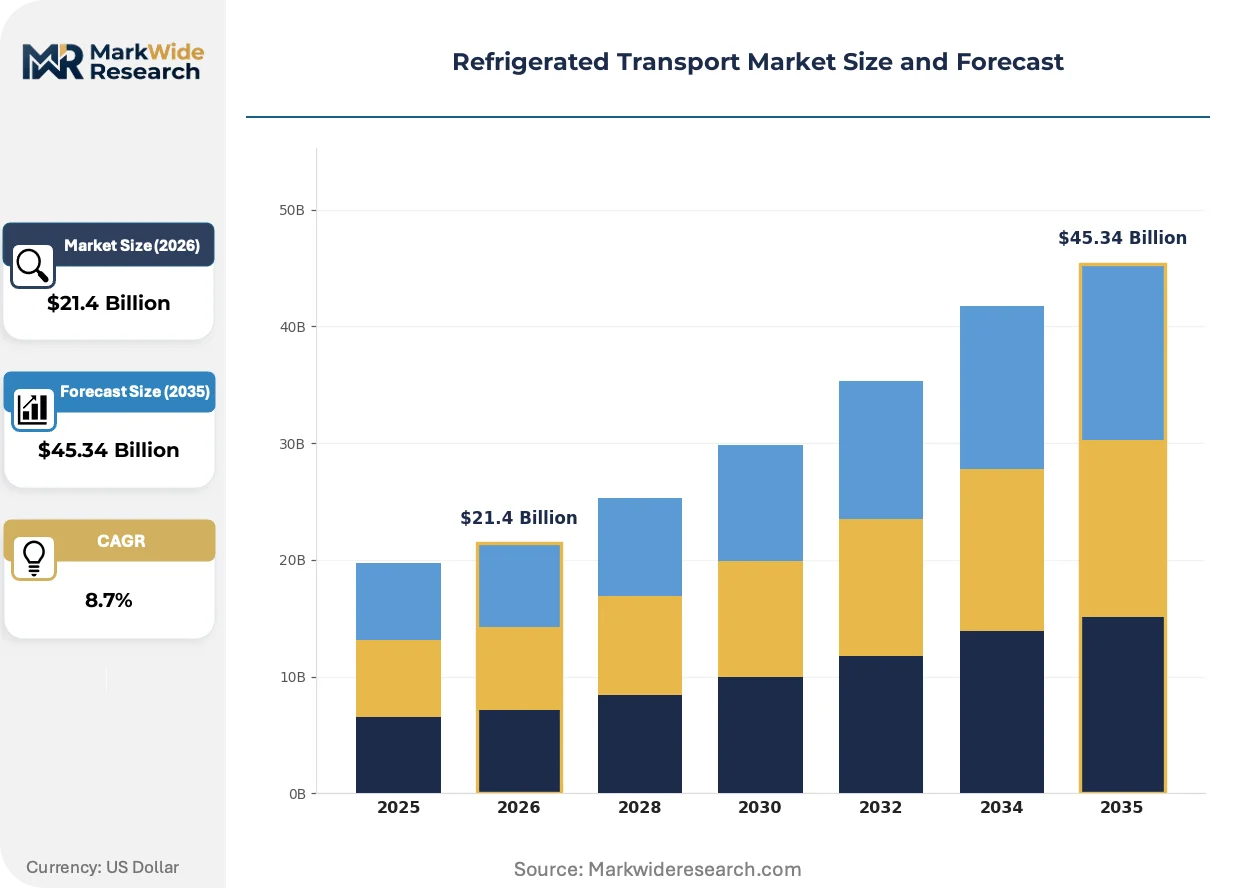
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $45.34 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Trucks, Refrigerated Trailers, Refrigerated Containers, Refrigerated Vans End User: Food & Beverage Industry, Pharmaceutical Companies, Retail Chains, Logistics Providers Temperature Control Type: Active Systems, Passive Systems, Multi-Temperature Systems, Single-Temperature Systems Fuel Type: Diesel, Electric, Hybrid, LNG |
| Companies Covered | Thermo King, Carrier Transicold, Daikin Industries, Schmitz Cargobull, Wabash National, Great Dane, Hyundai Translead, C.H. Robinson Worldwide, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Transport Market Emerging Trajectories
Digital twin architectures are virtualizing fleet management workflows, compressing the feedback loop between field performance and engineering iteration. This shift is redrawing competitive boundaries between equipment OEMs and software-native service providers.
Thermal energy storage using phase-change materials is virtualizing the conventional refrigeration cycle. Pharmaceutical logistics providers in the Netherlands are piloting eutectic plate systems that eliminate compressor runtime during transit. This architecture is virtualizing the traditional split between mobile and stationary cold storage, enabling trailers to function as autonomous temperature-buffered nodes.
The US EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency rules are tightening compliance costs for diesel-powered refrigerated fleets. California's Advanced Clean Trucks regulation is accelerating zero-emission chassis deployment ahead of federal timelines. Food distributors operating cross-border routes through the Midwest are dual-certifying equipment to satisfy both state and federal inspection protocols.
Consolidated procurement through third-party logistics platforms is compressing manufacturer-direct sales cycles. Large retail chains are unbundling equipment specification from maintenance contracts, forcing refrigeration unit suppliers to compete on standalone technology merit. This pattern is most pronounced in Germany, where centralized fleet management by discount grocery operators has eroded traditional distributor relationships.
Refrigerated Transport Market Segmentation
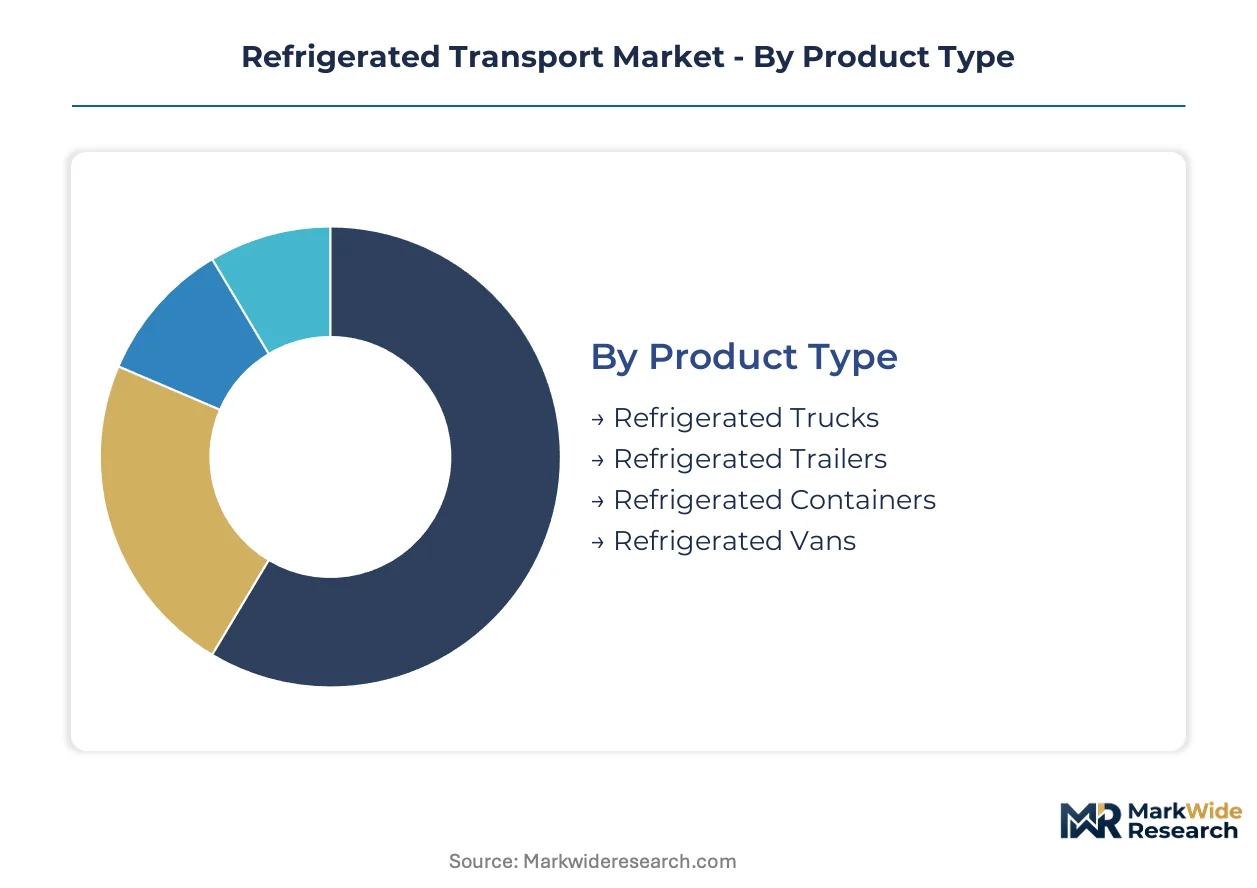
Refrigerated transport segmentation reflects divergent equipment economics across payload scales and regulatory compliance horizons. Fleet operators configure procurement around cargo volume, temperature protocol stringency, and emission-zone access requirements.
Product Type:
Use-case spectrum spans urban last-mile vans through intercontinental container fleets, with chassis architecture determining insulation specifications and refrigeration unit mounting configurations.
- Refrigerated Trailers:Insulated semi-trailers with integrated vapor-compression units dominate pharmaceutical distribution corridors and fresh-food long-haul routes. German discount grocery operators and Dutch flower exporters drive procurement concentration for 13.6-meter curtain-sided variants with multi-zone partitioning.
- Refrigerated Trucks:Rigid chassis with factory-installed cold bodies serve urban foodservice distribution and regional dairy collection. Indian dairy cooperatives and Brazilian protein processors favor medium-duty configurations for farm-to-plant collection networks.
- Refrigerated Containers:Intermodal units with clip-on gensets enable ocean-rail-truck transshipment of frozen commodities. Reefer container demand clusters at Rotterdam and Singapore transshipment hubs serving South American fruit exporters.
- Refrigerated Vans:Compact urban delivery vehicles with direct-drive electric refrigeration address 15-minute grocery delivery windows. European city-center emission zones are accelerating battery-electric van adoption for last-mile frozen distribution.
Established volume favors refrigerated trailers; emerging adoption favors refrigerated vans.
End User:
Customer procurement maturity varies from specification-heavy pharmaceutical validation protocols to price-sensitive foodservice logistics.
- Pharmaceutical Companies:Validated cold-chain compliance for biologics and vaccines demands temperature-mapping documentation and redundant cooling architecture. mRNA manufacturers require -70°C cryogenic transport corridors with real-time telemetry integration.
- Food & Beverage Industry:Processors and distributors prioritize payload optimization and fuel efficiency over precision telemetry. Dairy and seafood exporters in India and Vietnam drive demand for cost-optimized single-temperature configurations.
- Logistics Providers:Third-party cold-chain operators unbundle equipment ownership from transport services, creating demand for leased assets with outcome-based maintenance contracts.
- Retail Chains:Centralized fleet management by discount grocery operators in Germany and France compresses manufacturer margins through consolidated procurement tenders.
Pharmaceutical validation commands premium pricing tiers; food and beverage procurement dominates unit volume.
Temperature Control Type:
System architecture determines energy draw, maintenance intervals, and cargo flexibility across frozen-to-chilled spectrum.
- Multi-Temperature Systems:Partitioned compartments with independent evaporator circuits enable simultaneous transport of frozen and chilled goods. Retail distribution networks serving mixed-format stores favor these configurations to reduce trip frequency.
- Active Systems:Engine-driven or electric vapor-compression refrigeration maintains precise setpoints through variable-speed compressors. These systems dominate pharmaceutical and premium fresh-produce corridors requiring tight temperature bands.
- Single-Temperature Systems:Simplified architecture with fixed evaporator capacity serves bulk commodity transport where cargo homogeneity permits. Frozen protein exporters in Brazil and Argentina favor these for cost-optimized ocean-rail legs.
- Passive Systems:Phase-change materials and eutectic plates store thermal energy during stationary charging, eliminating compressor runtime during transit. Dutch pharmaceutical pilots are validating these for zero-emission urban distribution.
Active systems anchor current fleet composition; passive architectures are climbing the fastest in emission-restricted zones.
Fuel Type:
Propulsion choice increasingly determines market access rather than operating cost alone, with regulatory geography dictating technology selection.
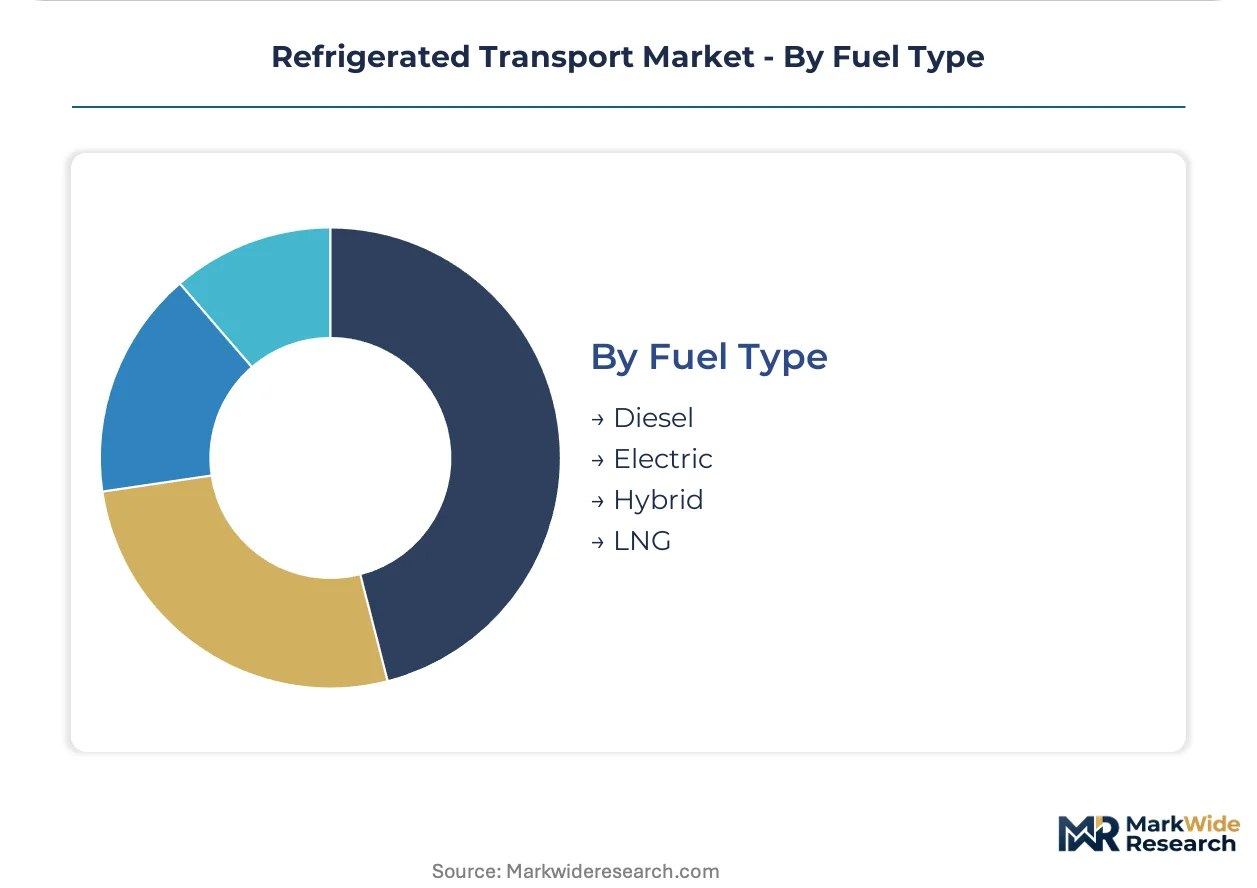
- Electric:Battery-electric chassis with integrated refrigeration face payload penalties but gain zero-emission zone access. California's Advanced Clean Trucks regulation and EU urban access restrictions are accelerating deployment ahead of total-cost parity.
- Diesel:Compression-ignition engines with mechanical or electric refrigeration units retain residual value pressure from EPA Phase 3 compliance costs and European F-Gas phase-down schedules. Long-haul operators in less regulated markets continue diesel procurement.
- Hybrid:Dual-mode architectures combine diesel range extension with electric refrigeration for urban emission zones. These configurations bridge compliance timelines for operators serving mixed geographies.
- LNG:Liquefied natural gas offers particulate reduction for heavy-duty corridors without full electrification infrastructure. Spanish and Italian haulers on trans-Alpine routes favor LNG for tunnel access compliance.
Diesel retains installed-base dominance; electric configurations are gaining share fastest in regulated urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in refrigerated trailer exports to neighboring EU states, while the United States absorbs Mexican produce imports through California and Texas border corridors. India's pharmaceutical cold-chain infrastructure is scaling to capture re-export traffic from Southeast Asian biologics manufacturers.
United States
California's Central Valley vegetable processors and Texas meatpackers drive trailer procurement for cross-border routes to Mexico. EPA Phase 3 standards and California's Advanced Clean Trucks regulation are compressing diesel fleet residual values. The Midwest corridor through Chicago and Indianapolis anchors intermodal reefer container transfers between rail and trucking networks.
Germany
Discount grocery operators in North Rhine-Westphalia and pharmaceutical distributors in Hesse concentrate refrigerated trailer demand for EU-wide distribution. The F-Gas Regulation and EU Green Deal carbon-border adjustments are accelerating electric chassis procurement ahead of 2030 deadlines. The Port of Rotterdam hinterland connection through the Ruhr region handles temperature-controlled transshipment for Dutch flower and Belgian chocolate exporters.
India
Dairy cooperatives in Gujarat and protein processors in Maharashtra favor medium-duty refrigerated trucks for farm-to-plant collection networks. BIS energy-efficiency labeling and the PLI scheme for electric vehicle manufacturing are creating localized chassis assembly incentives. The Delhi-Mumbai Industrial Corridor is emerging as a cold-chain consolidation zone for pharmaceutical exports to Africa and the Middle East.
Brazil
Frozen protein exporters in São Paulo state and fruit growers in Minas Gerais drive demand for cost-optimized single-temperature configurations. ANVISA temperature-mapping mandates are tightening validation requirements for pharmaceutical distribution infrastructure. The Santos port cluster is expanding reefer container capacity for soybean and poultry exports to China.
Netherlands
Flower auction houses in Aalsmeer and pharmaceutical logistics providers in Rotterdam pilot phase-change material systems for zero-emission urban distribution. The EU Green Deal urban access restrictions are accelerating battery-electric van deployment for last-mile frozen grocery delivery. The Rotterdam-Singapore transshipment corridor anchors intermodal reefer demand for South American fruit exporters.
Refrigerated Transport Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability clusters. Integrated transport refrigeration unit manufacturers with captive compressor technology compete against trailer fabricators sourcing modular cooling systems. Specialized telematics providers are inserting themselves between equipment vendors and fleet operators through outcome-based service contracts. Strategic moves center on battery-electric portfolio expansion and backward integration into thermal insulation panel production.
Within the integrated systems tier, Thermo King and Carrier Transicold occupy positions defined by their battery-electric and cryogenic technology portfolios. Among trailer fabricators with refrigeration partnerships, Schmitz Cargobull and Wabash National exemplify regional production archetypes serving European and North American fleet specifications respectively. These named entities represent strategic positioning around electrification compliance rather than commodity equipment supply.
| Leading Market Players |
|---|
| Thermo King |
| Carrier Transicold |
| Daikin Industries |
| Schmitz Cargobull |
| Wabash National |
| Great Dane |
| Hyundai Translead |
| C.H. Robinson Worldwide |
| DB Schenker |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cell supply concentration in Chinese cathode processing determines both three-tier pricing spreads across premium-electric, standard-hybrid, and economy-diesel configurations and the geographic shape of refrigerated chassis assembly networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume scale and certification tier as primary price differentiation drivers. Cost compression in economy-diesel segments intensifies because EPA Phase 3 compliance erodes residual values, while pharmaceutical fleet operators show least price sensitivity due to validation requirements. Foodservice logistics providers exhibit highest price sensitivity, prioritizing payload optimization over precision telemetry.
Supply Chain Analysis
Export controls on high-voltage electrical components and battery management systems limit technology flows from China, South Korea, and Japan. Compressor manufacturing draws from rare earth magnet supply anchored in Chinese processing capacity, with thermal insulation panel production resting on European and North American petrochemical feedstock. Single-source vulnerability in cathode active material creates procurement risk. Distribution runs through third-party logistics platforms consolidating manufacturer-direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Passive thermal systems using phase-change materials threaten active vapor-compression incumbents by eliminating compressor runtime and enabling zero-emission urban access without battery payload penalties.
For Market Incumbents: Pre-empt substitution threats by backward integration into thermal insulation panel production and captive compressor technology development. Anchor technology leadership in battery-electric portfolios before F-Gas Regulation phase-down compresses hydrofluorocarbon availability. Defend service network density through dual-credential technician training programs addressing HVAC and high-voltage electrical certification scarcity.
For New Entrants and Emerging Players: Southeast Asian pharmaceutical re-export corridors offer underpenetrated white-space for validated cold-chain infrastructure serving African and Middle Eastern markets. Target last-mile frozen grocery delivery in European city-center emission zones with compact electric refrigerated van configurations. Pursue telematics-native positioning enabling outcome-based service contracts monetizing temperature assurance rather than equipment uptime alone.
For Investors and Strategic Acquirers: EU Green Deal carbon-border adjustments reshape the acquisition landscape by accelerating electric chassis procurement ahead of compliance deadlines. Five-to-ten-year viability favors integrated transport refrigeration unit manufacturers with captive battery-electric portfolios over trailer fabricators sourcing modular cooling systems. Monitor ANVISA enforcement patterns in Brazil as signal for Latin American pharmaceutical distribution infrastructure buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Portfolio Expansion | Thermo King and Carrier Transicold anchor zero-emission technology leadership in trailer refrigeration. |
| Backward Integration into Thermal Insulation | Schmitz Cargobull and Wabash National secure captive supply of high-performance panel materials. |
| Telematics Platform Integration | Real-time cargo monitoring enables outcome-based contracts monetizing temperature assurance. |
| Dual-Credential Technician Training | Service network expansion addresses HVAC and high-voltage electrical certification scarcity. |
| Phase-Change Material Pilot Deployment | Dutch pharmaceutical logistics validate passive systems for zero-emission urban distribution. |
Methodological Framework
A standing panel of fleet operations directors, cold-chain logistics procurement managers, transport refrigeration unit engineering leads, and aftermarket service heads provided ongoing calibration across primary interviews. Secondary validation drew from EPA Phase 3 regulatory filings, EU F-Gas Regulation quota tracking, BIS energy-efficiency labeling databases, and refrigerated trailer production records. Bottom-up equipment shipment analysis triangulated against top-down fleet operator capital expenditure surveys.
Scenario-bracketing framed projections across the analysis window, modeling fuel type transition curves, temperature control architecture shifts, and end-user procurement maturity. Segmentation dimensions spanned product type, end-user industry, temperature control protocol, and fuel propulsion architecture. CAGRs derived from equipment replacement cycles, regulatory compliance deadlines, and fleet electrification adoption curves informed volume and value outputs.
Practitioners should monitor lithium-ion cell supply disruption, F-Gas refrigerant quota compression, and emission-zone expansion schedules for early signals requiring forecast revision. Material shifts in battery chemistry cost curves or natural refrigerant scale deployment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
US Tolling Market
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Inland Water Freight Transport Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Mexico Cold Chain Logistics Market