
 Europe Fleet Management Market | 2026-2036
Europe Fleet Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fleet Management Market Foresight
A shortage of data engineers with embedded systems expertise is rotating fleet operators toward vendor-managed SaaS platforms rather than in-house telematics stacks. Arval leverages its leasing network to bundle fleet analytics with vehicle financing across France and Italy. Targa Telematics anchors southern European markets through specialized compliance management tools aligned with EU emission standards. Trimble competes on precision agriculture and construction fleet extensions, occupying niches where GPS tracking accuracy determines equipment utilization rates.
Europe fleet management encompasses the integrated hardware, software, and service systems that monitor, coordinate, and optimize commercial vehicle operations through real-time data transmission, typically via cellular or satellite networks with positioning accuracy within three meters. These systems process engine diagnostics, driver behavior metrics, and geospatial coordinates to reduce fuel consumption, enforce regulatory compliance, and extend asset lifecycles. Cloud-based deployment now leads solution architecture as operators abandon server maintenance burdens, while telematics hardware sustains margin pools through recurring connectivity fees and firmware upgrade cycles. Fuel management services grow fastest among service types as diesel price volatility and EU carbon border adjustments intensify cost scrutiny across logistics companies and transport services.
The EU Green Deal, GDPR data governance requirements, and the F-Gas Regulation for mobile air conditioning systems collectively reshape fleet technology procurement, with the European Commission's CO2 standards for heavy-duty vehicles directly mandating telematics-enabled emission monitoring. EMA guidelines on driver working hours and the CE marking framework for automotive electronics further tighten product certification requirements for solution vendors. Fleet operators and technology providers must monitor the interplay between national tolling system interoperability mandates and emerging battery-electric vehicle range verification protocols as electrification timelines compress.
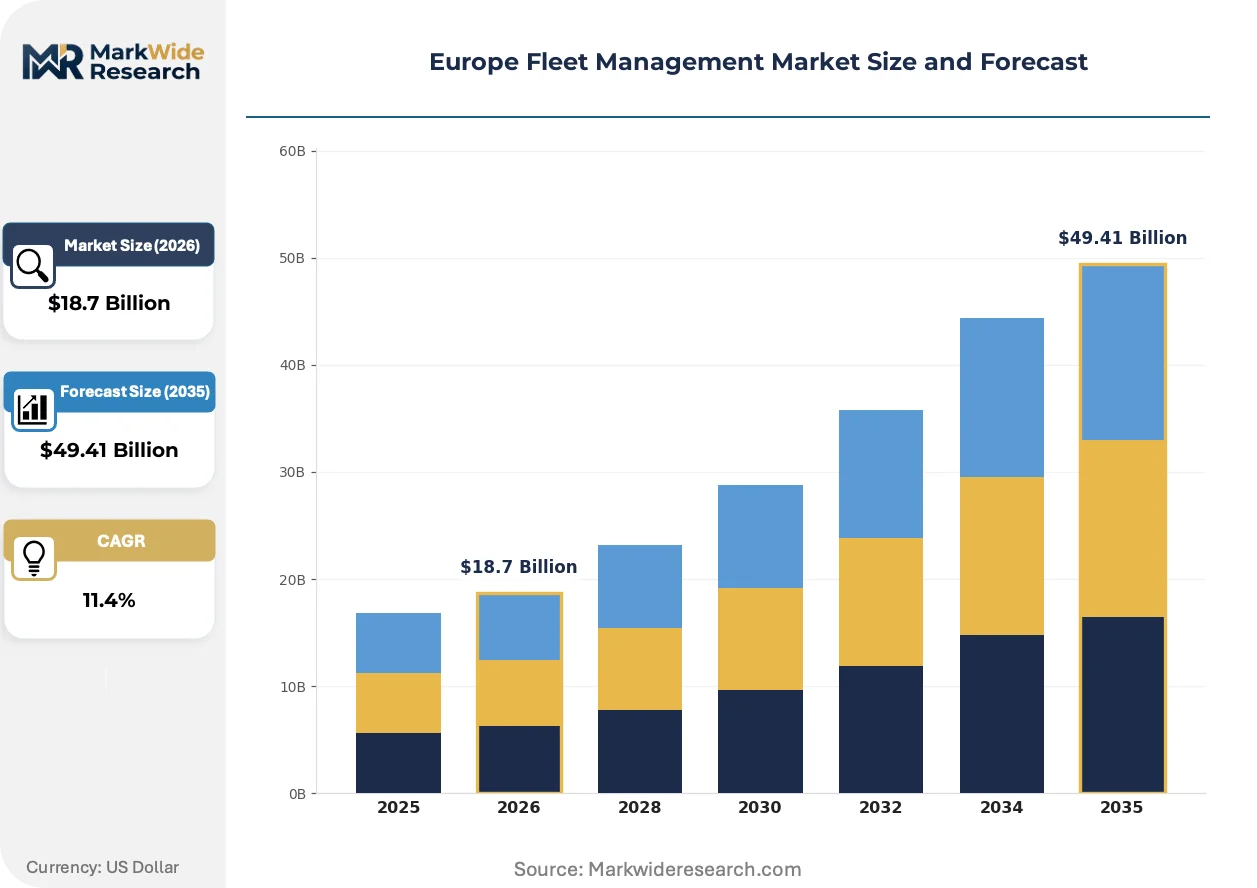
Market Dynamics
Cloud-based telematics platforms are consolidating fleet operator technology stacks as diesel price volatility and EU carbon border adjustments intensify cost scrutiny across logistics corridors. The shift from on-premise servers to vendor-managed SaaS architectures represents the dominant structural force reshaping procurement patterns and competitive positioning.
Growth Catalysts
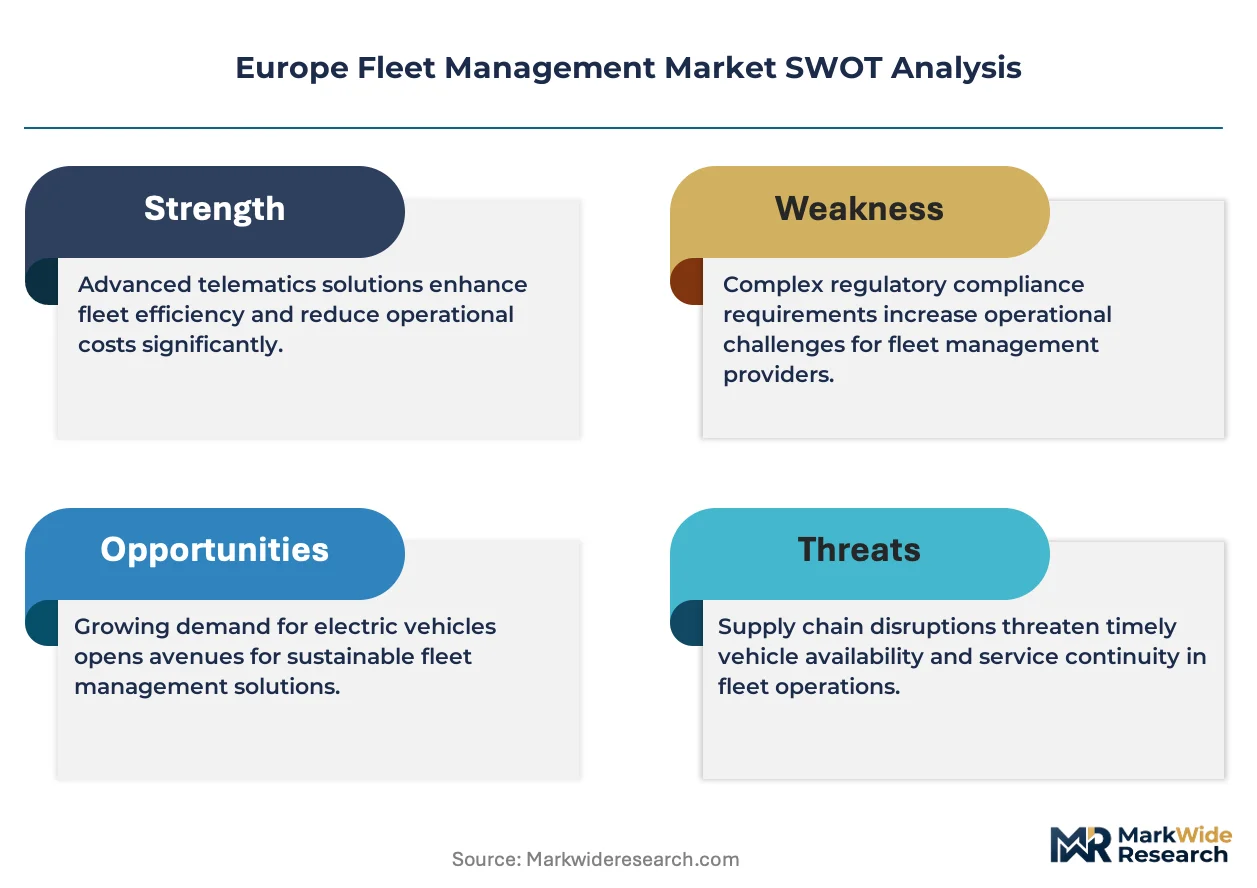
- EU Green Deal emission mandates:Heavy-duty vehicle CO2 standards compel fleet operators to integrate telematics-enabled carbon reporting. Transport services across Germany and France accelerate compliance investments.
- Cloud architecture migration:Logistics companies abandon server maintenance burdens for cellular-connected platforms. Real-time engine diagnostics and geospatial coordination now process through centralized vendor infrastructure.
- Dense commercial corridors:Route optimization deployments concentrate in Germany's logistics networks. Fleet density enables rapid payback periods for GPS-accurate positioning systems.
Market Restraints
- Data engineering talent scarcity:Embedded systems expertise shortages rotate operators toward bundled vendor solutions. In-house telematics development becomes structurally uneconomical.
- Connectivity hardware margins:Recurring firmware upgrade cycles and cellular fee structures lock operators into long-term vendor relationships with limited substitution options.
- GDPR governance friction:Driver behavior metrics and geospatial data collection trigger stringent consent and retention requirements. Compliance costs escalate for cross-border fleet operations.
Strategic Opportunities
- Battery-electric range verification:Electrification timelines compress demand for telematics protocols validating commercial EV performance. Southern European markets lack specialized compliance tools.
- Fuel management service expansion:Diesel price volatility intensifies cost scrutiny. Analytics platforms monetizing consumption optimization represent underpenetrated white space.
- Tolling system interoperability:National mandates across Italy and Spain create integration opportunities for unified trans-European fleet coordination platforms.
Industry Challenges
- F-Gas Regulation compliance:Mobile air conditioning system monitoring requires specialized sensor integration. CE marking frameworks for automotive electronics extend product certification timelines.
- EMA working hours enforcement:Driver behavior metrics must align with cross-border labor regulations. Telematics vendors face fragmented national implementation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fleet Management Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Service Type: Fuel Management, Vehicle Tracking, Maintenance Scheduling, Compliance Management End User: Logistics Companies, Transport Services, Government Fleets, Construction Firms Solution: GPS Tracking, Telematics, Fleet Analytics, Route Optimization |
| Companies Covered | Arval, Omnitracs, Targa Telematics, Vimcar, Donlen, Verizon, ARI, Wunder Mobility, Trimble, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fleet Management Market Shifts & Advancements
Cellular-based telematics architectures are actively displacing satellite-dependent systems as fleet operators prioritize cost-efficient connectivity over remote-area coverage. The convergence of emission compliance mandates and cloud infrastructure economics is compressing technology refresh cycles across European logistics networks.
Edge computing modules embedded within vehicle OBD-II ports are supplanting centralized black-box telematics units. Logistics operators in Germany's Rhine-Ruhr corridor adopt these distributed processors for sub-second engine diagnostic alerts. The technology is supplanting legacy hub-and-spoke data architectures that bottlenecked real-time fuel consumption analytics during peak routing periods.
The EU AI Act's risk classification framework now governs automated driver scoring algorithms deployed across commercial fleets. Predictive maintenance systems using machine learning face heightened transparency requirements for algorithmic decision-making. Heavy-duty vehicle segments operating across German and French cross-border routes invest most heavily in explainable AI documentation to satisfy emerging liability standards.
Leasing-procurement bundling now dominates fleet technology acquisition as operators seek to convert capital expenditure into operational expenditure. Vehicle finance providers embed telematics subscriptions within monthly lease payments, displacing standalone software contracts. This shift concentrates most visibly among Italian transport services where credit access constraints favor all-inclusive mobility service agreements over fragmented vendor relationships.
Europe Fleet Management Market Segmentation
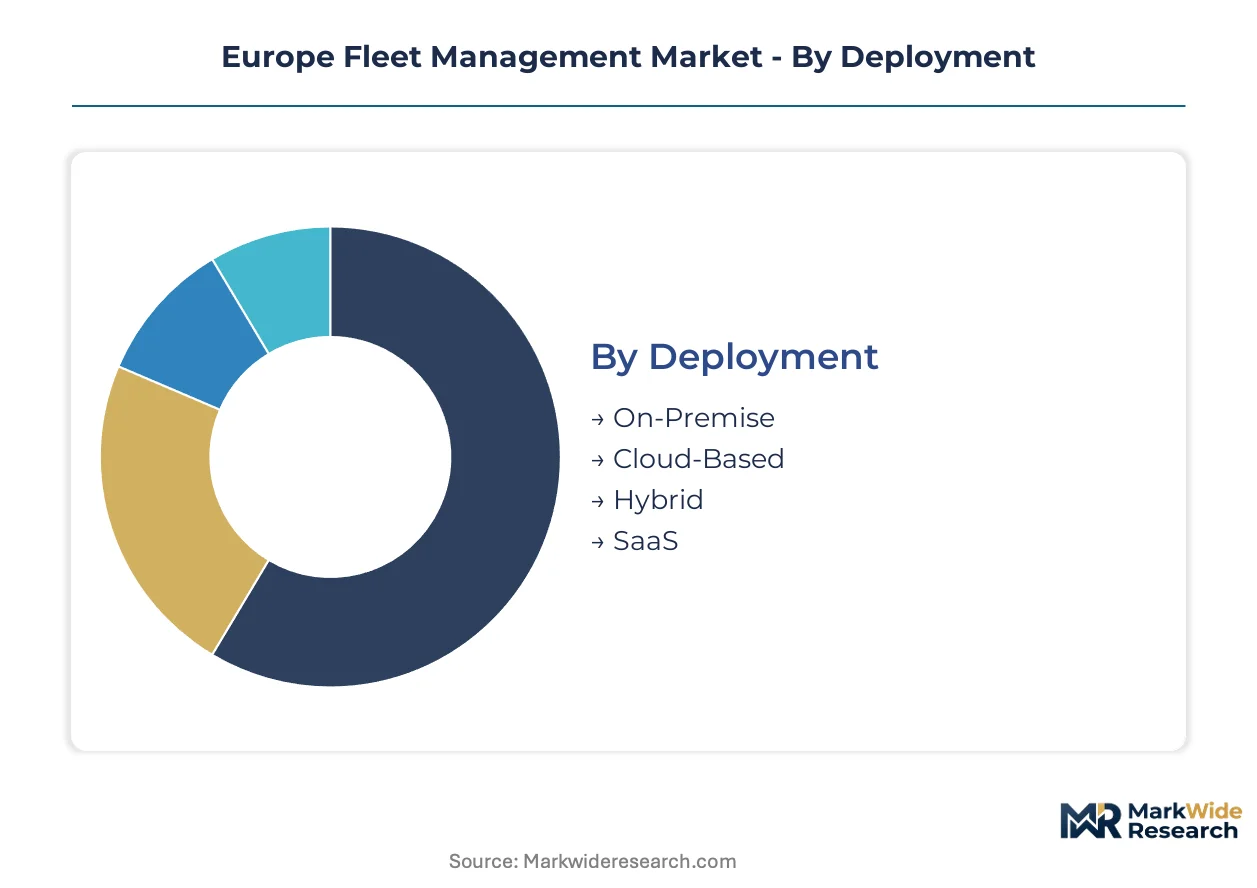
European fleet operators structure procurement around deployment economics, service criticality, and regulatory exposure. Segmentation reveals where cloud migration concentrates and which compliance tools command premium positioning across Germany, France, and Italy.
Deployment:
Channel mix varies sharply by operator IT maturity, with vendor-managed platforms displacing self-hosted infrastructure among mid-market logistics providers.
- Cloud-Based:Cellular-connected architectures process engine diagnostics and geospatial coordination through centralized vendor infrastructure. German logistics corridors favor these platforms for real-time route recalculation during Rhine-Ruhr peak congestion.
- SaaS:Subscription models bundle telematics subscriptions within monthly lease payments, converting capital expenditure to operational expenditure. Italian transport services adopt these most aggressively where credit access constraints favor all-inclusive mobility agreements.
- Hybrid:Split architectures retain sensitive driver data on local servers while pushing anonymized fleet analytics to cloud processors.
- On-Premise:Legacy server installations persist among defense and government fleets with stringent data sovereignty requirements.
By volume, Cloud-Based leads. By growth pace, SaaS is climbing the fastest as leasing-procurement bundling accelerates across southern Europe.
Service Type:
Cost tier stratification separates commodity tracking from high-margin compliance services shaped by EU Green Deal mandates.
- Fuel Management:Analytics platforms monetizing diesel consumption optimization face intensifying demand as EU carbon border adjustments tighten cost scrutiny. French haulage operators deploy these tools most densely along Atlantic freight corridors.
- Compliance Management:Specialized tools aligned with EU emission standards and EMA working hours enforcement command premium pricing. Southern European markets show underpenetration relative to German adoption rates.
- Vehicle Tracking:GPS-accurate positioning systems within three-meter precision dominate baseline service procurement.
- Maintenance Scheduling:Predictive algorithms using edge-computing OBD-II modules reduce unplanned downtime for construction equipment fleets.
By revenue concentration, Fuel Management leads. By margin expansion, Compliance Management is gaining share fastest as certification requirements tighten.
End User:
Application intensity varies by asset utilization rates and regulatory touchpoints across commercial vehicle categories.
- Logistics Companies:Dense fleet networks across Germany's commercial corridors generate rapid payback periods for route optimization investments. These operators drive cloud architecture adoption most aggressively.
- Transport Services:Cross-border haulage facing fragmented national tolling mandates prioritizes interoperability features. French and Spanish operators concentrate demand for unified trans-European coordination platforms.
- Construction Firms:Equipment utilization tracking depends on GPS accuracy for high-value mobile assets in dispersed project sites.
- Government Fleets:Procurement cycles favor established vendors with CE marking compliance and established GDPR governance frameworks.
By deployment scale, Logistics Companies lead. By technology refresh velocity, Transport Services are expanding most quickly as electrification timelines compress.
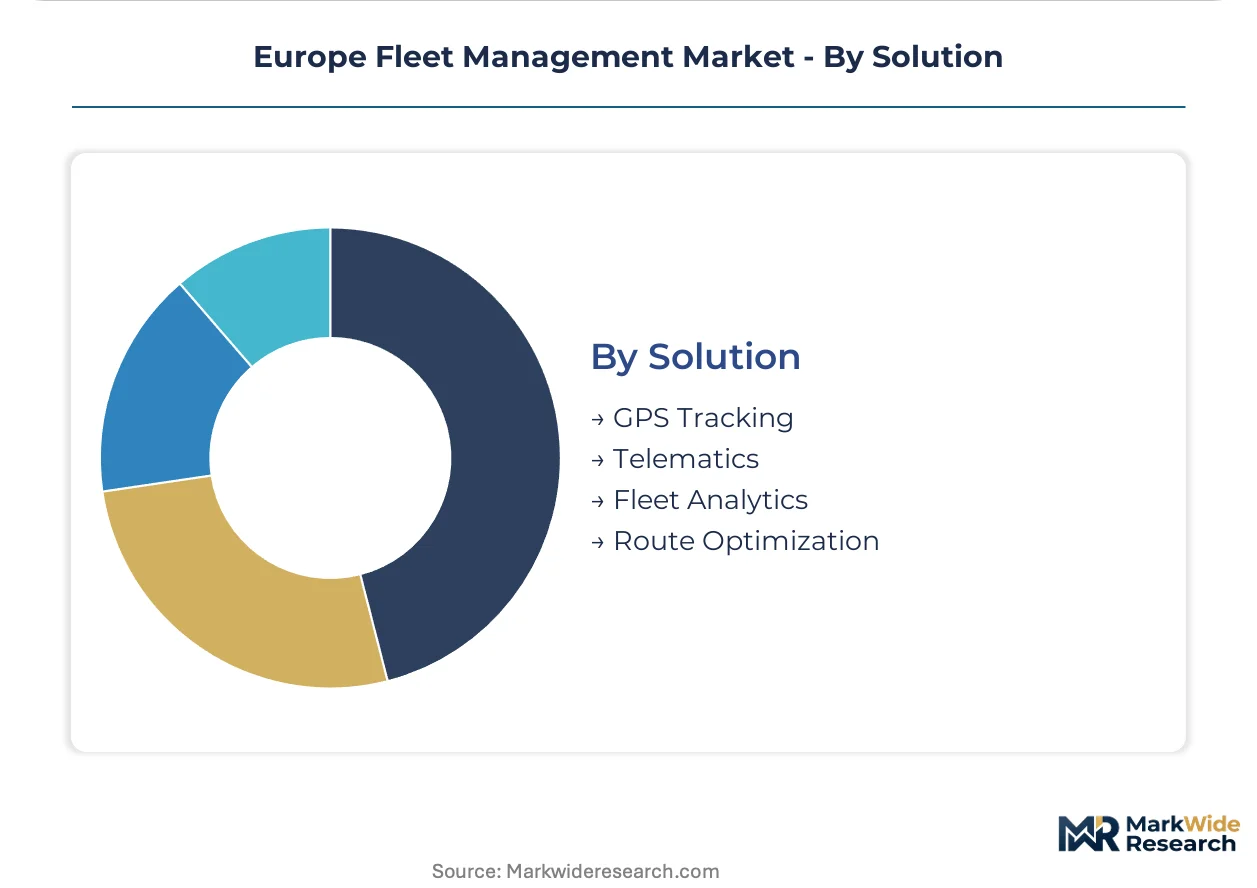
Solution:
Customer type segmentation separates integrated platform buyers from point-solution purchasers seeking modular expansion paths.
- Telematics:Integrated hardware-software systems combining engine diagnostics, driver behavior metrics, and connectivity modules form the core technology stack. GDPR consent frameworks and F-Gas Regulation sensor requirements shape vendor selection criteria.
- Fleet Analytics:Cloud-based processing layers transforming raw vehicle data into operational KPIs attract operators abandoning in-house data engineering. Talent scarcity rotates procurement toward vendor-managed analytics stacks.
- GPS Tracking:Positioning accuracy within three meters remains table stakes for commercial vehicle monitoring.
- Route Optimization:Algorithmic dispatch tools processing real-time traffic and delivery constraints concentrate demand in high-density logistics networks.
By installed base, Telematics leads. By substitution momentum, Fleet Analytics is climbing the fastest as embedded systems expertise shortages deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators command pricing premiums for compliance-integrated telematics suites while Italian transport services face margin compression from fragmented vendor relationships and credit access constraints.
Germany
Dense commercial corridors along the Rhine-Ruhr and Frankfurt logistics networks generate rapid payback periods for route optimization investments. The EU Green Deal's heavy-duty vehicle CO2 standards compel fleet operators to integrate telematics-enabled carbon reporting through KBA certification frameworks. Bavarian automotive clusters and North Rhine-Westphalia freight hubs concentrate demand for GPS-accurate positioning systems within three-meter precision.
France
Cross-border haulage operators prioritize interoperability features for fragmented national tolling mandates across Atlantic freight corridors. EMA guidelines on driver working hours enforcement shape telematics procurement specifications for transport services. Île-de-France logistics networks and Auvergne-Rhône-Alpes manufacturing belts anchor adoption of cloud-based fuel management analytics.
Italy
Credit access constraints rotate transport services toward all-inclusive mobility service agreements over fragmented vendor relationships. CE marking frameworks for automotive electronics extend product certification timelines for telematics hardware. Lombardy freight networks and Emilia-Romagna logistics clusters concentrate leasing-procurement bundling as operators convert capital expenditure to operational expenditure.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for cross-border fleet operations serving EU logistics corridors. GDPR data governance requirements and emerging AI Act transparency mandates reshape vendor selection criteria for automated driver scoring systems. London-Southeast logistics networks and Midlands manufacturing hubs drive demand for edge-computing OBD-II modules processing sub-second engine diagnostics.
Spain
National tolling system interoperability mandates create integration opportunities for unified trans-European fleet coordination platforms. F-Gas Regulation compliance for mobile air conditioning systems requires specialized sensor integration extending procurement cycles. Madrid logistics networks and Catalonia freight corridors concentrate demand for battery-electric range verification protocols as electrification timelines compress.
Europe Fleet Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European fleet management sector. Leasing-integrated platforms and specialized compliance vendors occupy distinct competitive tiers while standalone telematics providers face margin pressure from bundled service offerings. Three strategic archetypes dominate: vehicle finance bundlers, regulatory compliance specialists, and precision agriculture niche players. M&A activity concentrates on SaaS platform consolidation while strategic partnerships target tolling system interoperability across national borders.
Within the leasing-integrated tier, Arval anchors positioning through vehicle finance bundling across France and Italy. Targa Telematics occupies the regulatory compliance specialist archetype with southern European market focus. Trimble exemplifies the precision agriculture and construction niche where GPS tracking accuracy determines equipment utilization rates. These three players represent how geographic specialization and service bundling create defensible market positions against generalized telematics providers.
| Leading Market Players |
|---|
| Arval |
| Omnitracs |
| Targa Telematics |
| Vimcar |
| Donlen |
| Verizon |
| ARI |
| Wunder Mobility |
| Trimble |
| Others |
Supply & Pricing Matrix
Cellular connectivity modules displacing satellite-dependent hardware are redrawing component sourcing maps from Nordic semiconductor clusters toward Asian cellular chipset manufacturing centers while compressing connectivity service pricing across German logistics corridors.
Pricing Analysis
German fleet operators pay premiums of 15-25% above Italian transport services for identical telematics suites due to KBA certification requirements and GDPR governance overhead. Pricing stratifies across premium compliance-integrated tiers, standard connectivity bundles, and economy hardware-only configurations. Cost compression in the economy tier is intensifying because Chinese OBD-II module manufacturers are flooding southern European markets with unbundled hardware. Mid-market logistics companies in France exhibit the sharpest price sensitivity, while defense and government fleets in Germany accept premium positioning for data sovereignty guarantees.
Supply Chain Analysis
Taiwan and South Korea anchor cellular chipset fabrication for European telematics hardware, while Germany and the Czech Republic concentrate final assembly and firmware integration facilities. Supply chains draw from Taiwanese semiconductor foundries, Korean memory module producers, and Chinese GPS sensor manufacturers. Single-source vulnerability concentrates in cellular baseband processors where Qualcomm and MediaTek dominate design licensing. Distribution runs through Tier 1 automotive suppliers and vehicle finance bundlers rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires incumbents to defend against software-defined vehicle platforms that embed native fleet management capabilities, eroding standalone telematics value propositions.
For Market Incumbents: Secure exclusive leasing-procurement bundling relationships with Arval-scale vehicle finance providers before OEMs internalize telemetry stacks. Deepen backward integration into edge-computing OBD-II module design to escape commoditized hardware margins. The EU AI Act's explainable AI mandates threaten algorithmic maintenance products lacking documentation infrastructure. For New Entrants and Emerging Players: CE marking fast-tracks for F-Gas Regulation-compliant sensor integration unlock southern European transport services where Targa Telematics lacks density. Battery-electric range verification protocols represent the most penetrable white space as Spanish and Italian electrification timelines compress ahead of compliance tool availability. Partner with national tolling system operators for interoperability certification rather than building standalone integration layers. For Investors and Strategic Acquirers: Capital is best deployed toward SaaS-native platforms with embedded GDPR consent automation and existing KBA certification pathways. Long-term viability hinges on cloud architecture economics displacing on-premise installations across mid-market logistics. Watch for EU carbon border adjustment enforcement intensity as the inflection signal for fuel management service monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Leasing-Procurement Bundling | Arval's vehicle finance integration demonstrates how credit access constraints rotate Italian transport services toward all-inclusive mobility agreements. |
| CE Marking Fast-Track Investment | Compressed certification timelines for F-Gas Regulation sensors enable first-mover positioning in Spanish mobile air conditioning compliance monitoring. |
| Cloud Architecture Migration | German logistics corridors abandoning server maintenance burdens validate vendor-managed SaaS economics across dense commercial networks. |
| Battery-Electric Range Verification Protocol Development | Southern European electrification compression creates white space for telematics platforms validating commercial EV performance ahead of OEM native solutions. |
| Tolling System Interoperability Partnership | Italian and Spanish national mandates favor unified trans-European coordination platforms over fragmented national vendor relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors at German logistics companies, IT procurement officers at French transport services, telematics platform engineers, and vehicle finance bundling specialists at Italian leasing providers. Secondary validation incorporated KBA certification databases, EMA working hours enforcement guidelines, EU Green Deal heavy-duty vehicle CO2 standard filings, GDPR consent framework documentation, and customs records for cellular chipset imports. Bottom-up deployment counts across cloud-based, SaaS, hybrid, and on-premise architectures were triangulated against top-down vendor revenue disclosures.
Across the analysis window, forecasts integrated deployment model migration curves, service type margin trajectories, and end-user technology refresh velocities. Segmentation dimensions modeled include deployment architecture, service criticality tier, commercial vehicle category, and regulatory exposure intensity. CAGRs were derived from logistic diffusion curves fitted to historical cloud migration patterns and EU emission mandate compliance deadlines. Fuel price volatility indices and carbon border adjustment enforcement schedules served as scenario-weighting inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or accelerated cellular connectivity cost declines would require recalibration. Forecasts reflect documented assumptions regarding GDPR governance friction persistence and embedded systems talent scarcity depth. Recalibration cycles align with material shifts in EU AI Act implementation timelines and national tolling system interoperability mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Malaysia Refrigerated Trailer Market
Transportation & Logistics
Digital Shipment Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
United Kingdom Road Freight Transport Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Europe Long Haul Transport Market