
 Transplant Monitoring Kits Market | 2026-2036
Transplant Monitoring Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Transplant Monitoring Kits Market Analytics
North American molecular diagnostics producers is pivoting toward integrated transplant monitoring workflows. Thermo Fisher Scientific leverages its CLIA-certified laboratory network to sustain high-throughput kit deployment across major academic medical centers. F. Hoffmann-La Roche Ltd anchors its position through automated assay platforms that dominate reference laboratory channels. QIAGEN competes with sample-to-insight systems that reduce technician hands-on time during acute rejection workups.
Transplant monitoring kits comprise in-vitro diagnostic systems designed to detect biomarkers of graft rejection, infection, or immunosuppressant toxicity through blood, urine, or tissue specimen analysis, typically employing PCR amplification, ELISA quantification, or next-generation sequencing with turnaround times under 24 hours for critical care decisions. Their primary purpose centers on enabling clinicians to intervene before irreversible organ damage occurs. Molecular assays command the largest revenue share due to superior sensitivity for early rejection signatures, while biosensors represent the fastest-expanding technology segment as point-of-care formats penetrate outpatient transplant clinics. Kidney monitoring generates the highest procedure volume given the relative frequency of renal transplants, though heart monitoring kits sustain premium pricing tied to higher clinical stakes and lower test volumes.
FDA premarket notification requirements under 21 CFR Part 820 govern kit design controls and post-market surveillance, while EMA In Vitro Diagnostic Regulation mandates clinical evidence thresholds that reshape product development timelines for European market entry. ISO 15189 accreditation pressures laboratories to standardize analytical validation protocols, directly influencing kit manufacturer quality system investments. Stakeholders must weigh regulatory pathway complexity against the margin premium of multiplexed rejection-infection panels when prioritizing R&D portfolios.
Market Dynamics
Harmonization between FDA and EMA on companion diagnostic validation standards is compressing development timelines while elevating capital requirements for kit manufacturers serving dual markets.
Growth Catalysts
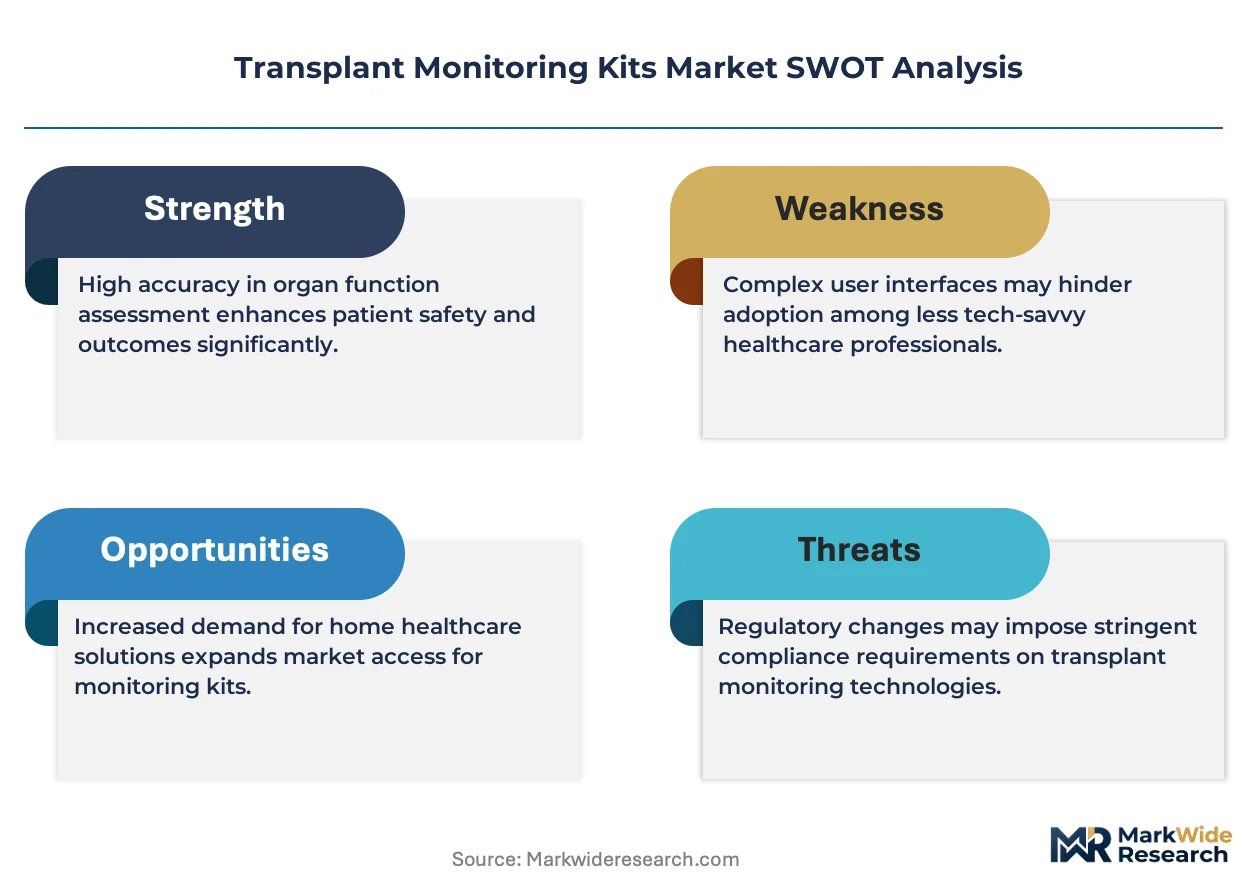
- IVDR Evidence Thresholds:EMA's tightened clinical evidence requirements for In Vitro Diagnostic Regulation are accelerating consolidation among manufacturers with robust quality systems, filtering out undercapitalized competitors.
- Molecular Assay Platforms:Hospital-based transplant centers are deploying PCR and next-generation sequencing systems that enable simultaneous rejection-infection panel testing, reducing acute care decision windows.
- Point-of-Care Biosensors:Outpatient transplant clinics in Germany and Japan are adopting portable monitoring formats that shift testing volume from centralized laboratories to ambulatory settings.
Market Restraints
- Reagent Supply Concentration:Critical PCR enzymes and fluorescent probes concentrate among three specialty chemical suppliers, exposing kit manufacturers to input volatility and allocation risk.
- ISO 15189 Accreditation Burden:Laboratory certification mandates in Europe and Japan force redundant analytical validation studies, extending commercialization timelines by 12-18 months for multi-market launches.
- Immunosuppressant Therapeutic Drug Monitoring Substitution:Pharmacokinetic testing platforms for tacrolimus and mycophenolate mofetil compete for budget share with rejection biomarker assays in resource-constrained settings.
Strategic Opportunities
- India Transplant Infrastructure:The country's expanding organ allocation network and CDSCO regulatory streamlining create first-mover advantages for kit manufacturers establishing local analytical partnerships.
- Heart-Lung Machine Perfusion Monitoring:Ex-vivo organ perfusion systems used during transport require real-time graft viability biomarker integration, opening adjacent device-agnostic assay markets.
- Digital Pathology Convergence:Integration of whole-slide imaging with molecular assay data enables AI-augmented rejection scoring, differentiating premium kit offerings in academic medical centers.
Industry Challenges
- Multiplex Assay Validation Expertise:Scarcity of biostatisticians capable of designing clinical studies for simultaneous rejection-infection-toxicity panels constrains R&D throughput at mid-tier manufacturers.
- Legacy LIMS Integration:Hospital laboratory information management systems require custom middleware development for automated result reporting, complicating kit deployment and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transplant Monitoring Kits Market |
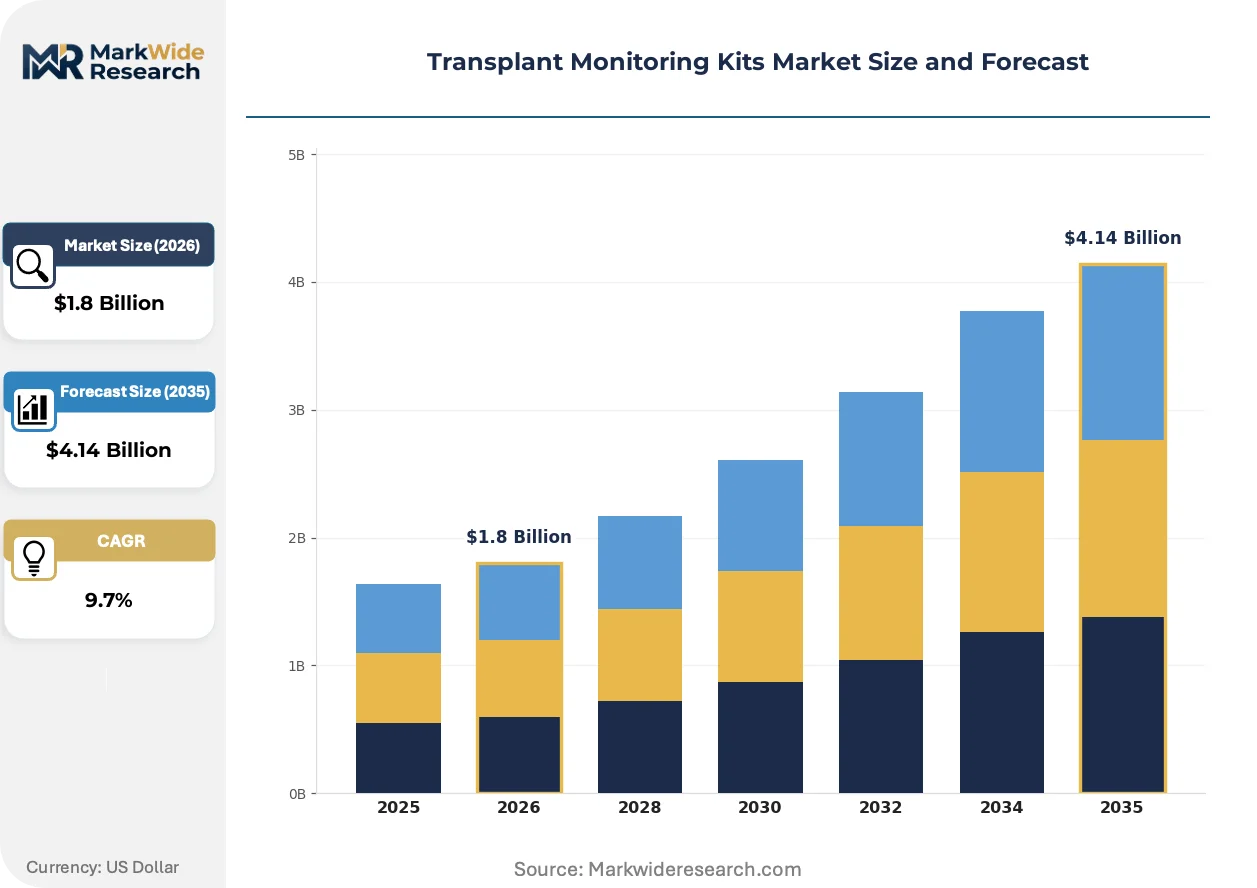
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kidney Monitoring, Liver Monitoring, Heart Monitoring, Lung Monitoring Technology: Biosensors, Molecular Assays, Imaging Systems, Data Analytics End User: Hospitals, Laboratories, Homecare Settings, Research Institutions Application: Post-Transplant Care, Pre-Transplant Screening, Patient Follow-Up, Complication Management |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, QIAGEN, Bio-Rad Laboratories, CareDx Inc., Immucor Inc., Eurofins Scientific, Natera Inc., Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transplant Monitoring Kits Market Evolving Landscape
Automation of sample processing and regulatory data management is compressing technician labor requirements while expanding test menu complexity in transplant monitoring workflows.
Microfluidic cartridge systems are automating nucleic acid extraction and PCR setup within closed disposable units, reducing contamination risk and hands-on time. Reference laboratories in the United States are adopting these platforms at accelerating pace to manage rising test volumes without proportional staffing expansion. This automation is automating the shift of molecular testing from skilled technologist-dependent workflows to instrument-mediated processes that enable overnight batch processing.
EMA's In Vitro Diagnostic Regulation implementation is mandating clinical performance studies with defined sensitivity and specificity thresholds for Class C devices including transplant rejection assays. Kit manufacturers must now generate prospective clinical evidence from European transplant centers before market authorization, restructuring development roadmaps and partnership strategies. Heart and lung monitoring kits face the steepest compliance burden given lower historical procedure volumes and scarcer archived specimen banks for retrospective validation.
Bundled payment models for transplant episodes are consolidating purchasing authority within integrated delivery networks, shifting procurement from individual laboratory directors to centralized value analysis committees. These committees prioritize total cost-per-test metrics over reagent pricing alone, favoring manufacturers offering automated platforms with reduced quality control labor requirements. The United States exhibits the most advanced consolidation, with three national transplant networks controlling majority procurement decisions for affiliated academic centers.
Transplant Monitoring Kits Market Segmentation
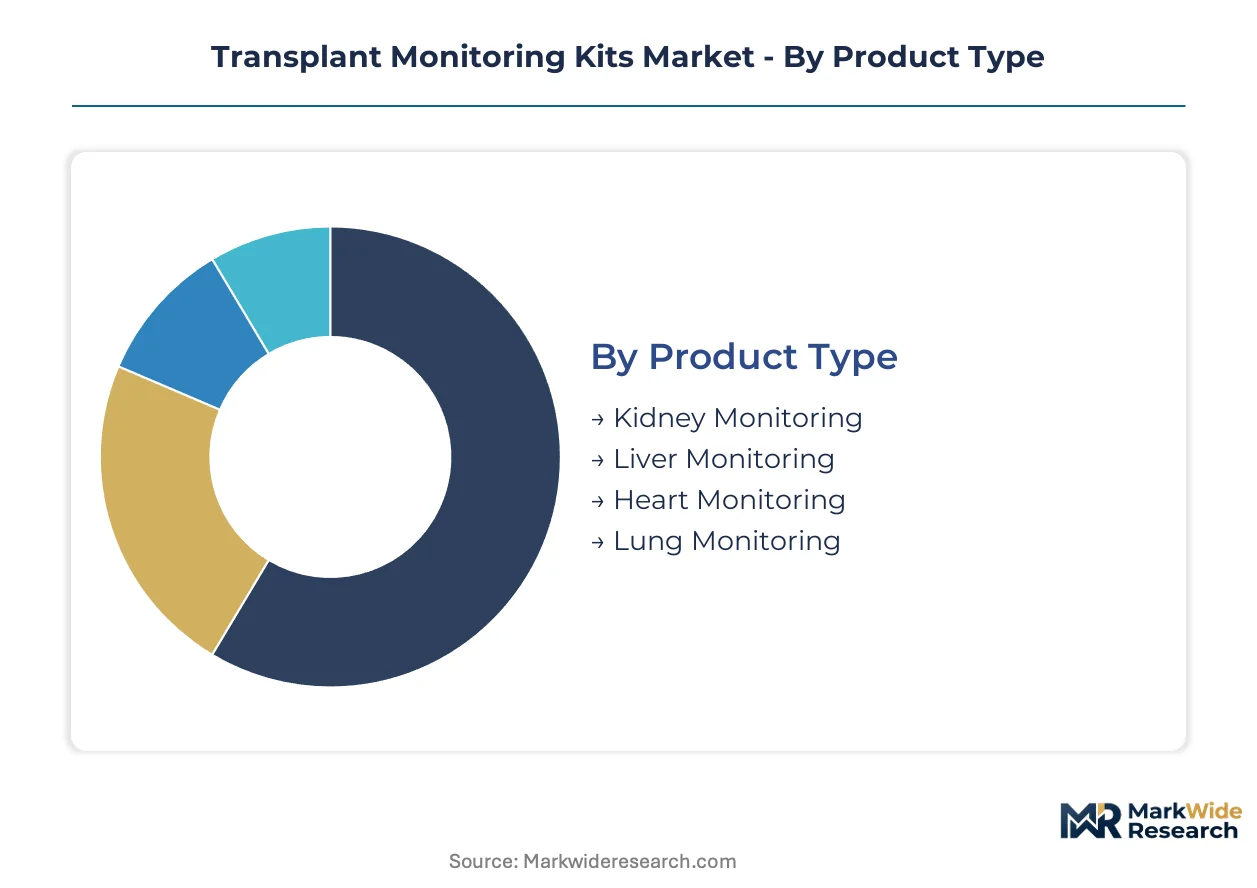
Transplant monitoring kits segment across organ-specific, technological, and care-setting dimensions that determine reimbursement pathways, regulatory classification, and procurement authority. Understanding these divisions reveals where kit manufacturers must align product specifications with distinct clinical workflows and purchasing decision structures.
Product Type:
Replacement cycles for organ-specific monitoring kits accelerate as transplant centers upgrade from single-analyte to multiplexed rejection panels, creating upgrade revenue streams alongside new-procedure demand.
- Kidney Monitoring:PCR-based donor-derived cell-free DNA assays dominate this segment, detecting tubular injury markers and rejection-associated transcripts in blood and urine specimens. United States academic medical centers concentrate demand here, driven by the high absolute volume of renal transplants and established Medicare reimbursement for molecular surveillance protocols.
- Heart Monitoring:Gene expression profiling kits command premium positioning through AlloMap and similar platforms that stratify rejection risk without invasive biopsy. German and Japanese transplant networks prioritize these assays given the clinical stakes of cardiac graft failure and their integration into bundled episode payments.
- Liver Monitoring:Hepatocyte-specific biomarker panels track cholestatic injury and biliary complications through serum microRNA quantification.
- Lung Monitoring:Bronchoalveolar lavage-based assays detect acute cellular rejection and infection through combined pathogen-rejection multiplexing.
Kidney monitoring sits at the top of the volume ranking, with heart monitoring climbing the fastest as risk-stratification protocols displace protocol biopsies.
Technology:
Cost tiering separates automated high-throughput platforms from portable point-of-care formats, with reimbursement differentials of 40-60% between centralized laboratory and ambulatory testing codes.
- Molecular Assays:Quantitative PCR and next-generation sequencing systems enable simultaneous detection of rejection signatures, viral load, and pharmacogenomic markers from single specimens. Hospital-based transplant centers in the United States and Japan anchor demand, compelled by IVDR and FDA harmonization to validate multi-analyte performance against stringent clinical evidence thresholds.
- Biosensors:Electrochemical and optical transducer systems deliver creatinine, lactate, and immunosuppressant levels at bedside or in outpatient clinics within minutes. German ambulatory transplant clinics and Japanese homecare programs drive fastest expansion here, reducing central laboratory dependency for stable post-transplant patients.
- Imaging Systems:Contrast-enhanced ultrasound and elastography platforms assess graft perfusion and fibrosis non-invasively.
- Data Analytics:Machine learning algorithms integrate multi-modal biomarker trajectories to predict rejection episodes before clinical manifestation.
Molecular assays capture the highest revenue tier, while biosensors gain share fastest as point-of-care reimbursement codes mature in European and Asian markets.
End User:
Customer type determines kit format specifications, with centralized laboratories demanding batch-processing efficiency and homecare settings requiring foolproof sample collection and connectivity.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing for affiliated transplant centers, favoring automated platforms with reduced quality control labor. These institutions mandate LIMS interoperability and 24-hour turnaround for acute rejection workups, shaping manufacturer middleware development priorities.
- Laboratories:Reference laboratories in Germany and Japan process high volumes for multiple transplant centers, requiring high-throughput molecular assay systems with ISO 15189-compliant validation documentation.
- Homecare Settings:Patient self-testing formats with smartphone-connected readers enable remote monitoring of stable graft recipients.
- Research Institutions:Academic medical centers validate novel biomarker panels through prospective clinical studies under FDA and EMA investigational device exemptions.
Hospitals dominate absolute kit consumption, with homecare settings expanding most quickly as remote patient monitoring reimbursement frameworks stabilize.
Application:
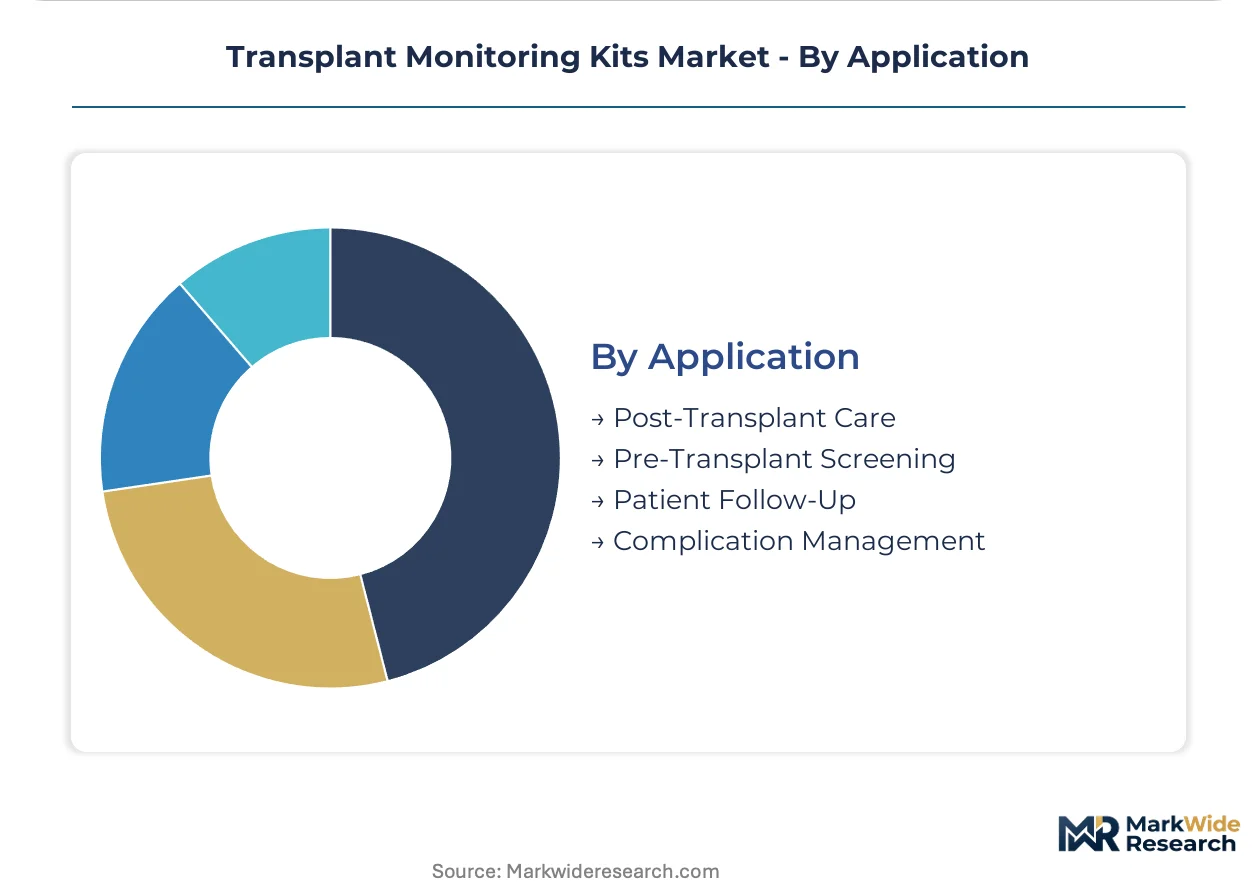
Application focus shapes regulatory pathway selection, with post-transplant surveillance kits facing Class C device requirements under IVDR while pre-transplant screening assays navigate donor eligibility testing standards.
- Post-Transplant Care:Serial monitoring protocols track graft function through scheduled biomarker surveillance, with rejection-infection differential diagnosis representing the highest-stakes decision point. United States transplant networks and German statutory health insurance programs concentrate reimbursement here, mandating documented sensitivity and specificity for authorization.
- Complication Management:Acute rejection workups and infection triage require rapid turnaround panels that simultaneously rule out CMV, BK virus, and cellular rejection. Japanese transplant centers prioritize these applications given regulatory emphasis on minimizing immunosuppressant exposure through precise infection-rejection discrimination.
- Pre-Transplant Screening:Donor-specific antibody detection and crossmatch assays assess immunological risk before organ allocation.
- Patient Follow-Up:Long-term surveillance kits monitor chronic allograft dysfunction and medication adherence in stable recipients.
Post-transplant care commands the largest procedure volume, with complication management showing the steepest expansion trajectory as multiplexed acute panels displace sequential testing algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kit manufacturers face divergent compliance costs across jurisdictions, prompting strategic facility placement and partnership decisions. EMA's IVDR implementation has elevated European evidence thresholds above FDA benchmarks, reshaping where clinical validation studies occur.
United States
Medicare reimbursement for molecular surveillance protocols drives hospital-based transplant center procurement. FDA premarket notification pathways under 21 CFR Part 820 govern kit design controls, with CLIA-certified laboratory networks concentrating in Massachusetts and California. Academic medical centers in Boston and San Francisco anchor high-throughput deployment of multiplexed rejection-infection panels.
Germany
Statutory health insurance programs mandate documented sensitivity and specificity for transplant monitoring authorization. EMA In Vitro Diagnostic Regulation compliance requirements compress development timelines while filtering undercapitalized competitors. Reference laboratories in Munich and Heidelberg process high volumes for multiple transplant networks, requiring ISO 15189-compliant validation documentation.
Japan
PMDA regulatory emphasis on minimizing immunosuppressant exposure accelerates precise infection-rejection discrimination demand. METI-supported homecare programs drive biosensor adoption for stable graft recipient remote monitoring. Tokyo and Osaka transplant centers prioritize rapid turnaround acute panels given bundled episode payment structures.
India
Expanding organ allocation networks and CDSCO regulatory streamlining create first-mover advantages for kit manufacturers. The country's national pharmaceutical regulator is harmonizing clinical evidence requirements with international benchmarks. Analytical partnerships in Maharashtra and Karnataka enable local validation studies for multi-market launch strategies.
Switzerland
Swissmedic oversight of companion diagnostic validation aligns with EMA standards while offering streamlined authorization for novel biomarker panels. Precision medicine clusters in Basel and Zurich attract kit manufacturers seeking proximity to pharmaceutical development pipelines. Local reference laboratories serve as European validation sites for heart and lung monitoring assays.
Transplant Monitoring Kits Market Competitive Landscape
United States producers anchor the automated platform tier; European specialists hold the standardized assay segment. Market structure concentrates around three to five integrated diagnostic conglomerates with captive laboratory networks, while mid-tier manufacturers compete through niche organ-specific panels. Strategic archetypes include high-throughput reference laboratory suppliers, point-of-care format developers, and multi-analyte panel specialists. Dominant competitive moves encompass automated platform licensing agreements and backward integration into specialty reagent supply.
Among United States-based conglomerates, Thermo Fisher Scientific and CareDx Inc. exemplify the automated platform archetype through CLIA-certified network leverage. F. Hoffmann-La Roche Ltd occupies a position within the European standardized assay tier. QIAGEN represents the sample-to-insight systems specialist segment competing on technician efficiency metrics.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| QIAGEN |
| Bio-Rad Laboratories |
| CareDx Inc. |
| Immucor Inc. |
| Eurofins Scientific |
| Natera Inc. |
| Hologic |
| Others |
Value Network & Pricing Analysis
Specialty PCR enzyme spot prices cascade through transplant monitoring kit manufacturing, compressing margins for mid-tier producers while amplifying pricing power for conglomerates with captive reagent supply. This input volatility stratifies the market into three performance tiers that transplant centers navigate through bundled procurement contracts.
Pricing Analysis
Distributor markups of 15-25% separate reference laboratory pricing from direct hospital procurement, with integrated delivery networks negotiating volume rebates that erase this spread. Three-tier pricing structure across premium, standard, and economy levels reflects automation intensity and validation documentation depth. Cost compression in the standard tier is intensifying because ISO 15189 accreditation requirements force redundant analytical studies. Academic medical centers exhibit lowest price sensitivity given bundled episode payments, while outpatient clinics in Germany and Japan prioritize per-test economy.
Supply Chain Analysis
ISO 13485 quality system certification gates supplier qualification, with only 12% of specialty chemical vendors meeting dual FDA-EMA documentation standards. Critical PCR enzymes and fluorescent probes concentrate among suppliers in the United States, Germany, and Japan. Kit manufacturing draws from single-source dependencies for thermostable polymerases and rare-earth optical substrates. Tariff exposure runs through reagent import channels from concentrated chemical hubs. Distribution runs through CLIA-certified laboratory networks and GPO-authorized distributors serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where EMA IVDR harmonization with FDA standards filters out undercapitalized competitors, concentrating procurement authority among transplant networks demanding premium multiplexed panels with documented clinical evidence.
For Market Incumbents: Extend automated platform licensing agreements into emerging transplant networks in India and Switzerland before CDSCO and Swissmedic validation requirements harden. Backward integration into specialty reagent supply insulates against polymerase allocation risk from concentrated chemical suppliers. Capacity expansion in Maharashtra analytical partnerships secures first-mover positioning for multi-market launches. For New Entrants and Emerging Players: Launch via white-label partnerships with reference laboratories in Germany seeking ISO 15189-compliant kidney monitoring alternatives to incumbent gene expression platforms. Homecare biosensor formats for Japanese METI-supported remote monitoring programs offer the most penetrable entry vector. Target academic medical center research collaborations under FDA investigational device exemptions to generate prospective clinical evidence. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier molecular assay specialists possessing IVDR-ready quality systems but lacking hospital network penetration. Long-term viability hinges on consolidation into integrated diagnostic conglomerates with captive laboratory infrastructure. The signal to watch is bundled payment model adoption velocity across United States transplant networks as procurement authority centralization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Clinical Evidence Generation | Prospective European transplant center studies satisfy EMA Class C device thresholds before market authorization. |
| Automated Platform Licensing | Middleware integration with hospital LIMS systems reduces deployment friction and support cost burdens. |
| Specialty Reagent Backward Integration | Captive polymerase supply insulates manufacturing from allocation volatility in concentrated chemical markets. |
| Digital Pathology Convergence | AI-augmented rejection scoring differentiates premium kit offerings in academic medical center procurement. |
| Homecare Biosensor Deployment | Smartphone-connected formats capture Japanese METI remote monitoring reimbursement as ambulatory codes mature. |
Research Methodology
Direct dialogue with transplant center laboratory directors, reference laboratory operations managers, biomedical engineers, and GPO contracts specialists combined secondary validation through FDA 510(k) filings, EMA IVDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up and top-down triangulation cross-validated molecular assay platform deployment metrics against statutory health insurance authorization data.
Bottom-up modeling anchored segment-level projections to installed base counts and replacement cycle frequencies, while top-down constraints checked aggregate revenue against bundled payment episode values across the analysis window. Segmentation dimensions spanned organ specificity, technology platform, care setting, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to historical platform penetration rates and harmonized validation timeline compressions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden reagent supply disruption or accelerated IVDR enforcement timelines. Forecasts reflect assumptions about transplant volume trajectories, reimbursement code stability, and regulatory harmonization velocity. A model refresh is warranted upon material change in bundled payment model adoption or specialty chemical supplier consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transseptal Access Systems Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Light Therapy Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Cranial Closure and Fixation Devices Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Asia-Pacific Biosurgery Market