
 Europe Freight and Logistics Market | 2026-2036
Europe Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Freight and Logistics Market Analysis
CE marking under the EU F-Gas Regulation is unwinding competitive access for refrigerated transport operators unable to meet fluorinated gas phase-down schedules. DHL Group leverages its pan-European electric fleet rollout to sustain compliance leadership in cold-chain logistics. Kuehne + Nagel anchors its position through proprietary carbon calculator tools that navigate emissions disclosure mandates.
Europe freight and logistics encompasses the physical movement, storage, and customs facilitation of goods across national borders using multimodal networks with specified transit-time guarantees and temperature-controlled capabilities. The sector manages inventory velocity for industrial supply chains through cross-docking, bonded warehousing, and real-time shipment visibility systems. Road freight dominates volume flows but faces margin compression from fuel cost volatility and driver shortages, while warehousing captures expanding value pools as e-commerce fulfillment demands same-day and next-day delivery infrastructure. Rail and intermodal segments are accelerating as shippers seek alternatives to road congestion and carbon accounting pressures intensify across manufacturing and retail supply chains.
EMA, ECHA, and the EU Green Deal framework collectively reshape fleet procurement decisions, warehouse energy standards, and cross-border emissions reporting obligations for logistics operators. REACH compliance requirements for chemical transport documentation and packaging materials add procedural layers that favor established providers with dedicated regulatory affairs teams. Stakeholders must weigh electrification capex against diesel asset stranded-risk as the EU F-Gas Regulation tightens and national low-emission zones multiply.
Market Dynamics
EU Green Deal emissions targets are compressing diesel fleet residual values while accelerating electric truck procurement timelines across German, French, and Polish logistics corridors.
Growth Catalysts
- E-commerce fulfillment density:Same-day delivery promises from retail platforms are forcing warehouse network expansion into secondary European cities. Automated sortation systems reduce per-parcel handling costs.
- REACH compliance documentation:Chemical transport mandates favor established operators with dedicated regulatory affairs teams. Bonded warehousing demand rises for cross-border hazardous materials.
- Rhine-Ruhr corridor concentration:Industrial manufacturing clusters in North Rhine-Westphalia generate continuous full-truckload volumes. Intermodal terminals at Duisburg and Cologne capture modal shift from road.
Market Restraints
- Driver availability constraints:Aging workforce demographics and restrictive cabotage rules limit operational flexibility. Eastern European labor pools face competitive pressure from construction and manufacturing.
- Battery energy density limitations:Current lithium-ion packs restrict electric heavy-duty trucks to sub-500km routes without mid-journey charging. Cold-chain operators face payload penalties from thermal management systems.
- CE marking under F-Gas phase-down:Refrigerated transport operators must retrofit or replace fluorinated gas systems. Smaller fleet owners lack capital for compliant reefer unit upgrades.
Strategic Opportunities
- Polish warehousing expansion:Central European location offers 24-hour truck access to Berlin, Prague, and Vienna. Labor costs remain 40% below German equivalents for fulfillment center operations.
- Rail intermodal integration:Combined transport contracts bundle first-mile collection with long-haul rail and final-mile delivery. Shippers absorb carbon accounting benefits without managing modal complexity.
- CSRD emissions disclosure mandates:Corporate sustainability reporting requirements create demand for verified logistics carbon data. Third-party verification services capture recurring revenue from Scope 3 reporting.
Industry Challenges
- Electrification capex timing:Fleet operators must balance premature battery technology adoption against diesel asset stranded-risk. Charging infrastructure gaps persist on Trans-European Transport Network corridors.
- Cross-border customs digitization:Post-UK withdrawal procedures and varying national electronic systems create documentation friction. Real-time shipment visibility requires API integration with multiple government platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Freight and Logistics Market |
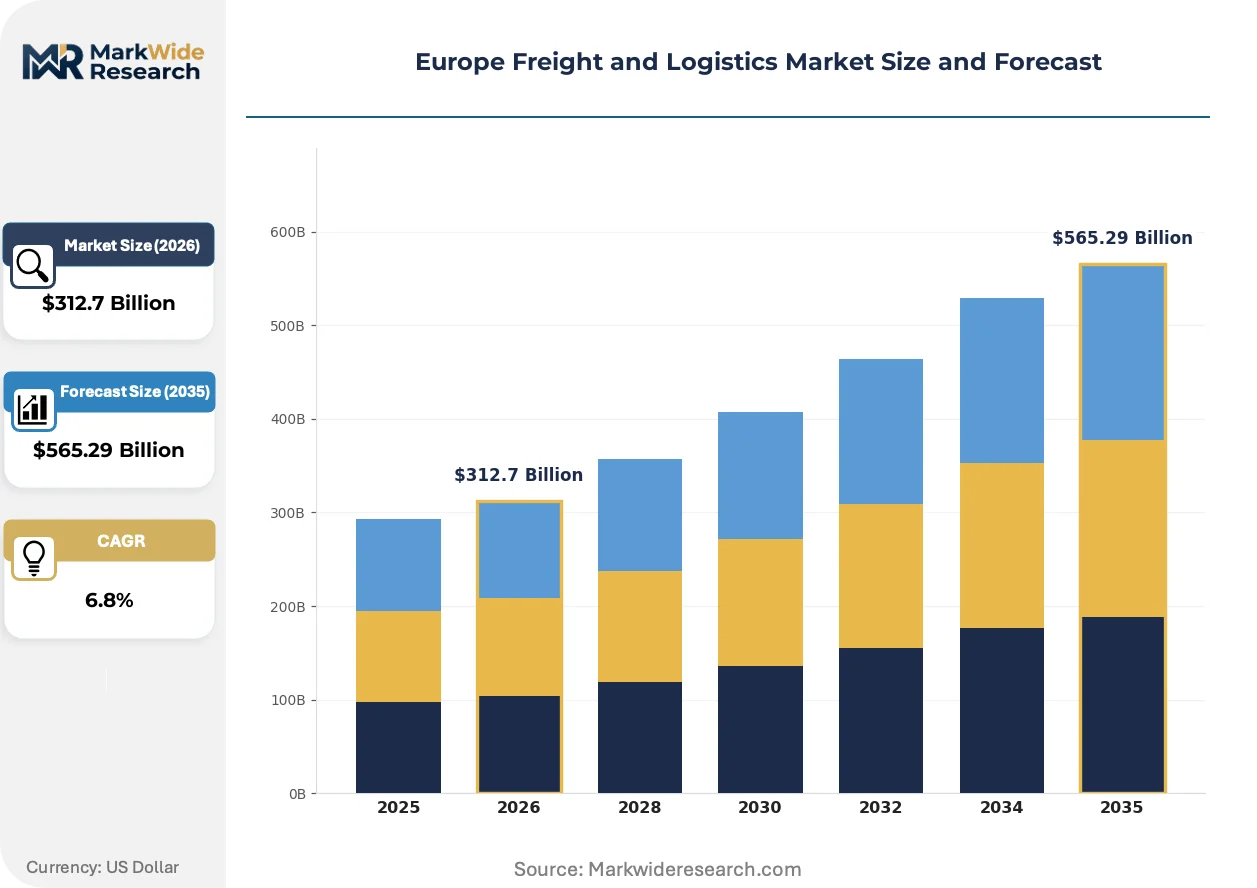
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: Manufacturing, Retail, E-Commerce, Pharmaceuticals Mode: Road, Rail, Air, Sea Technology: IoT, AI, Blockchain, Automation |
| Companies Covered | A.P. Moller - Maersk, GEODIS, DSV A/S, DACHSER, Rhenus Logistics, DHL Group, CEVA Logistics, Hellmann Worldwide Logistics, Kuehne + Nagel, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Freight and Logistics Market Emerging Trajectories
Digital freight platforms are restructuring how shippers access capacity, while regulatory disclosure requirements transform data into a competitive asset class.
Autonomous yard management systems are fragmenting traditional warehouse labor deployment patterns. Retail distribution centers in the Netherlands and Belgium deploy vision-guided forklifts for 24-hour container unloading. Third-party logistics providers compress site labor costs while retraining existing staff for exception-handling roles.
The EU F-Gas Regulation tightens fluorinated gas phase-down schedules through 2030. Refrigerated transport operators face accelerated reefer unit replacement cycles. Cold-chain specialists in Spain and Italy retrofit trailers with CO2 transcritical systems to maintain CE marking compliance.
Shippers now bundle carbon accounting with freight procurement decisions. Manufacturing verticals in Germany and France embed emissions thresholds into transport tender evaluations. Long-term contracts increasingly specify verified low-carbon fuel percentages rather than standard diesel rates.
Europe Freight and Logistics Market Segmentation
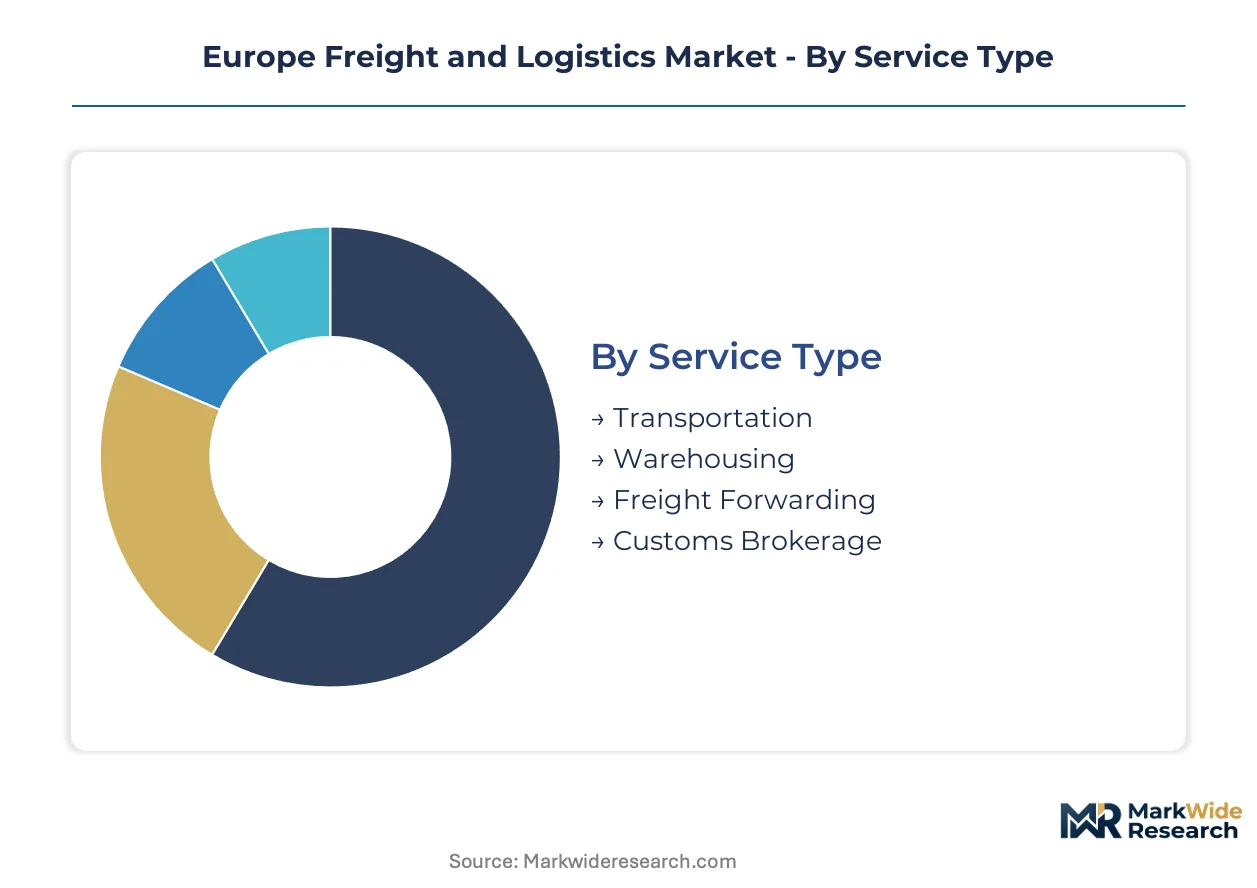
Service differentiation across Europe freight and logistics determines margin capture and regulatory exposure. Segmentation reveals which operational models absorb EU Green Deal compliance costs most efficiently and where digital infrastructure investments concentrate returns.
Service Type:
Rail intermodal and autonomous warehousing pose the strongest substitution threat to traditional road freight and manual distribution centers.
- Transportation:Physical movement of goods via owned or contracted fleet assets across multimodal networks. Rhine-Ruhr corridor operators capture dense manufacturing flows while electric truck limitations restrict long-haul substitution.
- Warehousing:Storage facilities with value-added services including cross-docking, inventory management, and fulfillment processing. Polish secondary cities attract automated sortation investments due to 24-hour access to Berlin, Prague, and Vienna.
- Freight Forwarding:Coordination of multimodal shipment routing and carrier procurement on behalf of shippers.
- Customs Brokerage:Documentation preparation and regulatory compliance facilitation for cross-border movements.
Transportation anchors the volume base while warehousing gains share at the steepest rate.
End User:
Customer concentration varies sharply by margin profile and emissions disclosure intensity.
- Manufacturing:Industrial supply chains requiring just-in-time delivery and bonded warehousing for imported components. German automotive clusters in Baden-Württemberg and Bavaria drive continuous full-truckload demand.
- E-Commerce:Platform-driven fulfillment requiring same-day and next-day delivery infrastructure. Netherlands and Belgium distribution centers deploy vision-guided forklifts for 24-hour container unloading.
- Retail:Seasonal inventory velocity with omnichannel replenishment requirements.
- Pharmaceuticals:Temperature-controlled distribution with REACH documentation mandates and EMA serialization requirements.
E-commerce commands capital deployment priority while pharmaceuticals delivers the highest margin per cubic meter.
Mode:
Carbon accounting pressures are reordering modal preference hierarchies across freight procurement.
- Road:Dominant volume share using diesel and emerging electric heavy-duty fleets. Driver shortages in Germany and cabotage restrictions compress operational flexibility.
- Rail:Long-haul bulk and container movements with intermodal terminal integration. Duisburg and Cologne terminals capture modal shift from congested road corridors.
- Air:Time-critical and high-value shipments with concentrated pharmaceutical and electronics demand.
- Sea:Deep-water container and Ro-Ro services connecting European ports to global manufacturing bases.
Road retains volume dominance while rail climbs the fastest on emissions compliance advantages.
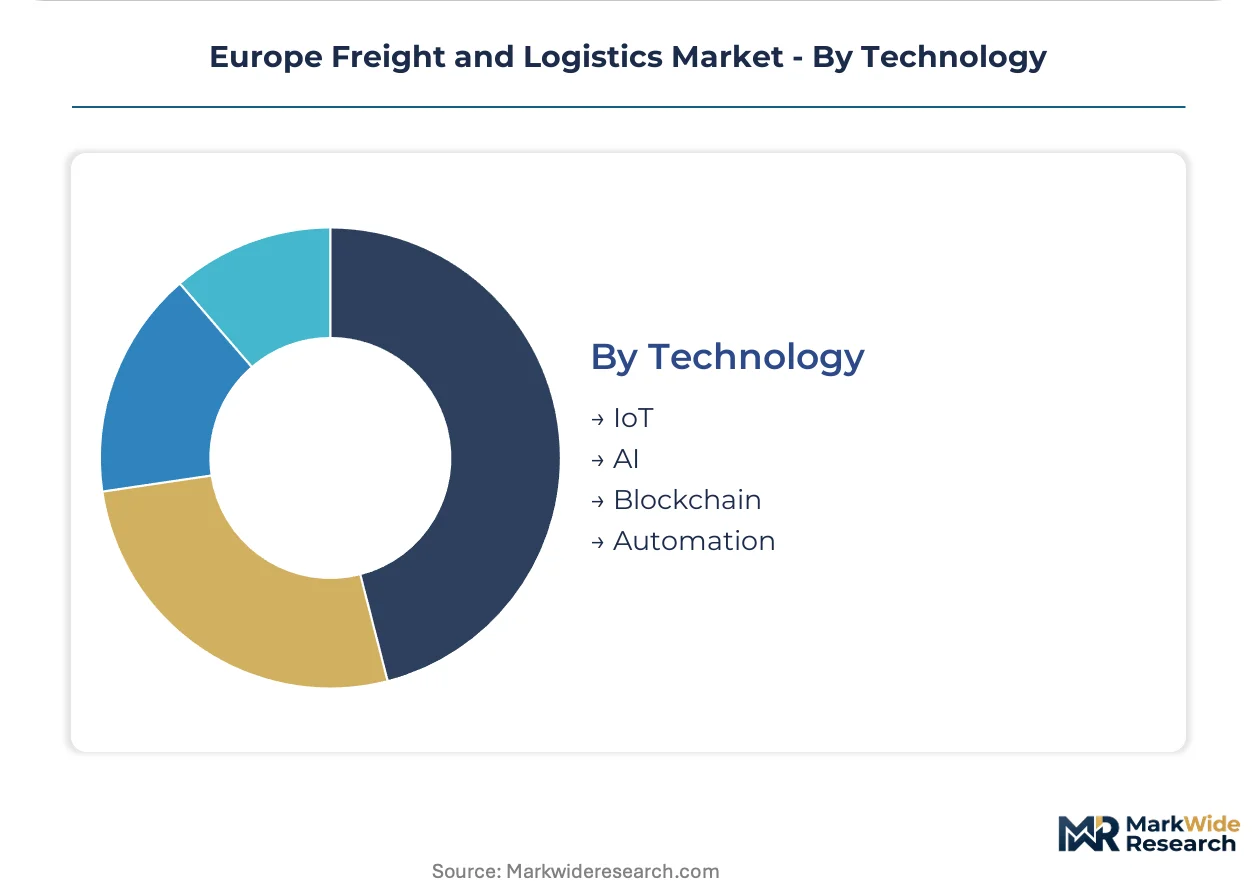
Technology:
Data infrastructure investments separate compliance-capable operators from stranded asset risk.
- IoT:Sensor networks providing real-time location, temperature, and condition monitoring across fleet and warehouse assets.
- AI:Predictive routing, demand forecasting, and automated customer service interfaces.
- Blockchain:Immutable documentation chains for customs verification and supply chain provenance.
- Automation:Robotic sortation, autonomous yard management, and vision-guided material handling systems.
IoT underpins baseline visibility while automation expands most quickly in labor-constrained markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and chemical buyers concentrate procurement volumes in the Rhine-Ruhr corridor. French retail platforms drive cross-border fulfillment density into Benelux distribution nodes. Polish manufacturing clusters attract warehouse automation investments from Western European capital.
Germany
Automotive just-in-time supply chains and chemical bulk movements generate continuous full-truckload demand across Baden-Württemberg and Bavaria. The KBA enforces strict commercial vehicle emissions standards that accelerate electric truck procurement timelines. Duisburg's intermodal terminals capture modal shift from congested road corridors serving the Rhine-Ruhr manufacturing belt.
France
Paris-based retail platforms and Lyon pharmaceutical clusters sustain temperature-controlled distribution volumes. The EU Green Deal's national low-emission zone mandates force fleet operators toward electrification in Greater Paris. Lille logistics parks serve as cross-border consolidation points for Benelux and UK-bound freight.
Netherlands
Rotterdam port throughput and Venlo e-commerce fulfillment centers drive automated warehouse deployment. ECHA chemical transport documentation requirements favor established operators with dedicated compliance teams. Waalwijk distribution clusters process parcel volumes for same-day delivery promises across Western Europe.
Poland
Central European location enables 24-hour truck access to Berlin, Prague, and Vienna from Warsaw and Wrocław logistics corridors. REACH compliance documentation for chemical imports favors bonded warehousing investments. Łódź and Poznań attract German retail fulfillment center expansions due to 40% labor cost advantages.
Italy
Milan-Turin industrial manufacturing and Rome pharmaceutical distribution sustain temperature-controlled road freight demand. ANSM serialization requirements for pharmaceutical transport add documentation layers favoring specialized logistics providers. Verona intermodal terminals capture modal shift from Alpine road congestion on north-south corridors.
Europe Freight and Logistics Market Vendor Landscape
Player mix skews toward integrated pan-European networks with dedicated regulatory affairs capabilities. The vendor base concentrates around asset-heavy fleet operators and asset-light freight forwarders with multimodal orchestration expertise. Three archetypes dominate: compliance-led cold-chain specialists, scale-driven parcel networks, and intermodal bundlers. Competitive moves center on electric fleet procurement acceleration and carbon data verification service launches.
Among Denmark-based integrated logistics groups, DSV A/S and A.P. Moller - Maersk represent the scale-driven archetype with extensive European network coverage. Swiss-headquartered Kuehne + Nagel occupies a position exemplifying the asset-light freight forwarding model with proprietary emissions disclosure tools. These three companies anchor the competitive structure through differentiated approaches to EU Green Deal compliance and cross-border customs digitization.
| Leading Market Players |
|---|
| A.P. Moller - Maersk |
| GEODIS |
| DSV A/S |
| DACHSER |
| Rhenus Logistics |
| DHL Group |
| CEVA Logistics |
| Hellmann Worldwide Logistics |
| Kuehne + Nagel |
| Others |
Supply Flow & Price Mechanics
Fourteen-day lead-time guarantees from German automotive clusters anchor contract premiums in the Rhine-Ruhr corridor, compressing margins for operators unable to match inventory velocity while amplifying pricing power for intermodal bundlers with bonded warehousing assets. This lead-time discipline reshapes procurement decisions as shippers absorb modal complexity premiums to secure transit-time certainty.
Pricing Analysis
Cost-plus contracts indexed to EU ETS carbon price movements dominate long-term logistics agreements, with fuel surcharges adjusting quarterly against diesel and electricity futures. Price differentiation centers on CE marking compliance for refrigerated units and real-time visibility API integration, with certified cold-chain operators commanding 15-20% premiums over standard road freight. Pricing pressure stems from Polish warehouse operators undercutting German fulfillment rates through labor arbitrage. Small fleet owners exhibit highest price sensitivity due to stranded diesel asset risk, while pharmaceutical shippers absorb premium tiers for temperature-validated lanes.
Supply Chain Analysis
Inventory velocity requirements from just-in-time automotive supply chains concentrate procurement decisions on operators with sub-48-hour cross-dock capabilities. Manufacturing inputs draw from Germany's chemical corridor, Polish component assembly clusters, and Benelux distribution nodes. Supply chain risk centers on single-source vulnerability at Duisburg intermodal terminals handling Rhine-Ruhr modal shifts. Distribution runs through hub-and-spoke warehouse networks with automated sortation at Warsaw, Venlo, and Waalwijk nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail intermodal bundling poses immediate substitution threat to traditional road freight operators as EU Green Deal compliance costs accelerate modal shift decisions among carbon-accounting-intensive shippers.
For Market Incumbents: Compound network density in the Rhine-Ruhr corridor through intermodal terminal control and bonded warehousing investments. Capture stranded diesel asset value through early electric fleet procurement aligned with KBA emissions timelines. Vertical integration into Polish secondary-city fulfillment centers defends margin position against labor-cost arbitrage from emerging regional operators. For New Entrants and Emerging Players: Lead with carbon verification services targeting CSRD-mandated Scope 3 disclosure gaps among mid-tier manufacturing shippers. Polish warehousing automation presents the most penetrable white-space, with 24-hour Berlin-Prague-Vienna access and 40% labor cost advantages over German equivalents. Position around real-time emissions API integration as the go-to-market wedge against established forwarders lacking proprietary carbon calculator tools. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric truck procurement and automated warehouse deployments, favoring asset-light freight forwarding models with technology differentiation over heavy fleet ownership. Acquisition targets should display compliance-led cold-chain specialization with F-Gas retrofit completion and established ECHA documentation teams. Watch EU ETS price trajectories as the signal for accelerated modal shift timing and electric fleet ROI inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Procurement Acceleration | DHL Group's pan-European rollout secures KBA compliance leadership ahead of diesel asset stranding. |
| Polish Warehouse Automation Investment | German retail fulfillment expansions into Łódź capture 40% labor cost advantages with 24-hour Western European access. |
| Rail Intermodal Terminal Control | Duisburg and Cologne terminals capture modal shift from congested road corridors serving Rhine-Ruhr manufacturing. |
| Carbon Verification Service Launch | Kuehne + Nagel's proprietary calculator navigates CSRD mandates for Scope 3 emissions disclosure. |
| CO2 Transcritical Reefer Retrofit | Spanish and Italian cold-chain operators maintain CE marking compliance under tightening EU F-Gas phase-down schedules. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU customs databases, ETS price registries, and operator fleet disclosure filings. Primary interviews engaged logistics procurement directors at German automotive OEMs, Polish warehouse operations managers, freight forwarding regulatory affairs leads, and intermodal terminal planners. Secondary validation drew from KBA vehicle registration data, ECHA chemical transport documentation, and EU Green Deal implementation progress reports. Bottom-up service revenue builds triangulated against top-down modal volume flows.
Segmentation dimensions modeled include service type, end-use vertical, transport mode, and technology infrastructure across the projection horizon. CAGRs derive from weighted capacity expansion schedules, regulatory compliance cost curves, and modal shift elasticity estimates. Forecast inputs incorporate EU ETS price trajectory assumptions and electric truck total-cost-of-ownership parity timelines against diesel equivalents.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated battery energy density improvements would require recalibration. Forecasts reflect documented assumptions regarding carbon price trajectories, charging infrastructure deployment rates, and labor cost differentials. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Transportation Aggregators Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market