
 Indonesia Refrigerated Trailer Market | 2026-2036
Indonesia Refrigerated Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Refrigerated Trailer Market Insights
Pharmaceutical distributors is redrawing fleet procurement priorities across Indonesia as vaccine and biologics logistics tighten temperature integrity requirements. PT Kamadjaja Logistics leverages its port-centric depot network to dominate pharmaceutical cold-chain contracts in Surabaya and Jakarta. PT Puninar Logistics anchors its position through captive maintenance facilities that reduce reefer downtime for FMCG clients. Schmitz Cargobull AG differentiates via modular cooling units that allow rapid payload reconfiguration between frozen and chilled cargo.
A refrigerated trailer is an insulated semi-trailer equipped with an integrated mechanical refrigeration unit capable of maintaining cargo temperatures between minus 30 degrees Celsius and plus 20 degrees Celsius, constructed with polyurethane foam core panels bonded to fiberglass or aluminum skins. Its primary commercial purpose is to transport temperature-sensitive commodities across Indonesia's archipelagic logistics corridors without breaking the cold chain during multi-modal transfers. Tandem axle configurations lead unit sales due to their optimal balance of payload flexibility and toll-road axle-weight compliance on Java's arterial highways. Direct expansion cooling technology occupies the largest installed base, though cryogenic systems are gaining traction among ultra-low temperature pharmaceutical shippers seeking to eliminate compressor maintenance in remote island routes.
BIS thermal performance standards, Ministry of Transportation axle-load regulations, and Ministry of Health Good Distribution Practice mandates collectively shape reefer specifications and fleet renewal cycles across the archipelago. Compliance with BIS insulation certification now gates access to government-backed cold-chain infrastructure subsidies, accelerating replacement of aging single-axle units. Stakeholders must monitor how forthcoming sulfur fuel specifications for inter-island shipping will reshape port-side reefer power protocols and electrification investment timelines.
Market Dynamics
BIS thermal insulation certification now gates access to government-backed cold-chain infrastructure subsidies, forcing fleet operators toward accelerated replacement cycles for aging single-axle reefers across Java's arterial corridors.
Growth Catalysts
- Ministry of Health Good Distribution Practice mandates:Vaccine and biologics logistics tighten temperature integrity requirements, pulling pharmaceutical distributors toward dedicated reefer procurement.
- Fresh produce export compliance:Supermarket chains impose stricter cold-chain reliability standards, expanding fleet orders from Indonesian exporters serving Singapore and Malaysia.
- Java's port throughput concentration:Surabaya and Jakarta distribution density creates chronic capacity constraints that justify premium reefer investment.
Market Restraints
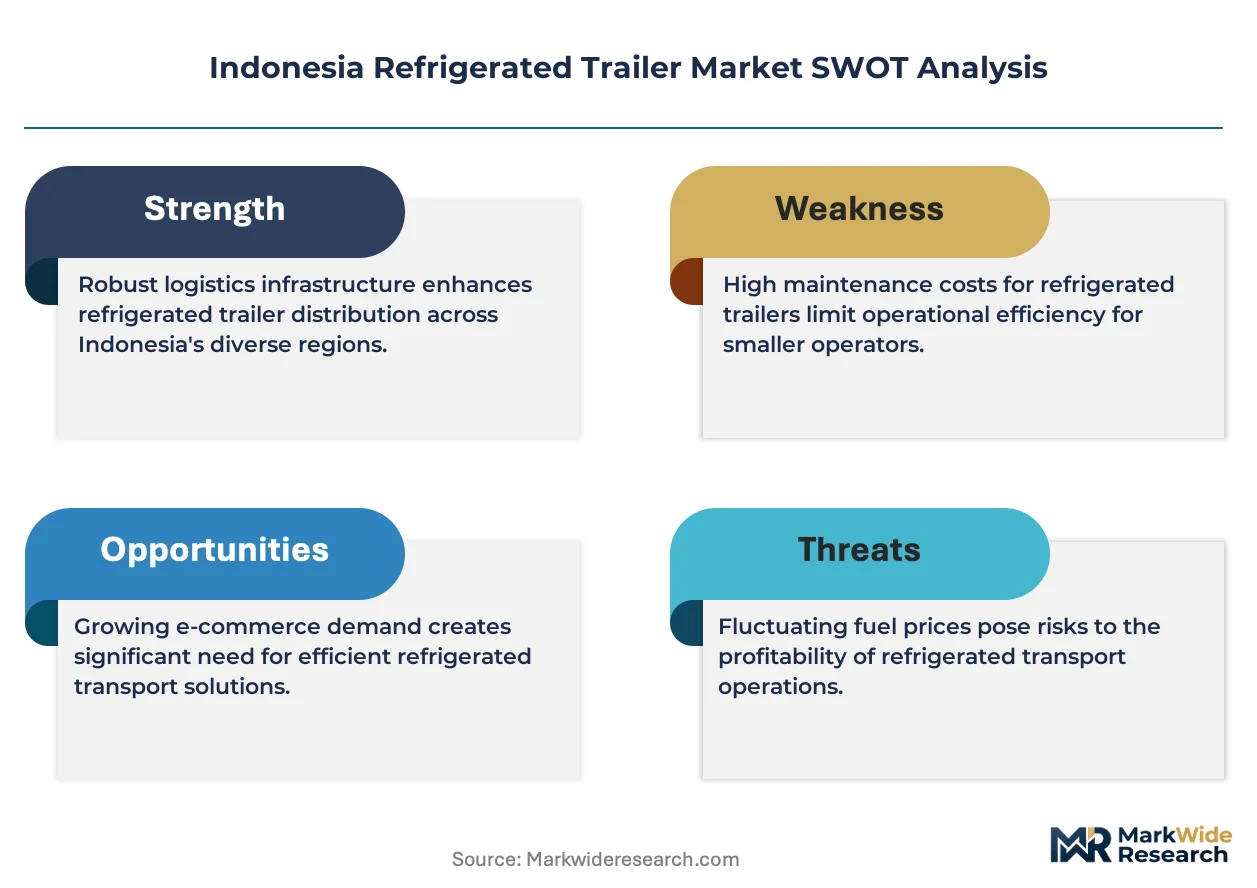
- Polyurethane foam input volatility:Insulation panel core material costs fluctuate with petrochemical feedstock pricing, compressing margin visibility for domestic trailer assemblers.
- Axle-load regulatory friction:Ministry of Transportation weight limits on toll-road networks restrict tandem-axle payload optimization despite higher unit economics.
- Inter-island shipping fuel sulfur specifications:Forthcoming maritime emissions rules will force port-side reefer power protocol reconfiguration, delaying electrification investment timelines.
Strategic Opportunities
- Sulawesi and Kalimantan underpenetration:Distribution infrastructure gaps in non-Java islands create first-mover advantage for operators deploying cryogenic cooling systems on remote routes.
- Modular cooling unit convergence:Rapid payload reconfiguration between frozen and chilled cargo enables asset utilization flexibility for diversified logistics providers.
- Captive maintenance facility networks:In-house service capabilities reduce reefer downtime, locking in FMCG client stickiness through guaranteed uptime contracts.
Industry Challenges
- Certification timeline compression:BIS thermal performance testing queues extend delivery schedules, forcing fleet planners to front-load orders.
- Multi-modal transfer integrity:Cold-chain breaks during port transloading between reefers and inter-island vessels generate spoilage liability disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Refrigerated Trailer Market |
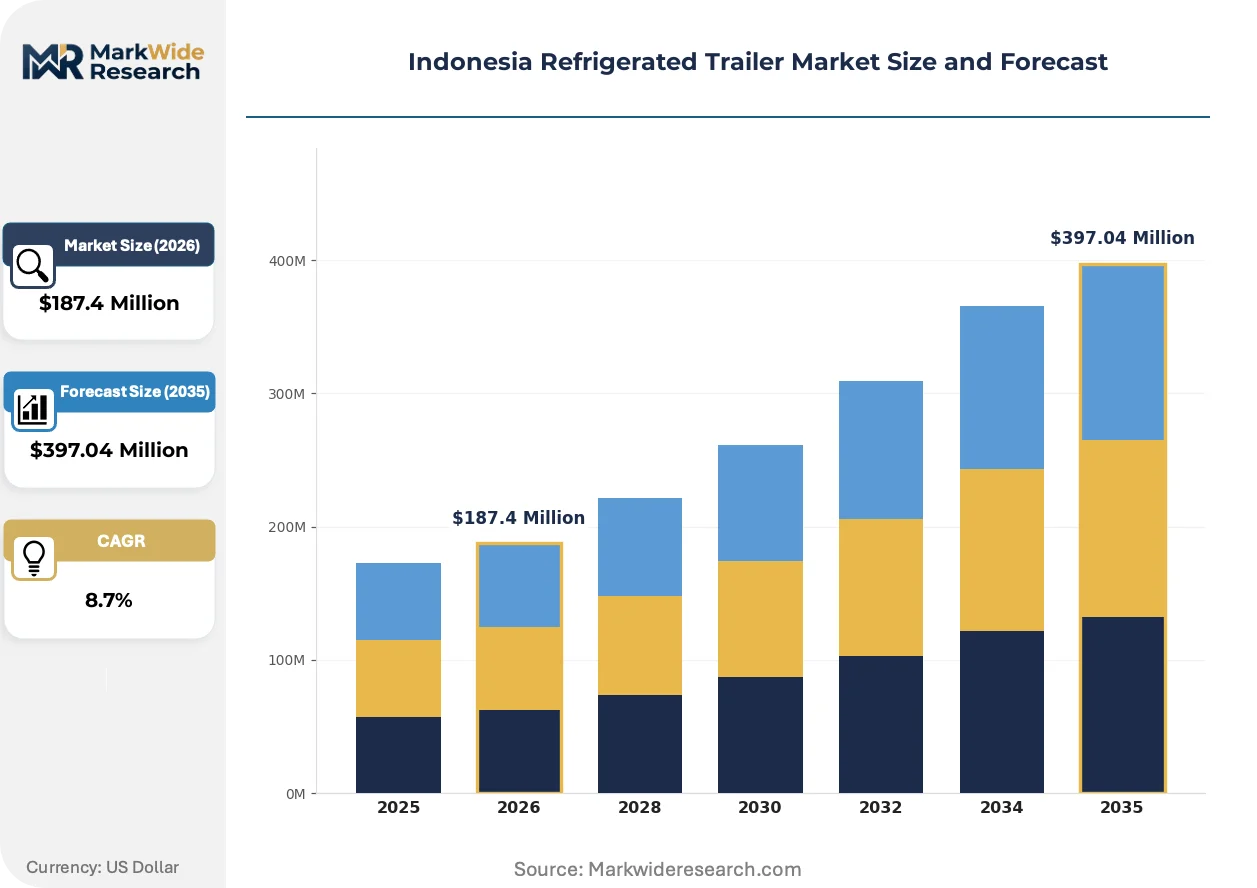
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Single Axle, Tandem Axle, Multi Axle, Ultra-Low Temperature Payload Capacity: Less than 5 Tons, 5-10 Tons, 10-15 Tons, Above 15 Tons End User: Food & Beverage, Pharmaceuticals, Agriculture, Logistics Cooling Technology: Direct Expansion, Refrigeration Units, Cryogenic, Others |
| Companies Covered | PT Siba Surya, PT Wahana Prestasi Logistik, PT Kamadjaja Logistics, PT Serasi Autoraya, PT Puninar Logistics, Schmitz Cargobull AG, Wabash National Corporation, Great Dane LLC, Trane Technologies Company LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Refrigerated Trailer Market Trends and Innovations
Refrigeration technology and fleet procurement models are diverging sharply as pharmaceutical-grade requirements separate from commodity food logistics, creating parallel specification tracks within the same asset class.
Direct expansion cooling systems dominate Indonesia's installed base, maintaining cargo temperatures through compressor-driven refrigerant cycles. Pharmaceutical shippers are adopting cryogenic alternatives at accelerating rates, seeking to eliminate mechanical maintenance burdens on remote island routes. The technology landscape is bifurcating into compressor-dependent systems for high-volume Java corridors versus cryogenic units for archipelago-wide vaccine distribution.
BIS certification requirements for thermal insulation performance now mandate standardized panel testing protocols. Compliance gates access to cold-chain infrastructure subsidies, redirecting capital toward certified suppliers. Domestic fleet operators are responding by consolidating procurement around pre-qualified fiberglass and aluminum skin fabricators.
Service contracting is unbundling from hardware procurement, with FMCG clients demanding uptime guarantees separate from capital lease arrangements. Third-party maintenance networks are displacing manufacturer-captive service in Surabaya and Jakarta. Pharmaceutical distributors lead this shift, prioritizing rapid-response repair commitments over initial acquisition cost.
Indonesia Refrigerated Trailer Market Segmentation
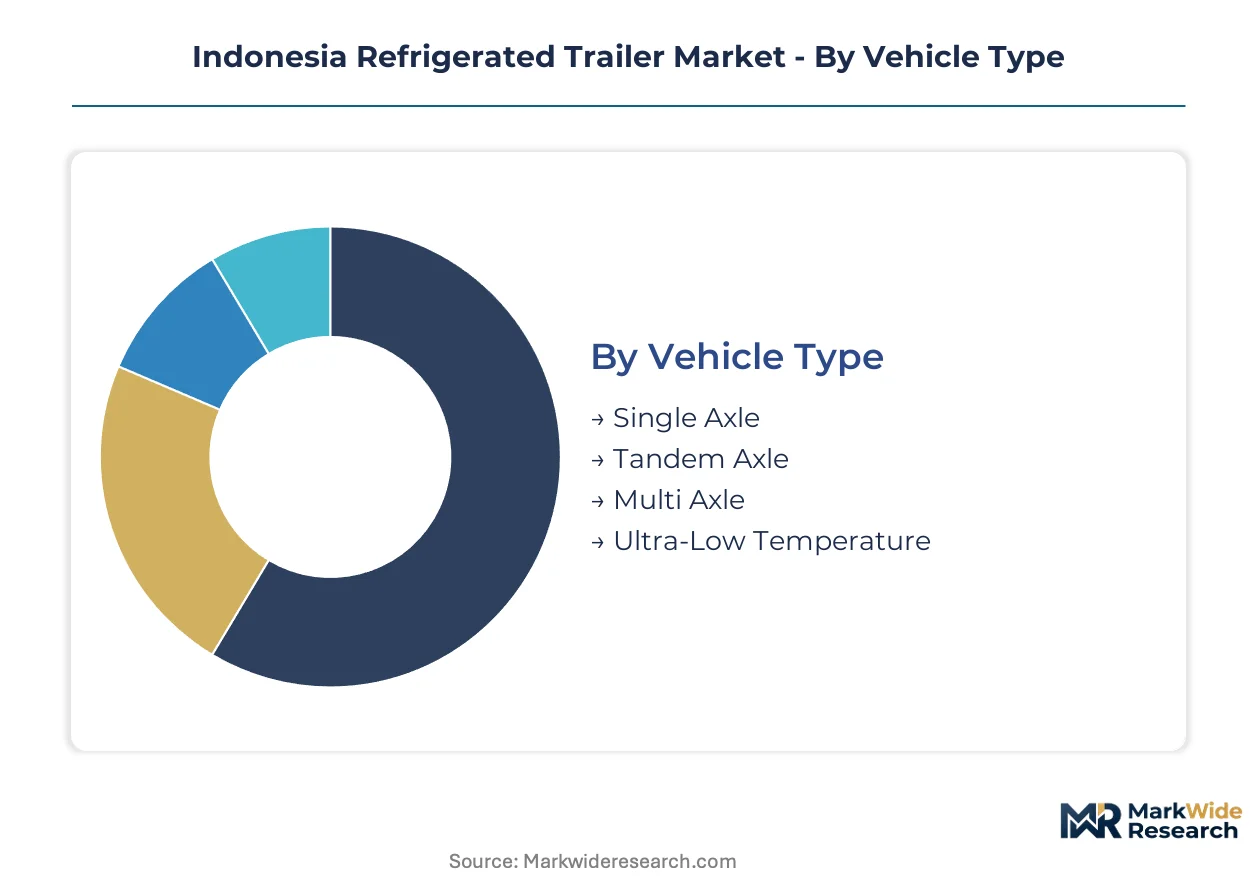
Segmentation in Indonesia's refrigerated trailer market reveals how fleet operators balance axle-weight compliance, thermal performance requirements, and payload economics across Java's toll-road corridors and inter-island shipping routes. Understanding these category boundaries exposes where procurement budgets concentrate and where specification gaps create substitution risks.
Vehicle Type:
Margin pools concentrate in configurations that optimize toll-road axle-weight compliance while maximizing cubic capacity for high-value pharmaceutical and fresh produce cargo.
- Tandem Axle:Dual-axle configurations distribute gross vehicle weight across four wheels, satisfying Ministry of Transportation limits on Java's arterial highways while preserving 28-32 pallet positions. Surabaya-Jakarta corridor operators favor this specification for its payload flexibility and toll-rate efficiency.
- Single Axle:Lighter two-wheel units dominate last-mile distribution in Jakarta's urban core where maneuverability trumps cubic capacity. BIS certification requirements are accelerating replacement cycles for aging single-axle fleets seeking subsidy eligibility.
- Multi Axle:Tri-axle and quad-axle variants serve Kalimantan mining corridor contracts requiring extreme gross weight tolerance on unpaved feeder roads.
- Ultra-Low Temperature:Specialized trailers maintain minus 30 degrees Celsius for vaccine distribution, commanding premium lease rates from Ministry of Health contractors.
The dominant share belongs to Tandem Axle configurations, while Ultra-Low Temperature units are expanding most quickly on pharmaceutical cold-chain contracts.
Payload Capacity:
Procurement patterns track the divergence between Java's dense supermarket distribution networks and Sulawesi's sparse agricultural collection routes.
- 5-10 Tons:Mid-range capacity captures the sweet spot for FMCG distributors serving Jakarta's modern trade channels, balancing turn-around speed with per-trip revenue. PT Puninar Logistics standardizes on this segment for captive maintenance fleet efficiency.
- 10-15 Tons:Heavy-mid units dominate fresh produce export consolidation from Surabaya's Tanjung Perak port, where single-container economics justify longer loading windows. Supermarket compliance standards are pulling exporters toward this capacity tier.
- Less than 5 Tons:Compact units serve urban pharmaceutical last-mile where temperature integrity demands outweigh cubic efficiency.
- Above 15 Tons:Maximum-capacity trailers concentrate in Cikarang industrial zone bulk dairy movements, constrained by axle-load regulations on Trans-Java toll roads.
Procurement gravity centers on 5-10 Tons for FMCG density, though 10-15 Tons is climbing the fastest on export compliance pressures.
End User:
Customer-type economics separate commodity food logistics from pharmaceutical-grade cold-chain requirements, creating parallel specification tracks.
- Food & Beverage:The largest demand pool spans dairy, frozen processed foods, and beverage distribution through Java's supermarket networks. Direct expansion cooling dominates this segment due to lower capital intensity and established service infrastructure.
- Pharmaceuticals:Vaccine and biologics distributors mandate redundant cooling systems and real-time temperature logging, driving specification divergence from commodity food logistics. PT Kamadjaja Logistics anchors its Surabaya-Jakarta pharmaceutical dominance through dedicated reefer pools.
- Agriculture:Fresh produce exporters serving Singapore and Malaysia impose supermarket chain compliance standards that accelerate fleet renewal cycles.
- Logistics:Third-party cold-chain operators aggregate demand across end-use segments, prioritizing modular payload reconfiguration capabilities.
Food & Beverage retains the largest installed base, while Pharmaceuticals is gaining share fastest on Good Distribution Practice mandate expansion.
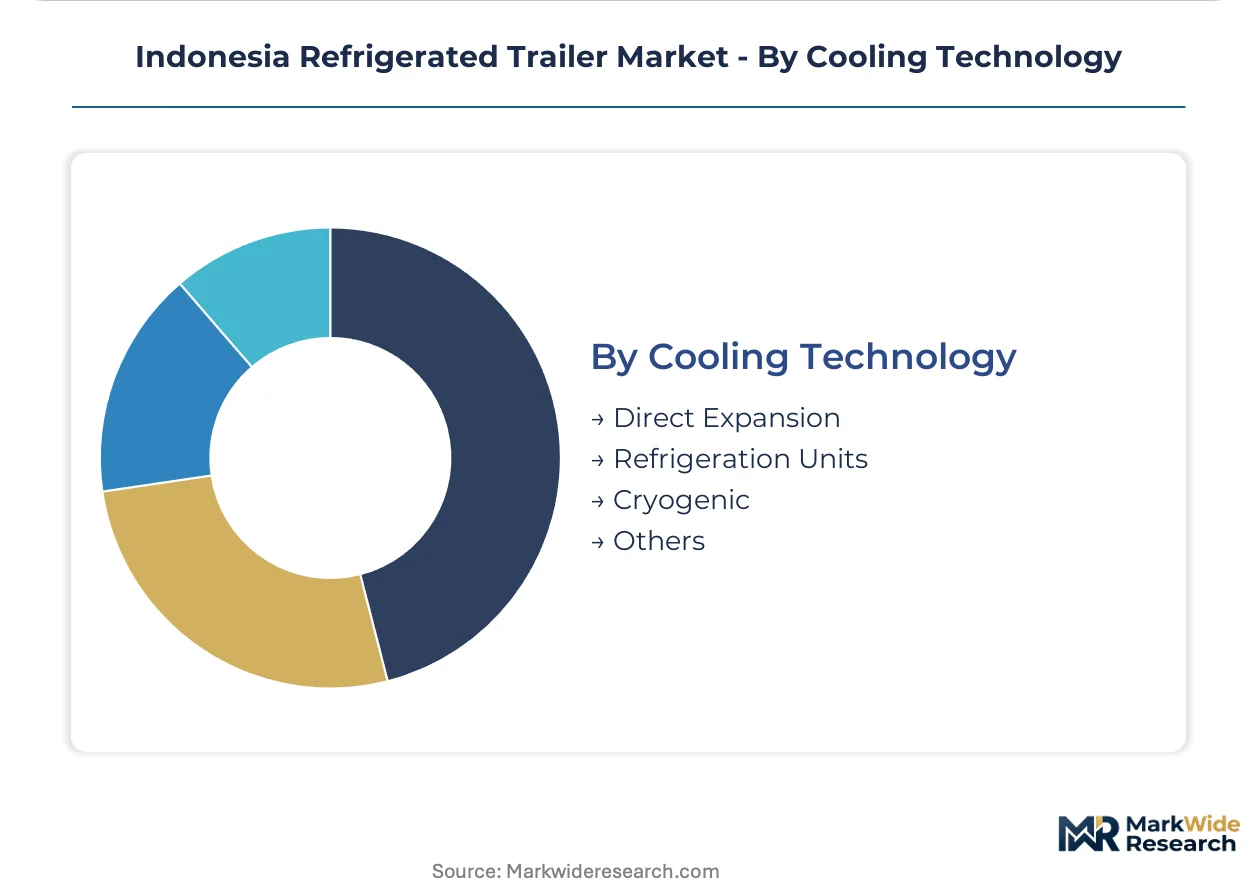
Cooling Technology:
Technology selection hinges on maintenance access, with compressor-dependent systems favored in Java's dense service networks and cryogenic alternatives penetrating remote archipelago routes.
- Direct Expansion:Compressor-driven refrigerant cycles occupy the largest installed base, leveraging established spare parts distribution and technician training networks across Java. Schmitz Cargobull AG's modular units enable rapid reconfiguration within this technology class.
- Cryogenic:Liquid nitrogen and carbon dioxide systems eliminate mechanical maintenance burdens, attracting pharmaceutical shippers operating Sulawesi and Papua vaccine distribution corridors where service infrastructure is sparse.
- Refrigeration Units:Self-contained engine-powered systems serve inter-island ferry transfers where shore power is unavailable.
- Others:Emerging eutectic plate and hybrid electric technologies pilot in Jakarta's urban emission-restricted zones.
Direct Expansion systems command the dominant installed position, while Cryogenic alternatives are expanding most rapidly on remote-route pharmaceutical contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tanjung Priok Port's container terminal expansion underwrites Jakarta's dominance in pharmaceutical cold-chain throughput, while Surabaya's Tanjung Perak facilities anchor fresh produce export consolidation for supermarket compliance chains.
Java
Surabaya-Jakarta corridor operators command premium reefer deployment density as FMCG distributors and pharmaceutical contractors compete for limited tandem-axle capacity. Ministry of Transportation axle-load regulations on Trans-Java toll roads constrain payload optimization despite higher unit economics. Cikarang industrial zone bulk dairy movements and Bekasi distribution clusters absorb the heaviest trailer procurement volumes.
Sumatra
Medan's palm oil processing complexes and Belawan port export lanes generate steady demand for multi-axle configurations on unpaved feeder roads. BIS thermal insulation certification requirements are accelerating fleet replacement cycles as operators seek subsidy eligibility for government-backed cold-chain programs. Palembang's rubber and agro-industrial corridors concentrate regional maintenance facility investment.
Sulawesi
Makassar's emerging pharmaceutical distribution nodes pull cryogenic cooling system adoption as vaccine logistics extend into remote island routes where compressor maintenance infrastructure remains sparse. Ministry of Health Good Distribution Practice mandates tighten temperature integrity requirements for archipelago-wide biologics distribution. Kendari and Manado agricultural collection points create first-mover opportunities for modular payload reconfiguration capabilities.
Kalimantan
Balikpapan's mining corridor contracts and Samarinda coal logistics generate specialized demand for extreme gross weight tolerance on deteriorated road surfaces. Axle-load regulatory friction limits tandem-axle optimization despite higher payload economics. Pontianak's palm oil consolidation points and border trade routes with Malaysia concentrate regional reefer leasing activity.
Papua
Jayapura's vaccine distribution corridors and Timika mining supply chains drive cryogenic system penetration where mechanical refrigeration service networks cannot reach. Inter-island shipping fuel sulfur specifications will force port-side reefer power protocol reconfiguration, delaying electrification timelines. Merauke's agricultural frontier expansion creates nascent demand for ultra-low temperature pharmaceutical-grade trailers.
Indonesia Refrigerated Trailer Market Competitive Landscape
Listed leaders compete with private specialists across service contracting and captive maintenance capabilities, creating a tiered structure where scale-driven fabricators anchor premium segments and domestic logistics operators control fleet deployment density. Strategic archetypes separate port-centric depot network operators, in-house maintenance facility consolidators, and modular cooling technology licensors. Competitive moves concentrate on geographic expansion through regional depot licensing and backward integration into panel fabrication to secure BIS certification compliance.
Among Indonesia-based logistics operators, PT Kamadjaja Logistics, PT Puninar Logistics, and PT Siba Surya exemplify the port-centric depot archetype, leveraging Surabaya and Jakarta distribution density to lock in pharmaceutical and FMCG contract stickiness. Schmitz Cargobull AG represents the modular cooling technology tier, occupying a position in rapid payload reconfiguration between frozen and chilled cargo specifications. These anchors illustrate how domestic fleet operators compete against European fabricators on service network depth rather than manufacturing scale.
| Leading Market Players |
|---|
| PT Siba Surya |
| PT Wahana Prestasi Logistik |
| PT Kamadjaja Logistics |
| PT Serasi Autoraya |
| PT Puninar Logistics |
| Schmitz Cargobull AG |
| Wabash National Corporation |
| Great Dane LLC |
| Trane Technologies Company LLC |
| Others |
Pricing and Supply Chain Analysis
Long-term fleet lease contracts with embedded maintenance obligations lock in both polyurethane panel supply access and price visibility for Indonesian operators navigating BIS certification timelines. These arrangements insulate domestic assemblers from petrochemical feedstock volatility while forcing smaller fleet operators toward spot procurement with compressed margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade cryogenic units from commodity direct-expansion reefers and aging single-axle conversions. Price differentiation hinges on BIS thermal certification grade and captive maintenance bundling. Cost compression in the economy tier is intensifying because domestic fabricators face margin pressure from imported fiberglass skin pricing. Smallholder agricultural exporters exhibit highest price sensitivity, while vaccine distributors prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Strait of Malacca petrochemical transit underwrites Indonesia's polyurethane foam core supply, creating vulnerability to maritime logistics disruptions. Manufacturing concentrates in China, South Korea, and domestic Cikarang industrial zone facilities for aluminum skin fabrication and refrigeration unit assembly. The supply chain rests on imported compressor components and liquid nitrogen cryogenic systems. Single-source vulnerability runs through European cooling unit licensors. Distribution runs through Surabaya and Jakarta port-centric depot networks with captive maintenance facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's refrigerated trailer market is approaching a platform-economics inflection as service contracting unbundles from hardware procurement, creating interoperability standards between fleet operators and pharmaceutical distributors.
For Market Incumbents: Compound port-centric depot density in Surabaya and Jakarta to lock in pharmaceutical cold-chain contracts before cryogenic system adoption accelerates. Deepen backward integration into BIS-certified panel fabrication to secure subsidy eligibility gates. Threat substitution from modular cooling licensors like Schmitz Cargobull demands faster captive maintenance response commitments. For New Entrants and Emerging Players: Lead with cryogenic cooling deployment in Sulawesi and Papua vaccine corridors where compressor service infrastructure remains sparse. White-space targets include Kendari agricultural collection routes and Merauke pharmaceutical frontier expansion. Go-to-market angle centers on guaranteed uptime contracts with Ministry of Health contractors seeking to eliminate mechanical maintenance burdens. For Investors and Strategic Acquirers: Port-centric logistics operators with captive maintenance networks represent the highest-conviction acquisition archetype for pharmaceutical cold-chain exposure. Long-term viability frames around electrification readiness as inter-island shipping fuel sulfur specifications force port-side power protocol reconfiguration. Signal to watch is BIS certification queue compression accelerating fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Fabrication | Captive BIS-certified supply secures subsidy access gates for domestic fleet operators. |
| Cryogenic System Deployment | Liquid nitrogen cooling eliminates compressor maintenance burdens on remote Sulawesi routes. |
| Captive Maintenance Network Expansion | In-house service capabilities lock in FMCG client stickiness through guaranteed uptime contracts. |
| Modular Cooling Unit Licensing | Rapid payload reconfiguration between frozen and chilled cargo enables asset utilization flexibility. |
| Port-Centric Depot Licensing | Regional expansion through Surabaya-Jakarta corridor density captures pharmaceutical distribution concentration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across fleet procurement directors, pharmaceutical logistics managers, BIS certification auditors, and refrigeration unit service technicians. Secondary validation drew from Ministry of Transportation axle-load regulation filings, Ministry of Health Good Distribution Practice mandates, BIS thermal performance standards, and customs import data for polyurethane foam feedstocks. Bottom-up fleet inventory estimates triangulated against top-down cold-chain infrastructure subsidy disbursement records.
Across the analysis window, volume and value outputs reflect segmented modeling across vehicle type, payload capacity tier, end-use application, and cooling technology architecture. CAGRs were derived from installed base replacement cycles, export compliance mandate expansion, and pharmaceutical distribution network growth. Forecast inputs incorporated BIS certification timeline projections and inter-island shipping fuel specification transition schedules.
The analysis sits within stated boundaries; outcomes outside sustained government subsidy disbursement or accelerated cryogenic adoption curves would require recalibration. Forecasts reflect assumptions around regulatory compliance timelines and petrochemical input cost stability. Practitioners should keep alternative scenarios live as sulfur fuel specifications and electrification investment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Germany Cold Chain Logistics Market
Transportation & Logistics
Europe Customs Brokerage Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Europe Refrigerated Transport Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Spain Road Freight Transport Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Europe Fleet Management Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Ride-Hailing and Taxi Market