
 United States Refrigerated Transport Market | 2026-2036
United States Refrigerated Transport Market Size, Share, and Industry Trends Forecast 2026-2036
United States Refrigerated Transport Market Intelligence
Trailer manufacturing capacity across the Upper Midwest is broadening as domestic producers respond to fleet replacement cycles. Americold Logistics sustains one of the largest temperature-controlled warehouse and distribution networks nationwide. Knight-Swift Transportation anchors its refrigerated division through dedicated lane density in the Southeast and Southwest corridors. J.B. Hunt competes by integrating intermodal refrigerated containers with its rail partnerships.
Refrigerated transport encompasses temperature-controlled movement of perishable goods using insulated vehicles equipped with mechanical or cryogenic cooling systems capable of maintaining precise thermal ranges from frozen to chilled conditions. The primary commercial purpose centers on preserving product integrity across pharmaceutical, food, and chemical supply chains where thermal deviation compromises safety or efficacy. Reefer trucks dominate current fleet composition due to route flexibility and last-mile accessibility, while intermodal service types capture expanding margin pools as rail electrification reduces long-haul fuel exposure. Pharmaceutical end users represent the fastest-growing demand segment as biologics and vaccine distribution tighten cold-chain specifications.
The FDA Food Safety Modernization Act and EPA Phase 2 greenhouse gas standards jointly shape equipment specifications, mandating both temperature traceability and cleaner powertrain configurations for interstate commerce. DOT hours-of-service regulations further constrain operational models, pushing fleets toward dedicated service contracts that optimize driver utilization. Stakeholders must monitor emerging refrigerant phase-down rules under AIM Act implementation, as hydrofluorocarbon restrictions will force equipment retrofits and accelerate adoption of cryogenic alternatives.
Market Dynamics
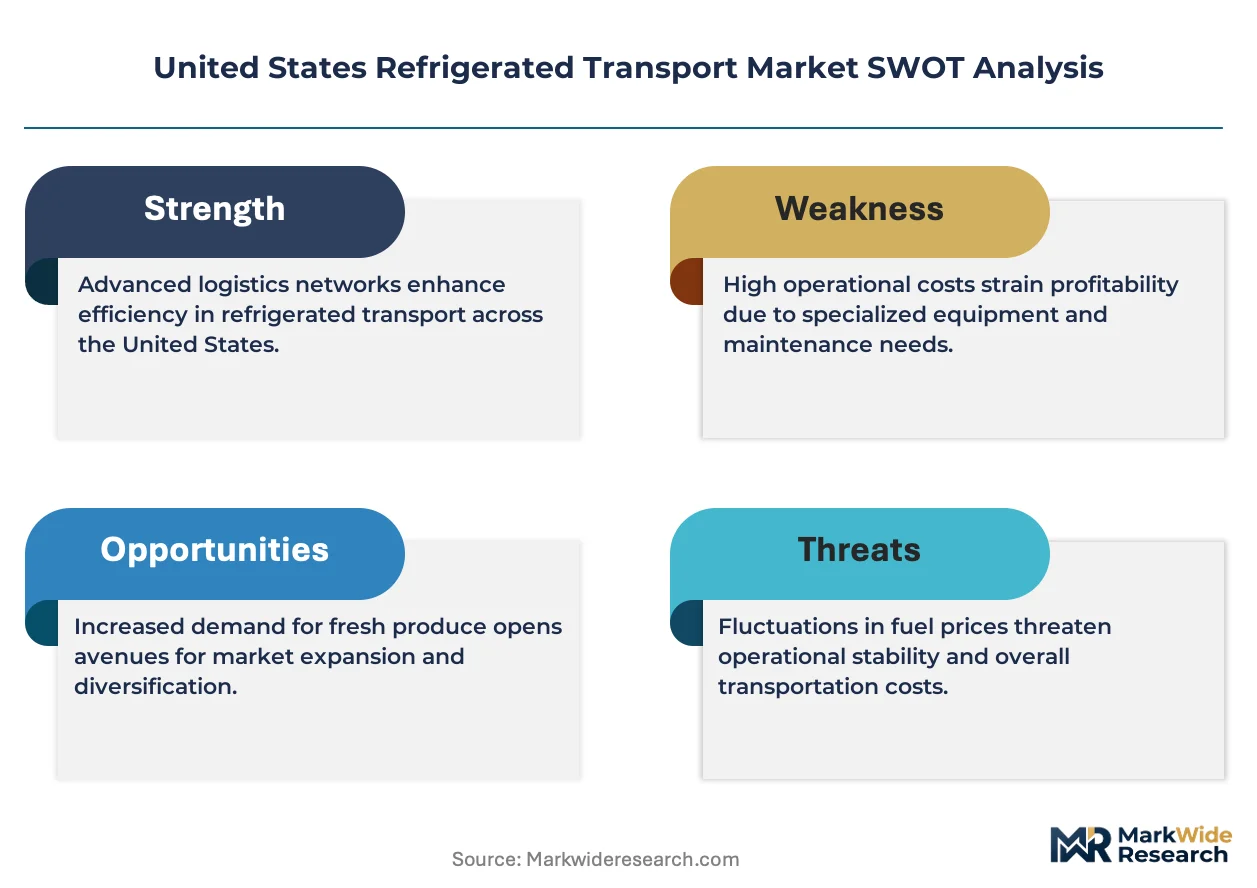
Fleet operators across the United States are recalibrating capital deployment around electrification timelines and refrigerant phase-down mandates. The collision of EPA powertrain standards with AIM Act hydrofluorocarbon restrictions is forcing simultaneous powertrain and thermal-system overhauls.
Growth Catalysts
- Biologics cold-chain expansion:Pharmaceutical distributors are tightening temperature specifications for cell therapies and mRNA products. FDA validation requirements for thermal packaging are extending contract lengths with qualified carriers.
- FSMA traceability mandates:The Food Safety Modernization Act's enhanced recordkeeping rules are pushing shippers toward integrated telematics platforms. Compliance investments are locking in carrier relationships with verified temperature documentation.
- Intermodal rail electrification:BNSF and Union Pacific corridor upgrades are absorbing long-haul volume from diesel-intensive trucking. Refrigerated container stacking density on electrified routes is improving unit economics for cross-country produce movements.
Market Restraints
- Refrigerant supply concentration:Domestic hydrofluorocarbon production is consolidating around three chemical manufacturers. Import dependency for next-generation cryogenic fluids is exposing fleets to quota allocation delays.
- Driver availability constraints:DOT hours-of-service regulations are compressing effective duty windows for long-haul refrigerated routes. Specialized reefer certification requirements are narrowing the qualified labor pool further.
- Trailer manufacturing bottlenecks:Insulated panel production is concentrated in the Upper Midwest steel corridor. Lead times for composite refrigeration units are extending fleet replacement cycles beyond optimal depreciation schedules.
Strategic Opportunities
- Last-mile pharmaceutical hubs:Urban hospital networks and specialty pharmacies in Texas and Florida are demanding direct-to-door cold-chain delivery. Micro-fulfillment temperature controls are creating margin pools distinct from long-haul freight.
- Renewable diesel compatibility:EPA renewable fuel standard credits are improving total-cost-of-ownership calculations for compliant powertrains. Early fleet adopters are securing preferential fuel contracts with biodiesel refiners in the Gulf Coast corridor.
- Blockchain traceability integration:Walmart and Kroger supplier mandates are creating demand for immutable temperature logging. Carriers with validated digital chain-of-custody systems are winning dedicated produce contracts.
Industry Challenges
- Telematics integration complexity:Legacy refrigeration units lack native API connectivity with modern fleet management platforms. Retrofit hardware costs are eroding margins on mid-life trailer assets.
- Refrigerant technician certification gaps:Section 608 technician credentials for low-GWP alternatives are not scaling with equipment deployment timelines. Training program capacity is lagging OEM service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Refrigerated Transport Market |
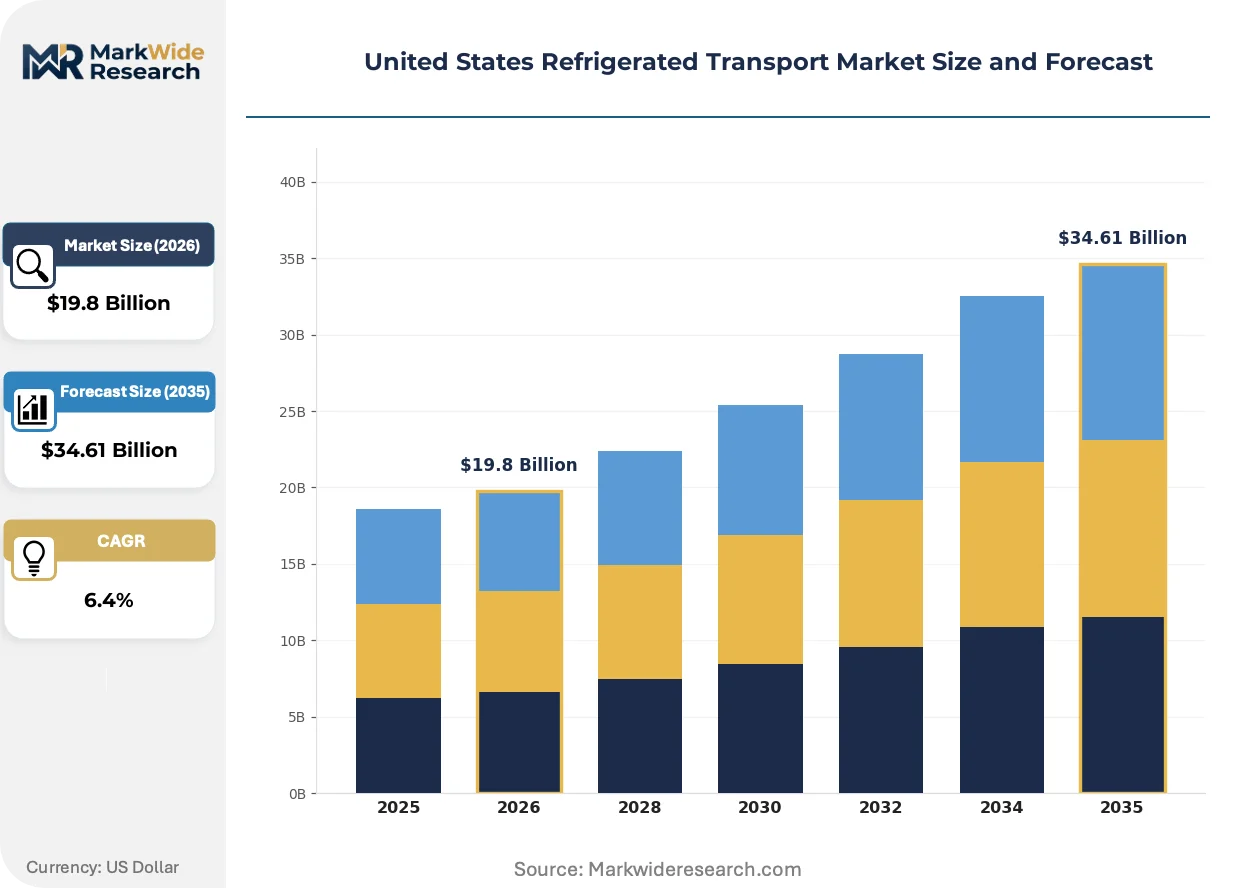
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Reefer Trucks, Refrigerated Trailers, Shipping Containers, Railcars Temperature Control Method: Mechanical, Cryogenic, Refrigeration Unit, Passive End User: Food & Beverage, Pharmaceuticals, Chemicals, Agriculture Service Type: Full Truckload, Less Than Truckload, Intermodal, Dedicated |
| Companies Covered | Americold Logistics, Knight-Swift Transportation, J.B. Hunt, C.H. Robinson Worldwide, Lineage Logistics, Prime Inc., Marten Transport, KLLM Transportation Services, Stevens Transport, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Refrigerated Transport Market Strategic Shifts & Innovations
Refrigerated transport in the United States is absorbing digitalization pressures from adjacent logistics sectors while confronting simultaneous thermal and mechanical system transitions. Technology convergence is compressing decision horizons for capital-intensive fleet investments.
Electric auxiliary power units are absorbing overnight idle reduction mandates from California Air Resources Board and pending EPA state waiver expansions. Foodservice distributors with urban delivery density are deploying battery-electric reefers for last-mile routes under 150 miles. The technology is absorbing compliance risk while transferring energy cost exposure from diesel price volatility to utility rate structures.
The AIM Act hydrofluorocarbon phase-down is forcing refrigerant transitions ahead of equipment replacement cycles. Fleet maintenance departments are retrofitting existing units with CO2 or propane-based systems to avoid stranded assets. California and Washington state implementations are running ahead of federal timelines, creating bifurcated compliance obligations for interstate operators.
Shipper procurement patterns are consolidating around carriers with validated temperature performance data. Large grocery retailers are unbundling transportation from warehousing contracts to source refrigerated lanes independently. This disintermediation is most visible in the Southeast produce corridor, where direct carrier relationships are displacing traditional freight broker intermediation.
United States Refrigerated Transport Market Segmentation
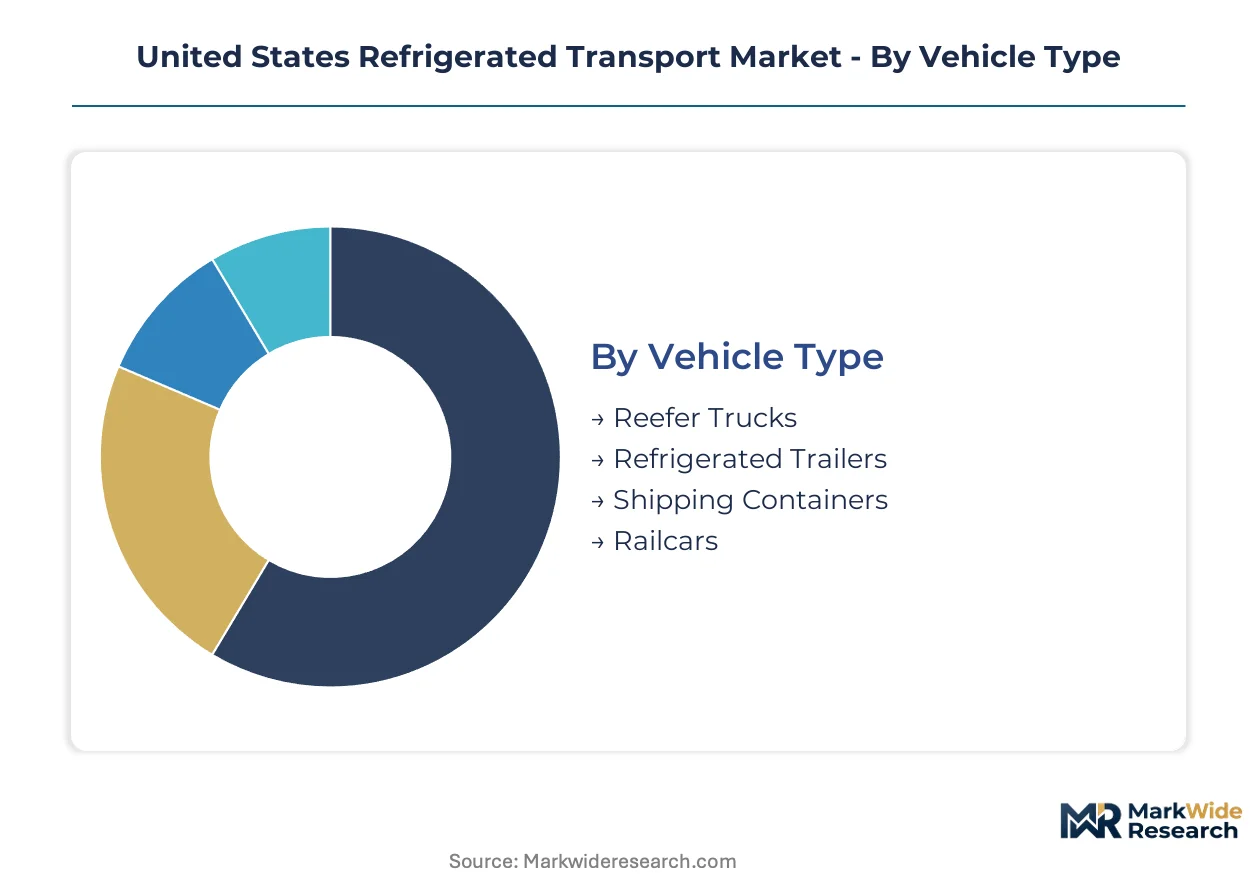
Refrigerated transport procurement decisions split across equipment specifications, thermal technology, cargo sensitivity, and service reliability. Fleet operators and shippers weight these dimensions differently based on route length, cargo value density, and regulatory exposure. Understanding how demand concentrates within each axis clarifies where capital deployment and contract negotiations generate sustainable margin.
Vehicle Type:
Fleet procurement prioritizes route flexibility against capital intensity and fuel exposure across modal alternatives.
- Reefer Trucks:Insulated box trucks with integrated mechanical refrigeration units dominate last-mile produce delivery and urban pharmaceutical distribution. Demand clusters in Florida and California produce corridors where frequent stops and variable dwell times require rapid temperature recovery. Driver certification requirements and California Air Resources Board idle restrictions are compressing effective duty cycles for smaller operators.
- Refrigerated Trailers:Detachable insulated semi-trailers with diesel-powered refrigeration units anchor long-haul interstate movements. Volume concentrates in the Great Lakes-Midwest corridor where food processing clusters intersect with I-80 and I-90 freight corridors. Trailer manufacturing bottlenecks in the Upper Midwest steel corridor are extending replacement cycles and forcing fleet extensions beyond optimal depreciation schedules.
- Shipping Containers:Intermodal refrigerated boxes with clip-on genset power enable ocean-rail-truck handoffs for import-dependent produce and frozen proteins. Port congestion at Los Angeles-Long Beach and Savannah is creating chassis availability constraints.
- Railcars:Insulated boxcars with mechanical refrigeration serve bulk frozen commodity movements between interior processing plants and coastal export terminals. BNSF and Union Pacific corridor electrification is absorbing volume from diesel-intensive trucking on transcontinental lanes.
Volume sits with refrigerated trailers; growth tilts toward reefer trucks.
Temperature Control Method:
Shipper compliance requirements and refrigerant phase-down timelines are forcing thermal system selections ahead of equipment replacement cycles.
- Mechanical:Vapor-compression systems using hydrofluorocarbon refrigerants remain the installed base standard for controlled chilled and frozen ranges. FDA Food Safety Modernization Act traceability mandates are locking in carrier relationships with verified temperature documentation. AIM Act hydrofluorocarbon quotas are forcing premature retrofit decisions.
- Cryogenic:Liquid nitrogen or carbon dioxide injection systems deliver ultra-low temperatures for cell therapies and mRNA distribution without compressor maintenance. Pharmaceutical end users in Texas and Florida hospital networks are demanding direct-to-door cold-chain delivery with cryogenic backup redundancy.
- Refrigeration Unit:Self-contained diesel-powered or electric auxiliary power units provide continuous cooling independent of tractor power. California Air Resources Board overnight idle reduction mandates are accelerating electric APU adoption for urban delivery density.
- Passive:Insulated packaging with phase-change materials maintains thermal ranges for 48-96 hours without active power. Vaccine distribution networks are validating passive systems for last-mile rural delivery where mechanical reliability is uncertain.
Mechanical systems retain volume dominance; cryogenic configurations are expanding most quickly.
End User:
Cargo value density and temperature tolerance windows determine carrier qualification requirements and contract structures.
- Food & Beverage:Perishable produce, dairy, meat, and frozen prepared foods require continuous chilled or frozen transit with minimal deviation. Walmart and Kroger supplier mandates are creating demand for immutable temperature logging through blockchain traceability integration.
- Pharmaceuticals:Biologics, vaccines, and cell therapies demand validated cold-chain with documented chain-of-custody. FDA validation requirements for thermal packaging are extending contract lengths with qualified carriers.
- Chemicals:Temperature-sensitive industrial compounds and specialty adhesives require controlled transit without cross-contamination protocols. Hazmat certification requirements narrow the qualified carrier pool.
- Agriculture:Livestock semen, breeding embryos, and specialty seed stock require precise thermal maintenance for genetic viability. Seasonal demand peaks align with planting and breeding cycles.
Food and beverage commands volume; pharmaceuticals are gaining share fastest.
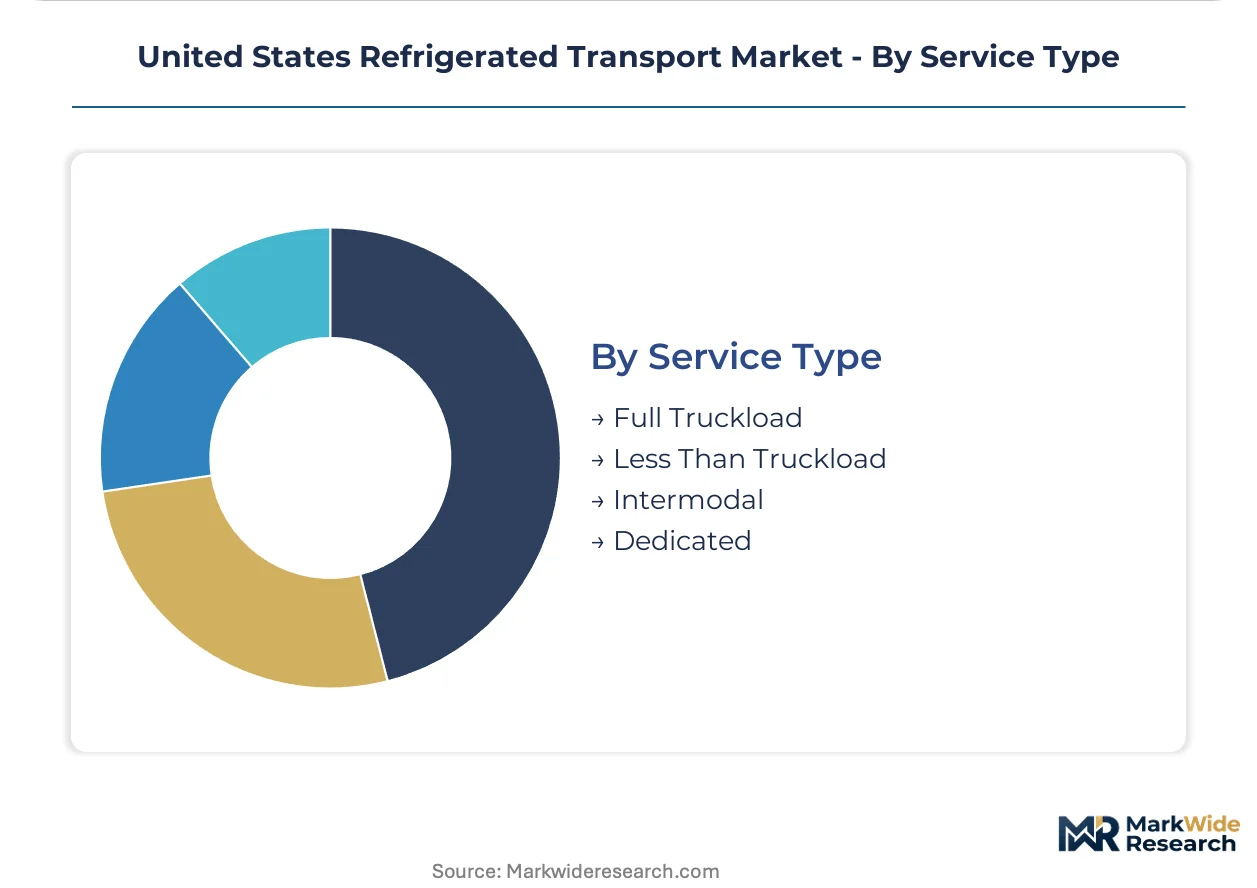
Service Type:
Shipper network design balances asset utilization, transit time reliability, and modal cost exposure against cargo sensitivity.
- Full Truckload:Dedicated trailer capacity for single-shipper movements minimizes handling and temperature deviation risk. Knight-Swift Transportation anchors refrigerated division through dedicated lane density in the Southeast and Southwest corridors.
- Less Than Truckload:Consolidated multi-shipper movements with hub-and-spoke terminal handling for smaller freight volumes. Terminal cross-dock operations introduce temperature recovery risks that pharmaceutical shippers avoid.
- Intermodal:Rail-truck combinations leveraging BNSF and Union Pacific electrified corridors for long-haul fuel cost reduction. J.B. Hunt competes by integrating intermodal refrigerated containers with rail partnerships.
- Dedicated:Contracted fleet capacity reserved for specific shipper networks with guaranteed equipment and driver assignment. DOT hours-of-service regulations are pushing fleets toward dedicated service contracts that optimize driver utilization.
Full truckload retains volume concentration; intermodal is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel production in the Upper Midwest feeds insulated panel manufacturing that supplies trailer assembly plants across Wisconsin and Indiana. This raw-material proximity anchors domestic refrigerated transport equipment production. Interstate highway density and food processing clusters determine where temperature-controlled freight concentrates.
Great Lakes-Midwest Corridor
Food processing plants in Illinois, Michigan, and Ohio generate continuous outbound refrigerated volume. FDA Food Safety Modernization Act traceability mandates push shippers toward carriers with verified temperature documentation. Chicago and Detroit distribution hubs absorb produce from Pacific Northwest and Southeast growing regions for redistribution.
Southeast Produce Belt
Florida vegetable harvests and Georgia poultry processing sustain year-round temperature-controlled demand. DOT hours-of-service regulations compress effective duty windows for long-haul routes serving Atlanta and Miami distribution centers. Knight-Swift Transportation anchors dedicated lane density through this corridor.
Southwest Border Zone
Cross-border produce imports from Mexico through Laredo and Nogales require rapid cold-chain handoffs. EPA Phase 2 greenhouse gas standards shape equipment specifications for fleets operating Texas-to-California lanes. J.B. Hunt integrates intermodal refrigerated containers with Union Pacific rail partnerships through this zone.
Pacific Northwest
Washington apple exports and Oregon dairy processing feed refrigerated outbound movements. California Air Resources Board idle reduction mandates accelerate electric auxiliary power unit adoption for fleets serving Seattle and Portland urban delivery zones. Port congestion at Tacoma affects chassis availability for intermodal refrigerated containers.
California Central Valley
Specialty crop harvests from Fresno to Bakersfield generate concentrated seasonal refrigerated demand. AIM Act hydrofluorocarbon phase-down rules run ahead of federal timelines, forcing premature equipment retrofit decisions. Americold Logistics sustains temperature-controlled warehouse networks in Stockton and Ontario to buffer harvest volatility.
United States Refrigerated Transport Market Key Industry Players
Global majors compete with regional champions across fleet scale and lane density in the United States refrigerated transport sector. The market structure tiered between national integrated carriers with dedicated refrigerated divisions and specialized temperature-controlled operators with geographic concentration. Three archetypes dominate: warehouse-integrated logistics platforms, asset-heavy trucking carriers with dedicated reefer fleets, and intermodal specialists leveraging rail partnerships. Consolidation through fleet acquisitions and exclusive lane contracts represents the primary competitive dynamic.
Among warehouse-integrated operators, Americold Logistics and Lineage Logistics exemplify the cold-storage-plus-transport model. Knight-Swift Transportation and J.B. Hunt anchor the asset-heavy carrier tier with distinct strategic positioning. These named entities occupy positions that illustrate how scale, lane density, and modal integration separate competitive tiers rather than competing head-to-head on identical service attributes.
| Leading Market Players |
|---|
| Americold Logistics |
| Knight-Swift Transportation |
| J.B. Hunt |
| C.H. Robinson Worldwide |
| Lineage Logistics |
| Prime Inc. |
| Marten Transport |
| KLLM Transportation Services |
| Stevens Transport |
| Others |
Cost & Logistics Intelligence
Certified reefer technician concentration across the Upper Midwest steel corridor feeds labor-cost differentials that widen pricing-tier spreads between premium validated carriers and commodity freight brokers. Specialized Section 608 credentials for low-GWP refrigerant systems command wage premiums that filter into dedicated contract rates versus spot-market lanes.
Pricing Analysis
Warranty and service-bundling decisions separate premium carriers from price competitors, with multi-year maintenance contracts and temperature-validated service level agreements bundled into dedicated arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and telematics integration depth. Cost compression in the economy tier intensifies as freight brokers compete on spot rates with minimal compliance documentation. Pharmaceutical shippers show least price sensitivity due to FDA validation requirements, while produce distributors operating on thin margins exhibit highest sensitivity to per-mile rates.
Supply Chain Analysis
Single-source vulnerability sits with hydrofluorocarbon refrigerant production concentrated among three domestic chemical manufacturers. Insulated panel manufacturing draws from steel feedstock anchored in Indiana and Ohio, while compressor units rest on German and Japanese component imports. Tariff exposure on cryogenic fluid imports creates quota allocation risk for fleets retrofitting ahead of AIM Act deadlines. Distribution runs through food processing clusters in the Great Lakes-Midwest corridor before radiating to coastal consumption centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States refrigerated transport functions as a consolidation play where refrigerant phase-down mandates and electrification capital requirements force sub-scale operators toward exit or acquisition. AIM Act compliance timelines compress decision horizons for fleet replacement cycles.
For Market Incumbents: Lock in dedicated lane density through exclusive contracts with pharmaceutical distributors tightening FDA validation requirements. Secure captive maintenance capacity by backward integration into certified technician training programs. Knight-Swift Transportation's Southeast corridor anchoring demonstrates how lane concentration defends against freight broker disintermediation.
For New Entrants and Emerging Players: Urban hospital networks and specialty pharmacies in Texas and Florida represent underserved buyer archetypes demanding direct-to-door cryogenic delivery with redundant backup systems. Last-mile pharmaceutical hubs with micro-fulfillment temperature controls offer penetrable white space distinct from long-haul freight commoditization. Go-to-market positioning should emphasize validated digital chain-of-custody systems meeting Walmart and Kroger supplier mandates.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional carriers possessing established lane density in the Southeast produce belt given intermodal rail electrification catalysts absorbing long-haul volume. Long-term viability over the coming decade favors operators with integrated warehouse-transport platforms and renewable diesel compatibility. Watch BNSF and Union Pacific corridor upgrade announcements as inflection indicators for intermodal refrigerated container adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic System Retrofit | CO2 and propane-based refrigeration units avoid stranded assets under AIM Act hydrofluorocarbon quotas. |
| Electric APU Deployment | Battery-electric auxiliary power units absorb California Air Resources Board overnight idle reduction mandates. |
| Blockchain Traceability Integration | Immutable temperature logging systems win dedicated produce contracts under Walmart and Kroger supplier mandates. |
| Intermodal Rail Partnership | Union Pacific and BNSF electrified corridors reduce long-haul fuel exposure for cross-country movements. |
| Last-Mile Pharma Hub Network | Micro-fulfillment temperature controls in Texas and Florida capture margin pools distinct from long-haul freight. |
Research Approach
Document review covered refrigerated transport fleet disclosures, EPA regulatory filings, and FDA guidance documents, complemented by interviews with fleet operations directors, pharmaceutical distribution executives, cold-storage facility managers, and foodservice procurement leads. Secondary validation drew from DOT hours-of-service regulatory records, AIM Act implementation timelines, and trade association equipment deployment surveys. Bottom-up equipment unit economics and top-down freight volume estimates underwent cross-triangulation to anchor market sizing.
Segment-level projections across vehicle type, temperature control method, end user, and service type dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from fleet replacement cycle modeling, regulatory compliance cost absorption rates, and modal shift elasticity parameters. Cryogenic system adoption curves and electric APU penetration rates served as industry-specific forecast inputs alongside pharmaceutical cold-chain expansion trajectories.
Revisions become necessary when refrigerant quota allocations, rail electrification timelines, or biologics distribution network expansions materialize differently than modeled assumptions anticipate. Forecasts reflect documented assumptions about regulatory implementation pace and fleet capital deployment capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
United Kingdom Warehousing and Distribution Logistics Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
Europe Fleet Management Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market