
 Toxoplasmosis Infection Treatment Market | 2026-2036
Toxoplasmosis Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Toxoplasmosis Infection Treatment Market Analytics
EU MDR requirements for antiparasitic drug sterility and traceability is expanding compliance burdens across European manufacturing networks. F. Hoffmann-La Roche AG leverages its diagnostic-treatment integration to anchor clinical workflow capture in high-volume transplant centers. Teva Pharmaceutical Industries Ltd competes through sustained generic pyrimethamine supply continuity amid intermittent shortages. Pfizer Inc. dominates hospital formulary access through its established infectious disease portfolio and institutional contracting scale.
Toxoplasmosis infection treatment encompasses pharmacological intervention against Toxoplasma gondii, a protozoan parasite managed through synergistic antifolate and sulfonamide combinations that inhibit dihydrofolate reductase and microbial protein synthesis. The primary clinical purpose centers on preventing congenital transmission, treating active chorioretinitis, and suppressing reactivation in immunosuppressed patients. Pyrimethamine retains the largest revenue share among product types due to its irreplaceable role in first-line combination regimens for severe disease. The oral administration route occupies the dominant volume position, though intravenous delivery commands premium pricing in acute hospital settings where patient compliance is clinician-controlled.
FDA orphan drug designation frameworks and EMA's pediatric investigation plan requirements shape development timelines and exclusivity economics for antiparasitic developers. WHO Essential Medicines List inclusion drives procurement prioritization in low-resource health systems and donor-funded programs. Stakeholders must monitor emerging resistance surveillance data and biosimilar entry timelines to calibrate portfolio allocation between originator and generic exposure.
Market Dynamics
FDA orphan drug incentives are redirecting R&D capital toward antiparasitic therapies, compressing development timelines for toxoplasmosis treatments while reshaping competitive entry economics. This regulatory pull is amplifying manufacturer investment in immunocompromised patient segments.
Growth Catalysts
- Transplant medicine protocols:Rising solid organ transplant volumes in United States hospital systems are expanding the prophylactic treatment addressable base. Immunosuppression regimens mandate sustained anti-Toxoplasma coverage.
- EMA pediatric investigation plans:Mandatory pediatric study requirements are accelerating formulation development for congenital infection management. This creates dedicated revenue streams separate from adult indications.
- HIV care standardization:WHO Essential Medicines List inclusion drives procurement prioritization in resource-limited health systems. Donor-funded programs guarantee volume commitments for pyrimethamine-based regimens.
Market Restraints
- Pyrimethamine supply concentration:Generic API manufacturing clusters in India create vulnerability to export restriction shocks. Single-source dependencies for dihydrofolate reductase inhibitors amplify shortage risk.
- EU MDR sterility compliance:Revised traceability and manufacturing documentation requirements are extending batch release timelines. European production networks face elevated quality assurance overhead.
- Atovaquone substitution pressure:Alternative antiprotozoal agents with simpler dosing profiles threaten combination therapy adherence. Clinicians in outpatient settings favor single-agent convenience.
Strategic Opportunities
- Diagnostic-treatment integration:PCR-based Toxoplasma detection platforms paired with therapeutic protocols capture workflow control in high-volume transplant centers. Roche's integrated model demonstrates channel anchoring potential.
- Sub-Saharan Africa maternal health programs:Congenital screening expansion in Kenya, Nigeria, and Tanzania creates new procurement channels. WHO prequalification pathways lower market entry barriers.
- Extended-release formulation development:Once-weekly pyrimethamine dosing would displace daily regimens in maintenance therapy. Patient compliance advantages support premium positioning.
Industry Challenges
- Resistance surveillance infrastructure:Limited real-time genotyping capacity in hospital laboratories delays treatment adaptation. Clinical microbiology departments lack dedicated Toxoplasma molecular epidemiology programs.
- Combination therapy manufacturing complexity:Sulfadiazine-pyrimethamine co-formulation requires synchronized API sourcing across multiple supplier networks. Batch synchronization failures disrupt finished dose availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toxoplasmosis Infection Treatment Market |
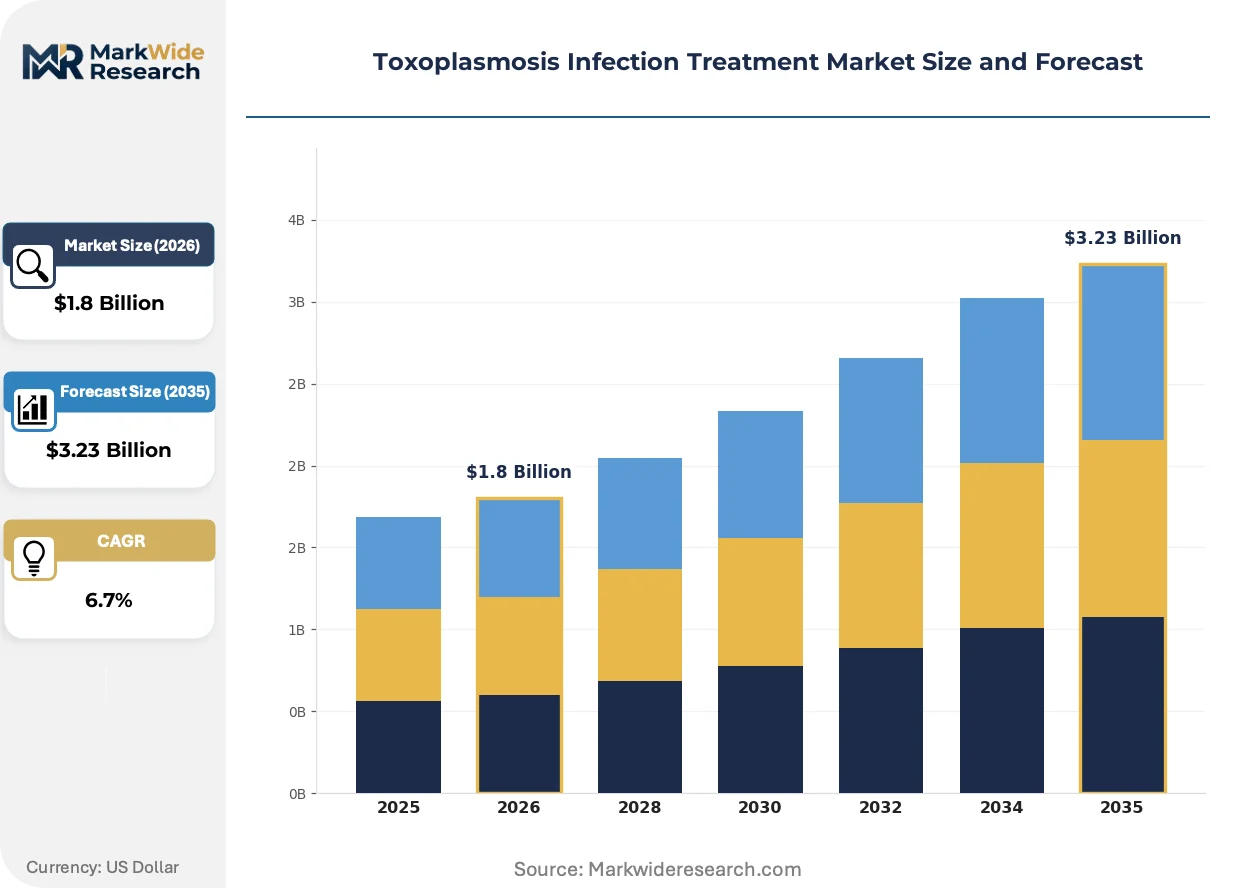
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyrimethamine, Sulfadiazine, Clindamycin, Trimethoprim Administration Route: Oral, Intravenous, Intramuscular, Sublingual End User: Hospitals, Homecare, Clinics, Pharmacies Therapy Area: Infectious Diseases, Neurology, Immunology, Pediatrics |
| Companies Covered | F. Hoffmann-La Roche AG, Teva Pharmaceutical Industries Ltd, Pfizer Inc., Viatris Inc., Sun Pharmaceutical Industries Ltd, Novartis AG, Dr. Reddy's Laboratories Ltd., Amneal Pharmaceuticals, Inc., Mangalam Drugs and Organics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toxoplasmosis Infection Treatment Market Evolving Landscape
Point-of-care molecular diagnostics are compressing the time from serological suspicion to targeted therapy initiation. This acceleration is reshaping clinical workflow economics and antimicrobial stewardship priorities.
Next-generation sequencing platforms for Toxoplasma genotyping are absorbing capital from conventional phenotypic susceptibility testing. Reference laboratories in the United States and Germany are adopting these systems for outbreak investigation and resistance monitoring. The technology is absorbing patient volume from centralized public health laboratories into academic medical center networks.
EU MDR requirements for antiparasitic drug sterility validation are mandating upgraded cleanroom infrastructure across European manufacturing sites. Batch release documentation burdens have extended quality assurance cycles by several weeks. Parenteral formulation producers in Italy and Spain are consolidating production to amortize compliance costs.
Hospital formulary committees are consolidating infectious disease procurement under centralized pharmacy and therapeutics boards. Academic medical centers are displacing physician-directed prescribing with protocol-driven order sets for transplant prophylaxis. This concentration is most visible in United States health systems managing large HIV and solid organ transplant populations.
Toxoplasmosis Infection Treatment Market Segmentation
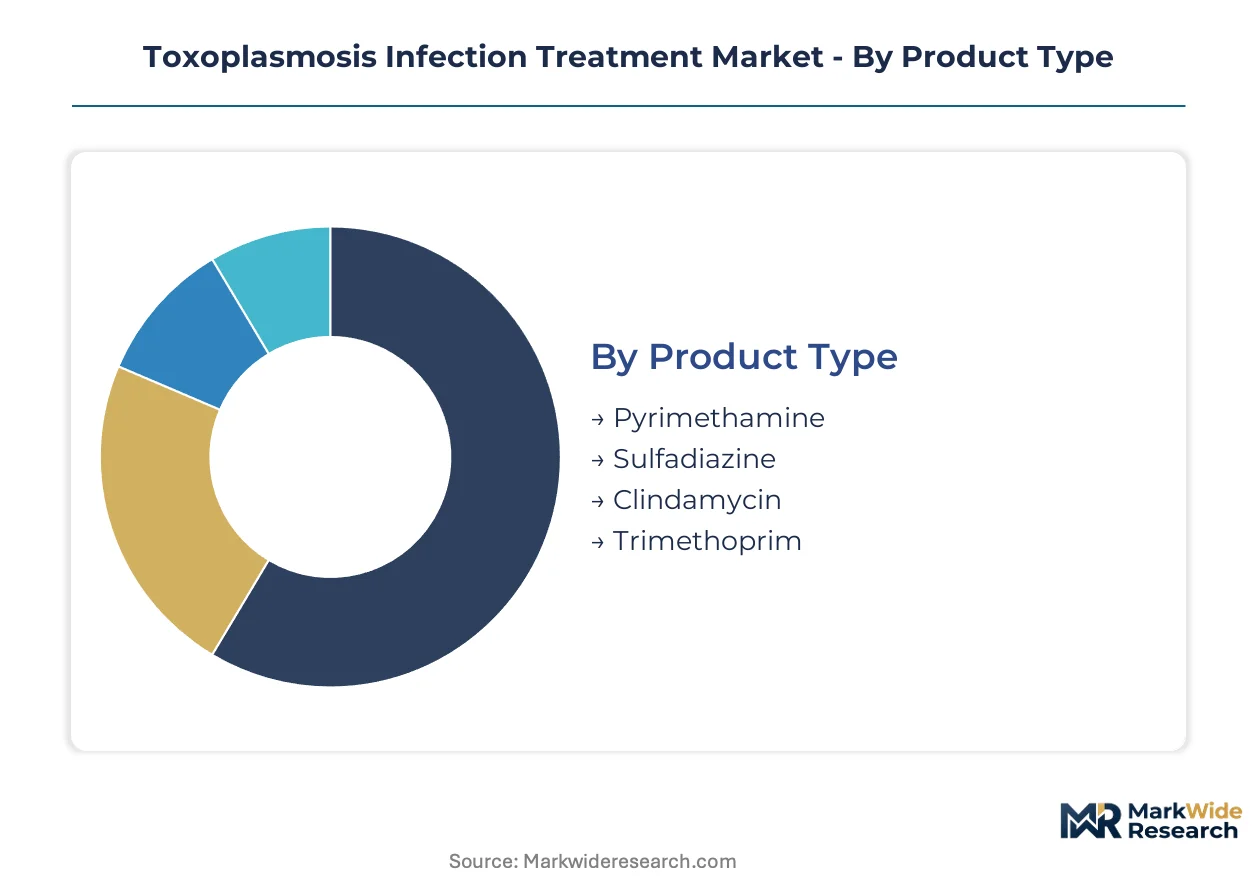
Therapeutic modality and delivery channel segmentation in toxoplasmosis treatment directly determines procurement economics and margin capture. Each dimension carries distinct regulatory, reimbursement, and supply chain characteristics that reshape competitive positioning.
Product Type:
API manufacturing concentration for dihydrofolate reductase inhibitors creates supply vulnerability that segments market power.
- Pyrimethamine:Irreplaceable first-line antifolate compound that inhibits Toxoplasma dihydrofolate reductase. Demand concentrates in United States transplant centers and HIV care protocols where combination regimens remain mandatory. Supply interruptions from single-source generic manufacturers periodically disrupt hospital formularies.
- Sulfadiazine:Sulfonamide antimicrobial administered synergistically with pyrimethamine to block microbial protein synthesis. United States hospital systems absorb the majority of procurement volume due to entrenched infectious disease protocols. Manufacturing complexity from synchronized API sourcing elevates shortage risk.
- Clindamycin:Lincosamide antibiotic reserved for pyrimethamine-intolerant patients or sulfonamide allergies. Alternative regimens in European markets favor this agent when first-line combinations fail.
- Trimethoprim:Dihydrofolate reductase inhibitor with broader antibacterial spectrum used in resource-limited settings. WHO Essential Medicines List inclusion drives procurement in donor-funded African maternal health programs.
Pyrimethamine absorbs the bulk of installed capacity; trimethoprim is expanding most quickly.
Administration Route:
Delivery modality segmentation separates outpatient convenience economics from acute care premium capture.
- Oral:Dominant volume position across maintenance therapy and congenital infection prophylaxis. Patient-controlled dosing in homecare settings drives adherence advantages over parenteral alternatives.
- Intravenous:Commands premium pricing in acute hospital settings where clinician-controlled administration ensures compliance. United States academic medical centers with large transplant populations generate concentrated demand for IV pyrimethamine-sulfadiazine combinations.
- Intramuscular:Limited application for patients with compromised gastrointestinal absorption or severe vomiting. Neurology departments in German and French hospitals deploy this route for encephalitis cases.
- Sublingual:Emerging formulation technology addressing bioavailability variations in immunocompromised patients. Pediatric investigation plans in Europe are accelerating development timelines for congenital infection management.
Oral formulations absorb the bulk of installed capacity; intravenous delivery commands the steepest pricing premium.
End User:
Channel segmentation reflects institutional purchasing power versus retail pharmacy reimbursement constraints.
- Hospitals:Centralized infectious disease procurement through pharmacy and therapeutics boards dominates high-volume transplant and HIV populations. Formulary committees in United States health systems consolidate vendor selection under protocol-driven order sets.
- Homecare:Growing segment for stable immunocompromised patients on maintenance prophylaxis. Medicare reimbursement policies in the United States shape prescribing patterns for oral combination therapies.
- Clinics:Outpatient infectious disease and ophthalmology practices manage active chorioretinitis cases. Retina specialists in academic medical centers drive pyrimethamine prescription volume.
- Pharmacies:Retail dispensing faces generic substitution pressure and prior authorization requirements. United States specialty pharmacies handle high-cost pyrimethamine distribution amid intermittent shortages.
Hospitals absorb the bulk of installed capacity; homecare is climbing the fastest.
Therapy Area:
Clinical indication segmentation separates prophylactic protocols from curative interventions with distinct reimbursement profiles.
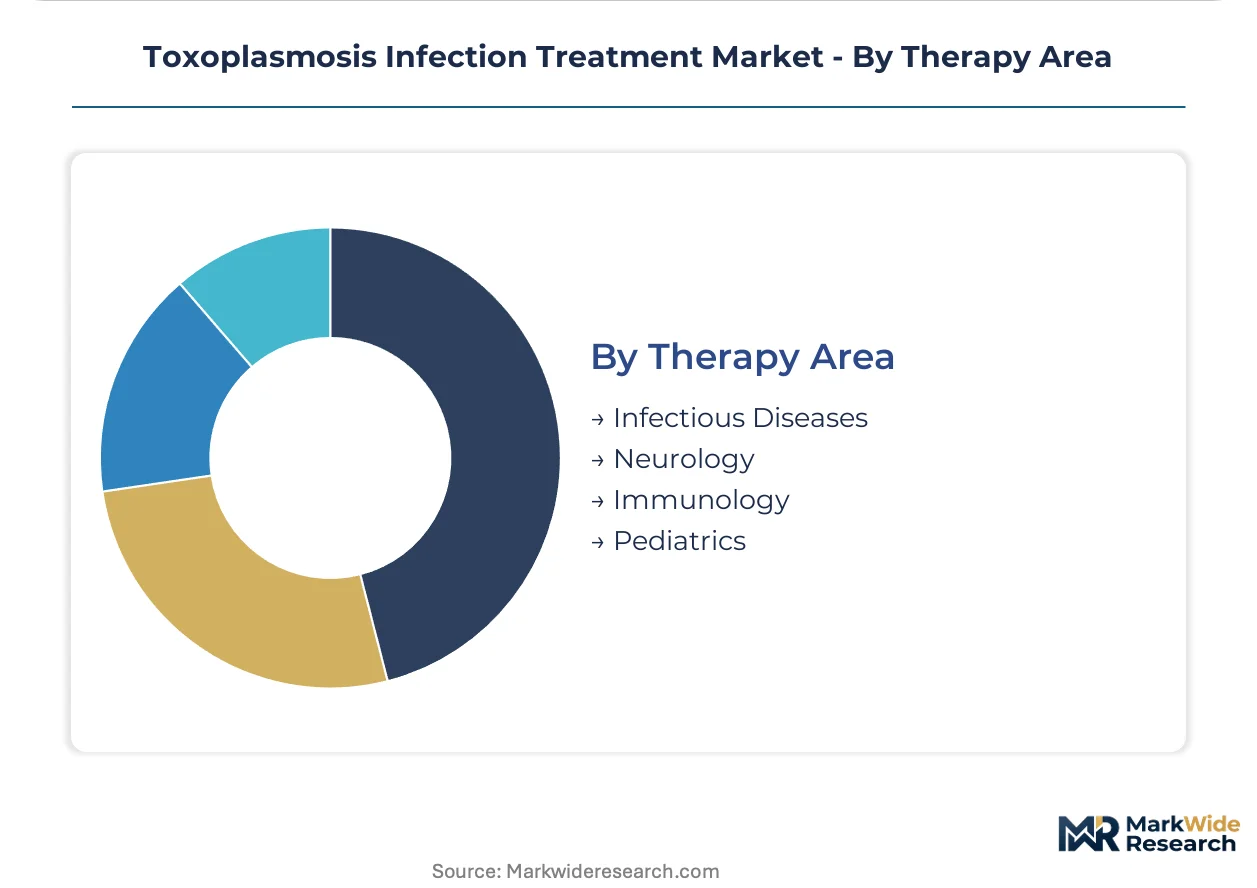
- Infectious Diseases:Core specialty managing Toxoplasma prophylaxis in transplant and HIV populations. United States hospital systems with large infectious disease departments generate sustained prescription volume for combination antifolate-sulfonamide regimens.
- Neurology:CNS toxoplasmosis treatment in AIDS-related encephalitis and brain abscess cases. Acute care settings favor intravenous delivery for rapid therapeutic levels.
- Immunology:Prophylactic management in solid organ transplant recipients on calcineurin inhibitor regimens. Transplant medicine protocols in United States academic centers mandate sustained anti-Toxoplasma coverage.
- Pediatrics:Congenital infection management and maternal-fetal transmission prevention. EMA pediatric investigation plan requirements are accelerating formulation development for neonatal dosing.
Infectious diseases absorbs the bulk of installed capacity; pediatrics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's transplant medicine corridor anchors North American demand concentration, while Basel and Mumbai manufacturing clusters supply API and finished dose networks across three continents.
United States
Solid organ transplant volumes at Cleveland Clinic and Mayo Clinic drive prophylactic prescription intensity. FDA orphan drug incentives compress development timelines for antiparasitic developers targeting immunocompromised segments. Specialty pharmacies in New York and Los Angeles manage pyrimethamine distribution amid intermittent shortages.
Germany
Academic medical centers in Berlin and Munich deploy next-generation sequencing for Toxoplasma resistance surveillance. EU MDR sterility requirements extend batch release timelines for parenteral formulation producers. Cleanroom infrastructure upgrades in Frankfurt-Rhine-Main manufacturing zones absorb compliance capital.
India
Generic API manufacturing clusters in Hyderabad and Ahmedabad supply dihydrofolate reductase inhibitors to global formulators. CDSCO manufacturing facility inspections align with WHO prequalification standards for donor-funded African procurement. Export restriction vulnerabilities concentrate in single-source pyrimethamine precursor networks.
Brazil
Congenital toxoplasmosis screening expansion in São Paulo and Rio de Janeiro maternal health networks drives pediatric formulation demand. ANVISA regulatory harmonization with FDA standards accelerates bioequivalence study requirements. Local production partnerships in Minas Gerais pharmaceutical corridors reduce import dependency.
United Kingdom
London transplant centers and HIV care protocols at Guy's and St Thomas' generate sustained combination therapy prescriptions. MHRA post-Brexit regulatory autonomy maintains EMA-aligned sterility standards for antiparasitic imports. Research Triangle Park collaborations in Cambridge accelerate diagnostic-treatment integration pilots.
Toxoplasmosis Infection Treatment Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with infectious disease portfolio depth. Hospital formulary committees consolidate vendor selection under protocol-driven order sets, concentrating procurement power among scaled institutional contractors. Two strategic archetypes dominate: diagnostic-therapeutic integrators capturing workflow control in high-volume transplant centers, and generic manufacturers ensuring supply continuity through API backward integration. Capacity consolidation and geographic licensing partnerships represent the dominant competitive moves.
Among Swiss and Israeli pharmaceutical conglomerates, F. Hoffmann-La Roche AG exemplifies diagnostic-treatment integration archetypes. Pfizer Inc. and Novartis AG occupy positions within the institutional contracting tier, anchoring hospital formulary access through infectious disease portfolio breadth. These three entities represent the concentration of manufacturing scale and regulatory navigation capability that defines competitive positioning in immunocompromised patient segments.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc. |
| Viatris Inc. |
| Sun Pharmaceutical Industries Ltd |
| Novartis AG |
| Dr. Reddy's Laboratories Ltd. |
| Amneal Pharmaceuticals, Inc. |
| Mangalam Drugs and Organics Ltd. |
| Others |
Value Network & Pricing Analysis
Specialized pharmaceutical chemists concentrated in Basel and Hyderabad drive labor-cost differentials that widen spreads between premium branded pyrimethamine and economy generic sulfadiazine tiers across transplant center procurement networks.
Pricing Analysis
Outcome-linked reimbursement anchors value-based pricing for pyrimethamine-sulfadiazine combinations in United States transplant protocols. Three-tier pricing structure across premium, standard, and economy levels separates originator pyrimethamine from authorized generics and unbranded sulfadiazine. Cost compression in the generic tier intensifies because Indian API manufacturers face export documentation burdens. Homecare patients on maintenance prophylaxis exhibit highest price sensitivity; academic medical centers with bundled transplant contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Hyderabad-based manufacturers of dihydrofolate reductase inhibitor precursors that feed global pyrimethamine formulation. Active pharmaceutical ingredient production draws from India, China, and Italy; finished dose packaging rests on facilities in the United States, Germany, and Brazil. Tariff exposure concentrates in sulfadiazine intermediate trade flows. Distribution runs through hospital purchasing consortia and specialty pharmacy networks serving immunocompromised populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR-based Toxoplasma detection platforms are displacing conventional serological workflows, creating technology-transition arbitrage for stakeholders positioning around diagnostic-therapeutic integration.
For Market Incumbents: Acquire point-of-care molecular diagnostic assets to anchor workflow control in high-volume transplant centers. Consolidate pyrimethamine API sourcing through backward integration into Indian precursor manufacturing. Atovaquone substitution pressure threatens combination therapy adherence; defend through extended-release formulation patents and pediatric indication exclusivity. For New Entrants and Emerging Players: Telehealth-integrated specialty pharmacy channels offer lowest-cost patient acquisition for maintenance prophylaxis populations. Target maternal health programs in Kenya, Nigeria, and Tanzania where WHO prequalification pathways lower regulatory barriers. Sub-Saharan Africa congenital screening expansion represents the most penetrable geography; partner with donor-funded procurement consortia for volume commitments. For Investors and Strategic Acquirers: Re-rating potential sits with diagnostic-therapeutic integrators given FDA orphan drug incentive compression of development timelines. Five-to-ten year viability favors manufacturers with captive API supply and EMA pediatric investigation plan capabilities. Watch resistance surveillance infrastructure buildout in United States academic medical centers as inflection indicator for combination therapy durability.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Once-weekly pyrimethamine dosing would displace daily regimens in transplant maintenance protocols. |
| Diagnostic-Treatment Integration Partnership | Roche's PCR platform paired with therapeutic protocols captures workflow control in Cleveland Clinic transplant corridors. |
| Pediatric Investigation Plan Submission | EMA requirements accelerate neonatal dosing formulations for congenital infection management. |
| API Backward Integration | Captive dihydrofolate reductase inhibitor supply insulates against Indian export restriction shocks. |
| WHO Prequalification Pathway | Donor-funded African maternal health programs guarantee volume for prequalified pyrimethamine suppliers. |
Research Methodology
FDA filings, EMA regulatory submissions, and ClinicalTrials.gov records formed the secondary backbone for treatment protocol and pipeline validation. Primary interviews with infectious disease department heads, hospital formulary directors, transplant center pharmacists, and specialty pharmacy procurement managers combined with secondary source triangulation. Bottom-up prescription volume modeling and top-down therapeutic category sizing anchored forecast construction.
Bottom-up patient-flow analysis tracked immunocompromised population segments through treatment lines, administration routes, and regional regulatory clusters across the projection horizon. CAGRs derived from segmented volume trajectories calibrated against institutional purchasing data and WHO Essential Medicines List procurement commitments. Resistance surveillance adoption curves and biosimilar entry timelines fed scenario-weighted outputs.
The model holds under stable immunosuppression protocol adherence and continued orphan drug incentive continuity; deviation in pyrimethamine supply disruptions or atovaquone guideline substitution would shift trajectory bounds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Infectious Enteritis Treatment Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Q Fever Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Valley Fever Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Brucellosis Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Hepatitis C Market