
 Asia Pacific Bio Composites Market | 2026-2036
Asia Pacific Bio Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Bio Composites Market Outlook
Project finance tied to green bond issuance is reconfiguring capital access for bio composite manufacturers that previously relied on balance-sheet expansion. Toray Industries leverages its upstream control over cellulose nanofiber precursors to anchor supply security for automotive tier-one contracts. Teijin Ltd. competes through high-R&D-intensity aramid-bio hybrid platforms targeting aerospace qualification pathways. Mitsubishi Chemical Group Corporation dominates regional bio-resin compounding with integrated fermentation-derived polyamide capacity.
Asia Pacific bio composites are fiber-reinforced or particle-filled materials combining renewable biological feedstocks with thermoset or thermoplastic matrices, typically processed through extrusion, injection molding, or compression molding to achieve densities between 0.9 and 1.4 g/cm³ for structural load-bearing applications. Natural Fiber Composites occupy the largest volume share where jute and kenaf supply chains in Bangladesh and Thailand sustain cost-competitive raw material access for building and construction profiles. Hybrid Composites represent the fastest-expanding category as automotive OEMs specify flax-carbon blends to satisfy crashworthiness and sustainability KPIs simultaneously. Bio-resins concentrate margin pools at specialty compounders serving medical device and consumer electronics clients with customized biodegradation profiles.
Japan's METI enforces JIS standards for bio-based content labeling that OEMs must satisfy to qualify for public procurement preferences, while India's BIS mandates fire-performance ratings for wood-plastic composites used in railway and metro infrastructure. China's SAMR implements GB standards for biodegradable plastics that constrain formulation choices for export-oriented compounders. Stakeholders must monitor regulatory divergence on end-of-life certification requirements across these three jurisdictions to avoid stranded inventory or reformulation costs.
Market Dynamics
Automotive OEMs across Asia Pacific are mandating bio composite content in interior panels to meet fleet-weight reduction targets, compressing traditional petroleum-based resin procurement timelines and forcing compounders to secure natural fiber supply chains ahead of qualification cycles.
Growth Catalysts
- India's PLI scheme for advanced materials:The production-linked incentive framework subsidizes domestic compounding capacity expansion, drawing foreign resin suppliers into joint ventures with local processors serving building and construction markets.
- Flax-carbon hybrid specification:Automotive crashworthiness engineering teams are validating natural fiber-carbon weave prepregs that satisfy sustainability KPIs without sacrificing structural performance in side-impact zones.
- Yangtze River Delta cluster concentration:Integrated wood-plastic composite extrusion parks in Jiangsu and Zhejiang provinces achieve feedstock-to-profile economies that undercut dispersed European supply costs for export-oriented building product manufacturers.
Market Restraints
- Jute and kenaf supply volatility:Monsoon-dependent harvests in Bangladesh and Thailand create raw material price swings that compounders cannot fully hedge, compressing margin stability for natural fiber composite producers.
- GB standards constraint on export formulations:China's SAMR biodegradable plastics regulations impose compositional limits that force reformulation of products destined for European markets, raising compliance overhead for dual-certified compounders.
- Petrochemical resin substitution pressure:Virgin polypropylene pricing weakness in regional spot markets periodically narrows the cost gap with bio-based alternatives, slowing conversion momentum among price-sensitive construction specifiers.
Strategic Opportunities
- Vietnam's underpenetrated automotive tier-one base:Emerging assembly plant clusters around Hai Phong lack established bio composite supply relationships, creating first-mover positioning for compounders with JIS-qualified production systems.
- Medical device biodegradation customization:Specialty compounders serving surgical instrument and diagnostic housing manufacturers can capture premium margin pools by engineering site-specific degradation profiles unattainable from commodity resin suppliers.
- Cellulose nanofiber-thermoplastic convergence:Laboratory-scale dispersion breakthroughs enable loadings above 20% by weight in injection-moldable grades, opening appliance and consumer electronics applications previously restricted to glass-filled compounds.
Industry Challenges
- Natural fiber preprocessing skill scarcity:Compounding facilities lack technicians trained in moisture-controlled fiber surface activation and silane coupling optimization, extending batch qualification timelines and raising scrap rates.
- Multi-jurisdiction end-of-life certification complexity:Divergent biodegradability testing protocols between Japan's METI, India's BIS, and China's SAMR create stranded inventory risk for compounders serving cross-border OEM supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Bio Composites Market |
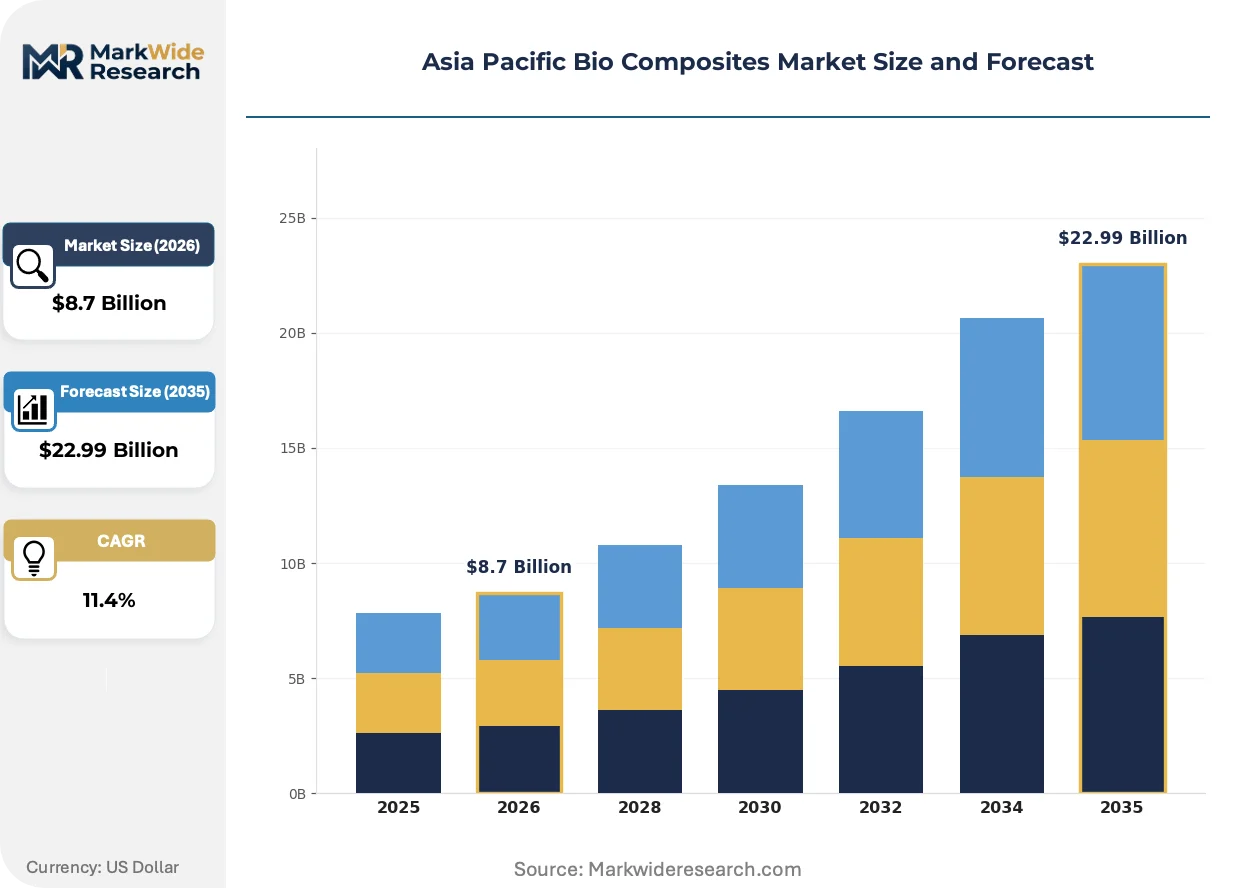
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fiber Composites, Bio-resins, Hybrid Composites, Biodegradable Composites Application: Aerospace, Automotive, Building & Construction, Consumer Goods End User: Manufacturers, Retailers, OEMs, Distributors Material: Wood Fiber, Plant Fiber, Polymer Matrix, Bio-based Fillers |
| Companies Covered | Toray Industries, Inc., Teijin Ltd., Mitsubishi Chemical Group Corporation, Trex Company, Inc., Universal Forest Products, Inc., Fiberon LLC, Azek Building Products, China Jushi Co., Ltd., Kineco Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Bio Composites Market Strategic Shifts
Material science advances are collapsing the performance gap between bio composites and engineered petrochemical alternatives, while regulatory labeling mandates and procurement specification changes are accelerating specification velocity in automotive and building end-uses.
Cellulose nanofiber reinforcement technology is hybridizing conventional polypropylene and polyamide matrices to achieve modulus values approaching short-glass compounds at 15-20% lower density. Japanese automotive tier-one suppliers are qualifying these grades for non-structural interior panels on 18-month validation cycles. The technology is hybridizing competitive positioning between commodity thermoplastics and advanced composites, compressing the addressable market for traditional glass-filled resins in weight-sensitive applications.
METI's JIS bio-based content labeling standards now mandate third-party verification for products claiming renewable feedstock percentages above 10%, with non-compliance disqualifying suppliers from public procurement preferences. The regulation forces compounders to invest in carbon-14 testing infrastructure and supply chain documentation systems. Automotive seating and trim manufacturers serving Japanese OEMs are most affected, with several restructuring supplier qualification workflows to incorporate blockchain-tracked biomass certificates.
Building and construction specifiers are consolidating procurement authority from distributed project engineers to centralized sustainability offices, compressing the vendor base accessible for wood-plastic composite decking and cladding contracts. Regional distributors in Australia and Southeast Asia are losing specification influence to direct manufacturer relationships with national homebuilder chains. This concentration is most visible in China's commercial real estate development sector, where LEED-equivalent certification requirements now embed bio composite content minimums into master specifications controlled by state-owned developers.
Asia Pacific Bio Composites Market Segmentation
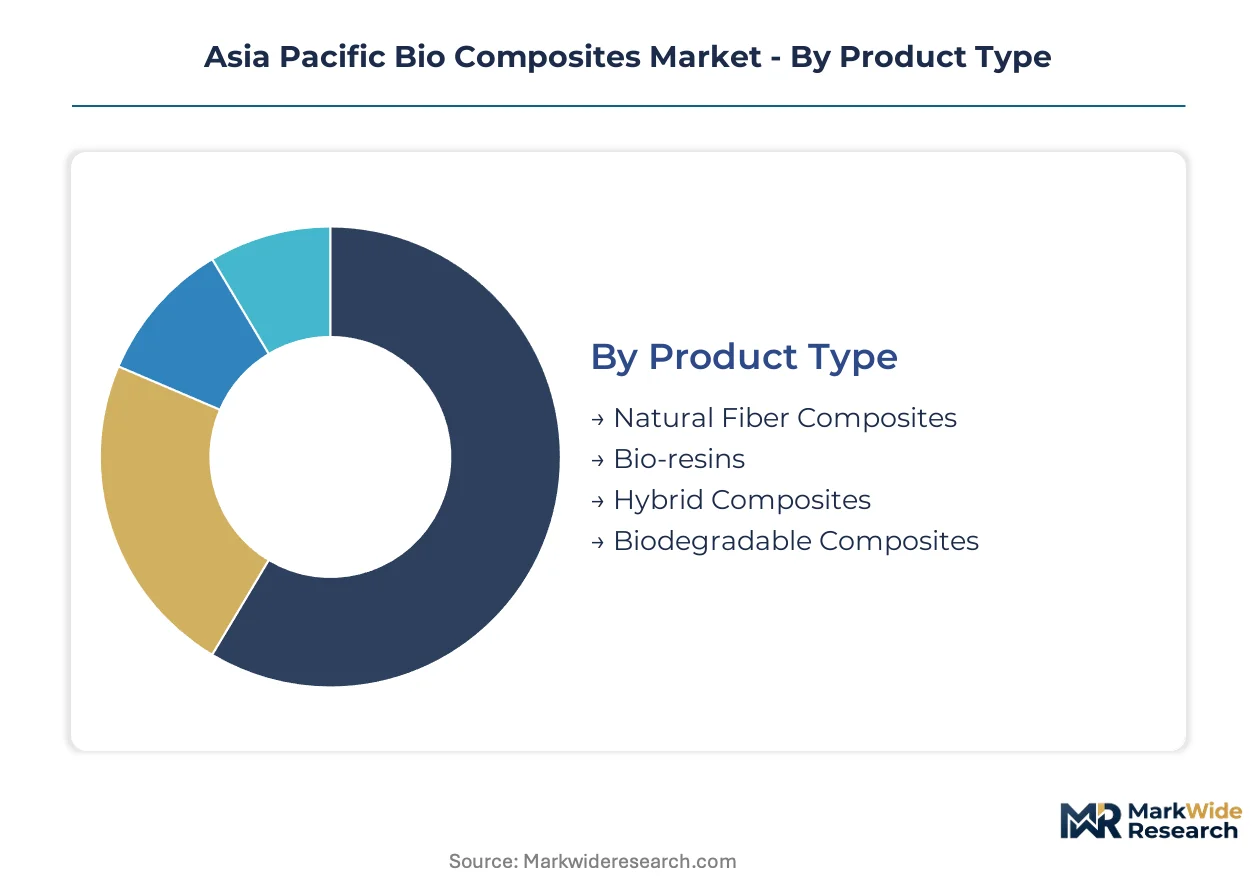
Segmentation in the Asia Pacific bio composites market reveals how material science maturity, application engineering requirements, and supply chain geography create distinct competitive arenas. Each dimension governs different margin structures and qualification barriers.
Product Type:
Mature commodity grades dominate volume flows while emerging hybrid platforms capture specification upgrades in performance-critical applications.
- Natural Fiber Composites:Jute and kenaf reinforce thermoplastic matrices at 30-50% fiber loading, achieving densities between 0.9 and 1.2 g/cm³. Automotive interior panel procurement from Thailand and Bangladesh supply chains sustains cost positioning against glass-filled alternatives. Building and construction specifiers in China's Yangtze River Delta cluster specify these grades for decking and cladding profiles where moisture resistance requirements are moderate.
- Hybrid Composites:Flax-carbon weave architectures combine renewable fiber surfaces with carbon fiber structural cores, enabling crashworthiness performance that satisfies OEM side-impact zone requirements. Japanese automotive tier-one suppliers are qualifying these grades on 18-month validation cycles for premium vehicle programs where sustainability KPIs carry procurement weight. The segment commands formulation premiums unavailable to commodity natural fiber compounds.
- Bio-resins:Fermentation-derived polyamides and thermosets serve medical device and consumer electronics clients requiring customized biodegradation profiles.
- Biodegradable Composites:Starch and PLA matrix systems face GB standards constraints from China's SAMR that limit export formulation flexibility.
Natural Fiber Composites handles the majority of throughput; Hybrid Composites is the fastest mover on share.
Application:
Application segmentation tracks how end-use engineering specifications translate into distinct supply chain and qualification requirements.
- Automotive:Interior panels, seat backs, and trim components specify bio composite content to meet fleet weight-reduction mandates. OEM procurement teams in Japan, South Korea, and Thailand are compressing traditional petroleum-based resin qualification timelines, forcing compounders to secure natural fiber supply chains ahead of validation cycles. METI's JIS bio-based content labeling standards now require third-party verification above 10% renewable feedstock for public procurement eligibility.
- Building & Construction:Wood-plastic composite decking, cladding, and structural profiles concentrate demand in China's commercial real estate sector where state-owned developers embed bio composite minimums into LEED-equivalent master specifications. India's BIS mandates fire-performance ratings for railway and metro infrastructure applications, creating compliance overhead distinct from residential construction.
- Aerospace:Aramid-bio hybrid platforms target qualification pathways for secondary structural components where weight reduction justifies premium material costs.
- Consumer Goods:Appliance housings and electronics enclosures represent emerging volume as cellulose nanofiber-thermoplastic dispersion breakthroughs enable injection-moldable grades above 20% loading.
Building and Construction absorbs the greatest raw material tonnage; Aerospace shows the steepest expansion trajectory on a low base.
End User:
End user categories reflect how procurement authority concentration shapes vendor accessibility and margin capture.
- OEMs:Automotive and appliance original equipment manufacturers wield consolidated specification authority, compressing the compounder base through direct qualification relationships rather than distributor intermediaries. Japanese OEMs impose METI JIS verification requirements that disqualify suppliers lacking carbon-14 testing infrastructure.
- Manufacturers:Tier-one and tier-two component producers serving building products, medical devices, and industrial equipment represent fragmented demand with heterogeneous technical requirements.
- Distributors:Regional distributors in Australia and Southeast Asia are losing specification influence to direct manufacturer relationships with national homebuilder chains.
- Retailers:Big-box and specialty retail channels for consumer-facing building products capture commoditized grades where brand differentiation is minimal.
OEMs command the tightest supplier qualification standards; Manufacturers represent the broadest addressable base.
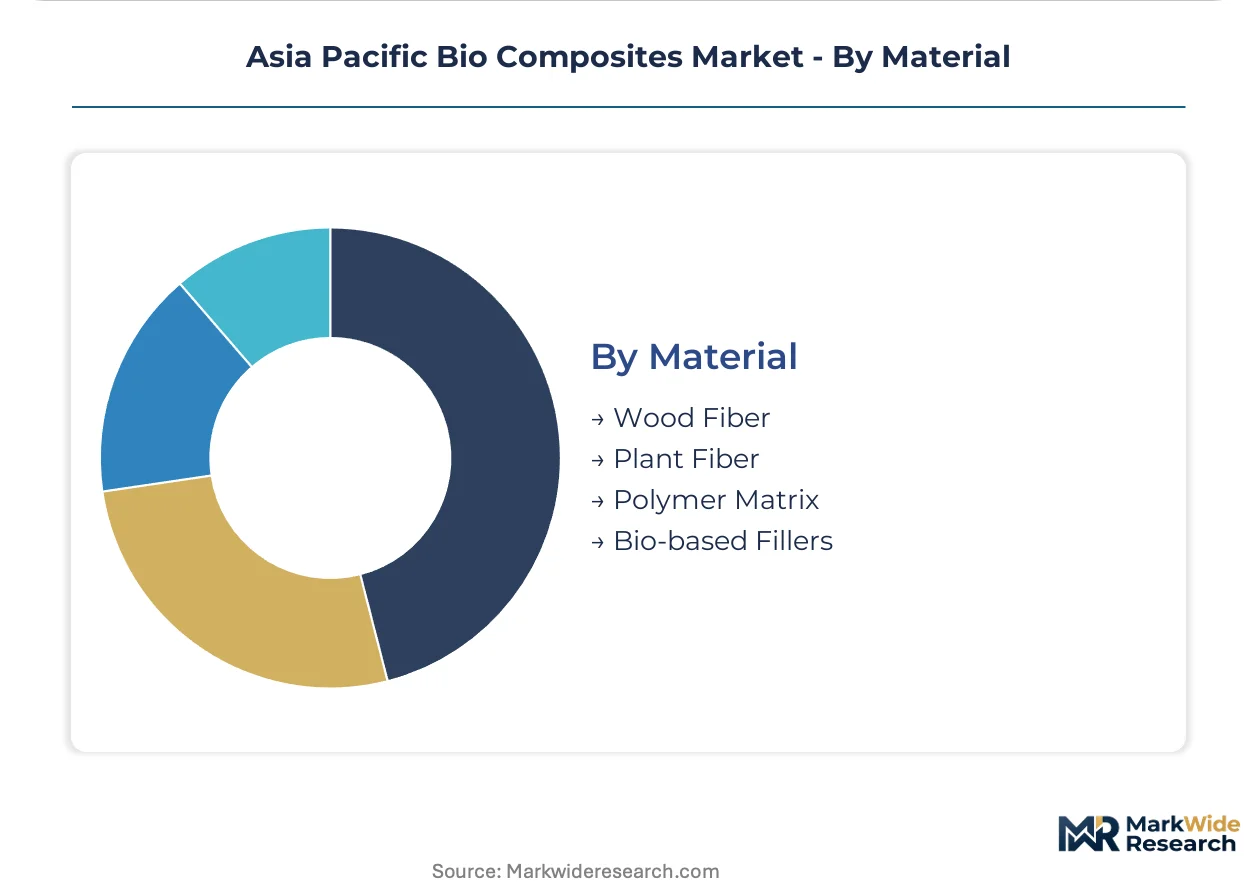
Material:
Material segmentation governs upstream supply security and preprocessing capital requirements.
- Plant Fiber:Jute from Bangladesh, kenaf from Thailand, and flax from European imports sustain Asia Pacific natural fiber composite production. Monsoon-dependent harvests create raw material price swings that compounders cannot fully hedge, compressing margin stability.
- Wood Fiber:Wood-plastic composite extrusion parks in Jiangsu and Zhejiang provinces achieve feedstock-to-profile economies through integrated sourcing from domestic forestry operations and recycled construction waste streams.
- Polymer Matrix:Virgin polypropylene pricing weakness in regional spot markets periodically narrows the cost gap with bio-based alternatives, slowing conversion momentum among price-sensitive construction specifiers.
- Bio-based Fillers:Cellulose nanofiber precursors anchor supply security for Japanese automotive tier-one contracts, with Toray Industries leveraging upstream control over dispersion technology.
Plant Fiber underpins the largest installed compounding capacity; Bio-based Fillers is climbing the fastest on technology investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific bio composite trade flows reflect a structural export surplus from integrated Chinese manufacturing clusters against import dependence for specialty bio-resins in Japan and South Korea. Regional supply chains fragment across monsoon-dependent fiber harvests in Southeast Asia and capital-intensive compounding infrastructure in East Asian industrial corridors.
China
Wood-plastic composite extrusion parks in Jiangsu and Zhejiang provinces serve building product exporters with feedstock-to-profile economies. SAMR enforces GB standards for biodegradable plastics that constrain formulation choices for European-bound shipments. The Yangtze River Delta cluster concentrates integrated capacity where state-owned developers embed bio composite minimums into LEED-equivalent master specifications.
Japan
Automotive tier-one suppliers qualify cellulose nanofiber-reinforced grades for interior panels on 18-month validation cycles. METI's JIS bio-based content labeling mandates third-party verification above 10% renewable feedstock for public procurement eligibility. Chubu/Nagoya industrial corridor hosts compounders serving Toyota and Honda supply chains with blockchain-tracked biomass certification systems.
India
Railway and metro infrastructure procurement drives fire-rated wood-plastic composite demand under BIS performance mandates. The PLI scheme for advanced materials subsidizes domestic compounding capacity expansion through foreign-resin joint ventures. Maharashtra and Gujarat host emerging extrusion facilities serving building and construction markets with jute-reinforced profiles.
South Korea
Automotive OEMs specify bio composite content in seat backs and trim components to meet fleet weight-reduction targets. MFDS regulates medical device biodegradation profiles that specialty compounders engineer for surgical instrument manufacturers. Seoul Capital Area concentrates R&D-intensive compounders developing aramid-bio hybrid platforms.
Thailand
Kenaf harvests sustain cost-competitive raw material access for regional natural fiber composite producers. Monsoon-dependent supply volatility creates price swings that compounders cannot fully hedge against. Eastern Economic Corridor automotive assembly plants are scaling bio composite procurement for interior panel applications.
Asia Pacific Bio Composites Market Competitive Environment
On the supply side, the industry is bifurcated between scale-driven Japanese chemical conglomerates with upstream cellulose nanofiber control and specialized wood-plastic composite fabricators serving building product channels. Three archetypes dominate: integrated resin compounders with fermentation-derived polyamide capacity, natural fiber preprocessing specialists anchored to Bangladesh and Thailand supply chains, and hybrid composite developers qualifying flax-carbon architectures for automotive crashworthiness. Capacity expansion and JIS qualification infrastructure represent the dominant competitive moves.
Within the integrated chemical conglomerate tier, Toray Industries, Teijin Ltd., and Mitsubishi Chemical Group Corporation occupy positions defined by upstream control over precursor technologies and automotive tier-one supply relationships. Toray exemplifies the cellulose nanofiber-anchored archetype through captive dispersion technology. Teijin represents high-R&D-intensity hybrid platforms targeting aerospace qualification pathways. Mitsubishi Chemical Group sits within bio-resin compounding with integrated fermentation-derived capacity. These three Japanese entities anchor the premium tier through qualification timelines and supply security mechanisms that mid-scale competitors cannot replicate.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Teijin Ltd. |
| Mitsubishi Chemical Group Corporation |
| Trex Company, Inc. |
| Universal Forest Products, Inc. |
| Fiberon LLC |
| Azek Building Products |
| China Jushi Co., Ltd. |
| Kineco Limited |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion cycles feed directly into landed cost spreads for wood-plastic composite exporters, compressing margin pools at compounders serving European building product channels while amplifying price differentiation between integrated Jiangsu-Zhejiang producers and dispersed Southeast Asian competitors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Asia Pacific bio composites. Premium tiers capture JIS-certified cellulose nanofiber grades for Japanese automotive seating contracts, while economy tiers serve price-sensitive Indian railway infrastructure specifiers under BIS fire-rating mandates. Cost compression in standard-grade natural fiber compounds is intensifying because virgin polypropylene spot weakness periodically narrows the bio-based cost gap. Tier-one automotive seating manufacturers exhibit least price sensitivity due to qualification lock-in, whereas distributed building product distributors face acute margin pressure from centralized homebuilder procurement consolidation.
Supply Chain Analysis
Monsoon-dependent harvest volatility between Bangladesh and Thailand dominates supply-side risk exposure for jute and kenaf fiber compounders. Raw material sourcing draws from Bangladeshi jute belt harvests, Thai kenaf plantations, and European flax import channels, with polymer matrices resting on regional petrochemical naphtha cracking capacity concentrated in South Korea and Singapore. Single-source vulnerability concentrates in cellulose nanofiber precursor supply where Toray Industries maintains captive dispersion technology. Distribution runs through direct manufacturer relationships with Japanese automotive tier-one suppliers and state-owned Chinese commercial real estate developers, bypassing traditional Australian and Southeast Asian distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific bio composites constitute a regulatory-moat market where METI JIS certification infrastructure and 18-month automotive qualification timelines create switching costs that entrench incumbents serving Japanese OEM supply chains.
For Market Incumbents: Harden supply security through backward integration into Bangladeshi jute preprocessing and Thai kenaf decortication capacity, insulating margin stability from monsoon-driven raw material volatility. Expand cellulose nanofiber dispersion capacity in the Chubu/Nagoya corridor to capture incremental automotive tier-one contracts as METI labeling mandates tighten public procurement eligibility. Prioritize blockchain-tracked biomass certification systems to defend against emerging European compounders seeking JIS qualification pathways. For New Entrants and Emerging Players: Vietnam's underpenetrated automotive assembly clusters around Hai Phong represent the most penetrable entry point for compounders with JIS-qualified production systems, as established Japanese supply relationships have yet to solidify. Medical device biodegradation customization for Seoul Capital Area surgical instrument manufacturers offers premium margin capture unavailable in commoditized building product channels. Lead with direct technical sales teams targeting MFDS-regulated diagnostic housing specifications rather than distributor-dependent building product routes. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Japanese chemical conglomerates seeking to divest non-core bio-resin compounding assets amid portfolio rationalization pressures. Five-to-ten year viability hinges on regulatory entrenchment durability across METI, BIS, and SAMR jurisdictions rather than technology differentiation alone. Watch for cellulose nanofiber-thermoplastic dispersion breakthroughs achieving injection-moldable loadings above 20% by weight as the signal indicating accelerated appliance and consumer electronics specification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Fiber Preprocessing | Bangladeshi jute decortication capacity secures raw material cost positioning against monsoon volatility. |
| JIS Certification Infrastructure Investment | Carbon-14 testing systems unlock Japanese automotive public procurement eligibility under METI mandates. |
| Cellulose Nanofiber Dispersion Scale-Up | Loadings above 20% by weight in injection-moldable grades penetrate appliance and electronics enclosures. |
| Direct Manufacturer Relationship Development | Bypassing Australian distributors captures specification authority from centralized Chinese state-owned developers. |
| Blockchain-Tracked Biomass Certification | Supply chain documentation systems satisfy METI third-party verification requirements for bio-based content claims. |
Study Parameters
A spread of perspectives from automotive tier-one procurement directors, bio-resin compounder technical R&D leads, building product specification managers at state-owned Chinese developers, and Southeast Asian natural fiber preprocessing operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, BIS and METI regulatory filings, SEC 10-K disclosures from listed chemical conglomerates, and Yangtze River Delta industrial park investment records. Bottom-up volume modeling across fiber loading tiers, matrix types, and end-use applications triangulated against top-down macro demand projections for automotive lightweighting and commercial real estate construction.
Demand-supply balance modeling across the projection horizon integrated segmentation dimensions spanning product type (natural fiber, hybrid, bio-resin, biodegradable), application (automotive interior, building cladding, medical device, aerospace secondary structure), and material (plant fiber, wood fiber, polymer matrix, bio-based filler). CAGRs derived from fitted growth curves applied to base-year volume estimates, with explicit modeling of India's PLI scheme subsidy absorption rates, Japanese automotive qualification cycle timelines, and Chinese SAMR GB standards compliance costs as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in regional naphtha pricing, monsoon precipitation patterns affecting Bangladeshi and Thai fiber harvests, or Japanese yen depreciation against export-market currencies would shift the trajectory. Material shifts in METI JIS certification stringency, BIS fire-performance rating enforcement, or SAMR biodegradable plastics standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
Pultrusion Market
Composite Materials
Transportation Composites Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Long-Fiber Thermoset Composites Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Green Composites Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Composite Preforms Market