
 Static Seals Market | 2026-2036
Static Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Static Seals Market Analytics
Modular seal kits bundling O-rings with gaskets and installation hardware is restructuring buyer procurement patterns across maintenance-intensive sectors. Freudenberg and Co. KG leverages its captive polymer compounding network to control material consistency. Parker Hannifin Corp. anchors North American distribution through integrated fluid power channels. Trelleborg AB competes on marine and offshore specialization with customized flat seal geometries.
Static seals are non-dynamic sealing elements engineered to prevent fluid or gas leakage between stationary mating surfaces, typically manufactured from elastomeric compounds with Shore A hardness ratings between 50 and 90 or from sintered PTFE with specific compressive creep resistance. These components serve primarily to maintain system integrity under static pressure loads in piping flanges, equipment housings, and structural joints. Gaskets dominate volume demand in industrial equipment applications where flange sealing tolerances are widest, while PTFE-based flat seals command premium positioning in chemical processing due to thermal and solvent resistance. Rubber O-rings sustain the largest installed base across automotive OEM assemblies, though silicone variants are gaining fastest in aerospace thermal management zones.
The U.S. EPA regulates volatile organic compound emissions from seal degradation under Clean Air Act frameworks, pushing compounders toward low-permeability fluoroelastomer formulations. REACH compliance in Europe restricts phthalate plasticizers and specific curing agents, forcing reformulation of conventional nitrile and EPDM seal stocks. Japan's METI energy-efficiency standards for industrial machinery indirectly tighten leakage-rate specifications for static seal interfaces. Stakeholders must monitor evolving material restriction lists and pre-qualify alternative compounds before supply chain disruptions force emergency substitutions.
Market Dynamics
Fluorocarbon formulation upgrades for next-generation propulsion systems are compressing qualification timelines while aerospace OEMs consolidate supplier bases around captive polymer compounding capabilities.
Growth Catalysts
- REACH Annex XVII restrictions:Phthalate plasticizer bans across Europe are accelerating fluoroelastomer substitution in nitrile-dependent industrial equipment, opening volume for low-permeability compounders.
- Aerospace thermal management zones:Silicone O-ring variants are displacing conventional elastomers in engine nacelle and auxiliary power unit sealing as operating temperatures climb above 200°C.
- Germany's industrial manufacturing corridor:Stuttgart and Munich machinery clusters are standardizing modular seal kits bundling O-rings with gaskets and installation hardware, restructuring MRO procurement patterns.
Market Restraints
- Fluoropolymer feedstock concentration:Virgin PTFE resin supply concentrates among three global chemical conglomerates, exposing compounders to price volatility and allocation risk during semiconductor industry demand spikes.
- Clean Air Act VOC frameworks:U.S. EPA volatile organic compound emission limits from seal degradation create formulation compliance costs that disproportionately burden small-batch custom seal fabricators.
- Metallic seal substitution:Sintered metal face seals are capturing share in ultra-high-pressure hydrogen infrastructure above 700 bar where elastomeric creep failure modes become unacceptable.
Strategic Opportunities
- India's PLI scheme for industrial machinery:Domestic content requirements in the Production Linked Incentive framework are creating localized seal manufacturing demand as European and Japanese OEMs establish assembly operations.
- Offshore wind installation vessels:Customized flat seal geometries for dynamic positioning systems and cable lay equipment represent uncontracted white space outside traditional oil and gas marine specifications.
- Japan METI energy-efficiency standards:Leakage-rate tightening for industrial compressors and pumps is mandating precision-molded seal interfaces that command premium positioning over cut-gasket alternatives.
Industry Challenges
- Fluoroelastomer compounding expertise scarcity:Formulation chemists capable of balancing FKM compression set resistance against low-temperature flexibility are concentrated among retirees and a handful of specialized technical institutes.
- FAA fire-resistance certification timelines:New material qualifications for aircraft engine seals require 18-36 month test cycles that lock working capital and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static Seals Market |
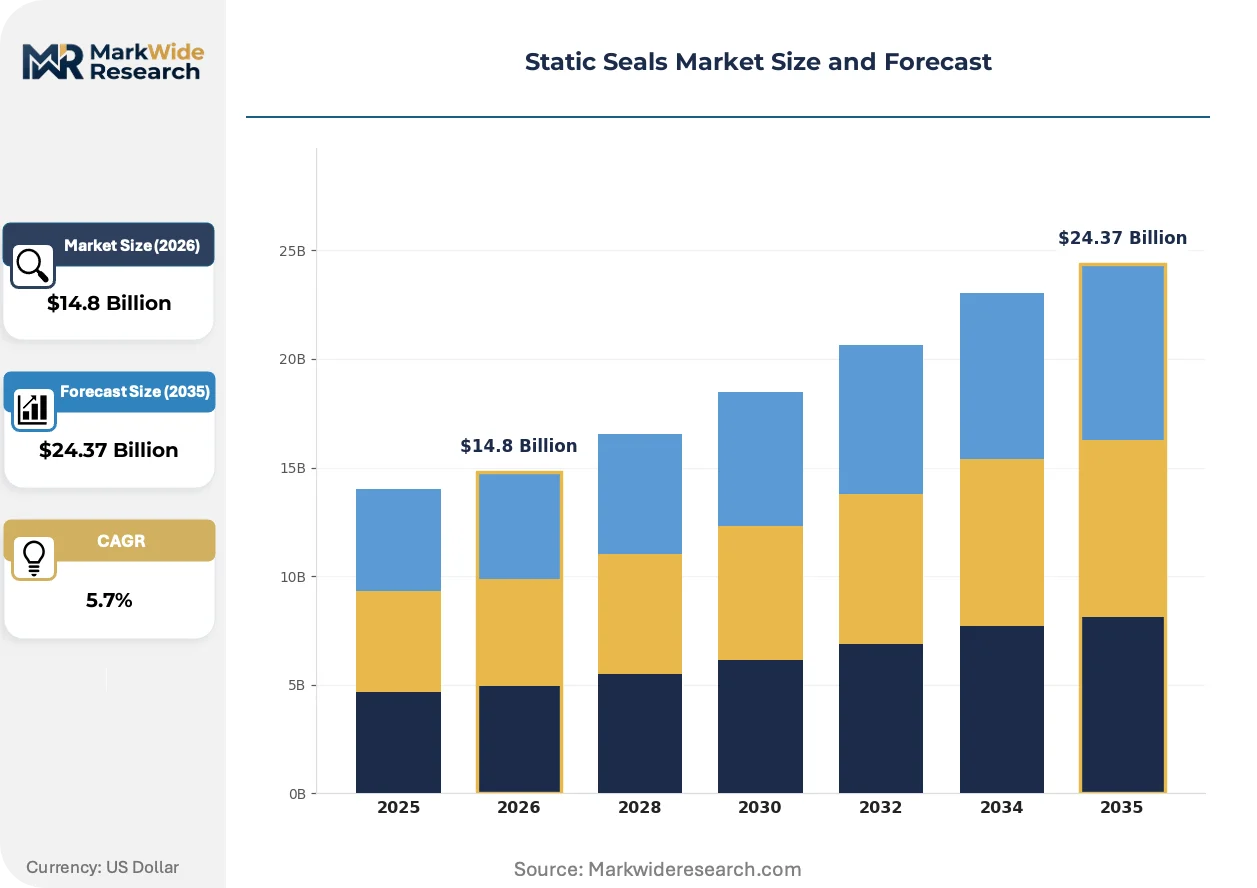
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Sealing Strips, Flat Seals Material: Rubber, Silicone, PTFE, Metal Application: Automotive, Aerospace, Industrial Equipment, Construction End User: Manufacturers, OEMs, Maintenance Providers, Distributors |
| Companies Covered | Freudenberg and Co. KG, Garlock Sealing Technologies LLC, AB SKF, NOK Corp., Greene Tweed and Co., Trelleborg AB, Hallite Seals International Ltd., A.W. Chesterton Co., Parker Hannifin Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static Seals Market Evolving Landscape
Material science advances and regulatory emission tightening are converging to reshape compound selection, manufacturing processes, and buyer-supplier contracting structures across static seal categories.
Multi-material seal kits combining O-rings, backup rings, and installation fixtures into single SKUs are modularizing procurement for maintenance-intensive sectors. Fleet operators in chemical processing and power generation are consolidating vendor lists around these bundled offerings. This standardization is compressing spot-buy margins for standalone gasket and O-ring distributors.
REACH compliance deadlines for restricted curing agents are forcing reformulation of conventional EPDM and nitrile seal stocks across European industrial equipment supply chains. Compounders are pre-qualifying peroxide-cure alternatives ahead of sunset dates to avoid forced substitutions. Germany's machinery OEMs are most exposed given their reliance on legacy sulfur-cure EPDM water-handling seals.
Integrated fluid power channels are capturing aftermarket static seal volume previously flowing through independent distributors. Buyers in North American mobile hydraulics are consolidating purchases of seals, hoses, and fittings under single-source agreements with full-line suppliers. This channel consolidation is visible most acutely in construction equipment and agricultural machinery service parts.
Static Seals Market Segmentation
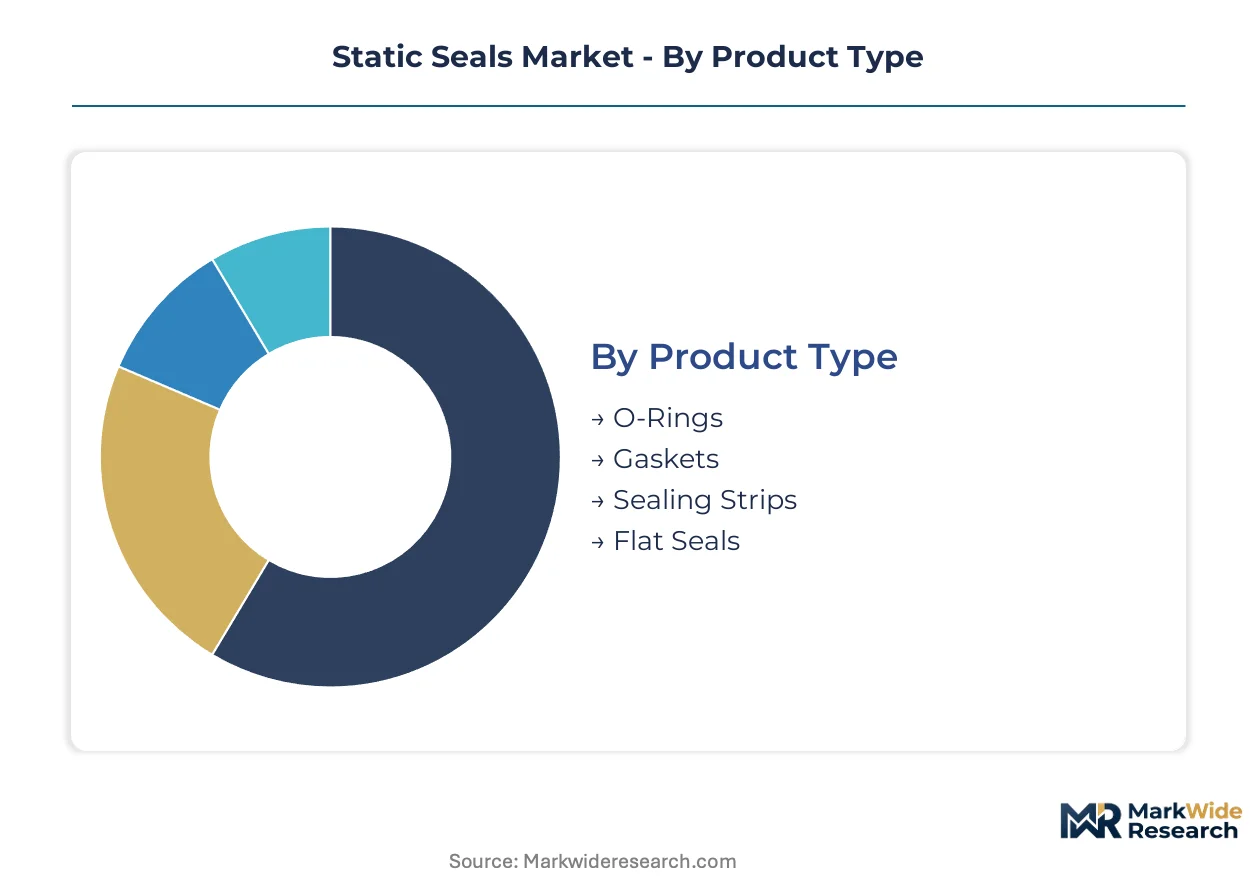
Static seal procurement patterns diverge sharply between high-volume standardized components and engineered solutions commanding material premiums. Understanding these segment boundaries reveals where compounders capture margin versus where distributors fight for share.
Product Type:
Gaskets dominate absolute volume through industrial flange applications, while O-rings concentrate value in precision-molded automotive and aerospace assemblies.
- O-Rings:Precision-molded elastomeric toroids with Shore A hardness calibrated to groove compression requirements. Automotive OEM assemblies in Germany's Stuttgart corridor sustain the largest installed base, though silicone variants are gaining fastest in aerospace thermal zones above 200°C.
- Gaskets:Compressible sheet materials die-cut or waterjet-profiled to flange geometries, spanning fiber-reinforced elastomer, spiral-wound metal, and solid metal configurations. Industrial equipment applications with widest sealing tolerances drive volume demand, with modular seal kits bundling gaskets with hardware restructuring MRO procurement.
- Sealing Strips:Extruded elastomer profiles for linear joint applications in construction glazing and transportation panel sealing.
- Flat Seals:Sintered PTFE or modified polymer plates for chemical processing and semiconductor equipment, commanding premium positioning through thermal and solvent resistance.
Today's leader: Gaskets. Tomorrow's challenger: O-Rings.
Material:
Compound selection tracks operating environment severity, with fluoroelastomer and PTFE formulations capturing margin in chemical and aerospace extremes while nitrile and EPDM fight for industrial volume.
- Rubber:Nitrile and EPDM compounds serve cost-sensitive industrial and automotive applications, though REACH Annex XVII phthalate restrictions are forcing reformulation of legacy sulfur-cure stocks.
- Silicone:VMQ and FVMQ formulations tolerate continuous service from -60°C to 230°C. Aerospace engine nacelle and auxiliary power unit sealing are displacing conventional elastomers as operating temperatures climb.
- PTFE:Virgin and filled polytetrafluoroethylene with specific compressive creep resistance for chemical processing. Virgin resin supply concentrates among three global chemical conglomerates, exposing compounders to allocation risk.
- Metal:Sintered stainless steel, aluminum, and specialty alloys for ultra-high-pressure hydrogen infrastructure above 700 bar where elastomeric creep failure becomes unacceptable.
Rubber and silicone currently anchor volume. PTFE and metal formulations are climbing the fastest as process severity intensifies.
Application:
Aerospace and industrial equipment segments separate by qualification burden, with FAA fire-resistance certification timelines locking working capital for 18-36 months in aviation while industrial buyers rotate suppliers faster.
- Automotive:Powertrain, HVAC, and fluid handling assemblies with standardized O-ring grooves and gasket flange specifications. Rubber O-rings sustain the largest installed base across OEM assemblies.
- Aerospace:Engine, fuel system, and thermal management sealing with material traceability and fire-resistance mandates. Fluorocarbon formulation upgrades for next-generation propulsion systems are compressing qualification timelines.
- Industrial Equipment:Pumps, compressors, valves, and process vessels with broadest tolerance ranges. Japan's METI energy-efficiency standards are tightening leakage-rate specifications for static seal interfaces.
- Construction:Building envelope, glazing, and infrastructure joint sealing with weathering and fire-code requirements.
Industrial equipment commands current volume leadership. Aerospace offers the steepest expansion trajectory through propulsion system upgrades.
End User:
Channel structure determines margin capture, with integrated fluid power distributors consolidating aftermarket volume while OEMs demand captive compounding capabilities.
- Manufacturers:In-house seal production for captive consumption, rare outside largest automotive and aerospace OEMs with polymer compounding expertise.
- OEMs:Original equipment assemblers specifying seals for new build, consolidating supplier bases around qualified compounders with batch traceability.
- Maintenance Providers:Fleet operators and industrial MRO buyers standardizing modular seal kits to compress vendor lists and spot-buy margins.
- Distributors:Independent and integrated channels, with full-line fluid power suppliers capturing aftermarket volume previously flowing through standalone gasket and O-ring specialists.
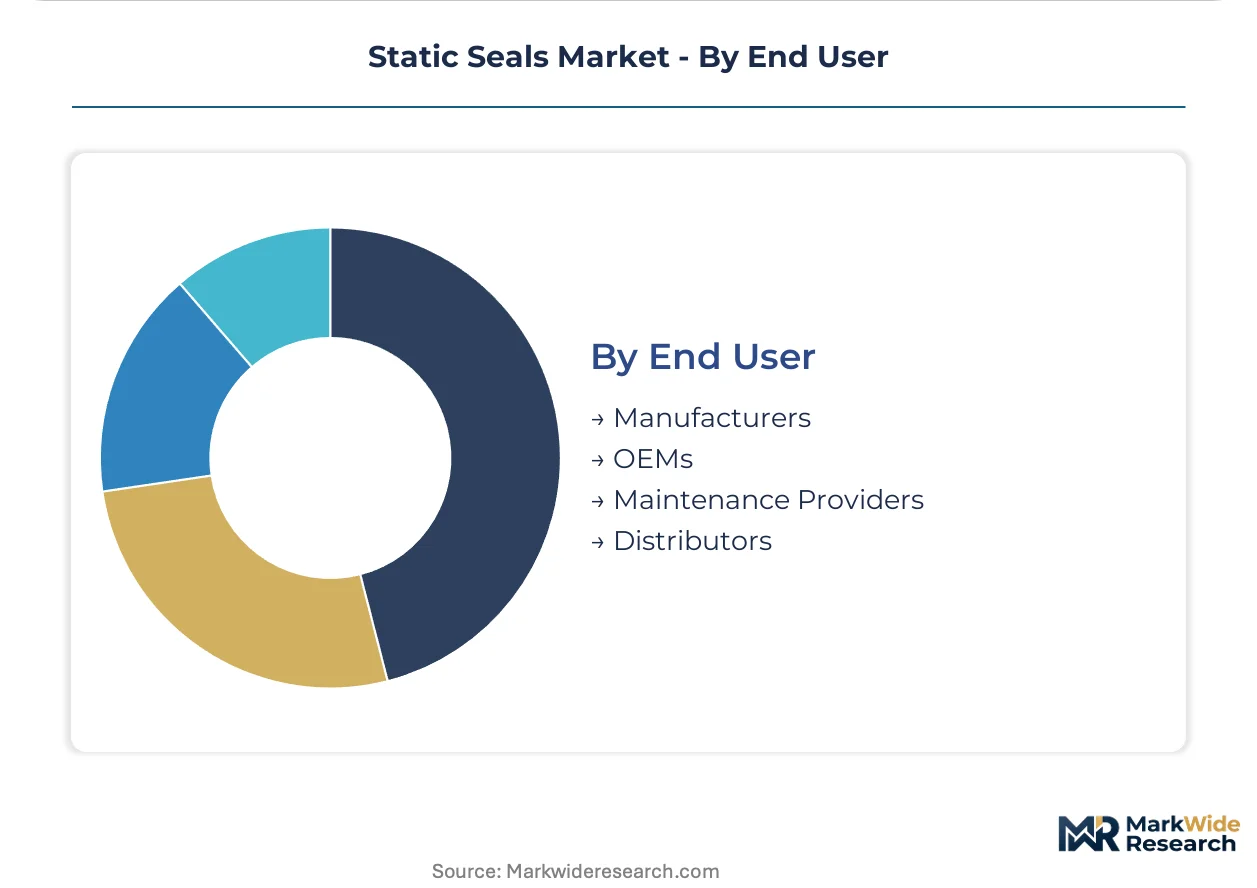
OEMs anchor premium positioning. Maintenance providers are gaining procurement leverage fastest through kit standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision elastomer compounding for industrial machinery in the early 20th century, establishing the technical foundation that now supports global static seal supply chains. The industry has since diffused across manufacturing corridors in Asia-Pacific and North America, with regional demand patterns tracking local regulatory tightening and industrial cluster formation.
United States
Aerospace OEMs in Seattle and Wichita are expanding fluorocarbon seal procurement for next-generation propulsion systems. The FAA and EPA impose 18-36 month fire-resistance certification cycles and VOC emission limits that compress supplier margins. Texas Gulf Coast petrochemical clusters drive demand for PTFE flat seals in process equipment.
Germany
Stuttgart and Munich machinery OEMs are standardizing modular seal kits that bundle O-rings with gaskets and installation hardware. REACH Annex XVII phthalate restrictions force reformulation of legacy sulfur-cure EPDM compounds. Baden-Württemberg's automotive supply base sustains Europe's largest precision-molded O-ring demand.
Japan
METI energy-efficiency standards for industrial compressors and pumps mandate precision-molded seal interfaces that displace cut-gasket alternatives. Nagoya's aerospace component cluster qualifies silicone variants for thermal management zones above 200°C. Osaka-based compounders face fluoroelastomer formulation chemist scarcity as veteran retirees exit.
China
Yangtze River Delta machinery builders are absorbing European seal kit designs for domestic MRO standardization. MIIT industrial upgrading programs tighten leakage-rate specifications for pumps and valves. Shanghai's petrochemical equipment fabricators concentrate demand for virgin PTFE resin despite allocation risks from semiconductor industry competition.
India
PLI scheme domestic content requirements are pulling European and Japanese OEMs toward localized seal manufacturing partnerships. Maharashtra and Gujarat industrial corridors host emerging assembly operations for pumps and compressors. BIS standards adoption lags REACH-equivalent chemical restrictions, creating formulation complexity for multinational compounders.
Static Seals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material qualification burden and captive compounding capabilities. The vendor base arranges into three tiers: integrated fluid power distributors capturing aftermarket volume, specialized marine and aerospace compounders commanding formulation premiums, and regional fabricators competing on die-cut gasket turnaround speed. Consolidation pressure concentrates among mid-scale custom seal houses facing REACH compliance cost absorption. Strategic moves center on backward integration into polymer compounding and geographic expansion through modular kit licensing.
Within the integrated distribution tier, Parker Hannifin Corp. anchors North American aftermarket channels through fluid power bundling. Freudenberg and Co. KG exemplifies the captive compounding archetype with in-house material consistency control. Trelleborg AB occupies the marine specialization position with customized flat seal geometries for offshore applications.
| Leading Market Players |
|---|
| Freudenberg and Co. KG |
| Garlock Sealing Technologies LLC |
| AB SKF |
| NOK Corp. |
| Greene Tweed and Co. |
| Trelleborg AB |
| Hallite Seals International Ltd. |
| A.W. Chesterton Co. |
| Parker Hannifin Corp. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FAA-qualified aerospace seals and commodity industrial gaskets generates divergent margin architectures across supply chain configurations. Premium compounders capture pricing power through 18-36 month fire-resistance qualification cycles that lock out spot-market competitors, while standard gasket fabricators face cost compression from modular kit bundling in Germany's Stuttgart corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with fluoroelastomer aerospace seals commanding material premiums against nitrile industrial volumes. Price differentiation rests on REACH compliance certification and batch traceability rather than raw compound cost alone. Cost compression in standard-grade EPDM gaskets is intensifying because REACH Annex XVII phthalate restrictions force emergency reformulation. Maintenance providers exhibit highest price sensitivity through consolidated kit procurement, while aerospace OEMs absorb premiums for qualified captive compounding.
Supply Chain Analysis
India's PLI scheme domestic content requirements are pulling European and Japanese OEMs toward localized seal manufacturing partnerships, fragmenting historically concentrated sourcing patterns. Virgin PTFE resin supply centers on Germany, China, and the United States, drawing from semiconductor industry demand competition. Fluoropolymer feedstock concentration creates single-source vulnerability when allocation spikes hit resin markets. Distribution runs through integrated fluid power channels in North America and modular kit licensors in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed formulation investment thresholds in India, creating margin relocation incentives for compounders with multi-plant footprints.
For Market Incumbents: Anticipate metallic seal substitution in hydrogen infrastructure above 700 bar by anchoring fluoroelastomer formulation expertise through captive polymer compounding networks. Consolidate supplier relationships with Stuttgart machinery OEMs standardizing modular seal kits to compress spot-buy competition. Channel control through integrated fluid power distribution defends position against independent gasket distributors.
For New Entrants and Emerging Players: Peroxide-cure EPDM alternatives to sulfur-cure stocks offer a technology-first wedge into Germany's water-handling equipment retrofit market. Target India's Maharashtra and Gujarat industrial corridors where PLI domestic content requirements outpace qualified local supply. A joint venture with established European compounders accelerates BIS standards navigation.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance cost absorption exceeds revenue scale for mid-batch custom seal fabricators. Five-to-ten year viability favors compounders with backward integration into virgin resin relationships or peroxide-cure formulation IP. Acquisition target archetype: specialized marine flat seal designers with offshore wind vessel qualifications. Watch for FAA certification timeline compression as next-generation propulsion programs accelerate.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Freudenberg's captive network controls material consistency against virgin PTFE allocation risk. |
| Modular Seal Kit Licensing | Parker Hannifin anchors North American aftermarket through bundled O-ring and gasket procurement. |
| Peroxide-Cure Formulation Pre-Qualification | German compounders avoid REACH Annex XVII sunset disruptions in EPDM water-handling seals. |
| Offshore Wind Flat Seal Specialization | Trelleborg captures uncabled white space in dynamic positioning systems outside oil and gas specifications. |
| India PLI Localization Partnership | European OEMs establish Maharashtra assembly operations to satisfy domestic content requirements. |
Research Methodology
Direct dialogue with plant maintenance directors, OEM procurement teams, aftermarket service heads, and fluoroelastomer formulation chemists grounded qualitative findings in operational reality. Secondary validation drew from customs trade data, SEC 10-K filings, ECHA REACH restriction updates, and BIS standards documentation. Bottom-up and top-down triangulation cross-checked volume estimates against resin consumption patterns and equipment installation bases.
Bottom-up modeling tracked segment-level demand across product type, material compound, application severity, and end-user channel structure over the projection horizon. Top-down validation anchored aggregate market size to industrial machinery production indices and aerospace OEM delivery schedules. CAGRs were derived from equipment replacement cycles, regulatory compliance deadlines, and regional manufacturing cluster formation. Forecast inputs incorporated MIIT leakage-rate tightening timelines and FAA fire-resistance certification velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluoropolymer feedstock allocation shocks, REACH restriction scope expansion, and hydrogen infrastructure metallic seal substitution velocity. Forecasts reflect documented assumptions regarding qualification timeline stability and regional regulatory harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Top Drive Systems Market
Valves
North America Residential Ball Valves Market
Valves
Expansion Valves Market
Valves
Global Gas Pressure Regulator Market
Valves
Safety Valve Market
Valves
Isolator Valves Market
Valves
Refrigeration Valves Market
Valves
North America Valves Market
Valves
Bend Restrictors and Stiffeners Market
Valves
One-Way Valve Market
Valves
Pneumatic Slide Gates Market
Valves
Pup Joint Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Europe Medium Voltage Switchgear Market
Valves
Safety Valve Test Benches Market
Valves
Ball Valves Market