
 Hydrostatic Steam Blancher Market | 2026-2036
Hydrostatic Steam Blancher Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrostatic Steam Blancher Market Analytics
Contract food manufacturers and private-label frozen vegetable packers is bifurcating demand away from small in-house operations across the Hydrostatic Steam Blancher landscape. JBT sustains its position through deep specialization in continuous steam infusion systems for high-volume vegetable processors. Laitram Machinery leverages vertical integration into stainless steel conveyor fabrication to control lead times on custom hydrostatic designs. GEA competes by anchoring its portfolio in heat exchanger-based indirect heating configurations that reduce water usage in European plants.
A hydrostatic steam blancher immerses product in a temperature-controlled water column while injecting pressurized steam to achieve uniform thermal treatment, typically operating at 85–100°C for 1–10 minutes depending on product density. This equipment preserves color, texture, and nutritional value while inactivating enzymes prior to freezing, canning, or dehydration. Continuous blanchers dominate installed capacity due to throughput advantages in high-volume vegetable processing lines, though automatic blanchers represent the fastest-growing configuration as mid-size processors automate to reduce labor dependency. Direct steam injection technology leads in new installations for its energy efficiency, while heat exchanger systems retain share where water recovery mandates apply.
The FDA enforces preventive controls validation for thermal processing equipment under FSMA, pushing processors toward instrumented blanchers with continuous temperature logging. USDA-graded facilities must document time-temperature parameters for each lot, favoring suppliers whose control systems integrate directly with plant HACCP databases. Equipment buyers should monitor how EU Green Deal water-efficiency targets and emerging state-level energy benchmarking in California reshape total-cost-of-ownership calculations for steam-intensive processing lines.
Market Dynamics
Clean-label mandates from retail chains are forcing frozen vegetable processors to validate thermal treatment with instrumented blanchers that log time-temperature data for every lot, compressing demand toward automated continuous lines and away from manual batch equipment.
Growth Catalysts
- FDA Preventive Controls Rule:FSMA mandates for thermal processing validation push processors toward blanchers with integrated HACCP data logging, accelerating replacement cycles in USDA-graded facilities.
- Direct Steam Injection:This technology reduces energy consumption per unit processed compared to heat exchanger configurations, attracting high-volume vegetable freezing operations seeking operational cost containment.
- Lower Saxony Cluster:Germany's concentration of large-scale vegetable freezing facilities around this region generates concentrated demand for high-throughput continuous blanching lines with rapid delivery requirements.
Market Restraints
- Stainless Steel Input Volatility:Fluctuations in nickel and chromium prices directly impact fabrication costs for hydrostatic conveyor systems, compressing margins for custom equipment builders.
- Water Recovery Mandates:EU Green Deal water-efficiency targets in certain member states create compliance friction for direct steam injection systems, forcing costly retrofits or technology switching.
- Heat Exchanger Substitution:Indirect heating configurations retain installed base share where water usage restrictions apply, limiting penetration of more energy-efficient direct steam alternatives.
Strategic Opportunities
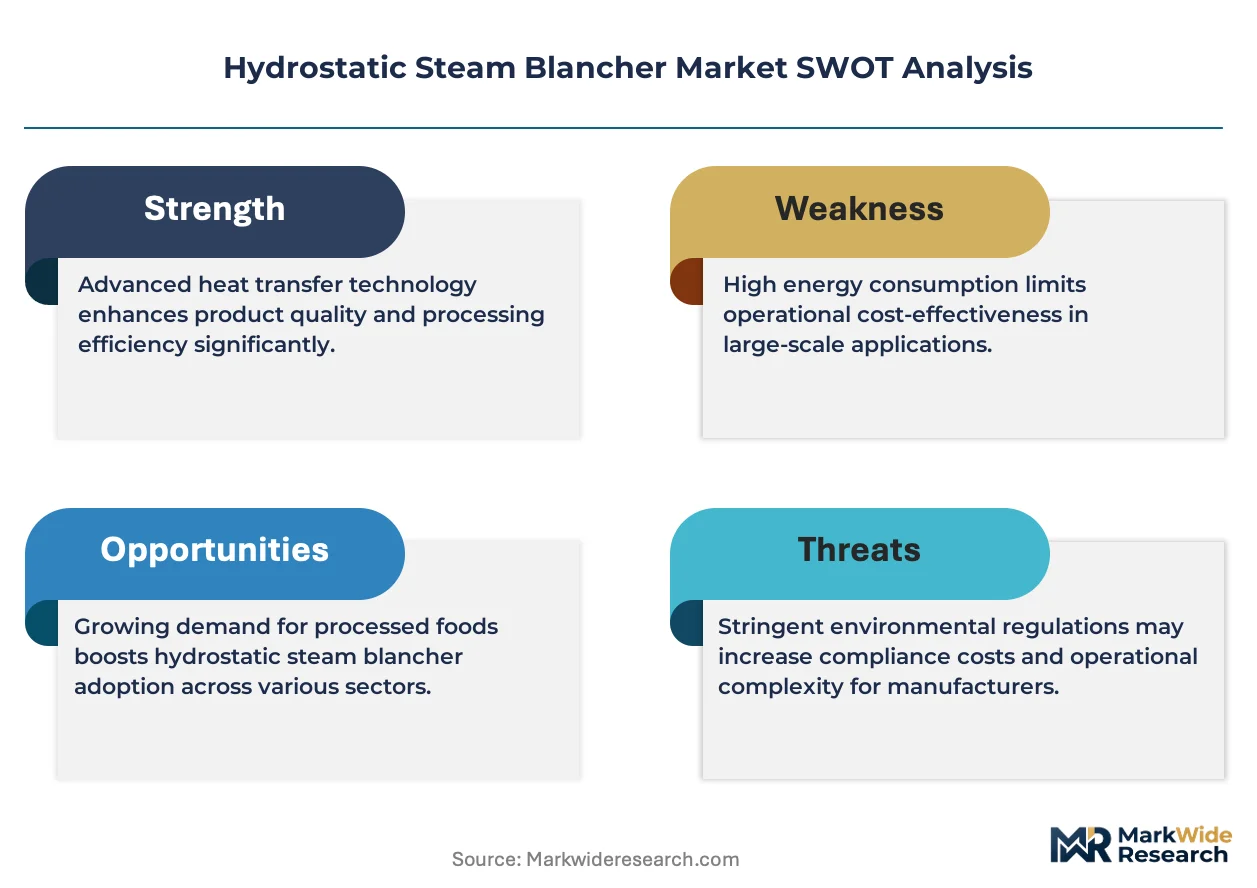
- California Energy Benchmarking:Emerging state-level energy performance standards for industrial steam systems create first-mover advantage for suppliers offering heat recovery and condensate return packages.
- Contract Manufacturing Pivot:Private-label frozen vegetable packers are consolidating processing capacity, opening volume contracts for automated blanching lines with integrated quality control systems.
- Mid-Size Processor Automation:Automatic blancher configurations address labor dependency concerns at facilities below continuous line scale, representing underserved demand between batch and high-volume segments.
Industry Challenges
- Thermal Validation Expertise Gap:Process engineers capable of documenting time-temperature parameters for FDA compliance remain scarce, extending commissioning timelines and increasing training burdens.
- Legacy Control System Integration:Instrumented blanchers must interface with existing plant SCADA and HACCP databases, creating protocol compatibility issues that delay deployment.
- Capex Intensity for Continuous Lines:High-throughput automated systems require substantial upfront investment, constraining adoption at processors with limited balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrostatic Steam Blancher Market |
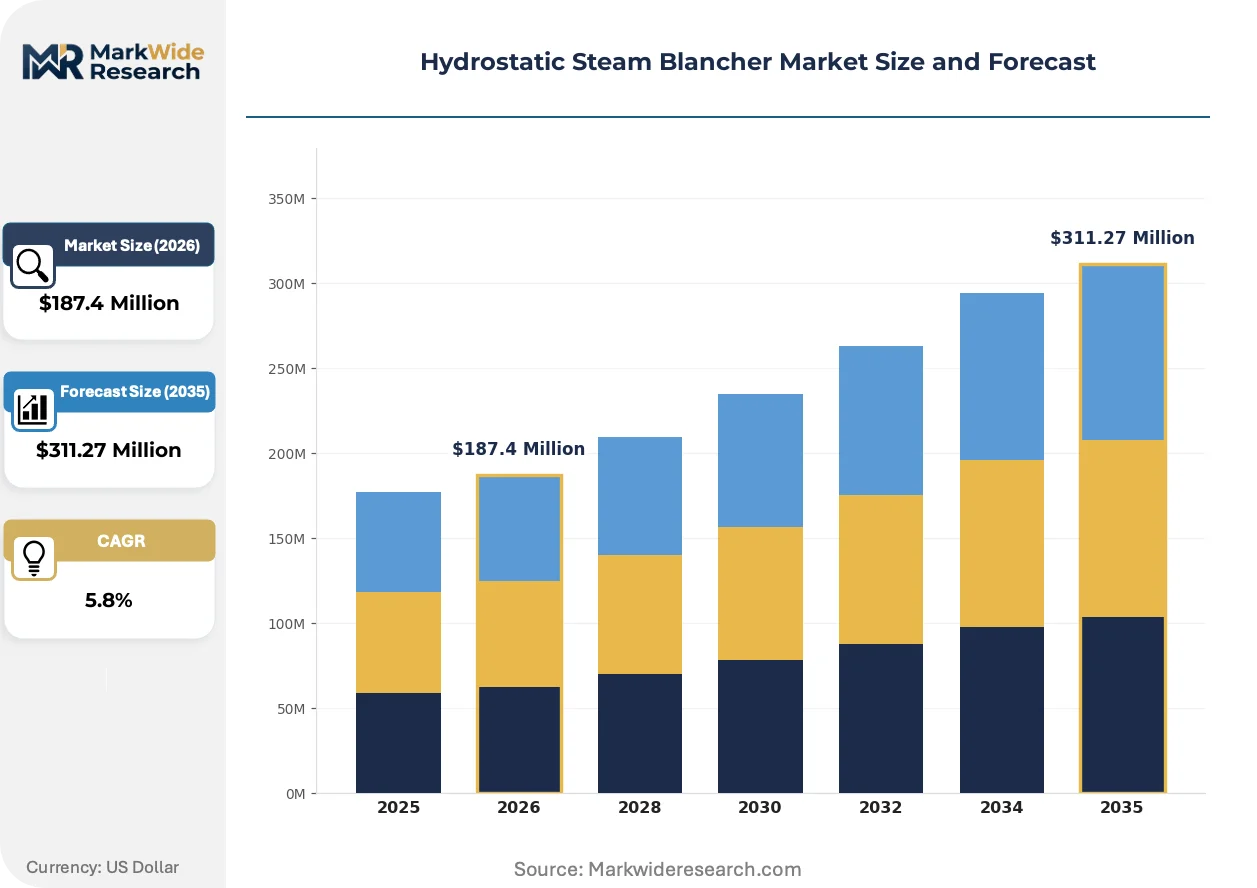
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Blanchers, Continuous Blanchers, Automatic Blanchers, Manual Blanchers Technology: Direct Steam Injection, Heat Exchangers, Indirect Heating, Steam Infusion End User: Food Processing Plants, Catering Services, Research Institutions, Fresh Produce Suppliers Application: Vegetable Processing, Fruit Processing, Seafood Processing, Ready-to-Eat Meals |
| Companies Covered | Laitram Machinery, JBT, GEA, OctoFrost AB, Lyco Manufacturing, Marel, Cabinplant A/S, Henan Huafood Machinery Technology, TOFFON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrostatic Steam Blancher Market Evolving Landscape
Equipment architecture is converging around energy recovery and data integration, with three distinct vectors reshaping how thermal treatment systems are specified, deployed, and validated across frozen food processing operations.
Direct steam injection technology is supplanting indirect heating configurations in new installations across high-volume vegetable processing lines. European facilities with less stringent water recovery requirements are adopting these systems most aggressively. The shift is compressing market share for heat exchanger-based designs that dominated prior generations of installed capacity.
EU Green Deal water-efficiency targets are tightening discharge standards for industrial steam operations. Processors in affected member states must document condensate recovery rates and thermal efficiency metrics. Heat exchanger systems with closed-loop water circuits are capturing replacement demand in these jurisdictions despite higher capital requirements.
Retail chain auditing protocols are compressing procurement cycles for blanching equipment with integrated quality documentation. Frozen food co-packers serving multiple retail banners now prioritize systems that automatically generate lot-specific time-temperature records. Germany's contract manufacturing sector exhibits the strongest preference for these instrumented configurations.
Hydrostatic Steam Blancher Market Segmentation
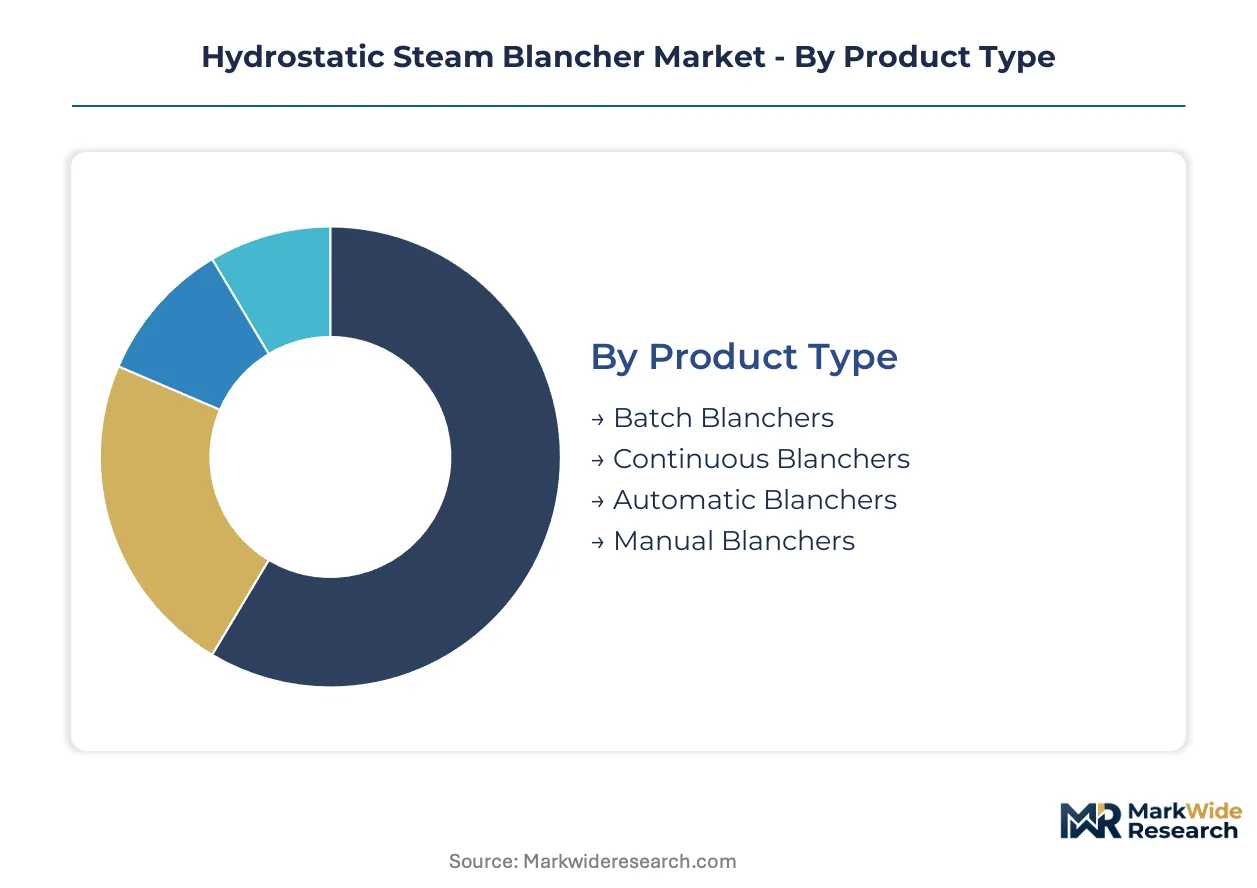
Segmentation in hydrostatic steam blanching equipment reflects divergent capital intensity, throughput requirements, and regulatory compliance burdens across frozen food processing operations. Buyers select configurations based on lot traceability mandates, energy benchmarking rules, and water recovery obligations that vary by facility scale and geographic jurisdiction.
Product Type:
Batch blanchers face the strongest substitution pressure from continuous lines as high-volume processors abandon manual loading to meet FDA preventive controls validation requirements.
- Continuous Blanchers:These systems integrate conveyor-driven product movement with pressurized steam injection columns operating at 85–100°C, enabling throughput rates that satisfy large-scale vegetable freezing facilities clustered around Germany's Lower Saxony region. Demand concentrates where USDA-graded operations require lot-specific time-temperature documentation for every production batch.
- Automatic Blanchers:Programmable logic controllers manage steam injection timing and water column temperature with minimal operator intervention, addressing labor dependency concerns at mid-size processors below continuous line scale. Contract food manufacturers in California are adopting these configurations to comply with emerging state energy benchmarking standards while maintaining operational flexibility.
- Batch Blanchers:Intermittent loading designs serve research institutions and small-scale fresh produce suppliers with variable product mixes and low volume requirements.
- Manual Blanchers:Operator-dependent systems retain niche presence in catering services with minimal regulatory oversight and irregular production schedules.
Continuous blanchers anchor the volume base while automatic blanchers gain share at the steepest rate.
Technology:
Cost tier differentiation separates capital-intensive heat recovery systems from energy-efficient direct injection alternatives, with water recovery mandates in EU member states forcing technology switching at existing facilities.
- Direct Steam Injection:Pressurized steam enters the water column through submerged nozzles, achieving rapid temperature uniformity with lower energy consumption per unit processed than indirect alternatives. High-volume vegetable freezing operations in water-abundant jurisdictions favor this configuration for operational cost containment.
- Heat Exchangers:Closed-loop water circuits recover thermal energy from condensate discharge, satisfying EU Green Deal water-efficiency targets in member states with stringent discharge standards. European plants facing water usage restrictions specify these systems despite higher capital requirements and longer payback periods.
- Indirect Heating:External heat sources warm the water column without steam-water mixing, serving facilities with limited boiler capacity or specialized product sensitivity requirements.
- Steam Infusion:High-velocity steam injection creates turbulent mixing for delicate products requiring precise temperature control, finding application in ready-to-eat meal processing where texture preservation is critical.
Heat exchangers dominate replacement demand in water-constrained jurisdictions while direct steam injection expands most quickly in new installations.
End User:
Application scale determines specification complexity, with food processing plants driving instrumented configurations and research institutions prioritizing experimental flexibility over throughput.
- Food Processing Plants:Frozen vegetable packers and canneries specify blanchers with integrated HACCP data logging to satisfy retail chain auditing protocols and FDA FSMA preventive controls mandates. Germany's contract manufacturing sector exhibits the strongest preference for these instrumented systems.
- Fresh Produce Suppliers:Pre-freezing operations serving multiple retail banners require rapid product changeover capabilities and automated quality documentation to manage diverse customer specifications.
- Catering Services:Centralized kitchen operations deploy compact batch units with minimal utility infrastructure requirements.
- Research Institutions:Pilot-scale facilities prioritize adjustable process parameters and data acquisition systems for product development and thermal validation studies.
Food processing plants generate the dominant equipment volume while fresh produce suppliers demonstrate the steepest adoption trajectory for automated configurations.
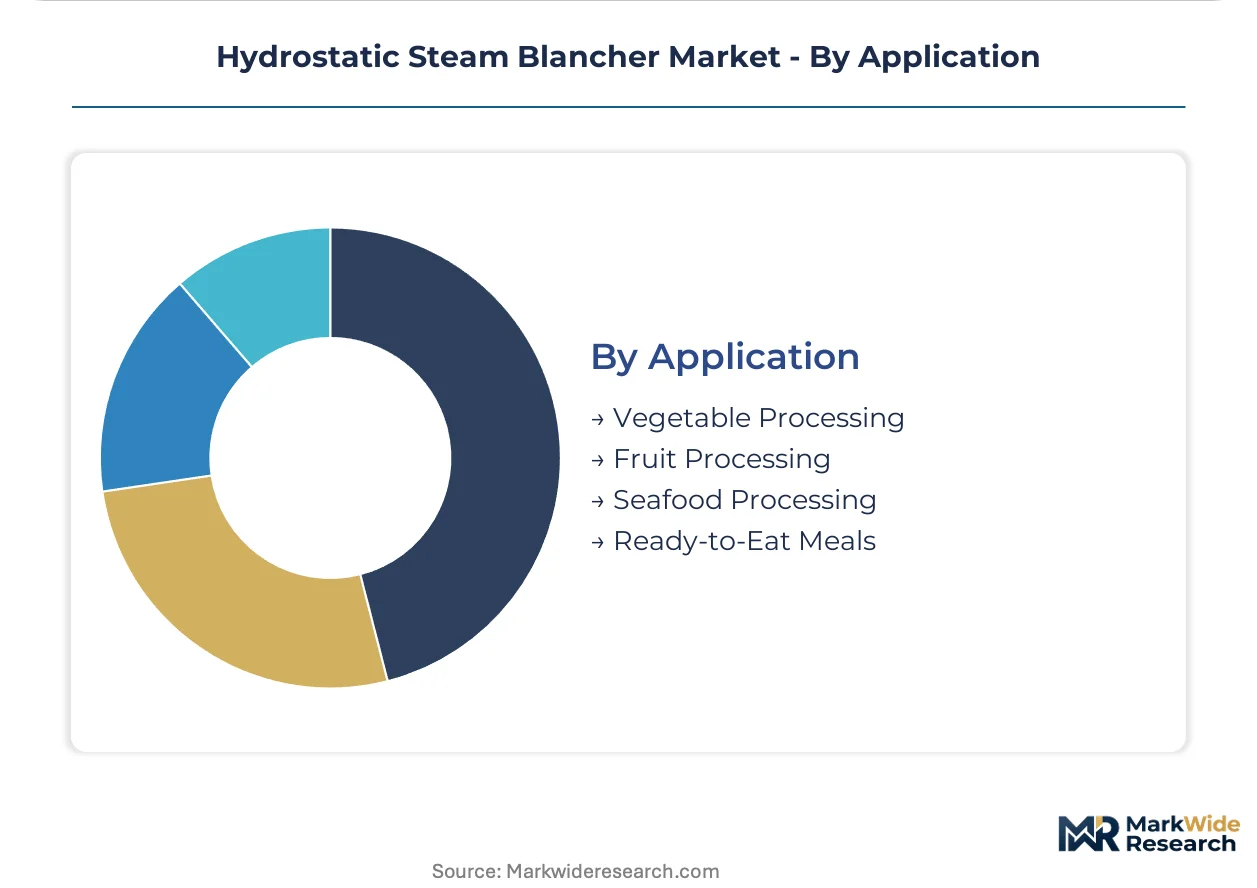
Application:
Product density and enzyme inactivation requirements create divergent processing time specifications, with vegetable processing demanding the most standardized equipment platforms.
- Vegetable Processing:Broccoli, green beans, and leafy greens require 1–10 minute blanching cycles depending on density, driving demand for continuous lines with precise temperature control to preserve color and nutritional value prior to freezing. Lower Saxony's freezing facility concentration shapes regional specification patterns.
- Ready-to-Eat Meals:Multi-component products with varying thermal sensitivities necessitate flexible steam injection profiles and rapid cooling integration, attracting automatic blancher configurations with programmable recipe management.
- Fruit Processing:Delicate tissue structures limit mechanical handling intensity, favoring gentle conveyor designs and reduced water column turbulence.
- Seafood Processing:Pathogen reduction requirements and protein denaturation constraints create specialized temperature-time protocols distinct from plant-based applications.
Vegetable processing anchors the installed base while ready-to-eat meal applications climb the fastest as convenience food manufacturers automate thermal treatment lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's dominance in frozen vegetable logistics, while the Rhine-Main-Danube corridor connects processing clusters to Central European markets.
Germany
Lower Saxony's vegetable freezing corridor generates concentrated demand for high-throughput continuous blanching lines, with facilities clustered around Wolfsburg and Hanover. The EU Green Deal water-efficiency targets force technology switching toward heat exchanger configurations in facilities facing discharge restrictions. Contract manufacturers in this region prioritize instrumented systems with integrated HACCP data logging to satisfy retail chain auditing protocols.
United States
California's Central Valley vegetable processors drive adoption of automatic blancher configurations to comply with emerging state energy benchmarking standards for industrial steam systems. The FDA's FSMA preventive controls rule mandates thermal treatment validation, pushing facilities toward instrumented equipment with continuous temperature logging. Frozen food co-packers in the Salinas-Watsonville corridor consolidate processing capacity, opening volume contracts for automated lines.
China
Shandong Province's vegetable processing belt anchors domestic demand for direct steam injection technology, with facilities prioritizing energy efficiency over water recovery. The country's dual carbon goals pressure processors to document thermal efficiency metrics and condensate recovery rates. Qingdao-based exporters serving European markets face EU import documentation requirements, favoring suppliers with instrumented control systems.
Netherlands
The Randstad's food technology corridor concentrates R&D-intensive blanching equipment demand, with pilot-scale facilities testing novel steam infusion configurations. REACH chemical safety regulations influence stainless steel specification standards for conveyor fabrication. Wageningen University's food processing research cluster shapes regional specification patterns toward experimental flexibility.
India
Maharashtra's Nashik-Satara vegetable processing corridor scales frozen food exports to European markets, driving demand for FDA-compliant thermal treatment documentation. FSSAI food safety regulations tighten process validation requirements for export-oriented facilities. Pune-based contract manufacturers automate mid-scale operations to reduce labor dependency while maintaining operational flexibility.
Hydrostatic Steam Blancher Market Competitive Landscape
Concentration sits with diversified industrial equipment conglomerates that anchor the premium tier through integrated thermal processing portfolios. Mid-cap specialists occupy the custom fabrication segment with backward integration into stainless steel conveyor production. The vendor base stratifies across three archetypes: scale-driven systems integrators, application-specific engineering houses, and regional fabricators serving emerging markets. Competitive moves center on geographic expansion through distribution partnerships and technology licensing arrangements that transfer direct steam injection expertise to local assembly operations.
Among European-based systems integrators, GEA exemplifies the heat exchanger-specialized archetype with upstream control over thermal component fabrication. JBT represents the scale-driven tier with deep specialization in continuous processing configurations for high-volume vegetable operations. Laitram Machinery anchors the custom engineering segment through in-house production of stainless steel conveyor systems that compress lead times on hydrostatic designs. These three companies illustrate how competitive positioning diverges across technology vectors and customer scale requirements.
| Leading Market Players |
|---|
| Laitram Machinery |
| JBT |
| GEA |
| OctoFrost AB |
| Lyco Manufacturing |
| Marel |
| Cabinplant A/S |
| Henan Huafood Machinery Technology |
| TOFFON |
| Others |
Value Network & Pricing Analysis
Direct steam injection technology displacing heat exchanger configurations in new installations simultaneously redistributes supply geography toward water-abundant manufacturing clusters and compresses pricing premiums for energy-efficient systems. Stainless steel conveyor fabrication costs and nickel-chromium input volatility amplify margin pressure for custom equipment builders serving European water-constrained jurisdictions.
Pricing Analysis
Volume-discount tiering separates continuous line procurement for large-scale vegetable freezing facilities from automatic blancher configurations serving mid-size processors. Pricing stratifies across premium instrumented systems with integrated HACCP data logging, standard programmable configurations, and economy batch units with minimal automation. Cost compression in the standard tier intensifies as contract manufacturers consolidate processing capacity and negotiate fleet pricing. Frozen food co-packers exhibit the highest price sensitivity due to thin operating margins, while USDA-graded facilities prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
Germany and the Netherlands anchor precision fabrication for stainless steel conveyor systems and thermal component assemblies. China feeds raw material supply for nickel and chromium alloys, with Shandong Province hosting downstream equipment assembly for domestic and export markets. Supply chain vulnerability centers on single-source dependency for specialized steam injection nozzles and instrumented control modules. Distribution runs through regional systems integrators with captive service networks, direct OEM relationships with large freezing facilities, and third-party food technology distributors serving mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as private-label frozen vegetable packers consolidate processing capacity into fewer contract manufacturers with volume procurement leverage.
For Market Incumbents: Shield installed base share by embedding proprietary HACCP data logging protocols that raise switching costs for FDA-compliant facilities. Deepen backward integration into stainless steel conveyor production to compress lead times on custom hydrostatic designs and defend against emerging Asian equipment assemblers with cost-advantaged supply chains. For New Entrants and Emerging Players: Differentiate on rapid deployment capabilities for automatic blancher configurations serving California mid-size processors facing energy benchmarking compliance deadlines. Target the underserved segment between batch and continuous line scale with modular systems offering programmable recipe management and minimal commissioning overhead. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors specialists with captive control system expertise over diversified industrial conglomerates. Long-term viability hinges on regulatory compliance integration rather than pure manufacturing scale. Acquisition candidates with validated FDA thermal treatment documentation capabilities and established relationships with Germany's Lower Saxony freezing cluster warrant priority attention. Watch for inflection signals in EU Green Deal water-efficiency enforcement tightening that would accelerate heat exchanger replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery Package Integration | Condensate return systems satisfy California energy benchmarking standards for industrial steam operations. |
| HACCP Data Logging Certification | FDA FSMA preventive controls validation requirements favor instrumented blancher suppliers with direct database integration. |
| Stainless Steel Conveyor Captive Production | In-house fabrication compresses lead times for custom hydrostatic designs serving Germany's Lower Saxony cluster. |
| Direct Steam Injection Technology Licensing | Technology transfer agreements enable local assembly in China's Shandong vegetable processing belt. |
| Mid-Scale Automatic Blancher Launch | Programmable configurations address labor dependency at facilities below continuous line throughput requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with frozen vegetable processing plant engineers, contract manufacturing procurement leads, thermal equipment maintenance directors, and food safety compliance officers. Secondary validation drew from FDA FSMA guidance documents, EU Green Deal water-efficiency regulatory filings, USDA-graded facility inspection records, and stainless steel commodity trade data. Bottom-up equipment shipment tallies and top-down frozen food processing capacity estimates were triangulated to anchor volume projections.
Across the analysis window, the forecasting framework models demand by product type, technology configuration, end-user scale, and application segment, with geographic resolution at country level. CAGRs were derived from segment-specific adoption curves weighted by regulatory compliance deadlines and energy benchmarking phase-in schedules. Key inputs include frozen vegetable export volume trajectories from Germany's Lower Saxony corridor and California Central Valley processor automation timelines.
Material uncertainties — nickel-chromium price volatility, EU member state water discharge enforcement variance, and FDA inspection priority shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and thermal validation expertise availability. Recalibration cycles align with material shifts in clean-label retail auditing protocols and state-level energy performance standard adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Global Food Sterilization Machines Market