
 Commercial Oven Market | 2026-2036
Commercial Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Oven Market Analysis
The commercial oven category is restructuring around a sharp split between premium combi-systems and commodity convection units. Rational AG dominates the high-margin combi-oven segment through captive control of its cooking intelligence platform. Middleby Corporation competes across multiple price tiers through its portfolio of specialized brands including TurboChef and Blodgett. Electrolux Professional anchors European institutional demand with manufacturing scale in Italy and Sweden.
A commercial oven is a thermally insulated chamber designed for sustained operation above 200°F, employing forced convection, radiant heat, or combined steam-convection cycles to process food at commercial volumes. Combi ovens represent the fastest-expanding product type as operators replace multiple single-function units with programmable multi-cook platforms. Electric ovens lead technology adoption in urban installations where gas hookup restrictions and building emissions codes tighten operational parameters. Full-size ovens retain the largest installed base, though countertop formats are gaining share in ghost kitchens and catering services where floor space carries premium lease costs.
The DOE's commercial cooking equipment standards and the EPA's Energy Star certification program shape product development cycles and procurement eligibility for US operators. In Europe, the Ecodesign Directive and REACH compliance requirements govern material selection and end-of-life disposal protocols for oven manufacturers. Stakeholders must monitor how building electrification mandates in California, New York, and Germany reshape the gas-to-electric technology mix across their installed base and new order pipelines.
Market Dynamics
The commercial oven market is compressing around electrification mandates that force operators to retire gas-fired infrastructure ahead of natural replacement cycles. Building codes in California and New York now prohibit new gas connections, accelerating capital redeployment toward electric and infrared platforms.
Growth Catalysts
- DOE Commercial Cooking Equipment Standards:Energy efficiency mandates in the United States disqualify legacy convection models from federal procurement programs, forcing institutional buyers toward certified electric and combi-oven platforms.
- Ghost kitchen proliferation:Delivery-only foodservice operators in urban clusters favor compact countertop ovens that minimize lease footprint and ventilation requirements.
- German bakery automation:Mid-sized hotel chains across Germany are replacing static rack ovens with programmable combi-systems to reduce skilled labor dependency during overnight production.
Market Restraints
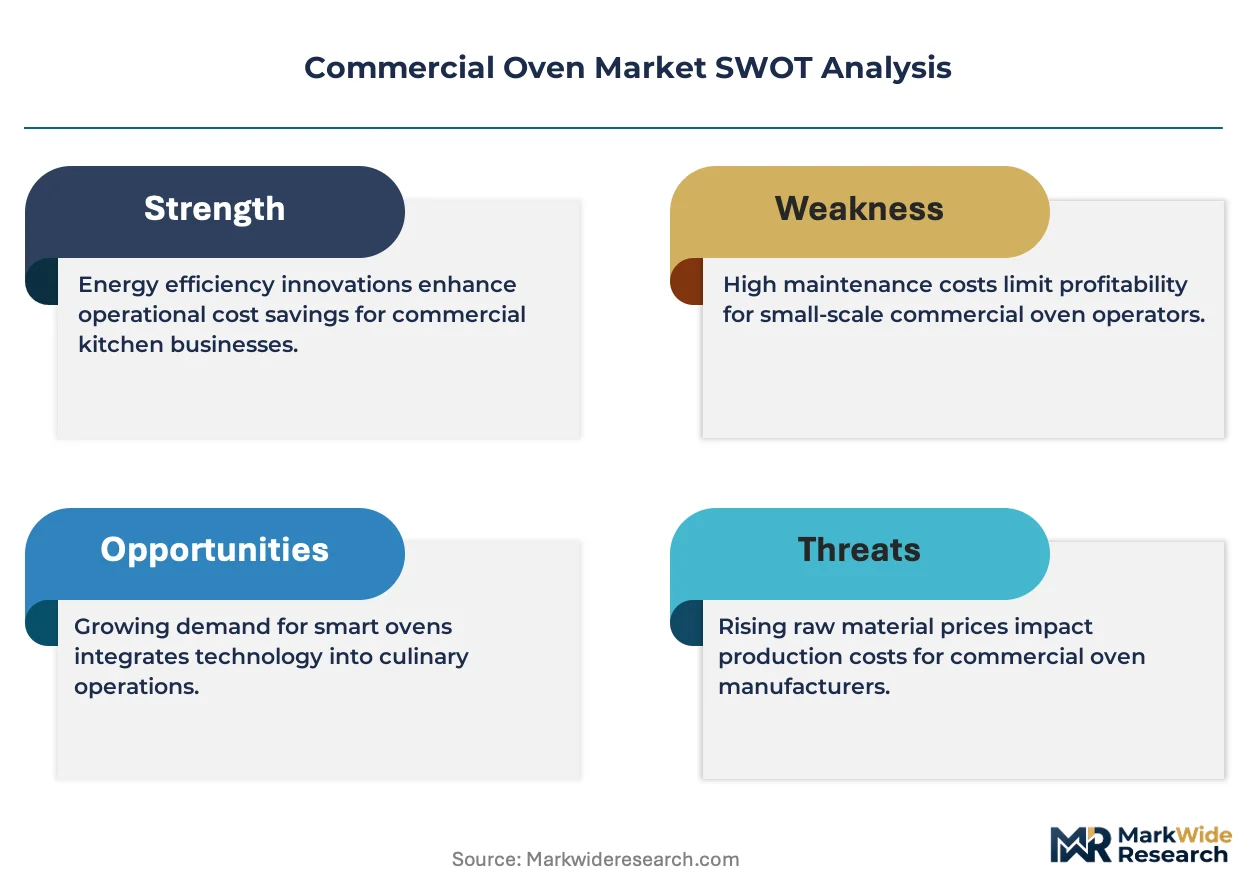
- Stainless steel input volatility:Grade 304 and 316 sheet prices fluctuate with nickel and chromium futures, compressing margin visibility for manufacturers with fixed-price contracts.
- Control system supplier concentration:Proprietary cooking intelligence platforms source embedded processors from a narrow base of semiconductor foundries, creating vulnerability to allocation constraints.
- Gas-to-electric infrastructure gap:Older buildings in Northeast US cities lack three-phase electrical capacity, forcing costly panel upgrades that delay equipment replacement timelines.
Strategic Opportunities
- India institutional catering:Central kitchen contracts for railway stations, airports, and hospital networks remain underpenetrated by programmable combi-technology, creating first-mover whitespace.
- California building electrification mandate:Senate Bill 30 and local reach codes in San Francisco and Los Angeles prohibit new gas hookups, generating guaranteed demand conversion for electric oven suppliers.
- Cloud-connected predictive maintenance:IoT-enabled ovens that monitor heating element degradation and door seal integrity are unifying equipment sales with recurring software revenue streams.
Industry Challenges
- Combustion technician shortage:Gas-to-electric transitions eliminate traditional HVAC-refrigeration skill sets while demand for certified electricians outstrips vocational program output in major metro areas.
- Energy Star certification timelines:EPA testing protocols for commercial ovens require 90-120 day validation cycles that delay product launches and compress selling seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Oven Market |
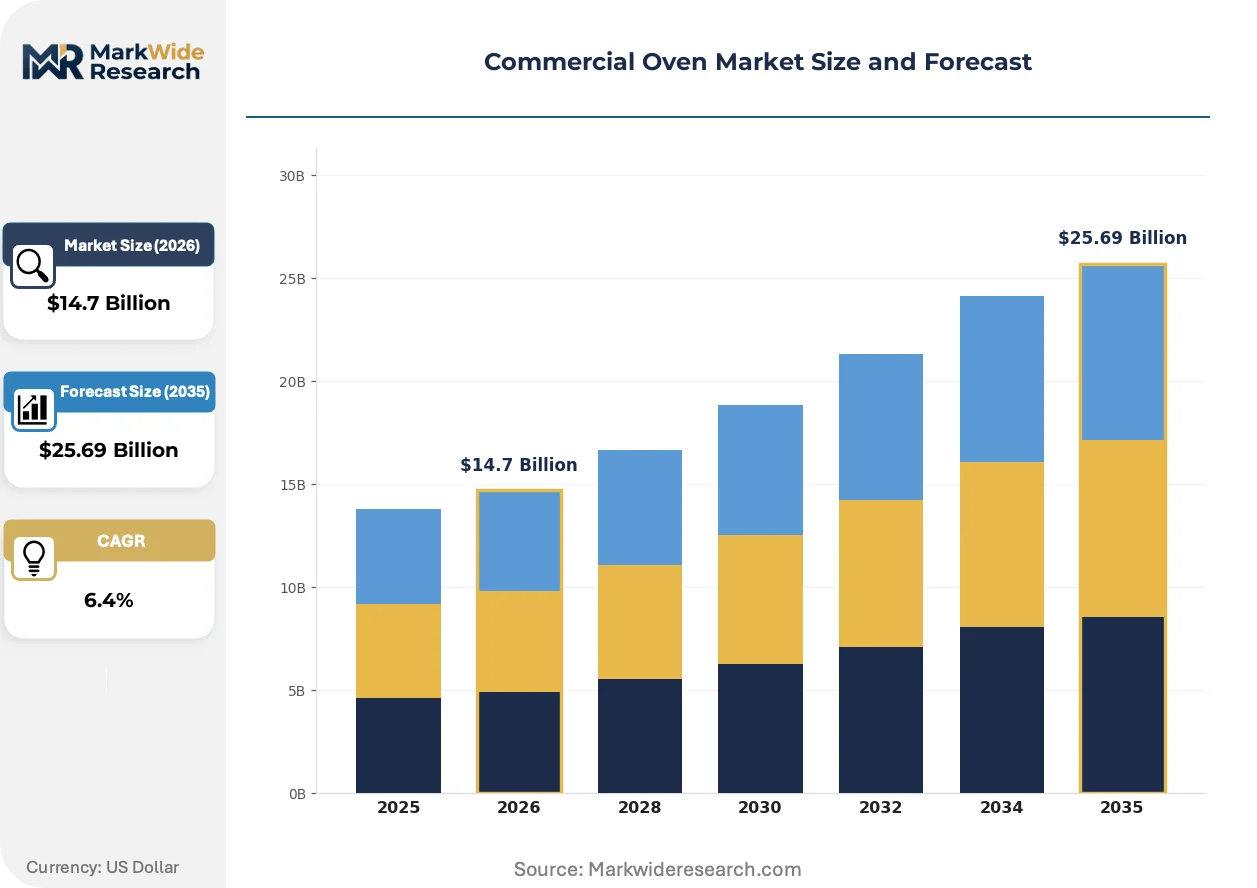
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $25.69 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Ovens, Pizza Ovens, Deck Ovens, Combi Ovens End User: Restaurants, Bakeries, Catering Services, Hotels Technology: Electric Ovens, Gas Ovens, Infrared Ovens, Induction Ovens Size: Countertop Ovens, Full-Size Ovens, Compact Ovens, Double-Stack Ovens |
| Companies Covered | Rational AG, Electrolux Professional, Middleby Corporation, Alto-Shaam Inc., UNOX SpA, Welbilt, Vulcan, Blodgett, TurboChef, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Oven Market Emerging Trajectories
Equipment intelligence and thermal platform convergence are redefining how operators configure kitchen footprints. The category is moving from single-function boxes toward programmable cooking environments.
Combi-steam technology is unifying convection, steam, and probe-controlled roasting within single cavities. Quick-service chains with standardized menu portfolios are adopting these platforms to replace separate convection and holding cabinets. This consolidation is compressing kitchen equipment counts by 30-40% in new buildouts while raising per-unit procurement thresholds.
REACH compliance requirements in Europe are restricting hexavalent chromium in surface coatings and certain flame-retardant compounds in control housings. Manufacturers with Italian and Swedish production footprints are reformulating material specifications to maintain CE marking eligibility. The Ecodesign Directive's ecodesign requirements for professional cooking equipment are accelerating modular component architectures that simplify end-of-life disassembly.
Foodservice procurement is fragmenting across equipment-as-a-service models that bundle installation, maintenance, and software updates into per-hour usage fees. Multi-unit operators with volatile throughput are favoring these arrangements over capital purchases. This shift is most visible in United Kingdom pub chains and United States airport concession portfolios where lease terms create disincentives for owned-asset balance sheets.
Commercial Oven Market Segmentation
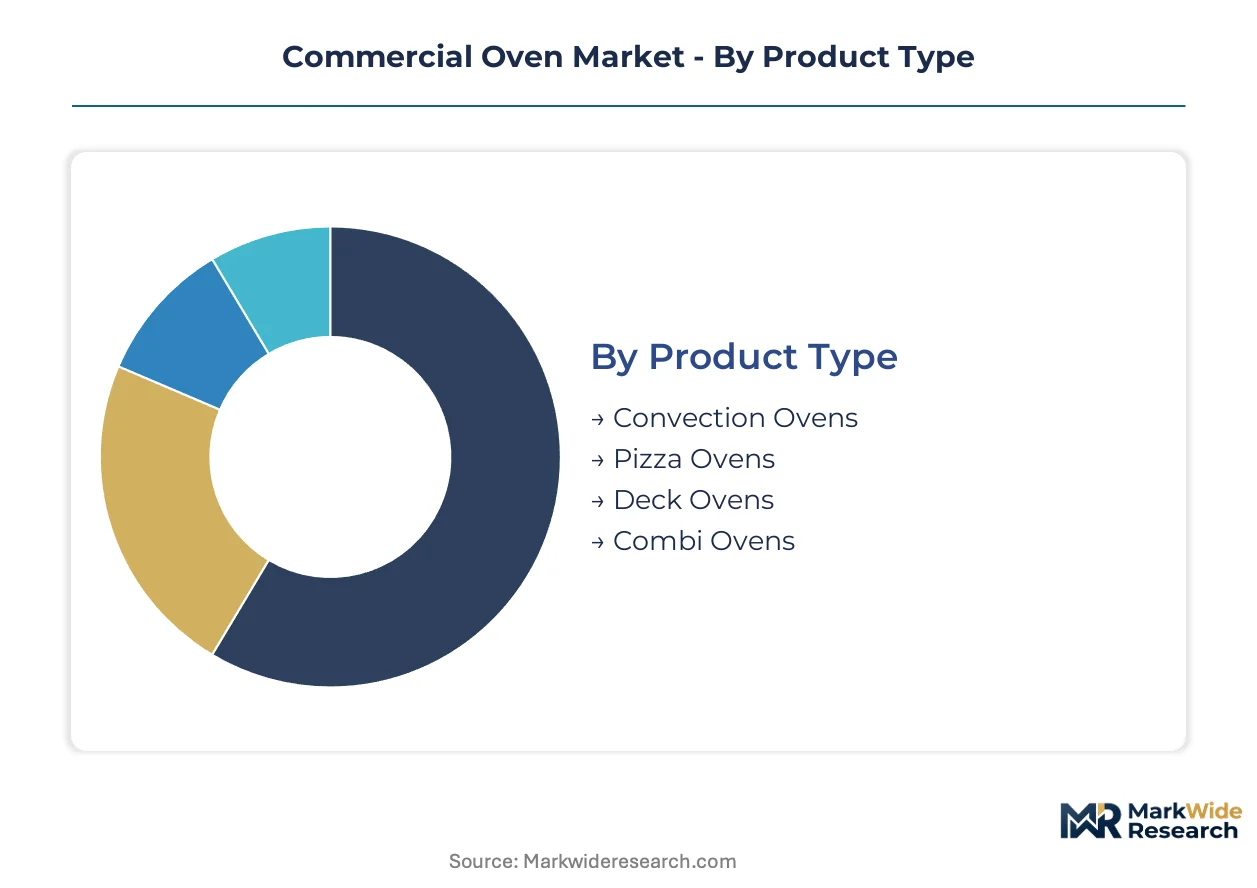
Equipment replacement cycles in commercial foodservice diverge sharply across operator types and facility constraints. Segmentation reveals where capital redeploys toward programmable platforms versus where legacy convection units retain residual demand.
Product Type:
Upgrade timelines stretch from immediate replacement in high-volume chains to deferred refresh in independent operations.
- Convection Ovens:Forced-air circulation chambers dominate institutional kitchens with standardized roasting and baking loads. Quick-service chains in the United States are extending replacement cycles as labor costs rise, deferring capital outlays unless DOE efficiency mandates disqualify existing units from procurement eligibility.
- Combi Ovens:Programmable steam-convection platforms consolidate multiple cooking modes within single cavities. Mid-sized hotel chains across Germany are replacing static rack ovens with these systems to reduce overnight skilled labor dependency in bakery production.
- Pizza Ovens:High-temperature radiant or deck-based units optimized for 450°F+ stone or steel surface cooking. Independent pizzerias in Italy retain traditional wood-fired installations despite electrification pressures.
- Deck Ovens:Static hearth chambers with independent temperature zones for artisan bread and pastry production. European craft bakeries favor these for crust development unobtainable in forced-air systems.
Volume placements concentrate in convection ovens; the faster expansion belongs to combi ovens.
End User:
Cost tier stratification separates premium specification buyers from price-sensitive volume purchasers.
- Restaurants:Full-service and limited-service operators with diverse menu portfolios requiring flexible thermal platforms. Ghost kitchen proliferation in United States urban clusters is compressing equipment footprints toward countertop formats.
- Hotels:Multi-outlet properties with banquet, room service, and restaurant production under single rooflines. German mid-market chains are driving combi-oven penetration above regional averages through centralized procurement.
- Bakeries:Dedicated production facilities with high-throughput, repetitive thermal cycles. Automation investments in Germany are displacing manual rack oven operations.
- Catering Services:Mobile and commissary-based operators with intermittent, high-volume production peaks. United Kingdom pub chains are adopting equipment-as-a-service models to avoid owned-asset balance sheets.
Procurement scale concentrates in restaurant chains; margin expansion tracks hotel property upgrades.
Technology:
Application constraints dictate thermal source selection, with building infrastructure and emissions codes overriding pure performance considerations.
- Electric Ovens:Resistance-element or infrared-radiant heating with zero on-site combustion. California and New York building codes now prohibit new gas connections, guaranteeing demand conversion for electric suppliers in these markets.
- Gas Ovens:Natural gas or propane combustion with higher Btu output per dollar of energy input. Older buildings in Northeast United States cities lack three-phase electrical capacity, forcing costly panel upgrades that delay replacement timelines.
- Infrared Ovens:High-intensity radiant heat transfer for rapid surface browning and moisture retention. Quick-service chains with standardized proteins are adopting these for speed-of-service advantages.
- Induction Ovens:Electromagnetic field heating with precise temperature control and minimal thermal mass. Ghost kitchens favor these where ventilation capacity constraints limit combustion-based options.
New installation permits concentrate in electric ovens; the steepest expansion trajectory belongs to infrared platforms in high-throughput chains.
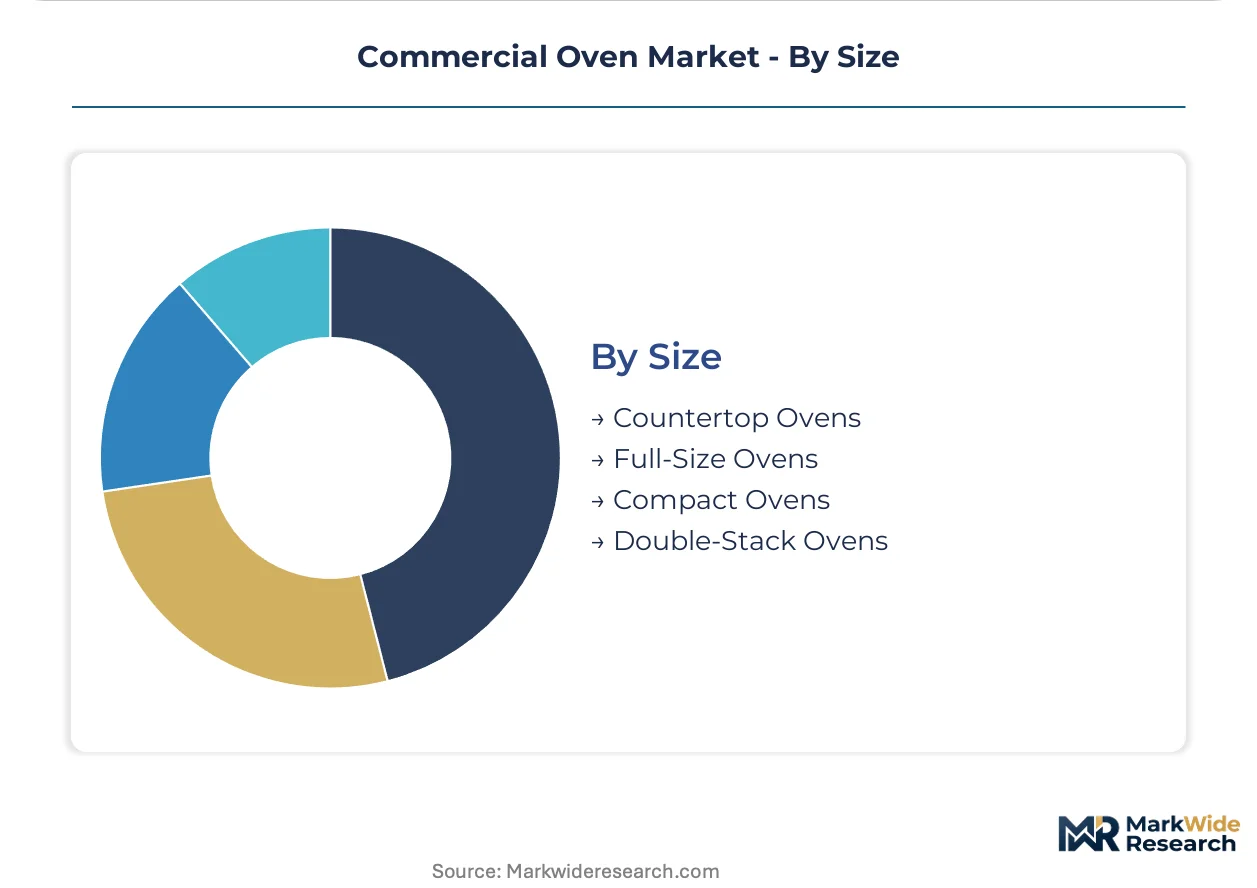
Size:
Customer type and facility maturity determine footprint allocation, with lease structures driving format selection.
- Full-Size Ovens:Floor-standing chambers with 10+ pan capacity for centralized production. Retain the largest installed base in traditional institutional kitchens with dedicated equipment rooms.
- Countertop Ovens:Ventless or reduced-ventilation units under 24 inches in height. Delivery-only operators in United States urban clusters favor these where floor space carries premium lease costs.
- Compact Ovens:Reduced-capacity floor units for secondary production lines or limited-menu concepts. Airport concession portfolios favor these for flexibility across rotating tenant mixes.
- Double-Stack Ovens:Vertically paired cavities maximizing output per square foot of kitchen footprint. High-volume bakery commissaries deploy these for throughput density.
Installed base concentrates in full-size ovens; share gains flow to countertop formats in urban delivery-only operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago's commercial kitchen equipment corridor concentrates North American procurement decision-making for chain restaurant headquarters and foodservice distributors. The metropolitan area anchors specification authority for nationwide rollout programs across quick-service and fast-casual formats.
United States
Quick-service chains headquartered in Atlanta and Dallas are extending replacement cycles as labor costs compress capital budgets. The EPA's Energy Star certification program disqualifies legacy convection models from federal procurement eligibility. California's Senate Bill 30 and New York City's Local Law 154 prohibit new gas connections, accelerating electric oven deployment in San Francisco and Los Angeles buildouts.
Germany
Mid-sized hotel chains across Bavaria and North Rhine-Westphalia are replacing static rack ovens with programmable combi-systems to reduce overnight skilled labor dependency. The Ecodesign Directive governs material selection and end-of-life disposal protocols for oven manufacturers. Stuttgart's industrial automation cluster is driving bakery equipment modernization through centralized procurement consortia.
Italy
Craft bakeries in Emilia-Romagna and Lombardy retain traditional deck ovens for crust development unobtainable in forced-air systems. REACH compliance requirements restrict hexavalent chromium in surface coatings and certain flame-retardant compounds in control housings. Milan's equipment manufacturing district is reformulating material specifications to maintain CE marking eligibility for export markets.
United Kingdom
Pub chains and airport concession portfolios are adopting equipment-as-a-service models to avoid owned-asset balance sheets amid volatile throughput. The country's national environmental regulator enforces emissions standards for commercial cooking equipment in urban centers. London's ghost kitchen clusters favor countertop formats where floor space carries premium lease costs and ventilation capacity is constrained.
India
Central kitchen contracts for railway stations, airports, and hospital networks remain underpenetrated by programmable combi-technology, creating first-mover whitespace for equipment suppliers. The Bureau of Indian Standards sets safety and performance benchmarks for commercial cooking appliances. Mumbai's institutional catering infrastructure is consolidating procurement authority for large-scale foodservice operations.
Commercial Oven Market Vendor Landscape
Premium-margin players sit above commodity-margin players across cooking intelligence platform differentiation and aftermarket service attach rates. The market structures around three tiers: captive technology owners with proprietary control systems, multi-brand portfolio operators with specialized sub-brands, and regional fabricators with price-competitive standard units. Two strategic archetypes dominate: integrated platform developers seeking recurring software revenue and scale manufacturers optimizing production cost curves. Consolidation is accelerating through brand portfolio assembly and geographic distribution network acquisition.
Within the integrated platform tier, Rational AG exemplifies captive technology ownership through its cooking intelligence ecosystem. Middleby Corporation occupies a position across multiple price tiers through its portfolio assembly strategy incorporating TurboChef and Blodgett. Electrolux Professional anchors European institutional demand with manufacturing scale concentrated in Italy and Sweden.
| Leading Market Players |
|---|
| Rational AG |
| Electrolux Professional |
| Middleby Corporation |
| Alto-Shaam Inc. |
| UNOX SpA |
| Welbilt |
| Vulcan |
| Blodgett |
| TurboChef |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of cooking intelligence platforms anchors Rational AG's premium pricing power while forcing competitors toward outsourced semiconductor sourcing that compresses margin visibility. This integration choice separates proprietary control system owners from portfolio assemblers dependent on external processor allocation.
Pricing Analysis
Throughput-linked value metrics anchor combi-oven pricing, with operators paying premiums for yield consistency and labor substitution rather than thermal capacity alone. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked programmable systems from basic convection units and unbranded fabricator imports. Pricing pressure stems from nickel and chromium futures volatility in Grade 304 and 316 stainless steel sheet. Independent pizzerias and small caterers exhibit highest price sensitivity; hotel procurement consortia and QSR chains absorb premiums for certified efficiency compliance.
Supply Chain Analysis
Italy's Ecodesign Directive local-content requirements and India's phased manufacturing program are reshaping component sourcing toward domestic assembly footprints. Manufacturing concentrates in Italy, Sweden, and Germany for European institutional demand, with China and Mexico serving price-competitive export tiers. Supply chains draw from semiconductor foundries in Taiwan, stainless steel mills in Indonesia, and control system firmware development in Germany. Single-source vulnerability in embedded processor allocation creates allocation risk during foundry capacity constraints. Distribution runs through foodservice equipment dealers and direct OEM sales forces to chain headquarters procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cooking intelligence platform differentiation, with DOE efficiency mandates and gas-to-electric infrastructure gaps forcing undifferentiated convection manufacturers toward exit or acquisition.
For Market Incumbents: Hedge semiconductor allocation exposure through dual-sourcing agreements with Taiwanese and South Korean foundries while capturing recurring software revenue via cloud-connected predictive maintenance subscriptions. Defend position by deepening captive control of heating algorithm IP rather than competing on stainless steel fabrication cost. For New Entrants and Emerging Players: Begin with India's central kitchen contracts for railway and airport catering, where programmable combi-technology remains underpenetrated and procurement authority is consolidating. Target ghost kitchen operators in California and New York with ventless countertop electric formats that bypass gas infrastructure constraints entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-technology acquisitions by multi-brand portfolio operators seeking cooking intelligence capabilities. Five-to-ten year viability favors integrated developers with recurring software attach rates over commodity fabricators exposed to input volatility. Watch California's building electrification mandate enforcement velocity as inflection signal for electric oven demand conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cooking Intelligence Platform Development | Captive algorithm IP locks in replacement parts and software subscription revenue at Rational AG. |
| Dual-Source Semiconductor Procurement | Foundry diversification insulates production schedules from Taiwan allocation constraints. |
| California Market Electrification Pivot | SB 30 compliance guarantees demand conversion for electric oven suppliers in Los Angeles buildouts. |
| Equipment-as-a-Service Model Launch | United Kingdom pub chains adopt usage-based fees to avoid owned-asset balance sheet exposure. |
| India Central Kitchen Penetration | Mumbai's railway catering consolidation creates first-mover whitespace for programmable combi-systems. |
Methodological Framework
Independent corroboration across foodservice equipment distributor interviews, DOE regulatory filings, and stainless steel futures market data underwrites the qualitative findings. Primary fieldwork engaged chain restaurant procurement directors, commercial kitchen design consultants, bakery equipment maintenance heads, and ghost kitchen facility operators across the United States, Germany, and India. Secondary validation drew from EPA Energy Star certification databases, ECHA REACH compliance registries, Bureau of Indian Standards safety benchmarks, and SEC 10-K disclosures from publicly traded equipment manufacturers. Bottom-up unit economics triangulated against top-down market sizing from trade association shipment data.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects and technology substitution dynamics. Segmentation modeling incorporated product type, end-user archetype, thermal source technology, and facility size format. CAGRs derived from equipment replacement cycle analysis, building code adoption curves, and chain restaurant expansion pipelines. Forecast inputs included DOE efficiency standard phase-in schedules, nickel futures price trajectory assumptions, and three-phase electrical infrastructure upgrade timelines in Northeast US cities.
Regulatory enforcement delays, semiconductor foundry allocation shocks, and stainless steel input cost spikes are the dominant revision risks to installed base and new order projections. Forecasts reflect documented assumptions on mandate adoption velocity and replacement cycle compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Global Food Blenders and Mixers Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Sword Feeders Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Chewing Gum Machine Market