
 Global Commercial Refrigeration Market | 2026-2036
Global Commercial Refrigeration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Refrigeration Market Analysis
Supermarket chains are expanding their fresh and frozen footprints, so end-user demand is rebalancing toward larger-format retail refrigeration systems. Carrier Global Corporation leverages its scale in integrated cold-chain solutions across North American grocery networks. Daikin Industries Ltd. anchors its position through compressor technology leadership and regional manufacturing depth. Danfoss A/S specializes in electronic controls and energy-efficient components that reduce operational costs for fleet operators.
Commercial refrigeration encompasses engineered systems that maintain controlled temperature environments for perishable goods, typically operating between -40°C and 15°C using vapor compression cycles with synthetic or natural refrigerants. These systems preserve food safety, extend shelf life, and enable compliant pharmaceutical storage across institutional and retail settings. Display cases now generate the strongest margin pools as retailers prioritize merchandising visibility alongside energy metrics. Vapor compression technology still dominates installed base volumes, though magnetic refrigeration is attracting R&D capital for ultra-low-temperature pharmaceutical applications. Absorption systems compete in specific hospitality niches where waste heat recovery improves total cost of ownership.
The EPA in the United States enforces phasedown schedules for hydrofluorocarbon refrigerants under AIM Act mandates, forcing equipment redesigns and service retrofits. EMA and national regulators across Europe enforce CE-marked MDR compliance for pharmaceutical cold storage, while REACH governs material safety in insulation and coatings. Stakeholders must monitor refrigerant transition timelines and certify supply chain readiness before regulatory deadlines lock in equipment procurement decisions.
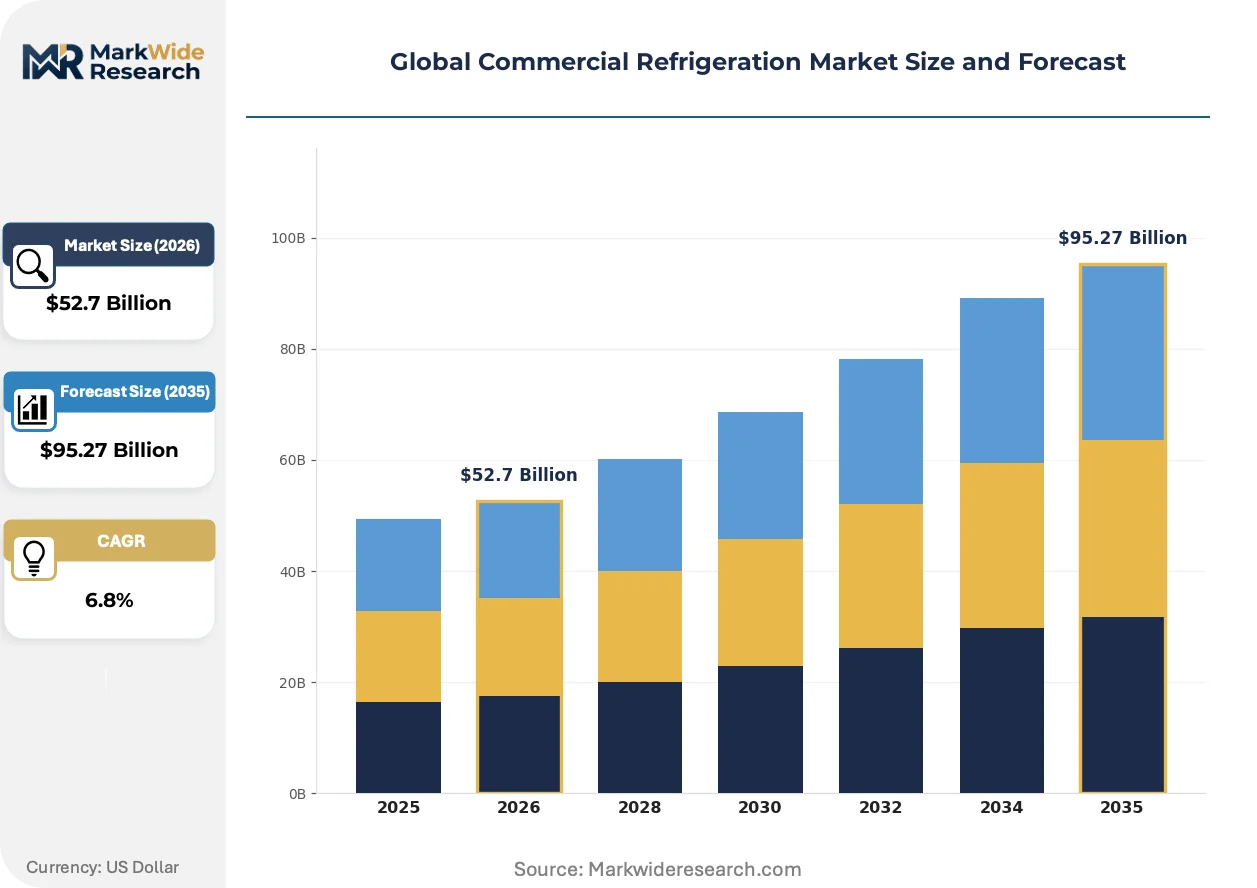
Market Dynamics
The EU F-Gas Regulation is compressing equipment replacement cycles and forcing refrigerant chemistry transitions across installed bases. This single mandate cascades through engineering specifications, service training requirements, and capital allocation decisions.
Growth Catalysts
- Natural refrigerant mandates:The EU F-Gas Regulation accelerates CO₂ and ammonia system deployments in supermarket chains. Equipment manufacturers report order backlogs for transcritical CO₂ racks.
- Urban retail modernization:Southeast Asian cities are expanding cold-chain coverage to reduce post-harvest losses. Modern format grocery penetration drives walk-in cooler and display case procurement.
- Pharmaceutical cold storage expansion:EMA MDR compliance requirements for temperature-controlled drug distribution create dedicated freezer and refrigerator demand at 3PL facilities.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and coil manufacturers face margin compression when base metal prices spike. Long equipment production cycles prevent real-time price pass-through.
- Compressor supply concentration:High-efficiency scroll and screw compressor production clusters in specific manufacturing regions. Equipment OEMs report 12-16 week lead times during peak seasons.
- Technician certification gaps:Natural refrigerant systems require specialized handling protocols. The installed service workforce lacks sufficient CO₂ and ammonia certification density.
Strategic Opportunities
- India cold-chain infrastructure:The country's PLI scheme for food processing incentivizes integrated refrigeration investments. Cold storage capacity per capita remains a fraction of developed market levels.
- Predictive maintenance convergence:IoT sensor networks and machine learning algorithms enable remote compressor monitoring. Fleet operators reduce unplanned downtime through condition-based service scheduling.
- Direct-to-installer distribution:Digital platforms bypass traditional wholesaler layers. Contractors in fragmented construction markets gain price transparency and faster parts availability.
Industry Challenges
- Refrigerant inventory stranding:Service contractors hold legacy HFC stocks that depreciate as phasedown deadlines approach. Working capital gets trapped in obsolete cylinders.
- Legacy control system integration:New electronic expansion valves and variable-speed drives must communicate with 15-20 year old building management protocols. Retrofit commissioning extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Refrigeration Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Freezers, Ice Makers, Display Cases End User: Food Service, Retail, Hospitality, Supermarkets Technology: Vapor Compression, Absorption, Thermoelectric, Magnetic Refrigeration Application: Food Preservation, Beverage Cooling, Pharmaceutical Storage, Floral Preservation |
| Companies Covered | Carrier Global Corporation, Daikin Industries Ltd., Danfoss A/S, Johnson Controls, Ali Group S.r.l., GEA Group Aktiengesellschaft, AB Electrolux, Dover Corporation, Emerson Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Refrigeration Market Emerging Trajectories
Refrigeration engineering is pivoting from centralized plant architectures toward distributed system designs. This structural shift alters how capacity gets sized, where equipment gets located, and who maintains it.
Modular refrigeration units with embedded microchannel heat exchangers and variable-capacity compressors are decentralizing cooling distribution in large-format retail. Supermarket operators deploy these self-contained cases to eliminate long refrigerant piping runs. The technology compresses installation timelines and reduces leak-prone joints.
The EPA's phasedown schedule under AIM Act mandates forces HFC refrigerant quota reductions on an accelerating timeline. Equipment manufacturers redesign product lines for A2L and natural refrigerant compatibility. North American grocery chains front-load procurement to secure grandfathered service access.
Service unbundling from equipment purchase contracts is fragmenting vendor-customer relationships. Independent service contractors capture maintenance revenue that OEMs previously controlled. This shift concentrates most visibly in North American commercial foodservice installations where multi-brand fleets complicate single-source agreements.
Global Commercial Refrigeration Market Segmentation
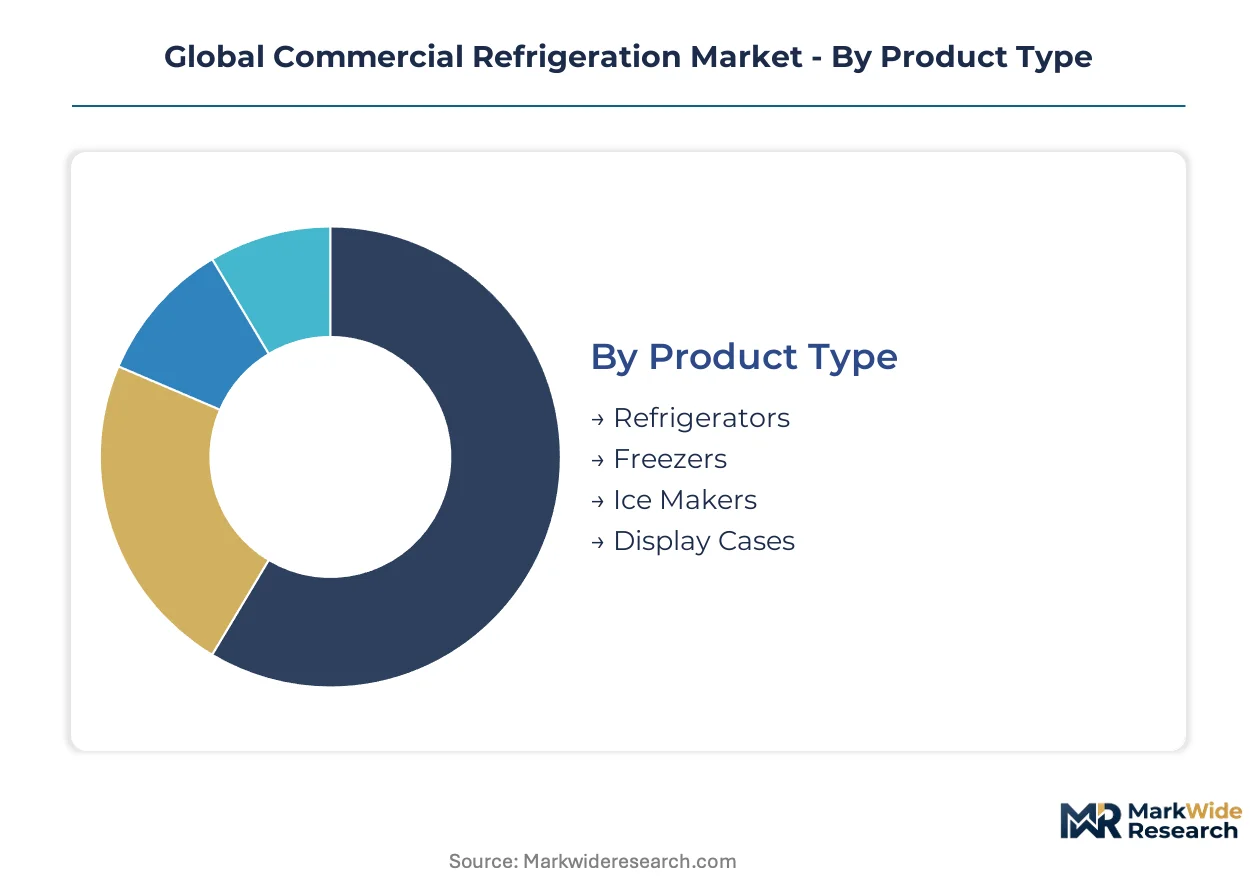
Commercial refrigeration equipment varies dramatically in capital requirements, operating complexity, and regulatory exposure across product configurations. Segmentation reveals where procurement budgets concentrate and which technology transitions will reshape vendor order books.
Product Type:
Display cases demand the highest upfront investment per linear foot due to integrated lighting, glass engineering, and merchandising controls. Freezers and refrigerators require substantial compressor and insulation capital. Ice makers and specialized units occupy lower capital tiers with faster replacement cycles.
- Refrigerators:Reach-in and walk-in configurations dominate foodservice back-of-house installations. Demand clusters in US supermarket renovation programs where operators replace aging HFC-based systems ahead of EPA phasedown deadlines.
- Freezers:Ultra-low-temperature cabinets maintain -40°C to -80°C for pharmaceutical and specialty food applications. Cold-chain expansion in Southeast Asian cities drives walk-in freezer procurement as modern format grocery penetration accelerates.
- Ice Makers:Modular and undercounter units serve hospitality and foodservice segments with high turnover requirements.
- Display Cases:Vertical and horizontal merchandisers integrate LED lighting and anti-fog glass for retail visibility.
Display cases absorb the bulk of installed capacity; freezers are expanding most quickly.
End User:
Supermarket chains command the largest average order values with integrated rack systems and centralized controls. Food service and hospitality operate fragmented fleets with higher service intensity. Retail spans convenience stores through big-box formats with divergent energy profiles.
- Food Service:Restaurants, cafeterias, and catering operations deploy reach-in units and prep tables with rapid door-cycle durability. US commercial kitchen renovation rates drive replacement demand as operators seek ENERGY STAR certification for utility rebates.
- Retail:Convenience stores and specialty shops prioritize compact footprint equipment with low ambient adaptability. Urban retail modernization across Indonesian and Vietnamese cities propels display case procurement as cold-chain coverage extends.
- Hospitality:Hotels and event venues require minibars, banquet carts, and back-bar coolers with aesthetic integration.
- Supermarkets:Full-format grocers deploy transcritical CO₂ rack systems and distributed cases across expansive selling floors.
Supermarkets command the dominant share of equipment value; food service shows the steepest expansion trajectory.
Technology:
Vapor compression systems represent the mature installed base with established supply chains and technician networks. Alternative technologies compete on niche applications where energy source or temperature precision creates advantage.
- Vapor Compression:Reciprocating, scroll, and screw compressors using synthetic or natural refrigerants power the vast majority of installed systems. EU F-Gas Regulation mandates are compressing replacement cycles as supermarket chains accelerate CO₂ and ammonia conversions.
- Absorption:Heat-activated systems utilize waste heat or natural gas where electricity costs are prohibitive. Hospitality installations in Germany and France adopt absorption for centralized plant efficiency in large hotel complexes.
- Thermoelectric:Solid-state cooling without moving parts serves portable and low-capacity applications.
- Magnetic Refrigeration:Magnetocaloric effect technology eliminates refrigerant fluids entirely. Pharmaceutical cold storage R&D in Switzerland and Japan targets ultra-low-temperature precision without environmental compliance burdens.
Vapor compression retains the overwhelming installed base; magnetic refrigeration is climbing the fastest among emerging alternatives.
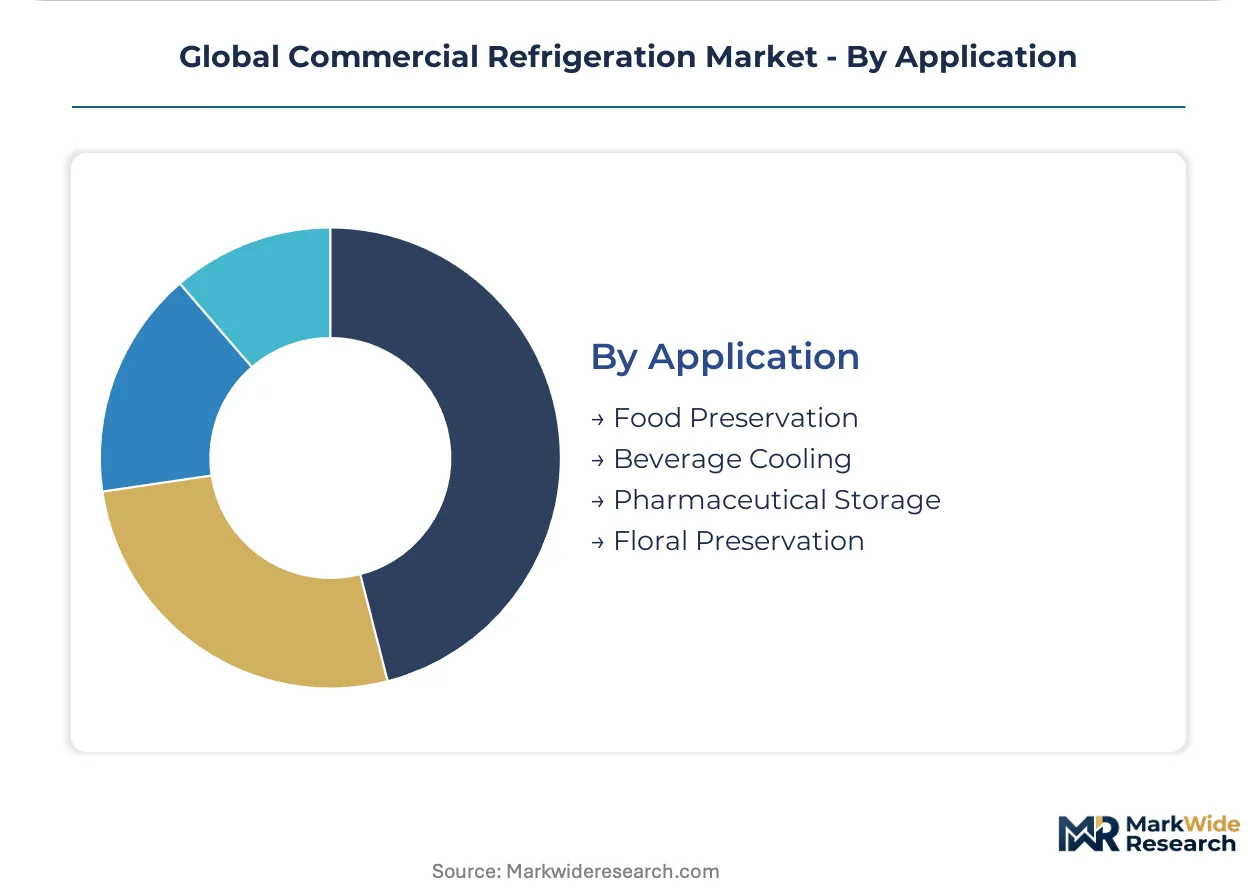
Application:
Food preservation drives volume through perishables handling across retail and foodservice. Pharmaceutical storage commands premium pricing with regulatory compliance requirements. Beverage cooling and floral preservation occupy specialized niches with distinct temperature band specifications.
- Food Preservation:Temperature control from -18°C to 4°C maintains safety and quality across meat, dairy, and produce categories. Southeast Asian government cold-chain infrastructure investments target post-harvest loss reduction as urbanization intensifies.
- Beverage Cooling:Reach-in merchandisers and draft systems optimize for rapid pull-down and consistent serving temperatures. US convenience store chains deploy high-capacity beverage coolers with glass door efficiency standards.
- Pharmaceutical Storage:Validated cold rooms and medical-grade refrigerators maintain 2°C to 8°C for vaccines and biologics. EMA MDR compliance requirements across Germany, France, and Italy compel 3PL facility upgrades with redundant monitoring systems.
- Floral Preservation:Humidity-controlled coolers extend cut flower viability in wholesale and retail settings.
Food preservation dominates absolute equipment deployment; pharmaceutical storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in Germany, Japan, and the United States, while consumption growth tilts toward Southeast Asian markets modernizing retail cold-chain infrastructure. This divergence shapes capital flows and equipment specification standards across regions.
United States
Supermarket renovation cycles and foodservice back-of-house upgrades drive equipment procurement. The EPA enforces AIM Act phasedown schedules for hydrofluorocarbon refrigerants, compelling HFC-to-natural refrigerant conversions. Cold-chain infrastructure investment clusters in California and Texas as grocery chains expand distribution footprints.
Germany
Transcritical CO₂ rack system adoption accelerates across discount grocery networks seeking F-Gas Regulation compliance. EMA MDR pharmaceutical storage mandates create demand for validated cold rooms at 3PL facilities. Industrial refrigeration engineering concentrates in Bavaria and Baden-Württemberg.
China
Urban supermarket format expansion and cold storage capacity buildouts absorb display cases and walk-in units. The Ministry of Ecology and Environment advances dual carbon goals through energy efficiency standards. Manufacturing scale centers on the Yangtze River Delta and Pearl River Delta production corridors.
India
Post-harvest loss reduction programs and modern retail penetration stimulate walk-in cooler demand. The PLI scheme for food processing incentivizes integrated cold-chain investments. Cold storage deployment concentrates in Maharashtra and Gujarat as agricultural processing hubs expand.
Vietnam
Urban grocery modernization and convenience store format growth propel display case procurement. National food safety regulations tighten temperature control requirements across retail and foodservice. Equipment demand clusters in Ho Chi Minh City and Hanoi metropolitan corridors.
Global Commercial Refrigeration Market Vendor Landscape
Top-tier vendors anchor integrated system solutions, while mid-tier specialists concentrate on component supply and regional fabrication. The market exhibits tiered concentration with scale advantages accruing to full-stack cold-chain providers. Strategic archetypes include compressor technology leaders, electronic controls specialists, and integrated rack system fabricators. Competitive moves center on refrigerant transition readiness and predictive maintenance service bundling.
Within the integrated solutions tier, Carrier Global Corporation and Daikin Industries Ltd. occupy positions exemplifying scale-driven cold-chain coverage. Daikin Industries Ltd. anchors Japanese manufacturing depth in compressor technology. Danfoss A/S represents the component-specialist archetype through electronic controls and energy-efficient subsystems. These three entities illustrate how vendor positioning fragments across system-level versus component-level value capture.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Daikin Industries Ltd. |
| Danfoss A/S |
| Johnson Controls |
| Ali Group S.r.l. |
| GEA Group Aktiengesellschaft |
| AB Electrolux |
| Dover Corporation |
| Emerson Electric Company |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up service contractors now dominate North American aftermarket maintenance, concentrating pricing power with consolidated parts distributors while compressing margins for independent technicians facing refrigerant inventory stranding risks.
Pricing Analysis
Margin tightening in standard-grade equipment reflects copper and aluminum input volatility that prevents real-time price pass-through during long production cycles. Project-based contracting dominates supermarket rack installations, while transactional per-unit sales govern foodservice replacement demand. Price differentiation rests on CE-marked certification tiers for pharmaceutical cold storage and ENERGY STAR compliance levels for utility rebate eligibility. Cost-down pressure on mid-tier display cases accelerates as Southeast Asian buyers prioritize footprint efficiency over premium merchandising features. Foodservice operators exhibit highest price sensitivity due to fragmented fleet replacement patterns, whereas supermarket chains absorb premium pricing for integrated CO₂ rack systems to secure regulatory compliance.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for compressor and electronic control components. Manufacturing concentrates in Germany for transcritical CO₂ engineering, Japan for scroll compressor technology, and China for heat exchanger fabrication. Raw material dependencies draw from Chilean copper, Australian aluminum, and specialized steel alloys for pressure vessels. Single-source vulnerability concentrates in high-efficiency screw compressor production clusters. Distribution runs through authorized dealer networks for integrated rack systems and direct-to-installer digital platforms for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
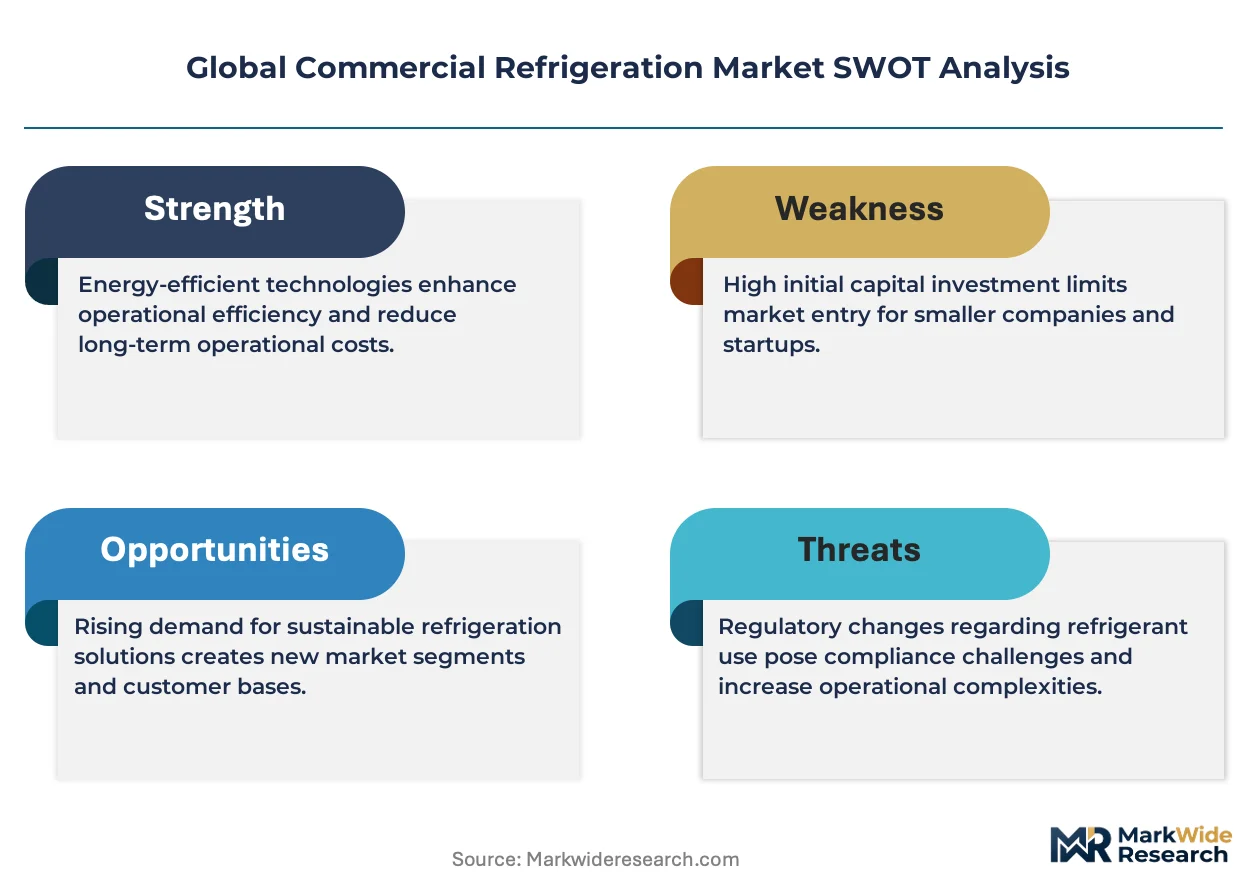
The EU F-Gas Regulation constructs a formidable cost-of-compliance moat: only capitalized incumbents with certified natural refrigerant service networks can bid on supermarket retrofit contracts, excluding undercapitalized regional competitors.
For Market Incumbents: Acquire CO₂-certified technician training facilities to lock in service revenue as HFC phasedown deadlines accelerate. Consolidate aftermarket parts distribution in fragmented Southeast Asian cities where independent contractors lack scale. Carrier Global Corporation and Daikin Industries Ltd. already leverage this playbook; smaller OEMs must match their certification density or surrender integrated rack contracts to compliant rivals. For New Entrants and Emerging Players: Direct-to-installer digital platforms bypass traditional wholesaler markups in India's PLI-subsidized cold-chain buildout. Target walk-in cooler procurement in Maharashtra and Gujarat agricultural hubs where per-capita cold storage capacity trails developed markets by an order of magnitude. White-space exists in predictive maintenance SaaS bundling for fragmented foodservice fleets lacking condition-based monitoring. For Investors and Strategic Acquirers: Order backlog announcements for transcritical CO₂ racks are the leading indicator that refrigerant transition readiness now determines market share trajectories. Five-to-ten year viability favors component specialists with backward integration into electronic controls and variable-speed drives. Watch EPA quota reduction timelines as inflection signals for North American procurement front-loading.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Certification Program | EU F-Gas Regulation mandates compress replacement cycles toward CO₂ and ammonia systems. |
| Predictive Maintenance Platform Launch | IoT sensor networks enable remote compressor monitoring for fleet operators. |
| Backward Integration into Microchannel Heat Exchangers | Captive supply of coil components insulates margins from copper price volatility. |
| Direct-to-Installer Distribution Expansion | Digital platforms bypass wholesaler layers in fragmented construction markets. |
| Pharmaceutical Cold Storage Partnership | EMA MDR compliance requirements compel 3PL facility upgrades with redundant monitoring. |
Methodological Framework
Multi-period observation of refrigerant quota allocations, supermarket renovation cycles, and cold-chain infrastructure investments anchored the trend analysis, supplemented by interviews with equipment OEM procurement directors, supermarket facilities managers, refrigeration service contractors, and pharmaceutical 3PL operators. Secondary validation drew from EPA AIM Act filings, EU F-Gas Regulation implementation reports, customs data on compressor and heat exchanger trade flows, and SEC 10-K disclosures from listed equipment manufacturers. Bottom-up equipment shipment modeling triangulated against top-down cold-chain capacity buildout estimates across the analysis window.
Segment-weighting applied product type, end user, technology, and application dimensions across the modeling period. Vapor compression system volumes, natural refrigerant conversion rates, and display case procurement intensity informed analytical framework inputs. CAGRs derived from equipment replacement cycle compression, regulatory deadline clustering, and urban retail modernization trajectories.
The model holds under steady regulatory enforcement timelines and commodity price bands; deviation in F-Gas Regulation implementation pacing or copper supply disruptions would shift equipment procurement patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Griddle Market