
 Spray Drying Market | 2026-2036
Spray Drying Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Drying Market Outlook
Modular skid-mounted spray drying systems is repositioning capital deployment for mid-sized pharmaceutical and food processors. GEA Group leverages its installed base of pharmaceutical-grade dryers across European FDA-inspected sites. ANDRITZ Group anchors large-scale dairy powder installations through process integration capabilities. SPX FLOW differentiates on sanitary design standards for food and beverage applications.
Spray drying atomizes liquid feedstock into a hot gas stream, producing free-flowing powders with controlled particle sizes typically ranging from 10 to 250 micrometers; the process serves industries requiring moisture reduction, encapsulation, and shelf-life extension. Multi-stage technology leads capital deployment for heat-sensitive pharmaceutical products where thermal degradation risks demand gentler processing profiles. Fluidized bed spray drying occupies the fastest-growing position in nutraceutical encapsulation, driven by functional coating requirements for controlled-release formulations.
FDA cGMP guidelines and EMA quality standards govern equipment qualification and cleaning validation, directly shaping vendor selection criteria for pharmaceutical end users. EPA emissions regulations and OSHA combustible dust standards constrain dryer design, forcing engineering trade-offs between thermal efficiency and containment. Stakeholders must monitor evolving EU Green Deal industrial emissions targets and their translation into equipment retrofit mandates across installed processing capacity.
Market Dynamics
Contract manufacturing agreements now dominate pharmaceutical spray drying deployment, as mid-sized API developers outsource capital-intensive particle engineering to avoid fixed asset burdens. This structural shift toward fee-for-service processing is compressing equipment ownership cycles and reshaping vendor-client relationships across the value chain.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive program for food processing accelerates domestic dairy powder capacity expansion, creating fresh equipment demand for integrated drying lines.
- EMA quality standards:Stringent pharmaceutical-grade validation requirements in Europe drive replacement of legacy batch systems with continuous manufacturing-compatible spray dryers.
- Functional coating convergence:Nutraceutical encapsulation for controlled-release formulations multiplies addressable applications beyond conventional moisture reduction use cases.
Market Restraints
- Energy input volatility:Natural gas and electricity price swings directly impact operating economics for thermal-intensive spray drying operations, squeezing processor margins.
- Solvent recovery mandates:REACH compliance and EU Green Deal industrial emissions targets impose costly retrofit requirements on installed European capacity.
- Atomization technology concentration:Proprietary nozzle designs and rotary atomizer supply concentrate among a limited vendor base, creating procurement bottlenecks for specialized pharmaceutical applications.
Strategic Opportunities
- Modular skid-mounted systems:Pre-engineered, containerized drying units reduce deployment timelines for mid-sized food and pharmaceutical processors seeking flexible capacity.
- Biologics formulation expansion:Heat-sensitive protein and peptide drying applications open high-value segments beyond small-molecule APIs.
- OSHA combustible dust standards:Tightened containment requirements in the United States create aftermarket demand for explosion-protection retrofits and isolated powder handling systems.
Industry Challenges
- Process analytical technology integration:Real-time particle size and moisture monitoring system deployment demands cross-functional automation expertise scarce among traditional dryer operators.
- Cleaning validation protocols:FDA cGMP requirements for equipment qualification between product changeovers extend downtime and complicate multi-product facility scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Drying Market |
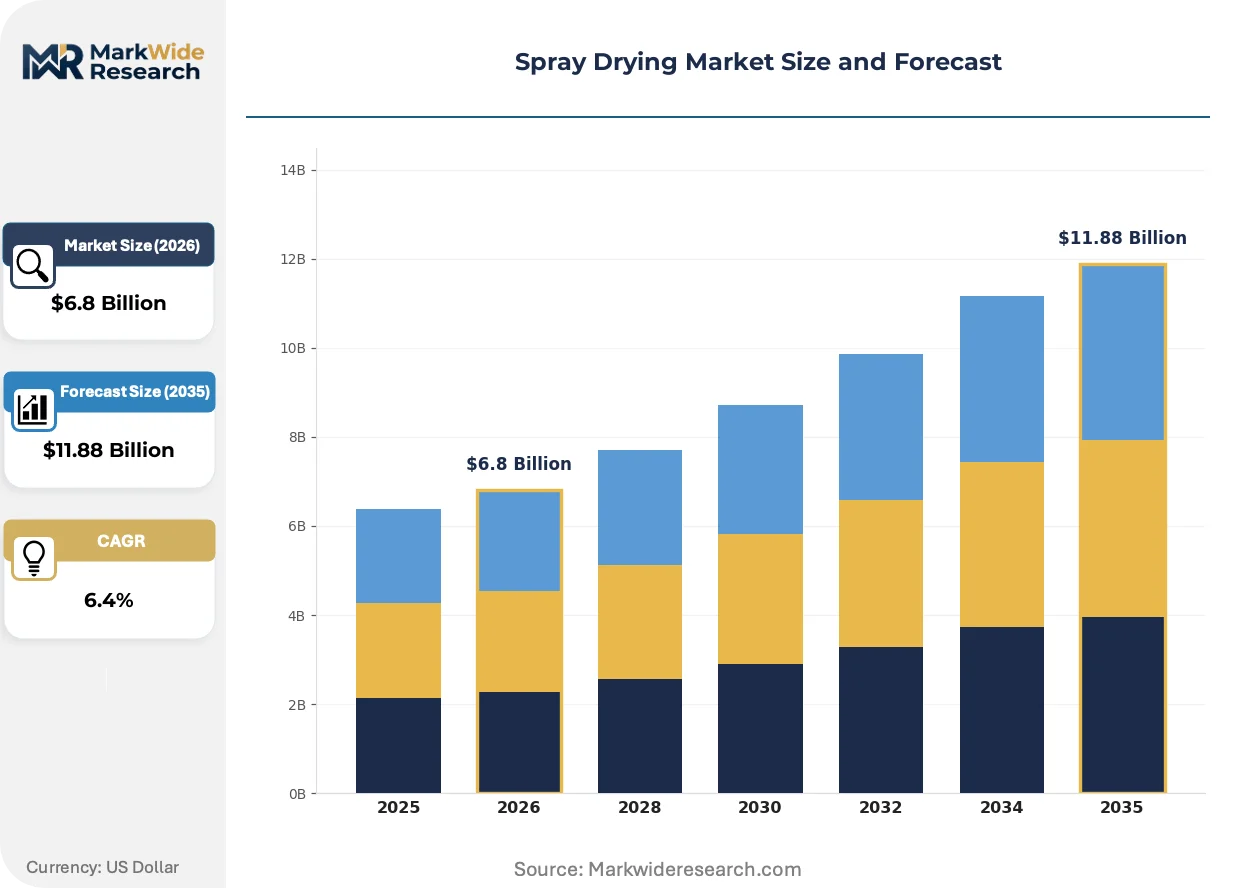
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Ingredients, Pharmaceutical Products, Dairy Powders, Chemical Additives End User: Food & Beverage, Pharmaceuticals, Agriculture, Cosmetics Technology: Single-Stage, Multi-Stage, Fluidized Bed, Spray Dryer Application: Encapsulation, Powdered Beverages, Nutraceuticals, Specialty Chemicals |
| Companies Covered | Yamato Scientific, ANDRITZ Group, GEA Group, Tetra Pak, SiccaDania Group, SPX FLOW, Dedert Corporation, VetterTec, Buchi Labortechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Drying Market Strategic Shifts
Digital process control architectures and closed-loop powder handling systems are redefining operational benchmarks. Equipment vendors now compete on integrated data analytics and containment assurance rather than thermal efficiency alone.
Closed-loop nitrogen spray drying systems are decentralizing pharmaceutical manufacturing geography by enabling high-potency API processing in non-traditional production locations without extensive HVAC infrastructure. Biologics contract manufacturers in Singapore and Ireland are adopting these systems to handle oxygen-sensitive and explosive compounds previously restricted to specialized facilities. The technology is decentralizing the geographic distribution of hazardous formulation work away from established chemical manufacturing clusters.
EU Green Deal industrial emissions targets are mandating solvent recovery rates above 95 percent for new pharmaceutical spray drying installations across member states. Equipment suppliers must now engineer integrated condensation and distillation modules as standard rather than optional configurations. German and Swiss pharmaceutical processors are responding by consolidating drying operations at fewer, larger sites capable of supporting centralized recovery infrastructure.
Equipment-as-a-service contracting is displacing traditional capital purchase arrangements among mid-sized dairy and nutraceutical processors. Monthly fee structures covering maintenance, validation, and throughput guarantees reduce balance sheet pressure for operators facing margin compression. This model is most visible in the Netherlands and Denmark, where cooperative dairy processors prioritize operational flexibility over asset ownership.
Spray Drying Market Segmentation
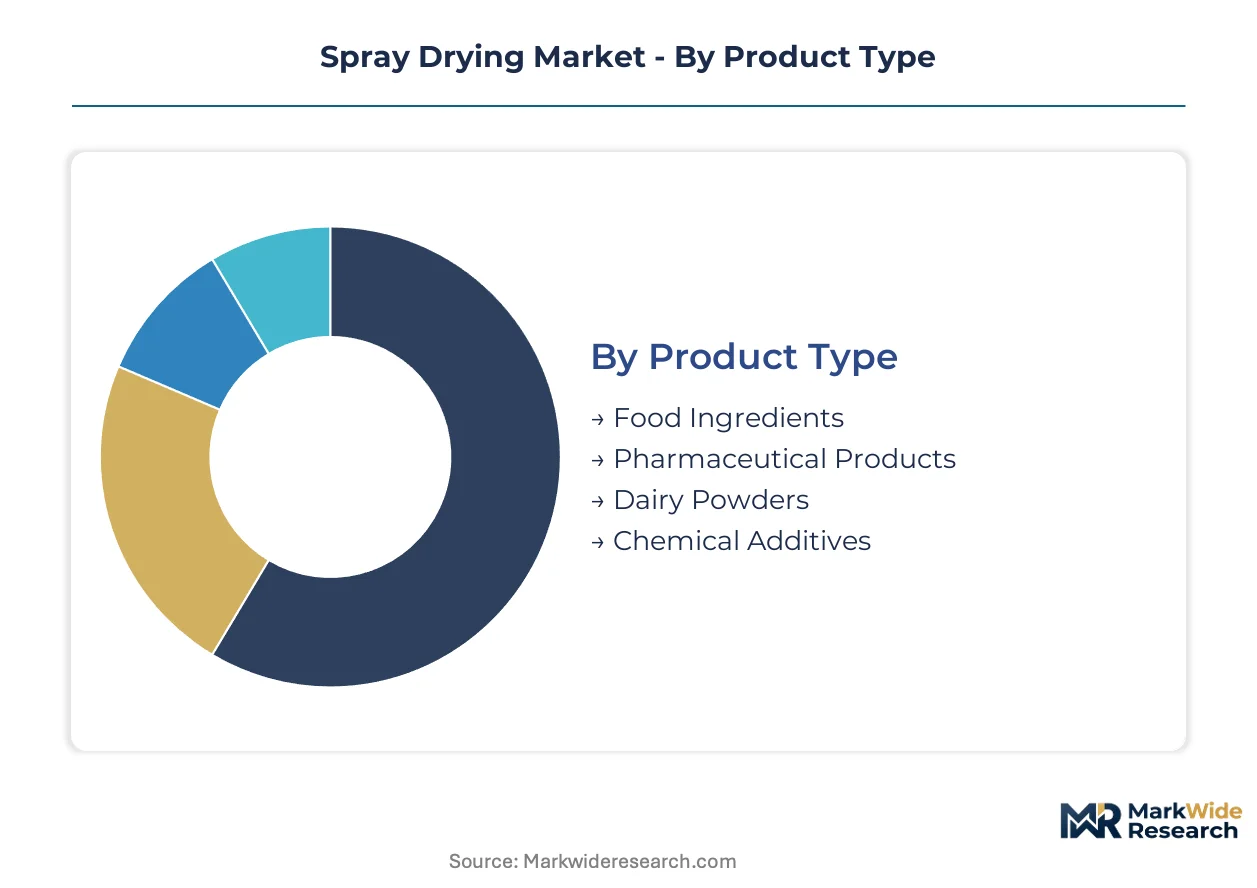
Spray drying equipment configurations diverge sharply across end-use requirements, with pharmaceutical validation protocols and food-grade sanitary standards driving incompatible design specifications. Technology selection determines capital intensity, energy consumption, and particle engineering capabilities. Segmentation clarity enables processors to match thermal profiles and containment levels to specific product critical quality attributes.
Product Type:
Thermal sensitivity and moisture specifications differentiate product categories, with each demanding distinct atomization pressures, inlet temperatures, and residence time controls.
- Pharmaceutical Products:Complex APIs and inhalable formulations require precise particle size distributions between 1-10 micrometers for pulmonary delivery. FDA cGMP validation and EMA quality standards drive demand for continuous manufacturing-compatible systems with integrated process analytical technology.
- Dairy Powders:Milk protein concentrates and infant formula bases prioritize gentle thermal processing to preserve nutritional integrity. India's PLI scheme incentives accelerate domestic capacity expansion for integrated drying lines serving export markets.
- Food Ingredients:Flavor encapsulation and instant coffee production utilize high-temperature single-stage configurations for cost efficiency.
- Chemical Additives:Catalysts and ceramic precursors tolerate aggressive thermal profiles with minimal containment requirements.
Mature deployment sits with Dairy Powders. Newer deployment is concentrated in Pharmaceutical Products.
End User:
Regulatory stringency and batch size economics shape vendor relationships, with contract manufacturing prevalence varying across customer categories.
- Pharmaceuticals:Outsourced particle engineering now dominates as mid-sized API developers avoid fixed asset burdens. Closed-loop nitrogen systems enable high-potency processing in Singapore and Ireland without extensive HVAC infrastructure.
- Food & Beverage:Cooperative dairy processors in the Netherlands and Denmark favor equipment-as-a-service contracting to preserve operational flexibility.
- Cosmetics:Encapsulated active ingredients for controlled-release skincare drive fluidized bed adoption.
- Agriculture:Fertilizer and feed additive applications prioritize throughput over particle uniformity.
Equipment-as-a-service penetration is deepest in Food & Beverage. Capital purchase persistence is strongest in Pharmaceuticals.
Technology:
Stage configuration determines thermal exposure duration and energy recovery potential, with multi-stage systems commanding premium positioning for heat-sensitive applications.
- Multi-Stage:Integrated drying and cooling zones reduce thermal degradation risks for protein and peptide formulations. Biologics contract manufacturers deploy these systems for gentle processing profiles that preserve bioactivity.
- Fluidized Bed:Functional coating capabilities enable controlled-release nutraceutical encapsulation with precise layer deposition. This segment is expanding most quickly as functional food convergence accelerates.
- Single-Stage:Simplicity and lower capital cost serve commodity dairy and chemical applications with forgiving thermal windows.
- Spray Dryer:Conventional configurations persist in legacy installations with limited retrofit incentives.
Process analytical technology integration lags in Single-Stage. Advanced automation concentrates in Multi-Stage.
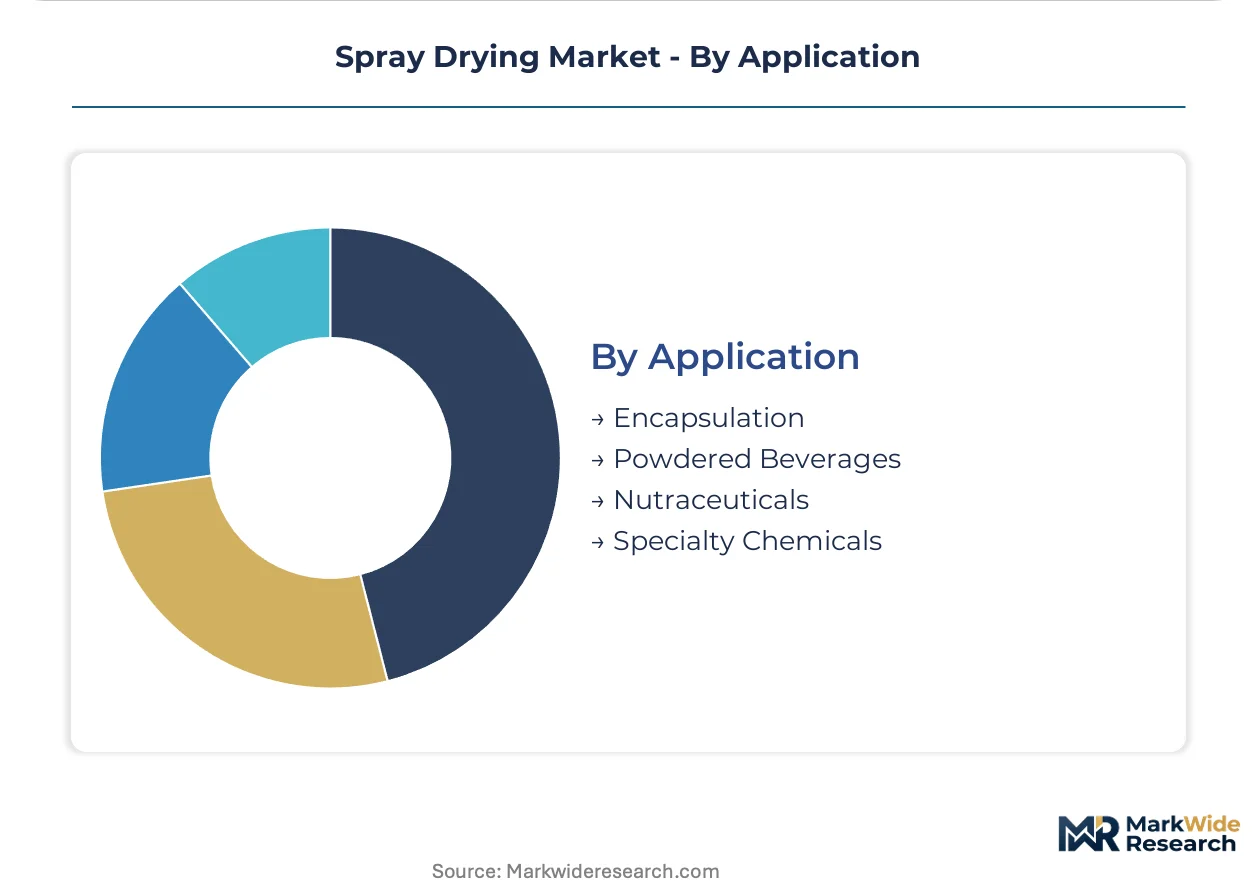
Application:
Functional requirements beyond moisture removal—encapsulation efficiency, release kinetics, and shelf-life extension—now drive technology selection more than drying capacity alone.
- Encapsulation:Lipid and polymer matrix entrapment of vitamins, probiotics, and flavors demands precise atomization control for uniform shell formation. EU Green Deal solvent recovery mandates above 95 percent reshape equipment specifications for pharmaceutical encapsulation lines.
- Nutraceuticals:Controlled-release formulations for dietary supplements require fluidized bed coating integration. OSHA combustible dust standards in the United States create aftermarket demand for explosion-protection retrofits.
- Powdered Beverages:Instant dissolution properties dictate agglomeration strategies and particle morphology.
- Specialty Chemicals:Catalyst supports and battery material precursors prioritize throughput and purity over encapsulation complexity.
Regulatory compliance complexity peaks in Encapsulation. Standardized processing dominates Specialty Chemicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production clusters in Germany and Switzerland while consumption concentrates in India and the United States. Pharmaceutical-grade system fabrication dominates European output. Dairy powder capacity expansion drives Asian and North American procurement.
United States
Pharmaceutical contract manufacturing demand for complex API formulations accelerates equipment procurement. OSHA combustible dust standards tighten containment requirements for powder handling systems. New Jersey and Massachusetts pharmaceutical corridors deploy closed-loop nitrogen systems for high-potency processing.
Germany
EU Green Deal industrial emissions targets mandate solvent recovery rates above 95 percent for new installations. REACH compliance drives retrofit demand across installed pharmaceutical processing capacity. Bavaria and North Rhine-Westphalia concentrate dairy powder system manufacturing for export markets.
India
PLI scheme incentives accelerate domestic dairy powder capacity expansion under food processing promotion programs. FSSAI standards govern equipment validation for infant formula production. Gujarat and Maharashtra host integrated drying line deployments serving export-oriented dairy processors.
Switzerland
Swissmedic pharmaceutical-grade validation requirements sustain premium equipment demand for biologics processing. Precision engineering capabilities support multi-stage system fabrication for heat-sensitive formulations. Basel and Zurich pharmaceutical clusters source specialized atomization technology for peptide drying applications.
Singapore
Biologics contract manufacturing expansion creates demand for gentle processing profiles preserving protein bioactivity. Closed-loop nitrogen systems enable high-potency API processing without extensive HVAC infrastructure. Tuas Biomedical Park hosts installations handling oxygen-sensitive compounds for regional pharmaceutical supply chains.
Spray Drying Market Competitive Environment
The competitive structure tilts toward diversified industrial equipment conglomerates with process integration capabilities. Market concentration remains moderate with tiered positioning across pharmaceutical validation intensity and dairy scale requirements. Strategic archetypes include pharmaceutical-grade specialists, dairy-focused integrators, and modular system fabricators. Capacity expansion and equipment-as-a-service contracting represent dominant competitive moves reshaping vendor-client relationships.
Among European-based diversified industrials, GEA Group and ANDRITZ Group exemplify pharmaceutical-grade and large-scale dairy positioning respectively. SPX FLOW occupies a position within sanitary design-focused fabricators serving food and beverage applications. Yamato Scientific represents laboratory-scale and pilot system specialists addressing R&D and small-batch production requirements.
| Leading Market Players |
|---|
| Yamato Scientific |
| ANDRITZ Group |
| GEA Group |
| Tetra Pak |
| SiccaDania Group |
| SPX FLOW |
| Dedert Corporation |
| VetterTec |
| Buchi Labortechnik |
| Others |
Value Chain & Pricing Dynamics
Contract manufacturing agreements for complex API formulations now dominate pharmaceutical procurement, forcing equipment vendors to absorb validation costs and compress delivery timelines. This buyer-driven restructuring concentrates pricing power with mid-sized processors seeking flexible capacity without fixed asset burdens.
Pricing Analysis
Margin tightening in pharmaceutical-grade systems reflects EMA validation requirements and integrated process analytical technology mandates. Three-tier pricing structure across premium, standard, and economy levels separates FDA-inspected continuous manufacturing units from batch-compatible legacy configurations. Price differentiation rests on certification grade and after-sales service bundling. Cost-down pressure on sanitary-design food systems accelerates because dairy processors in India prioritize PLI scheme compliance over feature depth.
Supply Chain Analysis
Freight cost volatility for precision-engineered atomization components from Germany and Switzerland strains just-in-time delivery commitments for biologics manufacturers in Singapore. Manufacturing concentration centers on Bavaria for multi-stage pharmaceutical systems and Gujarat for integrated dairy lines. Raw material dependencies include specialty stainless steel alloys, high-precision rotary atomizers, and nitrogen generation membranes. Single-source vulnerability for proprietary nozzle designs creates procurement bottlenecks. Distribution runs through regional equipment integrators with FDA qualification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards consolidation plays as EU Green Deal solvent recovery mandates force sub-scale European fabricators into distressed asset sales.
For Market Incumbents: Deepen backward integration into precision atomization component manufacturing to escape proprietary nozzle supply bottlenecks. Expand service contracting capabilities in India to capture PLI scheme-driven dairy capacity additions. Anchor position through equipment-as-a-service offerings that lock in long-term validation relationships. For New Entrants and Emerging Players: Mid-sized nutraceutical contract manufacturers represent an underserved buyer archetype seeking modular skid-mounted systems without enterprise-scale procurement overhead. Target fluidized bed coating applications for controlled-release formulations where functional food convergence outpaces incumbent R&D cycles. Lead with rapid deployment timelines and flexible financing structures. For Investors and Strategic Acquirers: The window for entry favors precision engineering specialists with Swissmedic-validated biologics capabilities. Long-term viability hinges on consolidation of atomization technology IP and regional service networks. Watch for inflection when EU member states translate Green Deal targets into mandatory retrofit deadlines for installed pharmaceutical capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Expansion | Monthly fee structures reduce balance sheet pressure for Dutch and Danish cooperative dairy processors. |
| Closed-Loop Nitrogen System Deployment | Tuas Biomedical Park installations enable high-potency API processing without extensive HVAC infrastructure. |
| Solvent Recovery Module Integration | German pharmaceutical processors consolidate operations to support centralized recovery infrastructure meeting 95 percent mandates. |
| Process Analytical Technology Integration | Real-time particle monitoring addresses FDA cGMP cleaning validation protocols between product changeovers. |
| Modular Skid-Mounted System Fabrication | Containerized units reduce deployment timelines for mid-sized food and pharmaceutical processors in India. |
Study Parameters
Multi-period observation of atomization technology adoption rates and contract manufacturing agreement structures anchored the trend analysis, supplemented by interviews with pharmaceutical plant engineers, dairy processing facility managers, equipment procurement leads at contract manufacturers, and aftermarket service directors. Secondary validation drew from FDA 483 inspection observations, EMA quality guideline updates, SEC 10-K filings of diversified industrial equipment conglomerates, and Indian PLI scheme disbursement records. Bottom-up equipment shipment tracking and top-down end-use demand modeling enabled triangulation across data sources.
Input-output matrices mapped atomizer specifications, thermal profile requirements, and containment levels to end-use applications across the projection horizon. Segmentation dimensions included product thermal sensitivity, validation intensity, stage configuration, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and greenfield capacity announcements. Industry-specific forecast inputs incorporated REACH compliance cost curves and PLI scheme incentive trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal implementation timing and natural gas price volatility affecting thermal processing economics. Forecasts reflect assumptions about regulatory translation timelines and buyer consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Individual Quick Freezing Market