
 Pizza Preparation Refrigerator Market | 2026-2036
Pizza Preparation Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Preparation Refrigerator Market Analytics
Equipment leasing and subscription-based service models are tilting competitive dynamics toward operators with lighter balance sheets. Tefcold leverages its European manufacturing footprint to sustain cost advantages across export channels. Infrico anchors its position through specialized refrigerated prep solutions designed for high-volume pizza operations. Afinox differentiates via precision temperature control technology that appeals to premium food service accounts.
Pizza preparation refrigerators are self-contained refrigerated cabinets with integrated work surfaces, typically maintaining temperatures between 33°F and 41°F to preserve perishable toppings while enabling immediate assembly access. These units employ forced-air refrigeration systems with stainless steel construction to withstand continuous sanitization cycles in commercial environments. Undercounter refrigerators occupy the largest installed base due to space efficiency in compact kitchens, while worktop refrigerators command attention where vertical workflow integration matters most. Salad and sandwich prep tables represent a mature segment with thinner margins, whereas nitrogen-cooled variants attract niche interest from operators prioritizing rapid temperature recovery during peak service windows.
The EPA SNAP program and DOE commercial refrigeration standards shape product development trajectories for equipment sold in the United States, compelling manufacturers to reformulate insulation and compressor specifications. CE marking under the EU F-Gas Regulation governs market access across European member states, with particular scrutiny of refrigerant global warming potential ratings. Stakeholders must monitor how pending efficiency standard revisions in multiple jurisdictions will recalibrate total cost-of-ownership calculations and retrofit timelines for existing kitchen fleets.
Market Dynamics
Ghost kitchen proliferation across the United States is compressing kitchen footprints and forcing operators toward compact, multi-functional prep refrigeration that consolidates workflow into single-unit footprints.
Growth Catalysts
- EPA SNAP refrigerant phase-down:The mandated transition away from hydrofluorocarbon refrigerants is accelerating replacement cycles as operators preempt compliance deadlines.
- Fast-casual pizza chains:Expansion of assembly-line pizza concepts is standardizing specifications for high-throughput prep tables with rapid temperature recovery.
- Polyurethane foam innovations:Vacuum-insulated panel technology is reducing cabinet wall thickness while maintaining thermal performance, freeing floor space in constrained kitchens.
Market Restraints
- Stainless steel price volatility:Fluctuations in nickel and chromium input costs compress margin predictability for cabinet manufacturers.
- Compressor supply concentration:Dependence on a limited supplier base for variable-speed refrigeration compressors creates procurement bottlenecks during peak demand periods.
- Refrigerant retrofit complexity:Existing hydrofluorocarbon-based units face technical limitations in drop-in alternative compatibility, extending fleet replacement timelines.
Strategic Opportunities
- Cloud kitchen infrastructure:Delivery-only foodservice facilities in dense urban cores represent underpenetrated demand for space-optimized undercounter configurations.
- IoT-enabled predictive maintenance:Convergence of refrigeration telemetry with kitchen management platforms creates recurring revenue streams through subscription diagnostics.
- US Inflation Reduction Act commercial efficiency incentives:Tax credits for qualifying energy-efficient equipment are lowering effective acquisition costs for certified models.
Industry Challenges
- EPA Section 608 technician certification:The shrinking pool of certified refrigeration technicians extends service response times and inflates maintenance labor costs.
- Legacy kitchen integration:Mismatched electrical specifications and dimensional standards between new prep units and existing line configurations complicate retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Preparation Refrigerator Market |
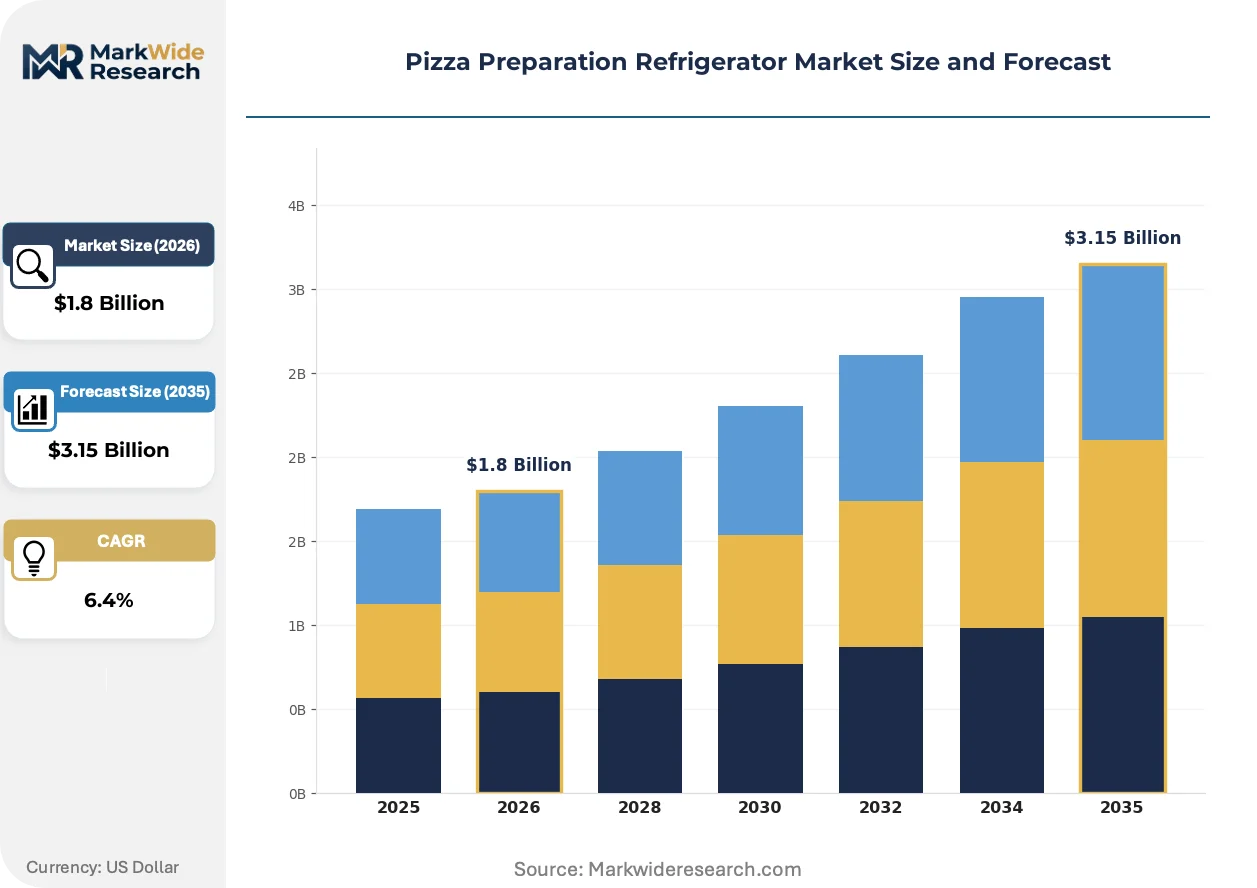
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undercounter Refrigerators, Salad/Sandwich Prep Tables, Reach-In Refrigerators, Worktop Refrigerators Use Case: Pizzerias, Food Trucks, Caterers, Restaurants Technology: Thermal, Refrigeration, Nitrogen, Eco-Friendly Refrigerants End User: Commercial Kitchens, Food Service Operators, Bakery Shops, Nightclubs |
| Companies Covered | Polar, Tefcold, Infrico, Sterling Pro, Blizzard, Lincat, Sagi, Afinox, Prodis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Preparation Refrigerator Market Evolving Landscape
Refrigeration architecture is converging with digital kitchen infrastructure, compressing the traditional separation between thermal equipment and operational intelligence systems.
Variable-speed compressor technology paired with adaptive defrost algorithms is virtualizing the traditional fixed-cycle refrigeration model. Independent pizzerias and regional chains are adopting these systems at accelerating rates to reduce energy penalties during low-volume periods. This virtualization is compressing the total cost-of-ownership gap between premium and standard equipment tiers, forcing mid-market manufacturers to accelerate their own control system development.
The US Department of Energy commercial refrigeration standards are tightening minimum efficiency thresholds for equipment categories covering pizza prep tables. Manufacturers must reformulate insulation densities and compressor specifications to maintain market access, with compliance costs concentrated in the undercounter segment where cabinet volume limits thermal engineering flexibility. The affected suppliers are responding by consolidating platform architectures to spread certification investments across multiple product lines.
Equipment-as-a-service contracting is displacing traditional capital purchase models among multi-unit operators. Third-party fleet management providers are inserting themselves between manufacturers and end-users, unbundling maintenance and upgrade obligations from initial acquisition. This channel restructuring is most visible in the United States, where private-equity-backed restaurant groups prioritize balance-sheet efficiency over ownership.
Pizza Preparation Refrigerator Market Segmentation
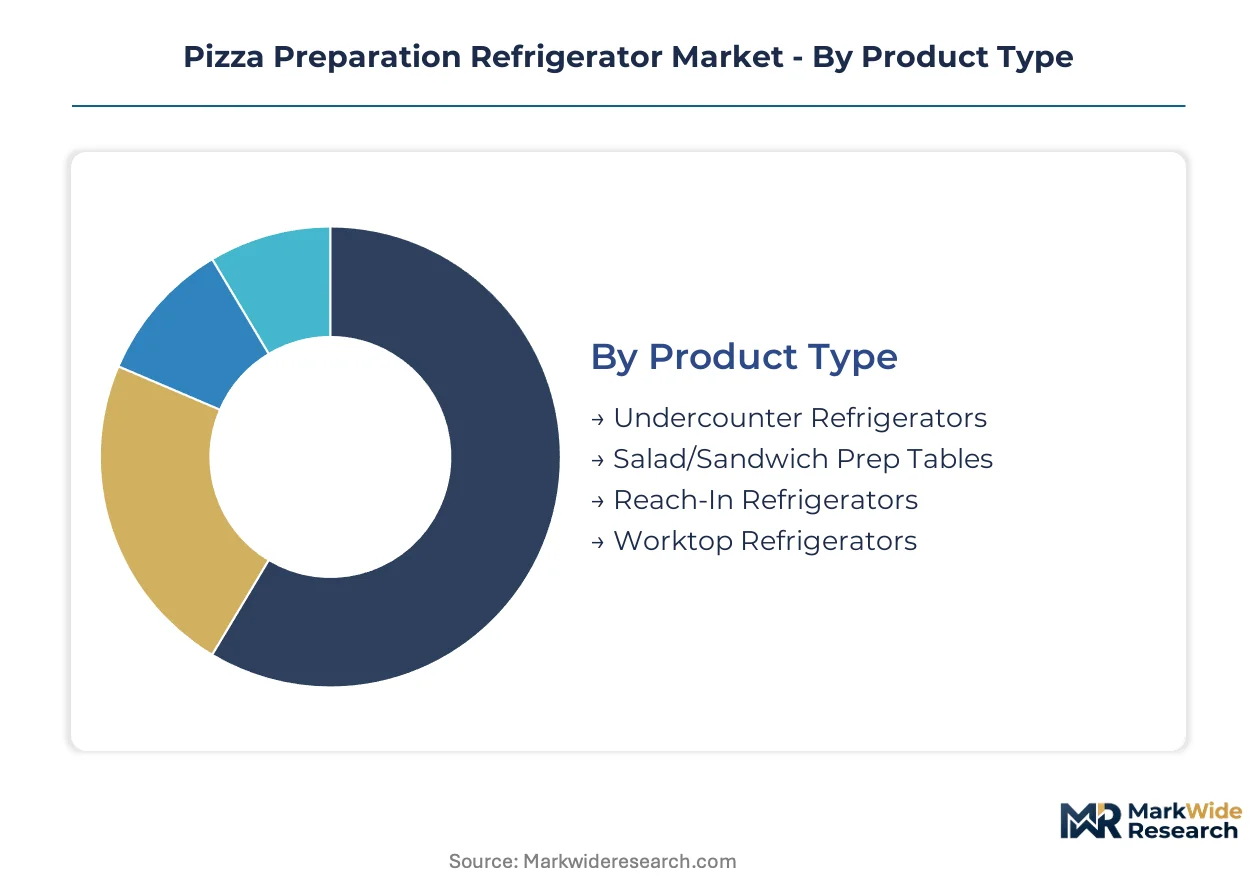
Pizza preparation refrigerators serve divergent operational requirements across kitchen footprints, service models, and regulatory environments. Equipment specifications vary sharply between compact ghost kitchens and high-volume assembly-line concepts, with each segment demanding distinct thermal performance, dimensional constraints, and compliance features.
Product Type:
Cost tier stratification separates premium worktop configurations from economy undercounter units, with mid-market salad prep tables occupying the contested center.
- Undercounter Refrigerators:Low-profile cabinets integrate beneath existing countertops, preserving vertical workspace in kitchens where square footage carries premium lease rates. Ghost kitchen operators in Manhattan, Los Angeles, and Chicago deploy these units to compress cold storage into minimal footprints while maintaining FDA food code temperature compliance.
- Salad/Sandwich Prep Tables:Shallow refrigerated wells with integrated cutting surfaces dominate fast-casual assembly lines. Chains expanding across Texas, Florida, and Ohio specify these units for standardized topping accessibility and rapid ticket throughput during lunch rushes.
- Reach-In Refrigerators:Vertical cabinet designs maximize storage density for high-volume pizzerias with dedicated prep stations.
- Worktop Refrigerators:Elevated work surfaces combine refrigeration with ergonomic pizza assembly height, attracting premium independent operators.
Undercounter refrigerators command the established base. The steepest expansion runs through worktop refrigerators.
Use Case:
Application context determines specification priorities, with mobility constraints and service velocity driving divergent equipment selections.
- Pizzerias:Dedicated pizza operations prioritize rapid temperature recovery during peak hours, specifying forced-air systems with stainless steel interiors rated for continuous sanitization cycles. Regional chains across Pennsylvania, New Jersey, and Connecticut standardize on NSF-certified units to streamline health inspection compliance.
- Food Trucks:Mobile operators confront vibration tolerance, electrical load limitations, and extreme ambient temperature swings. California and Texas food truck fleets increasingly specify 12V-compatible compressors and reinforced door hinges to withstand road stress.
- Caterers:Event-based service demands portable cold holding with rapid setup breakdown, favoring lighter cabinet construction.
- Restaurants:Full-service kitchens integrate pizza prep refrigeration into broader cold chain workflows, requiring compatibility with existing line configurations.
Pizzerias anchor volume demand. Caterers are climbing the fastest as event-service recovery accelerates.
Technology:
Regulatory pressure and energy cost trajectories are fragmenting technology adoption patterns across operator categories.
- Thermal:Passive cold retention systems without active compression serve backup holding applications and temporary event setups where electrical access proves unreliable.
- Refrigeration:Conventional vapor-compression systems with hydrofluorocarbon refrigerants still dominate installed base, though EPA SNAP phase-down deadlines are compressing replacement timelines for R-404A and R-134a dependent fleets.
- Nitrogen:Cryogenic cooling achieves sub-minute temperature recovery after door openings, attracting high-throughput operators in Las Vegas, Atlantic City, and other 24-hour gaming markets where equipment downtime incurs severe revenue penalties.
- Eco-Friendly Refrigerants:R-290 propane and R-600a isobutane systems qualify for DOE commercial efficiency incentives and IRA tax credits, lowering total cost-of-ownership for certified models.
Conventional refrigeration retains the largest installed base. Eco-friendly refrigerants are gaining share fastest as compliance deadlines approach.
End User:
Customer type determines procurement channel, with multi-unit operators leveraging fleet purchasing power against independent buyers prioritizing flexibility.
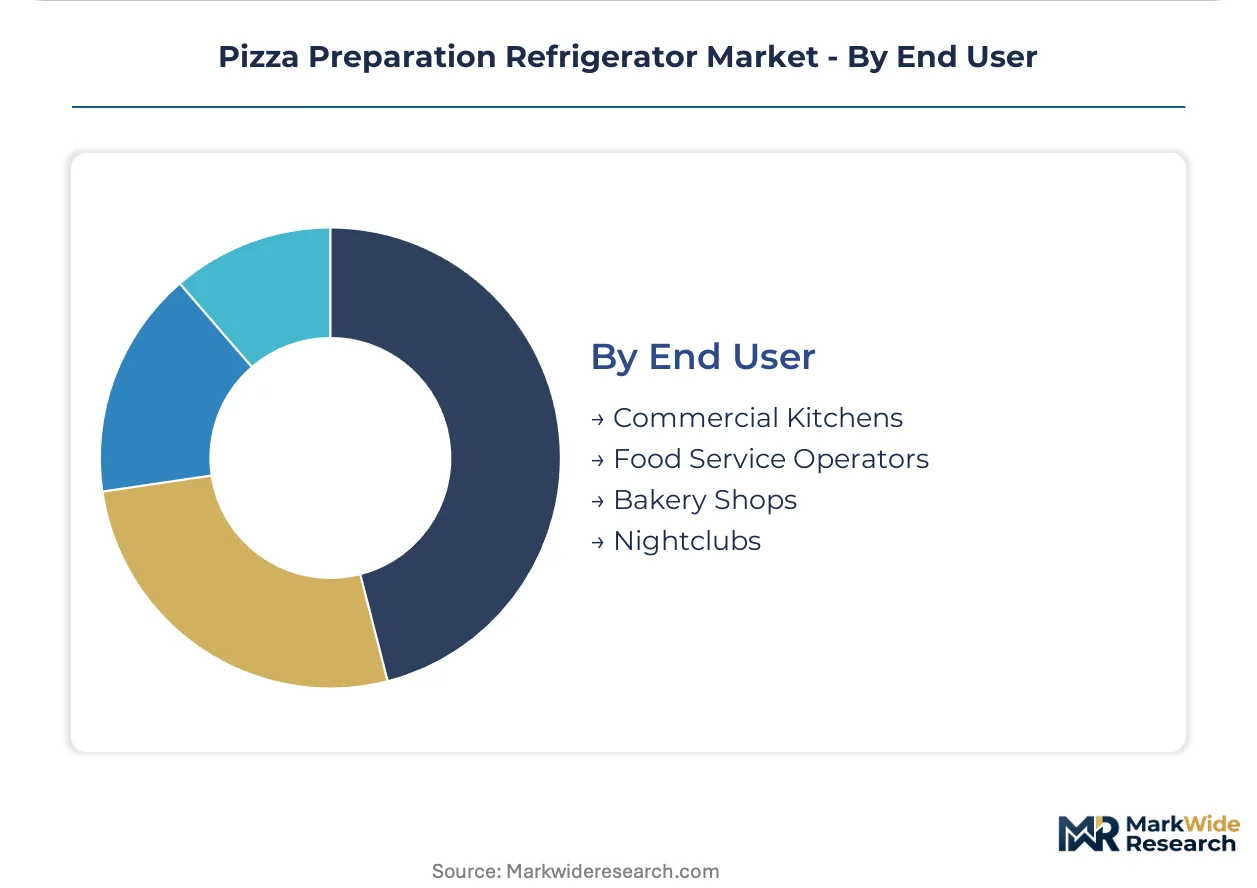
- Commercial Kitchens:Shared-use facilities and commissaries demand NSF and ETL sanitation certifications, with specification committees in Atlanta, Dallas, and Phoenix prioritizing standardized dimensions for interchangeable layout reconfigurations.
- Food Service Operators:National and regional chains negotiate manufacturer-direct pricing and consolidated maintenance contracts, unbundling acquisition from lifecycle service obligations.
- Bakery Shops:Crossover applications for dough retardation and topping storage require wider temperature range flexibility than pure pizza operations.
- Nightclubs:Late-night pizza service in Miami, New Orleans, and Nashville emphasizes compact undercounter units with noise-dampened compressors to preserve ambient atmosphere.
Commercial kitchens represent the volume anchor. Food service operators are expanding most quickly through chain rollout programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act commercial efficiency incentives and parallel European Green Deal funding mechanisms are redirecting capital toward certified equipment upgrades across major foodservice markets.
United States
Ghost kitchen proliferation in Manhattan, Los Angeles, and Chicago compresses cold-prep footprints into minimal square footage. EPA SNAP refrigerant phase-down deadlines accelerate replacement cycles for R-404A dependent fleets. The DOE commercial refrigeration standards tighten efficiency thresholds, compelling manufacturers to reformulate insulation specifications for undercounter units serving delivery-only concepts.
Germany
Fast-casual pizza chain expansion across Bavaria and North Rhine-Westphalia standardizes high-throughput prep table specifications. CE marking under EU F-Gas Regulation governs market access with scrutiny of refrigerant global warming potential ratings. Industrial clusters around Stuttgart and Cologne concentrate equipment fabrication serving export channels into Central and Eastern European markets.
United Kingdom
Independent pizzeria growth in Greater London and Manchester drives demand for worktop refrigerators with ergonomic assembly height. The UK Environment Agency enforces F-Gas Regulation compliance timelines parallel to EU frameworks. Regional equipment distributors in Birmingham and Leeds consolidate procurement for multi-site operators seeking standardized NSF-certified configurations.
Italy
Traditional pizzeria modernization across Lombardy and Emilia-Romagna balances heritage kitchen layouts with contemporary cold-chain requirements. National transposition of EU energy labeling directives affects specification priorities for family-owned operations. Manufacturing concentration around Bologna and Modena supplies refrigerated prep solutions optimized for thin-crust assembly workflows.
France
Premium foodservice accounts in Paris and Lyon specify precision temperature control systems for artisan topping preservation. ANSM and DGCCRF oversight intersects with EU F-Gas Regulation enforcement on refrigerant containment. Equipment leasing penetration rises among Île-de-France restaurant groups prioritizing balance-sheet efficiency over capital ownership.
Pizza Preparation Refrigerator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base distributes across three tiers: European manufacturing specialists with export scale, regional fabricators serving domestic installation channels, and private-label assemblers for foodservice equipment distributors. Strategic archetypes include refrigeration technology specialists, stainless steel fabrication generalists, and kitchen-system integrators. Dominant competitive moves encompass geographic expansion through distributor partnerships and portfolio diversification into adjacent cold-chain equipment categories.
Among UK-based specialists, Polar, Lincat, and Sterling Pro occupy positions within the mid-market fabrication tier. Tefcold anchors the Danish-origin export-specialist archetype with manufacturing footprint advantages across Northern European channels. Infrico exemplifies the Southern European precision-control positioning through its Spanish corporate base. Afinox represents Italian-origin premium-tier specialization with technology-forward control system integration. The competitive set distributes across national industrial clusters rather than consolidating under transnational holding structures.
| Leading Market Players |
|---|
| Polar |
| Tefcold |
| Infrico |
| Sterling Pro |
| Blizzard |
| Lincat |
| Sagi |
| Afinox |
| Prodis |
| Others |
Value Network & Pricing Analysis
Chinese compressor manufacturing concentration anchors cost structures for variable-speed refrigeration units, directing margin capture toward European stainless steel fabricators who command specification premiums through CE-certified assembly workflows.
Pricing Analysis
Certification level creates the primary spread between NSF-certified worktop configurations and uncertified economy imports. Three-tier pricing structure across premium, standard, and economy levels segments buyers by volume commitment and after-sales bundling requirements. Cost compression in the mid-market tier is intensifying because polyurethane foam insulation innovations are eroding thermal performance differentiation. Ghost kitchen operators exhibit the highest price sensitivity due to capital constraints, while premium independent pizzerias prioritize precision temperature control over acquisition cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates procurement risk for compressor-dependent manufacturers. Supply concentrates in Denmark for European export specialists, Spain for precision-control fabricators, and China for component sourcing. Stainless steel sheet and variable-speed compressors constitute critical input dependencies. Single-source vulnerability runs through the limited supplier base for R-290 compatible compressors. Distribution runs through foodservice equipment distributors and third-party fleet management providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against cloud kitchen infrastructure providers who bundle refrigeration into turnkey facility leases, threatening standalone equipment demand.
For Market Incumbents: Entrench specification control by embedding IoT telemetry into core product platforms, preempting third-party fleet managers from disintermediating maintenance relationships. Deepen backward integration into compressor supply through strategic partnerships with R-290 specialists, insulating against EPA SNAP compliance bottlenecks. Anchor position in fast-casual chain rollouts through standardized NSF-certified configurations that streamline health inspection compliance across multi-site deployments.
For New Entrants and Emerging Players: Secondary metropolitan food truck fleets in Texas and California represent underpenetrated demand for 12V-compatible vibration-tolerant units. Target catering recovery segments with lightweight rapid-deployment cabinets optimized for event setup breakdown. Pursue private-label partnerships with regional distributors in the United Kingdom and Germany to bypass incumbent brand recognition barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed ghost kitchen operators who prioritize balance-sheet efficiency over equipment ownership. The five-to-ten year viability window favors manufacturers with demonstrated EU F-Gas Regulation compliance pathways. Monitor EPA Section 608 technician certification pipeline constriction as an inflection signal for service revenue expansion opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Refrigeration telemetry convergence with kitchen management systems creates recurring diagnostic revenue streams. |
| Backward Integration into Compressors | In-house R-290 propane compressor sourcing insulates against EPA SNAP phase-down procurement bottlenecks. |
| Cloud Kitchen Partnership | Equipment-as-a-service contracting with delivery-only facilities captures balance-sheet-conscious demand. |
| EU F-Gas Compliance Certification | CE marking with low-GWP refrigerant qualification secures market access across member states. |
| Fast-Casual Chain Standardization | NSF-certified platform architectures spread certification investments across high-throughput prep table lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ghost kitchen facility managers, fast-casual chain procurement directors, independent pizzeria owners, foodservice equipment distributors, and EPA-certified refrigeration technicians. Secondary validation drew from DOE commercial refrigeration standard filings, EPA SNAP program rulemaking dockets, EU F-Gas Regulation compliance databases, and foodservice industry trade association reports. Bottom-up unit economics and top-down market sizing were triangulated to reconcile divergent data sources.
Calibration against historical replacement cycles and regulatory compliance deadlines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, use case, technology tier, and end-user category. CAGRs were derived from installed base turnover rates and expansion patterns in ghost kitchen and fast-casual chain segments. Forecast inputs incorporated EPA refrigerant phase-down timelines and IRA commercial efficiency incentive qualification thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by compressor manufacturers would shift outcomes through supply restructuring. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Spray Drying Market