
 Food Processing Machinery Market | 2026-2036
Food Processing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Food Processing Machinery Market Intelligence
Food-safe stainless-steel construction and IP69K washdown ratings is unwinding legacy equipment cycles across the industry. GEA Group Aktiengesellschaft leverages captive refrigeration technology to anchor European dairy lines. Bühler sustains its dominance in grain processing through in-house milling research centers. Marel specializes in portioning robotics for poultry, occupying a defensible niche in high-speed cutting automation.
Food processing machinery encompasses industrial equipment designed to transform raw agricultural inputs into packaged consumables through mechanical, thermal, or chemical operations, typically operating at throughputs exceeding 1,000 kg per hour with HACCP-compliant surface finishes. These systems serve commercial food manufacturers by standardizing yield, extending shelf stability, and eliminating contamination vectors across continuous production environments. Mixers and blenders lead capital expenditure in bakery and dairy applications where batch consistency determines brand retention. Automation technology is displacing pneumatic actuation in greenfield plants, driven by servo precision and predictive maintenance integration. Meat processing represents the fastest-growing application segment as labor costs and pathogen regulations tighten simultaneously.
FDA food-contact substance notifications and EU MDR conformity requirements shape equipment material selection and validation protocols for exporters serving dual jurisdictions. USDA FSIS directives on ready-to-eat product separation further dictate line architecture and clean-zone partitioning in North American facilities. BIS certification for India-bound imports adds a third compliance layer that smaller OEMs struggle to navigate cost-effectively. Stakeholders must monitor how cooling-system refrigerant phase-outs under EPA SNAP and EU F-Gas rules cascade into compressor and heat-exchanger redesign obligations.
Market Dynamics
EU F-Gas Regulation and parallel EPA SNAP mandates are forcing compressor and heat-exchanger redesigns across refrigeration-dependent lines, while servo-driven automation displaces pneumatic systems in greenfield facilities.
Growth Catalysts
- Refrigerant phase-out mandates:EU F-Gas Regulation and EPA SNAP rules compel equipment replacement cycles in dairy and meat processing, accelerating capital deployment toward compliant systems.
- Meat processing automation:Labor cost pressures combined with USDA FSIS pathogen directives drive adoption of high-speed portioning robotics in North American facilities.
- Stainless-steel washdown standards:IP69K ratings and HACCP-compliant surface finishes unwind legacy equipment cycles as hygiene protocols tighten across commercial bakeries and ready-to-eat plants.
Market Restraints
- Specialized alloy input volatility:Food-grade 316L stainless-steel pricing fluctuations compress OEM margins and extend quotation validity periods.
- Certification stacking costs:Dual FDA food-contact substance notifications and EU MDR conformity requirements create validation bottlenecks for exporters serving transatlantic markets.
- Technical integration barriers:Legacy pneumatic infrastructure resists retrofit with servo-precision architectures, constraining brownfield automation penetration.
Strategic Opportunities
- India import compliance services:BIS certification complexity creates advisory and localization revenue streams for engineering firms navigating equipment import protocols.
- Predictive maintenance convergence:Integration of IoT sensors with refrigeration monitoring enables uptime guarantees and unbundled service contracts in dairy processing.
- Plant-based protein lines:Extrusion and texturization equipment demand from alternative protein manufacturers opens greenfield installation opportunities distinct from traditional meat infrastructure.
Industry Challenges
- Mechatronics talent scarcity:Servo programming and refrigeration system integration skills outpace vocational training output in manufacturing clusters.
- Legacy control architecture migration:Proprietary PLC ecosystems resist interoperability with cloud-based predictive platforms, complicating brownfield digitalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Processing Machinery Market |
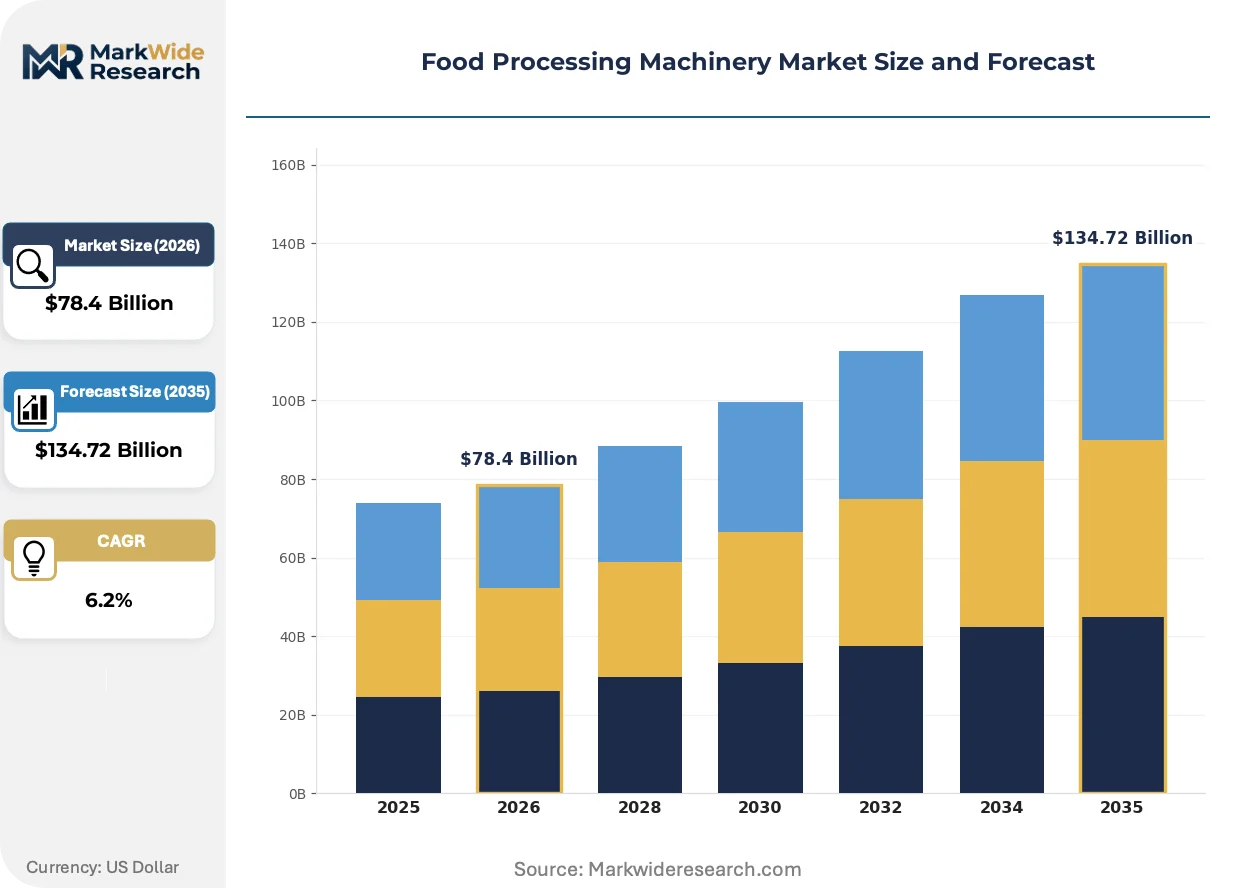
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
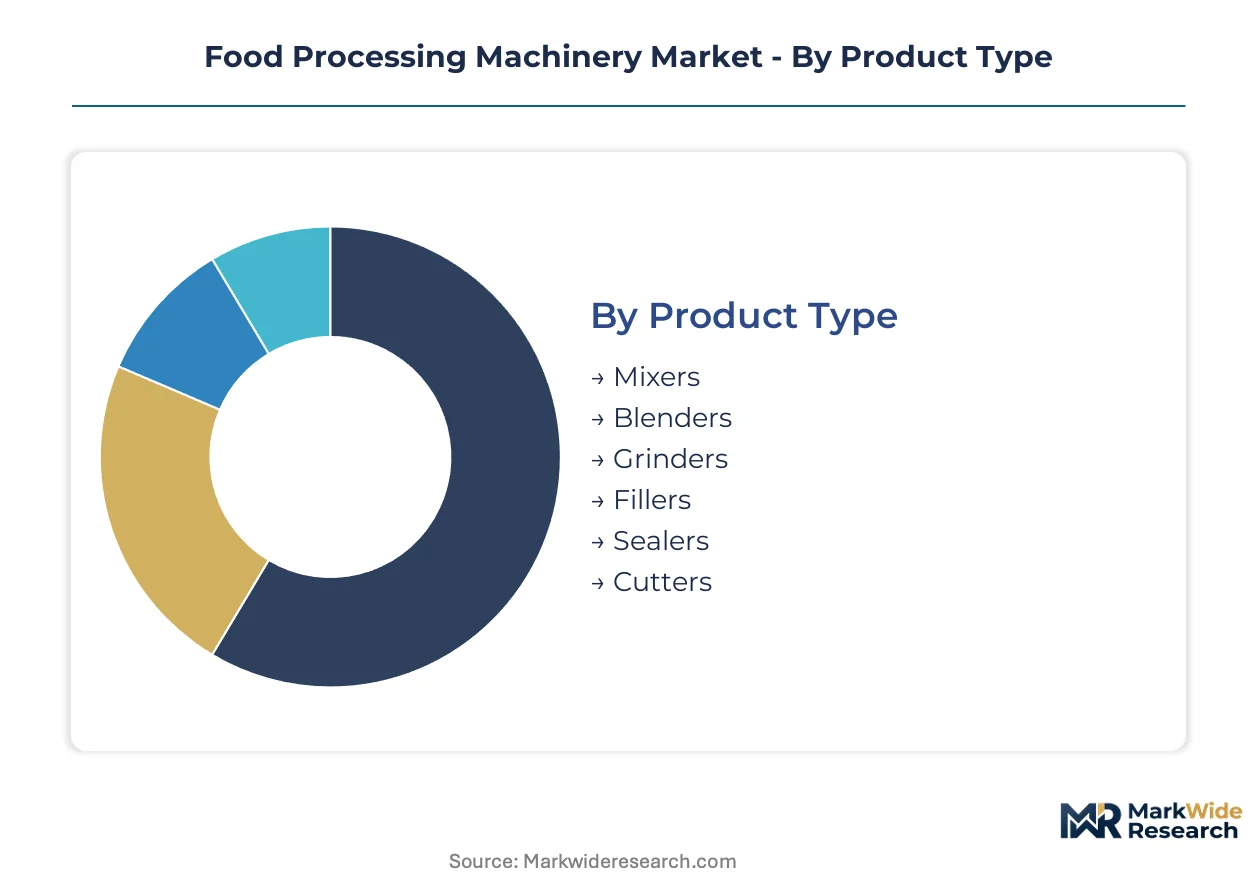
| Segmentation | Product Type: Mixers, Blenders, Grinders, Fillers, Sealers, Cutters Technology: Automation, Pneumatic, Hydraulic, Servo, Vacuum, Thermal Application: Dairy Processing, Bakery Products, Meat Processing, Beverage Production, Snack Manufacturing, Confectionery End User: Food Manufacturing Units, Packaging Companies, Research Laboratories, Catering Services |
| Companies Covered | GEA Group Aktiengesellschaft, Bühler, Marel, JBT Corporation, Tetra Laval, Tetra Pak International S.A., The Middleby Corporation, Alfa Laval, Hobart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Processing Machinery Market Strategic Shifts & Innovations
Servo-electric actuation architectures are displacing compressed-air systems across multiple processing categories, while regulatory refrigerant mandates and shifting procurement models reshape capital deployment patterns.
Electromechanical servo drives are decomposing the pneumatic infrastructure that dominated food processing automation for decades. High-speed cutting and portioning operations in poultry facilities now specify direct-drive motors for positional accuracy below 0.1 millimeters. This transition compresses energy consumption and maintenance intervals while elevating capital intensity per line.
EPA SNAP and EU F-Gas Regulation are cascading into compressor redesign obligations for refrigeration-dependent equipment categories. Natural refrigerant alternatives including CO2 and ammonia require heat-exchanger material changes and pressure-vessel recertification. Dairy processing lines in Germany and Wisconsin face the steepest retrofit timelines due to existing installed bases of HFC-dependent systems.
Equipment-as-service contracting is displacing outright purchase models among mid-cap food manufacturers. Opex-based arrangements bundle maintenance, refrigerant compliance updates, and throughput guarantees into single-line-item budgets. This shift concentrates most visibly in North American bakery and snack processing, where private-equity-owned rollups prioritize balance-sheet flexibility over asset ownership.
Food Processing Machinery Market Segmentation
Equipment specification varies sharply by product format and regulatory exposure. Channel economics favor different technology investments across dairy, meat, and bakery verticals.
Product Type:
Channel mix splits between turnkey line suppliers and component aftermarket, with capital intensity determining procurement route.
- Mixers:Batch and continuous configurations handle dough, batter, and viscous dairy preparations at throughputs exceeding 2,000 kg per hour. Demand concentrates in German and Wisconsin dairy facilities where HACCP-compliant surface finishes are mandatory for extended shelf-life products.
- Blenders:Twin-shaft and ribbon designs achieve coefficient of variation below 5% for dry ingredient uniformity. Expansion concentrates in North American ready-to-eat cereal and plant-based protein manufacturing as powder-to-liquid ratios tighten.
- Grinders:Particle size reduction systems for meat and spice applications.
- Fillers:Volumetric and gravimetric dosing equipment for liquid and semi-solid products.
- Sealers:Heat-seal and vacuum-seal systems for modified atmosphere packaging.
- Cutters:High-speed portioning and dicing machinery for protein processing.
Mixers dominate installed base. Blenders is where expansion concentrates.
Technology:
Cost tier stratification separates precision servo architectures from legacy pneumatic infrastructure.
- Automation:Integrated line control with SCADA connectivity and batch tracking compliance. Demand concentrates in greenfield European meat facilities where USDA FSIS and EU hygiene directives require full traceability.
- Servo:Electromechanical actuation delivering positional accuracy below 0.1 millimeters for high-speed cutting. Expansion concentrates in poultry portioning as labor costs and pathogen regulations tighten simultaneously.
- Pneumatic:Compressed-air actuation systems in legacy brownfield plants.
- Hydraulic:High-force pressing and forming applications in cheese and meat blocks.
- Vacuum:Deaeration and oxygen-exclusion systems for sensitive products.
- Thermal:Pasteurization, sterilization, and cooking modules for pathogen control.
Pneumatic systems dominate installed base. Servo is climbing the fastest.
Application:
Volume concentration tracks protein consumption patterns and dairy processing consolidation.
- Meat Processing:Portioning, grinding, and packaging lines for fresh and ready-to-eat products. Demand concentrates in North American facilities where USDA FSIS directives on Listeria control mandate equipment washdown protocols.
- Dairy Processing:Pasteurization, cheese making, and extended shelf-life packaging systems. Expansion concentrates in Germany where engineering-intensive machinery commands premium positioning and F-Gas refrigerant mandates force compressor upgrades.
- Bakery Products:Mixing, proofing, and baking automation for bread and pastry.
- Beverage Production:Filling, capping, and aseptic processing lines.
- Snack Manufacturing:Extrusion, frying, and seasoning equipment.
- Confectionery:Tempering, enrobing, and molding systems for chocolate and sugar products.
Dairy processing dominates installed base. Meat processing is gaining share fastest.
End User:
Customer type determines service intensity and contract structure preferences.
- Food Manufacturing Units:Integrated production facilities with captive maintenance capabilities. Demand concentrates in mid-cap North American bakeries where equipment-as-service contracting displaces outright purchase for balance-sheet flexibility.
- Packaging Companies:Co-manufacturers and contract packagers serving multiple brand owners. Expansion concentrates in private-equity-owned rollups prioritizing throughput guarantees over asset ownership.
- Research Laboratories:Pilot-scale equipment for product development and process validation.
- Catering Services:Central kitchen and commissary operations for institutional feeding.
Food manufacturing units dominate installed base. Packaging companies is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal machinery trade surpluses concentrated in German engineering clusters against deficit positions in emerging manufacturing economies. Capital equipment flows track regulatory divergence, with EU F-Gas compliance and USDA FSIS mandates creating distinct specification requirements across destination markets.
United States
Meat processing automation and dairy line upgrades drive capital deployment across Wisconsin and California processing corridors. EPA SNAP refrigerant phase-out rules compress replacement cycles for HFC-dependent compression systems. Chicago and Green Bay anchor midwestern dairy equipment demand where private-equity-owned rollups favor equipment-as-service contracting.
Germany
Engineering-intensive machinery commands premium positioning in global export markets, particularly for dairy pasteurization and bakery mixing systems. EU F-Gas Regulation forces compressor redesigns across refrigeration-dependent installed bases. Bavaria and Baden-Württemberg concentrate precision fabrication capacity serving transatlantic compliance requirements.
China
Domestic food safety scandals accelerate HACCP-compliant equipment adoption in coastal manufacturing zones. GB standards and SAMR enforcement tighten material certification for food-contact surfaces. Yangtze River Delta cities absorb imported European line technology while local fabricators capture mid-tier replacement demand.
India
Import dependence for precision processing equipment persists despite PLI scheme incentives for domestic manufacturing. BIS certification complexity creates validation bottlenecks for EU and US exporters. Maharashtra and Gujarat host emerging fabrication clusters targeting dairy cooperative and spice processing applications.
Brazil
Protein export orientation drives investment in portioning and packaging automation for beef and poultry value chains. ANVISA alignment with Codex Alimentarius standards shapes equipment specification for international market access. São Paulo state concentrates meat processing capacity where labor cost pressures accelerate robotics adoption.
Food Processing Machinery Market Key Industry Players
Concentration sits with diversified industrial conglomerates possessing captive refrigeration and precision fabrication capabilities. The vendor base stratifies across three tiers: European engineering houses with full-line integration, regional specialists dominating single-application niches, and Asian fabricators competing on capital intensity. Competitive moves center on refrigerant compliance bundling and predictive maintenance service unbundling.
Among European engineering houses, GEA Group Aktiengesellschaft exemplifies the diversified conglomerate archetype with captive technology spanning thermal and mechanical processing domains. Bühler occupies a position within grain and food processing specialization, while Marel represents the precision automation tier focused on protein applications. These three anchors demonstrate how geographic clustering around regulatory jurisdictions shapes competitive positioning.
| Leading Market Players |
|---|
| GEA Group Aktiengesellschaft |
| Bühler |
| Marel |
| JBT Corporation |
| Tetra Laval |
| Tetra Pak International S.A. |
| The Middleby Corporation |
| Alfa Laval |
| Hobart |
| Others |
Cost & Logistics Intelligence
Long-term equipment-as-service contracts lock in supply access and price visibility for mid-cap food manufacturers seeking balance-sheet flexibility over asset ownership. These arrangements bundle maintenance, refrigerant compliance updates, and throughput guarantees into predictable opex line items, insulating buyers from volatile stainless-steel input costs and compressor redesign cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in food processing machinery procurement. Premium tiers command positioning through IP69K washdown ratings and HACCP-compliant surface finishes, while standard configurations compete on throughput specifications and economy tiers sacrifice customization for capital efficiency. Cost compression in mid-tier equipment is intensifying because food-grade 316L stainless-steel pricing fluctuations compress OEM margins and extend quotation validity periods. Contract packaging companies exhibit highest price sensitivity due to private-equity ownership prioritizing balance-sheet flexibility, whereas integrated dairy processors demonstrate lowest sensitivity given captive maintenance capabilities and regulatory compliance imperatives.
Supply Chain Analysis
Extended lead times for precision servo drives and specialized refrigeration compressors now stretch procurement cycles beyond legacy pneumatic component availability. Supply concentrates in Germany for engineering-intensive thermal processing systems, Italy for pasta and bakery equipment, and China for mid-tier fabrication serving cost-sensitive Asian markets. Component sourcing draws from Japanese servo motor manufacturers, Swedish heat-exchanger specialists, and Indian control system integrators. Single-source vulnerability in CO2 compressor technology creates exposure as EU F-Gas Regulation accelerates HFC phase-out timelines. Distribution runs through authorized dealer networks for turnkey line integration and direct OEM relationships for aftermarket component supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across application-specific niches creates entry points for specialists as plant-based protein lines and alternative refrigerant systems generate demand pockets outside incumbent dairy and meat strongholds.
For Market Incumbents: Shield installed base revenue through predictive maintenance service unbundling and captive refrigeration technology retention in European dairy corridors. Consolidation of aftermarket parts distribution in North American bakery and snack processing defends against private-equity-owned contract manufacturers seeking equipment-as-service alternatives. Compressor redesign capabilities under EPA SNAP and EU F-Gas mandates represent the critical defensive lever against Asian fabricators lacking refrigerant compliance bundling expertise. For New Entrants and Emerging Players: Post-sales compliance advisory for BIS certification complexity in India offers immediate revenue traction where EU and US exporters struggle with validation bottlenecks. Plant-based protein extrusion equipment presents the most penetrable white-space segment, distinct from traditional meat infrastructure and underserved by protein-specialized incumbents. A go-to-market angle anchored in refrigerant transition consulting—bundling compressor specification, heat-exchanger recertification, and regulatory filing support—differentiates against component-only suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap servo-automation specialists possessing poultry portioning robotics expertise and established USDA FSIS compliance track records. Long-term viability across the analysis window favors targets with installed base density in F-Gas-mandated jurisdictions where replacement cycles accelerate capital deployment. The signal to watch is equipment-as-service contracting penetration in North American private-equity-owned food manufacturing rollups, indicating tipping point adoption for opex-based procurement models.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Compliance Bundling | Integrates CO2 compressor redesign with EU F-Gas and EPA SNAP validation to capture dairy line upgrade cycles. |
| Predictive Maintenance Convergence | Combines IoT sensor integration with refrigeration monitoring to enable uptime guarantees in continuous processing environments. |
| Servo-Automation Retrofit Services | Addresses brownfield pneumatic infrastructure resistance through phased electromechanical actuation migration programming. |
| Plant-Based Protein Line Development | Targets extrusion and texturization equipment demand from alternative protein manufacturers outside traditional meat infrastructure. |
| India Import Compliance Localization | Establishes BIS certification advisory capacity to reduce validation bottlenecks for EU and US equipment exporters. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers across dairy, meat, and bakery processing facilities; and secondary validation through SEC 10-K filings, EU MDR conformity documentation, FDA food-contact substance notifications, and customs/trade flow records. Bottom-up triangulation against top-down market sizing ensured segmentation integrity across equipment type, technology tier, and application vertical.
Across the modeling period, value and volume projections reflect disaggregated segment-level modeling incorporating replacement cycle timing, refrigerant mandate compliance deadlines, and automation penetration rates by facility vintage. Segmentation dimensions include product format, actuation technology, protein versus dairy versus bakery application, and customer type determining service intensity. CAGRs derive from installed base erosion analysis, greenfield capital expenditure patterns, and equipment-as-service contract adoption curves.
Forecasts assume regulatory continuity in EU F-Gas phase-out schedules, EPA SNAP refrigerant restrictions, and USDA FSIS pathogen control directives; material policy acceleration or rollback would require re-modeling. Stainless-steel alloy price volatility, mechatronics talent scarcity, and legacy PLC interoperability failures constitute specific revision triggers. Revision becomes warranted when servo-automation retrofit penetration in brownfield facilities crosses thresholds indicating technology substitution inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Refrigerated Vending Machines Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Beverage Processing Equipment Market