

Craft Beer Saccharification Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Beer Saccharification Equipment Market Insights
Direct-to-brewery equipment sales is rewriting how craft beer saccharification equipment reaches end users, bypassing traditional distributor networks in favor of manufacturer-led consultative relationships. GEA leverages its global service footprint to secure multi-vessel contracts with expanding regional breweries. Alfa Laval differentiates through heat exchanger integration that reduces energy consumption during the mash cycle. Paul Mueller Company anchors its position in North American microbreweries with stainless steel fabrication expertise and localized technical support.
Craft beer saccharification equipment encompasses vessels and auxiliary systems that convert malt starches into fermentable sugars through controlled temperature and enzymatic hydrolysis, typically operating at mash temperatures between 62°C and 72°C with precise pH monitoring to optimize amylase activity. The equipment serves the commercial brewing industry by determining extract yield, wort fermentability, and final beer body. Batch Mash Lauter systems occupy the largest installed base among product types due to their operational flexibility and lower capital barrier for small-scale brewers. Enzyme-Enhanced Saccharification technology is expanding fastest as breweries pursue adjunct-heavy recipes and reduced malt bills. Contract Brewing Facilities represent an underserved application segment where equipment sharing models create demand for modular, skid-mounted saccharification units.
The FDA enforces sanitary welding and surface finish standards under 21 CFR Part 117 for brewing equipment contacting food streams, while the EU Machinery Directive mandates CE conformity for automated mash control systems sold in member states. OSHA lockout/tagout regulations and EPA wastewater discharge limits further shape equipment design, particularly for water-intensive lautering operations. Stakeholders must monitor how evolving energy efficiency codes and carbon accounting requirements will alter capital allocation priorities for brewhouse upgrades.
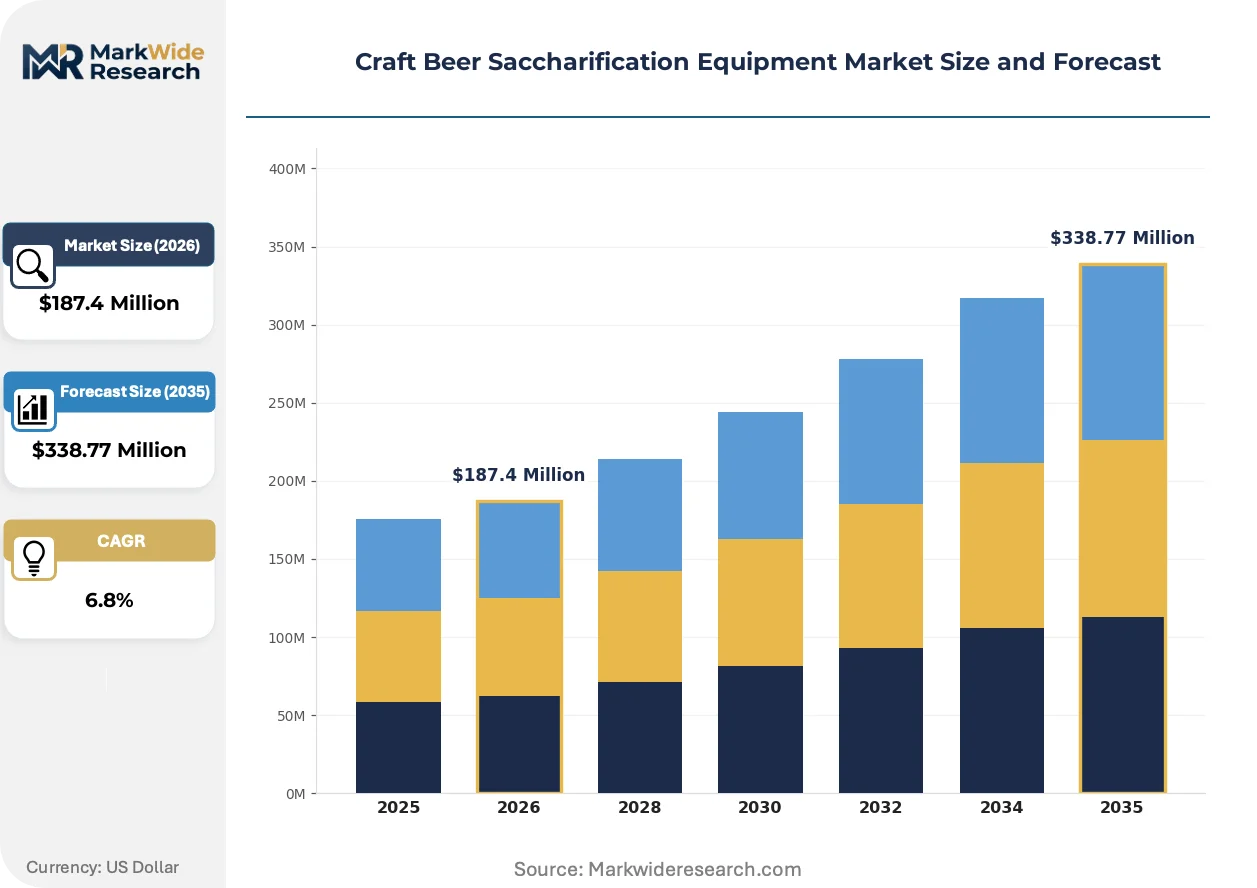
Market Dynamics
Enzyme-Enhanced Saccharification technology is collapsing traditional malt ratios as craft brewers pursue cost-efficient adjunct-heavy recipes, forcing equipment manufacturers to redesign vessel geometries for higher viscosity worts and extended enzymatic hold times.
Growth Catalysts
- FDA Food Safety Modernization Act:Sanitary welding mandates under 21 CFR Part 117 accelerate replacement cycles for legacy brewing vessels across American microbreweries.
- Contract Brewing Facilities:Equipment-sharing models in urban craft beer clusters generate demand for modular, skid-mounted saccharification units with rapid deployment timelines.
- Heat Exchanger Integration:Energy recovery systems that capture mash tun thermal output reduce brewhouse steam loads and align with tightening municipal energy codes.
Market Restraints
- Stainless Steel Input Volatility:304 and 316L alloy price swings compress fabrication margins for vessel manufacturers concentrated in North American foundry networks.
- EU Machinery Directive CE Conformity:Automated mash control systems face extended certification timelines and third-party audit costs before European market entry.
- Water-Intensive Lautering Operations:EPA wastewater discharge limits in water-stressed brewing regions impose capital-intensive filtration retrofits on existing installations.
Strategic Opportunities
- India Microbrewery Emergence:State-level excise liberalization in Karnataka and Maharashtra creates first-mover positioning for compact saccharification skits suited to commercial real estate constraints.
- Carbon Accounting Integration:EU Green Deal disclosure requirements position energy-monitoring mash systems as compliance-enabling purchases for export-oriented European craft brands.
- Direct-to-Brewery Sales Channel:Manufacturer-led consultative relationships bypass distributor markups and capture lifetime service revenue through embedded telemetry contracts.
Industry Challenges
- Sanitary Welding Certification Pipeline:ASME Section IX qualified welder shortages extend production lead times for vessels requiring pharmaceutical-grade surface finishes.
- Legacy DCS Integration Complexity:Proprietary mash automation protocols from established brewing groups resist interoperability with modern IoT-enabled temperature control architectures.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Beer Saccharification Equipment Market Trends and Innovations
Digital thread technologies and enzymatic process intensification are compressing brewhouse footprints while regulatory carbon tracking redefines equipment specification criteria across craft brewing procurement functions.
Continuous saccharification reactor designs are collapsing batch cycle economics for mid-scale regional breweries seeking throughput gains without linear capital expansion. Colorado and Oregon craft operators pilot plug-flow mash systems that eliminate lautering entirely through membrane filtration downstream. Equipment suppliers reconfigure vessel portfolios around this enzymatic intensification trajectory.
REACH chemical registration requirements for industrial enzymes used in adjunct-heavy brewing impose documentation burdens on European malt alternative suppliers. The European Chemicals Agency substance evaluation process extends formulation approval timelines, compressing recipe innovation velocity for craft brands dependent on exotic starch sources. German equipment manufacturers preemptively engineer compatibility with pre-certified enzyme portfolios.
After-sales telemetry unbundling disrupts traditional service contract structures as brewers demand usage-based maintenance rather than calendar-scheduled interventions. North American microbreweries in high-density clusters like Portland and Denver pilot sensor-as-a-service models where vibration and thermal data trigger predictive component replacement. Equipment vendors restructure field service organizations around remote diagnostic capabilities.
Craft Beer Saccharification Equipment Market Segmentation
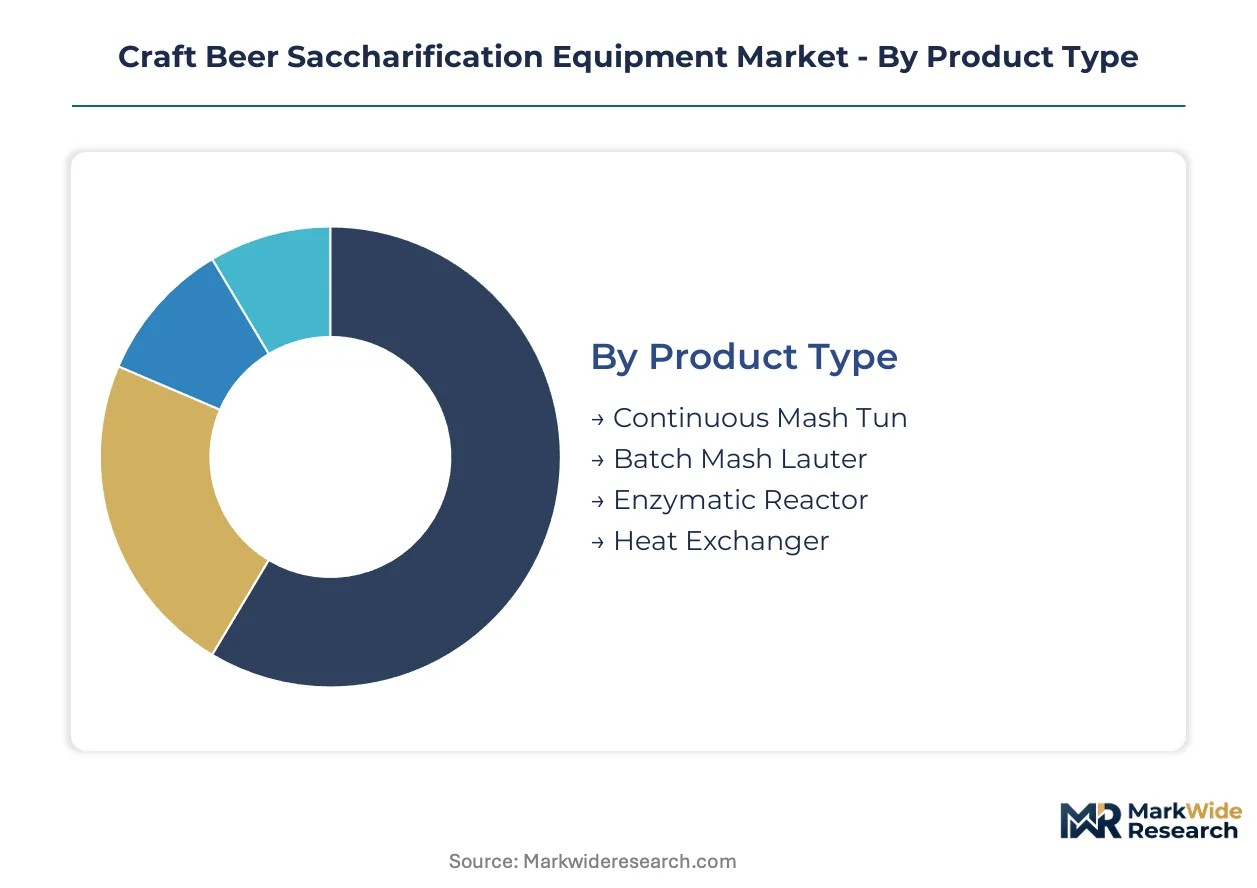
Equipment configuration in craft brewing saccharification varies sharply by operational scale and recipe complexity. Service intensity, spare parts availability, and telemetry integration requirements differ fundamentally across segment boundaries, reshaping manufacturer go-to-market economics.
Product Type:
After-sales service intensity peaks with continuous systems requiring specialized technician deployment, while batch vessels sustain simpler maintenance contracts through regional distributor networks.
- Batch Mash Lauter:Traditional vessel design combining mashing and wort separation in sequential operations dominates installed base across American microbreweries in Colorado and Oregon. Demand concentrates among sub-15,000 barrel operations seeking operational flexibility without dedicated lauter tun capital. FDA 21 CFR Part 117 sanitary welding mandates accelerate replacement cycles for legacy welded construction.
- Continuous Mash Tun:Steady-state thermal processing eliminates batch cycle downtime through automated grain-in/wort-out operation. German regional breweries pilot plug-flow configurations that collapse brewhouse footprints by 40 percent. Extended hold times and enzyme dosing precision demand manufacturer-direct service contracts with embedded telemetry.
- Enzymatic Reactor:Dedicated vessels for adjunct-heavy recipes with extended saccharification windows.
- Heat Exchanger:Energy recovery hardware integrated into mash temperature control loops.
By volume, Batch Mash Lauter leads. By growth pace, Continuous Mash Tun is climbing the fastest.
Technology:
Capital deployment per hectoliter varies threefold across technological approaches, with single-infusion systems anchoring entry-level economics and pressure-enhanced methods commanding premium positioning.
- Enzyme-Enhanced Saccharification:Exogenous amylase dosing enables 30-50 percent malt bill reduction through accelerated starch conversion. REACH chemical registration requirements for industrial enzymes impose documentation burdens on European craft brands sourcing exotic starch alternatives. ECHA substance evaluation timelines compress recipe innovation velocity.
- Step Mash:Programmable temperature ramping optimizes fermentability profiles for high-adjunct worts. American craft breweries in water-stressed western states favor step mash for its reduced lautering volume versus decoction methods. EPA wastewater discharge limits reinforce this preference through filtration cost avoidance.
- Infusion Mash:Single-temperature mashing with direct steam or hot water injection.
- Decoction Mash:Traditional German technique involving boiling portions of the mash.
- Pressure Saccharification:Elevated temperature operation above 100°C for accelerated conversion kinetics.
Infusion Mash retains the largest installed base. Enzyme-Enhanced Saccharification shows the steepest expansion trajectory as malt substitution economics improve.
Application:
Facility ownership structure determines equipment financing preferences, with independent operators favoring outright purchase and shared-production models driving modular lease arrangements.
- Microbreweries:Sub-15,000 barrel annual production facilities with limited cellar space and flexible recipe portfolios. Portland and Denver density clusters generate replacement demand as initial equipment reaches end-of-design-life. OSHA lockout/tagout compliance upgrades trigger capital events.
- Contract Brewing Facilities:Equipment-sharing infrastructure serving multiple brand labels from shared brewhouses. Urban real estate constraints in London and Berlin drive demand for skid-mounted saccharification units with rapid deployment timelines. Revenue-per-square-foot optimization favors compact continuous systems.
- Craft Breweries:Mid-scale regional producers with dedicated packaging lines.
- Brewpubs:On-premise consumption operations with aesthetic vessel requirements.
Microbreweries dominate current procurement volume. Contract Brewing Facilities are expanding most quickly as brand fragmentation outpaces greenfield construction.
End User:
Technical sophistication and specification authority vary sharply across buyer categories, with beverage conglomerates centralizing engineering decisions and independent operators relying on manufacturer consultative support.
- Independent Brewers:Owner-operated craft brands with direct equipment specification authority and price sensitivity to total cost of ownership. Karnataka and Maharashtra state-level excise liberalization in India creates first-mover positioning for compact saccharification skids suited to commercial real estate constraints. Localized technical support availability shapes vendor selection.
- Research & Development Labs:Pilot-scale brewing operations at ingredient suppliers and academic institutions. EU Green Deal carbon disclosure requirements position energy-monitoring mash systems as compliance-enabling purchases for export-oriented European craft brands. Telemetry integration supports grant-funded sustainability documentation.
- Beverage Producers:Diversified alcohol companies extending into craft beer.
- Specialty Drink Manufacturers:Adjacent category producers entering fermented beverages.
Independent Brewers anchor demand by unit volume. Research & Development Labs are gaining share fastest as ingredient innovation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sanitary welding mandates under 21 CFR Part 117 anchor the United States as the dominant geography, with microbrewery density in Colorado and Oregon driving replacement cycles for legacy vessels.
United States
Colorado and Oregon brewery clusters generate concentrated demand for Batch Mash Lauter systems as initial equipment reaches end-of-design-life. OSHA lockout/tagout compliance upgrades trigger capital events across sub-15,000 barrel operations. Portland's equipment-sharing facilities pilot modular skid-mounted units for contract brewing models.
Germany
Regional breweries in Bavaria pilot plug-flow continuous mash systems that eliminate lautering through downstream membrane filtration. The EU Machinery Directive mandates CE conformity for automated mash control systems, extending certification timelines for European market entry. Steinecker GmbH anchors fabrication expertise in Freising.
India
State-level excise liberalization in Karnataka and Maharashtra creates first-mover positioning for compact saccharification skids suited to commercial real estate constraints. The Food Safety and Standards Authority of India tightens sanitary standards for brewing equipment contacting food streams. Bangalore microbreweries drive procurement volume as brand fragmentation accelerates.
United Kingdom
London contract brewing facilities optimize revenue-per-square-foot through compact continuous systems in urban real estate constraints. The EU Green Deal disclosure requirements position energy-monitoring mash systems as compliance-enabling purchases for export-oriented craft brands. Manchester and Birmingham clusters favor step mash configurations for water-stress adaptation.
Australia
Victoria and New South Wales craft operators pursue enzyme-enhanced saccharification to reduce malt bills amid input cost volatility. The Therapeutic Goods Administration framework influences adjacent beverage equipment standards through quality system harmonization. Melbourne's high-density brewery districts generate replacement demand for telemetry-integrated vessels.
Craft Beer Saccharification Equipment Market Competitive Landscape
Global engineering conglomerates and specialized brewing fabricators split the market into distinct capability tiers. Consolidation concentrates around multi-vessel contract winners with embedded service footprints. Three archetypes dominate: integrated process technology groups, stainless steel fabrication specialists, and regional turnkey system providers. Capacity expansion in North American foundry networks and strategic partnerships for enzyme compatibility testing represent the dominant competitive moves.
Among German-based process technology groups, GEA and Krones occupy positions as integrated solution architects with global service infrastructures. Alfa Laval exemplifies the heat transfer specialization archetype through its exchanger integration capabilities. Paul Mueller Company anchors the North American fabrication tier with stainless steel vessel expertise. Steinecker GmbH represents the dedicated brewing technology archetype with concentrated regional presence. These three anchors—GEA, Alfa Laval, and Paul Mueller Company—sit within distinct strategic positions that shape procurement segmentation across microbrewery, contract brewing, and regional craft scale tiers.
| Leading Market Players |
|---|
| GEA |
| Krones |
| Alfa Laval |
| Steinecker GmbH |
| Paul Mueller Company |
| BrauKon |
| Specific Mechanical Systems |
| Briggs of Burton |
| Prospero Equipment Corporation |
| Others |
Pricing and Supply Chain Analysis
Trans-Atlantic freight corridors from Hamburg to Charleston anchor cost dynamics for stainless steel vessel fabricators, concentrating supply-side pricing power among North American and German foundry networks while forcing downstream price differentiation between configured-to-order and standard equipment tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order Batch Mash Lauter systems from standard skid-mounted units by 35-50 percent, with FDA 21 CFR Part 117 sanitary welding certification and ASME Section IX welder scarcity driving price differentiation at the premium tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, surface finish requirements, and embedded telemetry bundling. Cost compression in the economy tier is intensifying because Indian microbrewery procurement favors compact, lower-specification vessels. Contract Brewing Facilities demonstrate highest price sensitivity due to shared-capital constraints, while mid-scale regional craft breweries show lowest sensitivity when energy-monitoring features align with EU Green Deal compliance requirements.
Supply Chain Analysis
Supplier-financing facilities from German equipment manufacturers extend payment terms to 180 days for qualified microbrewery buyers, anchoring procurement decisions in working capital availability rather than upfront capital expenditure. Geographic supply concentration centers on Germany, the United States, and China for precision-machined components, with 304 and 316L stainless steel sheet and seamless tubing drawing from North American and European mill networks. Single-source vulnerability persists for pharmaceutical-grade surface finish processing, where ASME-qualified welder shortages extend lead times. Distribution runs through manufacturer-direct consultative relationships for continuous systems, while regional distributor networks sustain batch vessel aftermarket parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME Section IX qualified welder shortages and specialized sanitary fabrication expertise constrain capacity expansion across vessel manufacturers, creating asymmetric returns for stakeholders who secure scarce technical talent or captive production assets.
For Market Incumbents: Insulate service revenue streams by embedding telemetry-as-a-service contracts that lock in multi-year aftermarket relationships before competitors establish remote diagnostic capabilities. Backward integration into stainless steel processing secures margin control against 304 and 316L alloy price volatility. Prioritize certification investment for EU Machinery Directive CE conformity to preempt extended audit timelines that disadvantage smaller fabrication competitors. For New Entrants and Emerging Players: Compact saccharification skids for Indian microbreweries in Karnataka and Maharashtra represent the most penetrable entry point, where state-level excise liberalization outpaces established vendor localization. Modular equipment-sharing configurations for urban contract brewing clusters in London and Berlin offer second-mover positioning without direct confrontation with GEA or Krones. A direct-to-brewery sales channel with localized technical support teams bypasses entrenched distributor relationships that resist new vendor onboarding. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized brewing equipment divisions lacking dedicated service infrastructure. Long-term viability favors specialists with telemetry-integrated product architectures and enzyme-compatibility testing partnerships. Watch for REACH chemical registration timeline extensions for industrial enzymes as an inflection indicator that would compress recipe innovation velocity and favor equipment vendors with pre-certified enzyme portfolio compatibility.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry-as-a-Service Integration | Remote diagnostic capabilities from Alfa Laval and GEA restructure field service economics around predictive maintenance contracts. |
| Enzyme Compatibility Certification | Pre-engineered compatibility with REACH-registered enzyme portfolios accelerates European craft brand procurement cycles. |
| Compact Skid Modularization | Urban real estate constraints in Bangalore and Berlin drive demand for rapid-deployment saccharification units. |
| Backward Integration into Steel Processing | Captive 304 and 316L alloy supply from Paul Mueller Company insulates fabrication margins from commodity volatility. |
| Direct-to-Brewery Channel Expansion | Manufacturer-led consultative relationships bypass distributor markups and capture lifetime service revenue through embedded contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with craft brewery owners, brewhouse operations managers, equipment procurement leads at regional breweries, and aftermarket service directors at major fabrication facilities. Secondary validation drew from FDA 21 CFR Part 117 guidance documents, EU Machinery Directive technical files, ASME Boiler and Pressure Vessel Code standards, and stainless steel commodity trade data. Bottom-up unit economics from individual brewery capital expenditure records were triangulated against top-down vendor shipment estimates across the analysis window.
Calibration against historical replacement cycles in Colorado and Oregon microbrewery clusters anchored volume projections, with segmentation modeled across equipment configuration, saccharification technology, facility ownership structure, and buyer technical sophistication. CAGRs were derived from installed base turnover rates and greenfield capacity announcements. Enzyme-enhanced recipe adoption curves and municipal energy code tightening trajectories served as industry-specific forecast inputs throughout the projection horizon.
Practitioners should monitor REACH chemical registration timeline extensions, FDA sanitary welding enforcement intensity, and stainless steel alloy price volatility for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.