
 Top Drive Systems Market | 2026-2036
Top Drive Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Top Drive Systems Market Intelligence
The historical divergence in capital expenditure between large-scale rig integrators and niche technology specialists is collapsing as automation becomes a baseline requirement. This shift benefits integrated equipment giants like National Oilwell Varco Inc., which leverages its vast portfolio to offer complete drilling packages. In contrast, major drilling contractors such as Nabors Industries Ltd. focus on operational efficiency and fleet-wide technology standardization. Schlumberger Limited competes by embedding its digital solutions and drilling software into the top drive control systems.
A top drive system is a complex mechanical and electrical apparatus that hangs from the derrick and provides rotational force directly to the drill string. This design eliminates the need for a traditional kelly and rotary table, allowing for continuous drilling with longer pipe sections. Key specifications include torque ratings, often exceeding 80,000 ft-lbs, and power output, which dictates drilling speed and efficiency. Electric top drives have become the dominant product type due to their precise control and lower maintenance compared to hydraulic alternatives. The application segment for offshore drilling commands higher-margin systems built for harsh environments.
Equipment safety and operational standards create a complex compliance environment for manufacturers. The American Petroleum Institute (API) specifications, specifically API 8C, govern the design and manufacturing of hoisting equipment used in drilling. In parallel, systems sold in Europe must adhere to CE marking requirements under the Machinery Directive, ensuring fundamental safety. The choice between retrofitting older rigs with modern top drives and commissioning new-builds with fully integrated systems will define capital allocation strategies for operators.
Market Dynamics
The central dynamic shaping the market is the bifurcation of capital investment between new-build rigs with fully integrated drilling systems and the selective, high-return retrofitting of existing fleets with advanced, automated top drives.
Growth Catalysts
- Deepwater Exploration:The technical demands of drilling in ultra-deepwater basins, such as Brazil's pre-salt fields, require top drives with higher torque and advanced control capabilities.
- Drilling Automation:A push towards fully automated and remote-operated drilling rigs necessitates the adoption of intelligent top drive systems that can integrate with rig-wide control software.
- Safety Mandates:Enhanced global well control standards and a focus on personnel safety drive the adoption of systems that allow for continuous drilling and reduce manual pipe handling on the rig floor.
Market Restraints
- Capital Intensity:The significant upfront cost of acquiring and installing a new top drive system presents a major financial barrier for independent drilling contractors and smaller operators.
- Component Sourcing:A high dependency on a small number of global suppliers for critical components like high-power variable frequency drives (VFDs) creates supply chain vulnerability.
- Legacy Integration:Retrofitting older derricks, not originally designed for the weight and dynamic loads of a top drive, poses significant engineering challenges and structural modification costs.
Strategic Opportunities
- Geothermal Drilling:Adapting top drive technology for the high-temperature, hard-rock conditions of geothermal energy projects opens a new, non-cyclical application segment beyond oil and gas.
- Fleet Modernization:A substantial opportunity exists in upgrading the large, aging land rig fleets in Middle Eastern countries like Saudi Arabia with modern, efficient electric top drives.
- Digital Services:Developing and selling subscription-based predictive maintenance and performance optimization software as a service (SaaS) for installed top drive units creates a recurring revenue stream.
Industry Challenges
- Specialized Skill Gaps:A persistent shortage of field technicians who possess dual expertise in heavy mechanical systems and sophisticated digital control electronics hampers maintenance and troubleshooting efforts.
- Complex Certification:Managing dual compliance for API 8C in the Americas and CE marking under the Machinery Directive in Europe adds significant cost and time to product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Top Drive Systems Market |
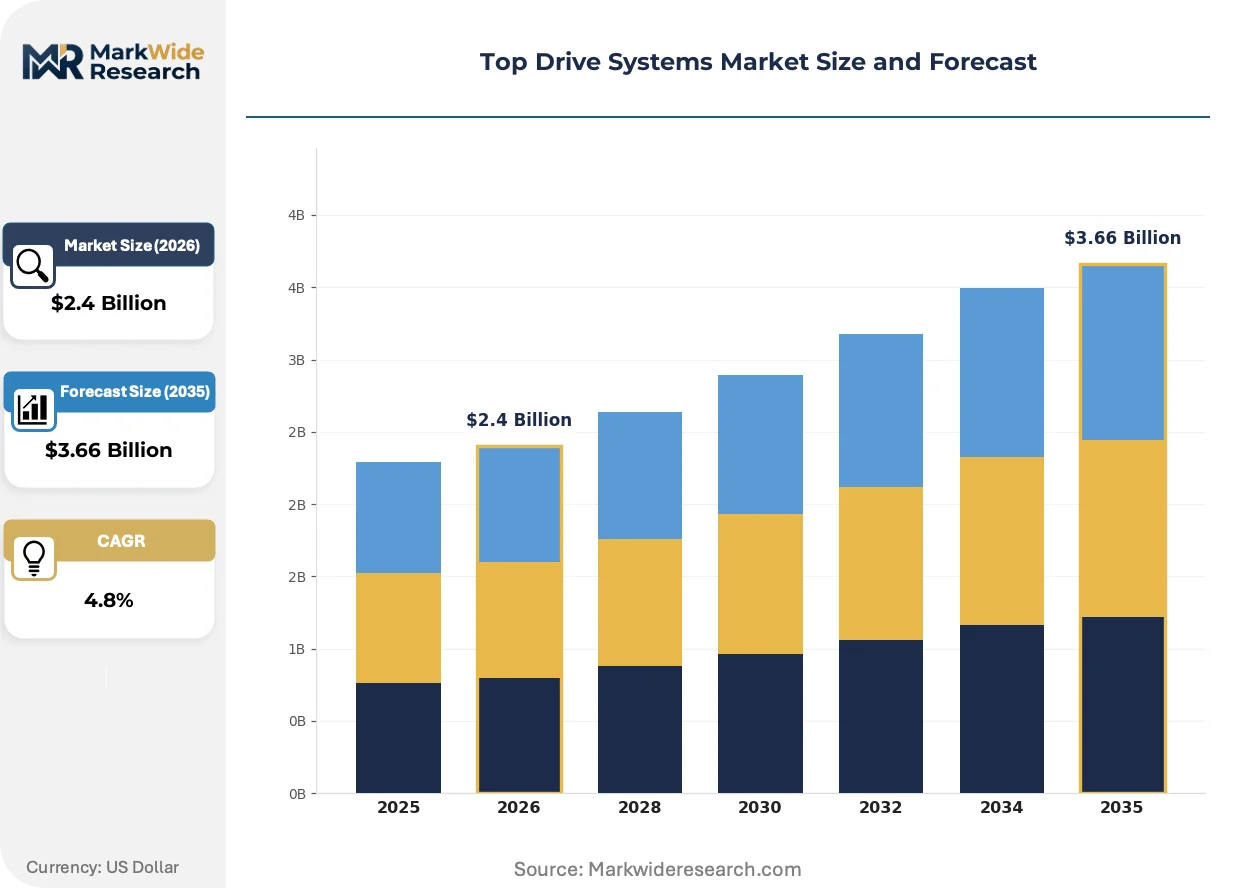
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Top Drive, Hydraulic Top Drive, Combined Drive, Chain Drive, Gear Drive Application: Onshore Drilling, Offshore Drilling, Deepwater Drilling, Shallow Water Drilling, Directional Drilling Installation Type: Fixed Rig, Mobile Rig, Jack-up Rig, Drillship, Semi-submersible Rig End User: Oil & Gas Operators, Drilling Contractors, Exploration Companies, Service Providers, Equipment Leasing Firms |
| Companies Covered | Nabors Industries Ltd., Bentec GmbH Drilling & Oilfield Systems, National Oilwell Varco Inc., China National Petroleum Corporation, Drillmec S.p.A., Schlumberger Limited, Aker Solutions AS, AXON EP Inc., Canrig Drilling Technology Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Top Drive Systems Market Strategic Shifts & Innovations
The evolution of top drive systems is defined by the integration of digital intelligence, transforming these machines from pure mechanical power sources into data-generating hubs that optimize the entire drilling process. This shift prioritizes operational efficiency and predictive capability.
Condition-based monitoring systems, often paired with digital twins, provide real-time data on equipment health and performance. Major offshore drilling contractors are rapidly implementing this for their deepwater fleets to preemptively identify potential failures. This technology is decomposing the traditional, reactive break-fix maintenance model into a proactive and data-driven operational workflow that minimizes non-productive time.
Stringent enforcement of ISO 14001 environmental standards is influencing equipment design. This pressures manufacturers to engineer electric top drives with higher energy efficiency and no hydraulic spill risk. The offshore segment in sensitive areas like the Norwegian continental shelf is most affected, driving demand for systems with certified environmental performance.
A transition from capital purchase to performance-based leasing contracts is gaining momentum. This model disrupts the equipment sales cycle, bundling maintenance and support into an operational expense. This trend is most pronounced among onshore US operators seeking to conserve capital and transfer risk.
Top Drive Systems Market Segmentation
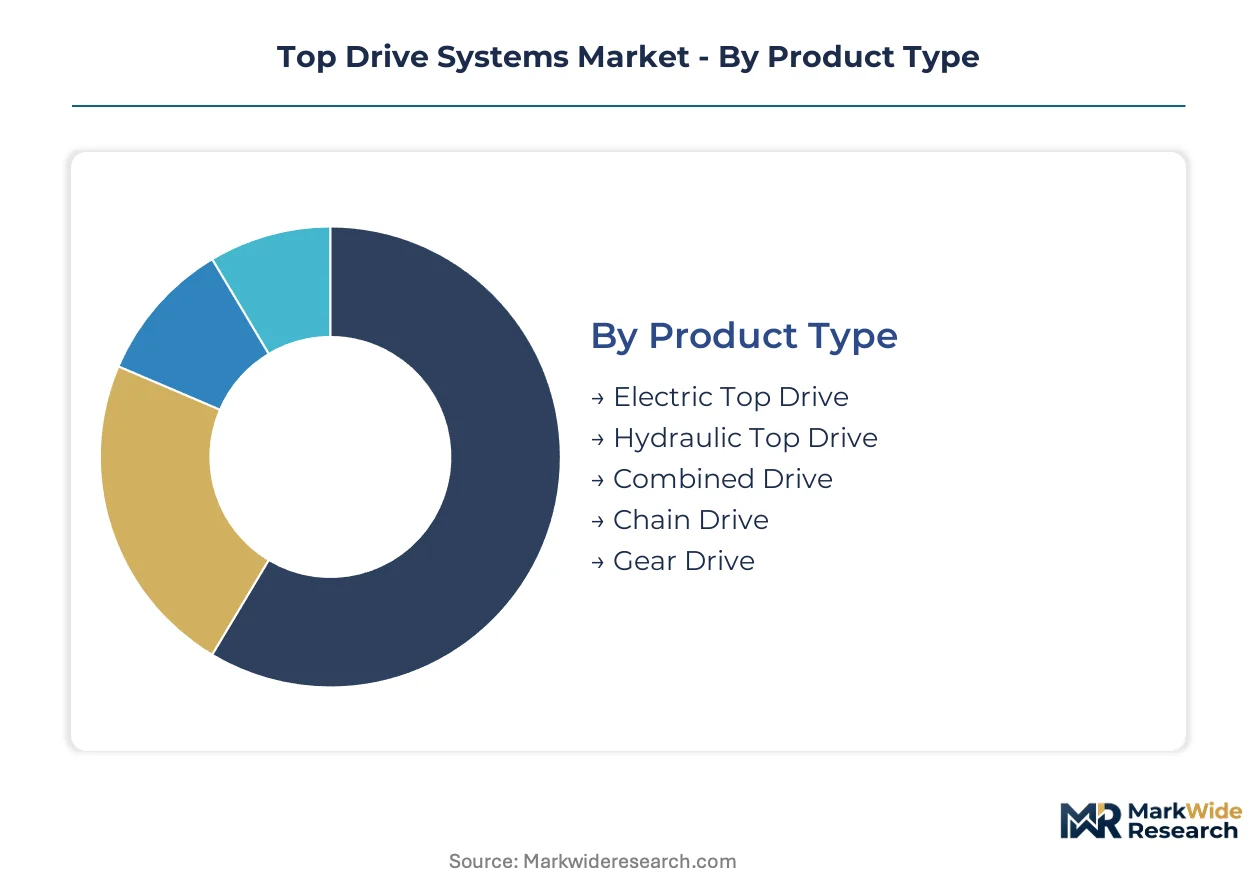
The Top Drive Systems market exhibits diverse characteristics across its various segments, reflecting the specialized demands of drilling operations worldwide. Understanding these distinctions is crucial for identifying areas of concentrated investment and technological advancement. Market segmentation highlights the specific performance requirements driving innovation in this equipment sector.
Product Type:
The product type segmentation reveals how technological preferences for top drive systems vary across different drilling regions and operational scales.
- Electric Top Drive:These systems utilize electric motors for precise control and high torque, becoming the dominant product due to their efficiency and lower maintenance requirements. Demand for electric top drives is concentrating in offshore deepwater projects in regions like the Gulf of Mexico, driven by stringent performance and environmental standards.
- Hydraulic Top Drive:Hydraulic systems offer robust power delivery through fluid pressure, often favored for their reliability in challenging conditions and ease of integration with existing hydraulic infrastructure. Their demand remains strong in land-based drilling operations across North America, where capital expenditure on new electric systems can be prohibitive for smaller operators.
- Combined Drive:These units integrate both electric and hydraulic components to leverage the benefits of each power source, offering flexibility for varied drilling applications.
- Chain Drive:Chain drive systems employ a heavy-duty chain mechanism to transmit rotational power to the drill string, providing a cost-effective solution for less demanding operations.
- Gear Drive:Gear drive top systems use a series of gears to deliver torque, known for their compact design and mechanical simplicity in certain rig configurations.
Electric Top Drive holds the largest share; momentum sits with Hydraulic Top Drive as retrofits continue.
Application:
Segmentation by application highlights the varying technical complexities and operational environments that dictate the choice and specification of top drive systems.
- Offshore Drilling:This segment requires top drive systems engineered for harsh marine environments, demanding robust construction, high reliability, and advanced control features to manage complex well designs. Demand is significant in regions such as the North Sea and Brazilian pre-salt fields, driven by the need for continuous operation and safety in remote locations.
- Deepwater Drilling:Specialized top drives for deepwater operations must handle extreme pressures and temperatures, providing superior torque and precise control for drilling ultra-long wells. Operators in the Gulf of Mexico and West Africa drive demand for these high-specification systems, where technical challenges necessitate advanced capabilities.
- Onshore Drilling:Top drives for onshore operations focus on mobility, ease of setup, and cost-effectiveness, serving a broad range of conventional and unconventional drilling projects.
- Shallow Water Drilling:Systems for shallow water applications balance performance with economic considerations, often used on jack-up rigs in continental shelf areas.
- Directional Drilling:This application requires top drives with precise rotational control and integration with sophisticated downhole steering tools, crucial for complex well trajectories.
The demand for Offshore Drilling systems is substantial, while Deepwater Drilling represents a segment with specialized requirements.
Installation Type:
The installation type segment reflects how the inherent characteristics of drilling platforms influence the design and integration requirements for top drive systems.
- Drillship:These self-propelled vessels are equipped for ultra-deepwater exploration and production, requiring highly integrated and automated top drive systems capable of dynamic positioning and continuous drilling in harsh conditions. Major oil companies deploying drillships in the Atlantic Ocean and off the coast of Brazil prioritize these advanced systems for their operational efficiency.
- Semi-submersible Rig:Semi-submersibles operate in deep to ultra-deep waters, offering stability in rough seas and demanding top drives that can withstand significant motion and provide consistent performance. Demand for these robust systems is concentrated in regions like the North Sea and Southeast Asia, supporting long-term development projects.
- Fixed Rig:Top drive systems for fixed rigs are typically permanent installations on platforms, emphasizing durability and integration with existing infrastructure for long-term production.
- Mobile Rig:Mobile rigs, primarily land-based, require top drives that are relatively lightweight and easily transportable, facilitating rapid deployment across different well sites.
- Jack-up Rig:These rigs are common in shallow to medium water depths, utilizing top drives that are robust enough for offshore conditions but also adaptable for various operational settings.
The Drillship segment drives significant investment, with Semi-submersible Rig installations indicating future technological direction.
End User:
End user segmentation illustrates the diverse procurement patterns and operational priorities that shape the market for top drive systems among key industry participants.
- Drilling Contractors:These entities own and operate drilling rigs, making them primary purchasers of top drive systems, focusing on operational efficiency, fleet standardization, and maintenance support. Major contractors like Nabors Industries Ltd. invest in advanced systems to enhance their service offerings and reduce non-productive time across their global fleets.
- Oil & Gas Operators:Operators commission drilling projects and often influence equipment specifications, prioritizing systems that ensure well integrity, safety, and project timelines. National oil companies in Saudi Arabia and international majors drive demand for high-performance top drives that align with their long-term production goals and environmental mandates.
- Exploration Companies:These firms focus on identifying new hydrocarbon reserves, requiring top drives that support efficient and reliable exploratory drilling in various geological formations.
- Service Providers:Companies offering specialized drilling services, such as directional drilling or well intervention, procure top drives tailored to their specific technical operations.
- Equipment Leasing Firms:These firms acquire top drive systems for rental to smaller operators or for projects requiring temporary equipment, focusing on asset utilization and return on investment.
The market is significantly influenced by Drilling Contractors, with Oil & Gas Operators emerging as a critical growth area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between mature offshore basins and emerging deepwater frontiers. Established markets with high regulatory burdens often command premium pricing for advanced systems, while regions prioritizing rapid development and cost efficiency may see more competitive bidding. This dynamic shapes capital allocation for top drive system procurement.
United States
Demand for top drive systems in the United States stems from offshore deepwater projects in the Gulf of Mexico and extensive onshore unconventional drilling. EPA environmental standards and OSHA safety mandates drive the adoption of advanced, continuous drilling systems. Houston, Texas, serves as a primary hub for oilfield services, hosting numerous technology developers and equipment manufacturers.
Brazil
Brazil's market for top drives is propelled by ultra-deepwater exploration in the pre-salt fields, requiring high-torque and specialized deepwater systems. ANP regulations govern offshore safety and operational requirements, influencing equipment specifications. Rio de Janeiro and Macaé are critical operational bases for offshore support and advanced deepwater drilling logistics.
Saudi Arabia
Saudi Arabia exhibits strong demand for modern electric top drives to upgrade its aging land rig fleets and meet long-term production goals. Saudi Aramco's stringent operational standards and local content requirements, supported by initiatives like IKTVA, shape procurement decisions. The Eastern Province, particularly Dhahran, hosts significant oil and gas infrastructure and technology centers.
Norway
The Norwegian market for top drive systems focuses on offshore drilling in the challenging Norwegian continental shelf, emphasizing robust design and environmental performance. The Petroleum Safety Authority Norway (PSA) mandates strict safety and environmental compliance, including adherence to ISO 14001 standards. Stavanger functions as a major energy capital, driving innovation in harsh environment drilling technologies.
China
China's market requires top drives for both expanding offshore and onshore drilling activities, driven by national energy security initiatives. Operational standards from entities like China National Petroleum Corporation (CNPC) and environmental regulations from the MEE influence equipment design. Tianjin and Shenzhen are growing hubs for offshore equipment manufacturing and service providers.
Top Drive Systems Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the top drive systems market. The market exhibits a tiered structure, with a few integrated equipment giants offering comprehensive solutions alongside specialized drilling contractors focused on operational efficiency. Strategic partnerships and portfolio diversification are common competitive moves among the larger entities.
Integrated equipment giants like National Oilwell Varco Inc. leverage their vast portfolio to offer complete drilling packages, anchoring the premium segment. Major drilling contractors such as Nabors Industries Ltd. prioritize operational efficiency and fleet-wide technology standardization across their global operations. Schlumberger Limited occupies a position as a digital solutions provider, embedding its software into top drive control systems to enhance drilling performance.
| Leading Market Players |
|---|
| Nabors Industries Ltd. |
| Bentec GmbH Drilling & Oilfield Systems |
| National Oilwell Varco Inc. |
| China National Petroleum Corporation |
| Drillmec S.p.A. |
| Schlumberger Limited |
| Aker Solutions AS |
| AXON EP Inc. |
| Canrig Drilling Technology Limited |
| Others |
Cost & Logistics Intelligence
API 8C and CE marking requirements gate both supplier qualification and price differentiation within the top drive systems market, creating distinct pricing tiers for compliant and specialized equipment.
Pricing Analysis
Configured-to-order pricing dominates for offshore deepwater systems, reflecting unique project specifications and high performance demands. The pricing model often follows a project-based structure, particularly for new rig builds or complex retrofits. Price differentiation stems from the specific certification level required, such as API 8C for hoisting equipment, and the extent of after-sales digital services bundled with the system. Pricing softness emerges in the land-based drilling segment due to a broader supplier base and less stringent customization needs. Smaller independent drilling contractors exhibit the highest price sensitivity, often opting for more cost-effective hydraulic alternatives or refurbished units.
Supply Chain Analysis
Inventory management for critical top drive components often involves longer lead times due to specialized manufacturing processes. Geographic supply concentration for high-power variable frequency drives (VFDs) and precision-machined components centers on countries like Germany, the United States, and select manufacturers in China. The supply chain draws from specialized steel alloys and advanced control electronics. Single-source vulnerability for specific VFD models presents a structural risk to manufacturers. Distribution runs through direct sales channels to major drilling contractors and oil and gas operators, often integrated into larger equipment packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The top drive systems market is undergoing a cyclical recovery, primarily driven by sustained capital investment in deepwater oil and gas exploration and production projects.
For Market Incumbents: Consolidate technology platforms to integrate advanced digital solutions and automation capabilities across product lines. This strategy counters the threat from niche digital solution providers who offer specialized software. Investment in R&D for next-generation electric motor designs and predictive maintenance algorithms represents a critical lever to maintain market leadership and capture higher-margin service revenue.
For New Entrants and Emerging Players: Certification fast-track through rigorous API 8C compliance can open market access, especially in established drilling regions. Target the modernization of aging land rig fleets in Middle Eastern countries like Saudi Arabia, where demand for efficient electric top drives is strong. A performance-based leasing model, bundling equipment and maintenance as an operational expense, offers a compelling go-to-market angle for smaller operators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the deepwater drilling segment, driven by the need for more powerful and automated systems. Long-term viability rests with companies possessing proprietary control software and robust after-sales service networks. The consolidation of digital service providers and specialized component manufacturers represents a key signal to watch as an inflection indicator for future M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing costs and streamlines maintenance for drilling contractors. |
| Digital Twin Development | Enhances predictive maintenance capabilities, minimizing non-productive time for operators. |
| Geothermal Application Expansion | Diversifies revenue streams beyond cyclical oil and gas markets into new energy segments. |
| Subscription-based Software Offerings | Creates recurring revenue streams from installed equipment for improved financial stability. |
| Advanced Material Integration | Improves system durability and performance in harsh deepwater environments for drillships. |
Research Approach
Initial hypotheses were tested against primary input from drilling engineers, procurement managers, rig operators, and regulatory compliance officers, then refined through an iterative validation process. Secondary validation involved comprehensive analysis of API standards, International Energy Agency (IEA) reports, publicly available company 10-K filings, and various industry association publications. This approach ensured a robust bottom-up and top-down triangulation of market data.
Variance decomposition was applied to segment the market by product type, application, installation type, end user, and regional regulatory environment across the analysis window. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected through quantitative modeling. Key forecast inputs included global crude oil prices, deepwater project sanctioning rates, and the pace of drilling automation adoption.
Decision-makers should treat outputs as directional under base assumptions of a stable regulatory environment and sustained energy demand; material deviation would warrant model refresh. Geopolitical instability or a major technological disruption in drilling methods represent significant risk factors that could alter these forecasts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pigging Valves Market
Valves
Fin Tube Market
Valves
Gate Impellers Market
Valves
Compressor Valves Market
Valves
Global Valve Positioners Market
Valves
Oil Drain Valves Market
Valves
Aerospace Valves Market
Valves
Hybrid Valve Market
Valves
Flanges Market
Valves
Supply Stop Valves Market
Valves
Actuators and Valves Market
Valves
Pipeline Strainers Market
Valves
Isolator Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Explosion Vents Market
Valves
Blow - Off Valves Market