
 Isolator Valves Market | 2026-2036
Isolator Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Isolator Valves Market Foresight
Aftermarket maintenance contracts and predictive service subscriptions are restructuring how isolator valve vendors capture lifetime value from installed bases. Emerson Electric Co. leverages its Plantweb digital ecosystem to bind customers into recurring diagnostics revenue. Flowserve Corporation anchors its competitiveness through vertical integration into specialty alloy casting for corrosive service valves. IMI plc differentiates via its Bimba engineering subsidiary's focus on ultra-high purity applications in biopharma.
Isolator valves are mechanical flow control devices engineered to provide absolute separation between process fluids and external environments, typically achieving leak-tight performance through metal-to-metal or soft-seat sealing interfaces rated to 10⁻⁶ mbar·l/s helium leak rates. Their primary purpose spans containment of hazardous media, protection of sterile pharmaceutical batches, and prevention of cross-contamination in multi-product chemical plants. Ball valves dominate the product type landscape due to their quarter-turn actuation reliability and compact envelope, while PTFE-lined variants command premium positioning in aggressive chemical service where fluoropolymer inertness justifies higher unit economics. Stainless steel remains the default material specification for pharmaceutical and food-grade applications, though PVC persists in water treatment where chloride resistance and cost sensitivity outweigh metallic durability requirements.
The US FDA enforces containment integrity standards through its guidance on potent compound handling, while the EU's MDR framework imposes traceability and validation documentation burdens on valve suppliers serving European pharmaceutical OEMs. EPA leak detection and repair protocols in the United States further tighten fugitive emission thresholds for chemical processing installations, directly influencing seat material selection and actuator specification. REACH compliance in Europe restricts certain elastomer formulations, compelling manufacturers to qualify alternative sealing compounds. Stakeholders must weigh regional regulatory divergence against platform standardization economics when configuring global product portfolios.
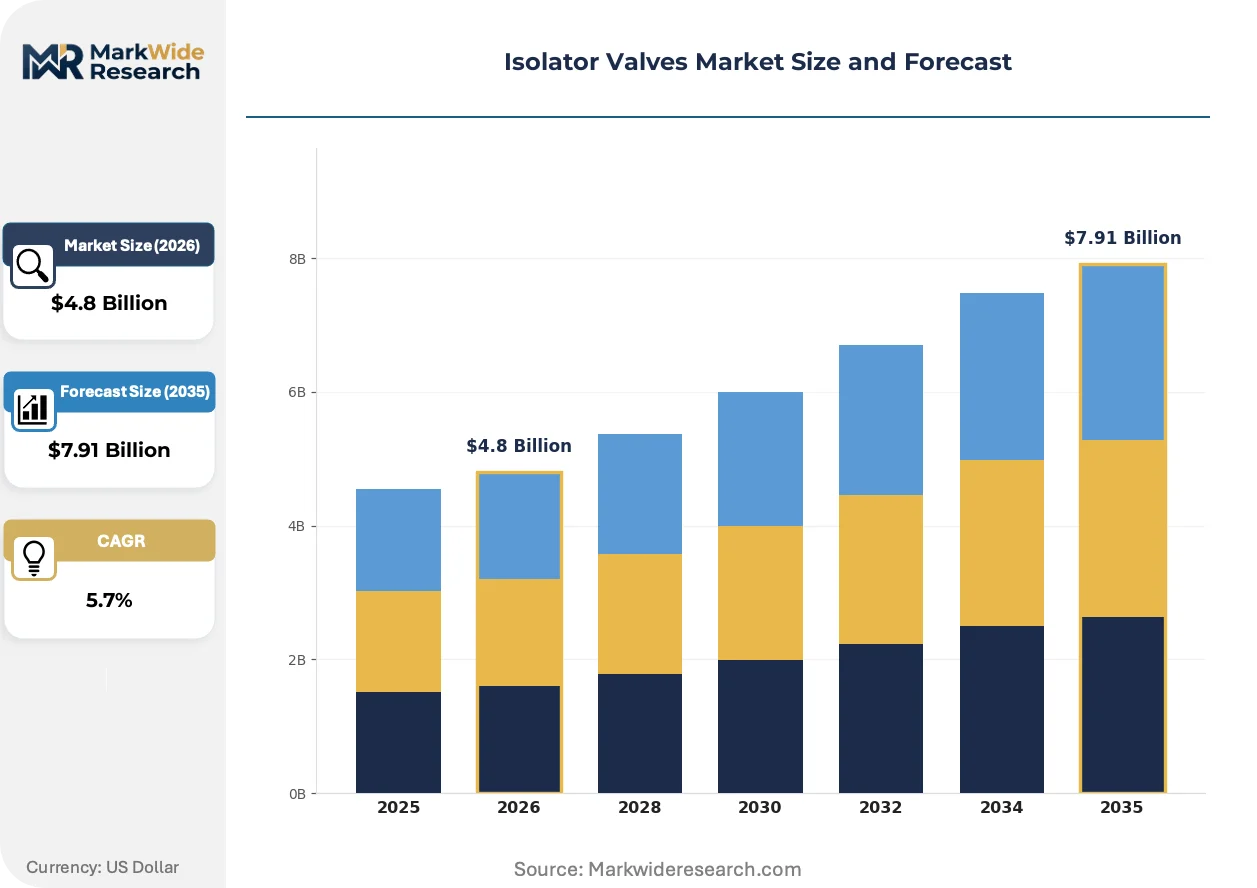
Market Dynamics
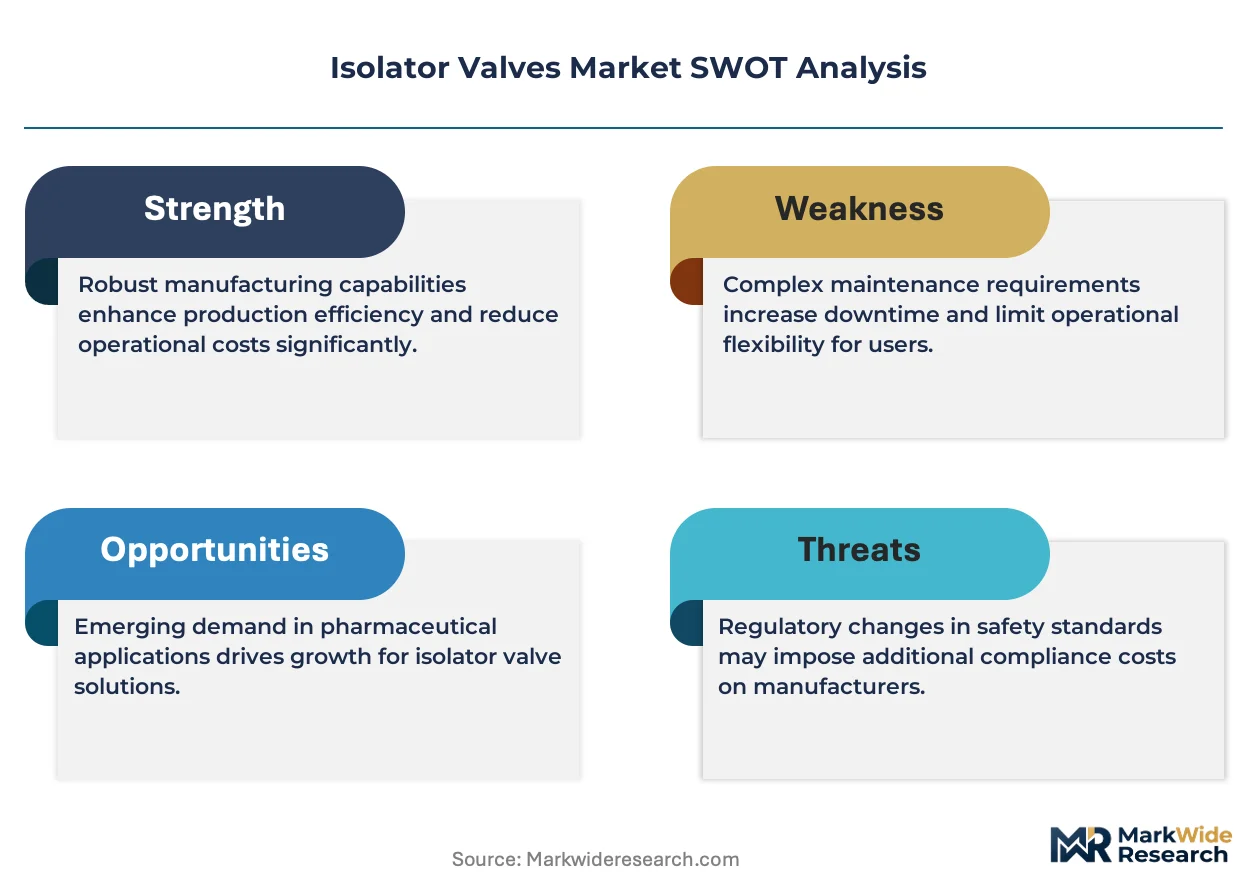
The isolator valves market is experiencing structural pressure from the US FDA's updated containment guidance for potent compounds, which mandates higher integrity sealing technologies and is forcing pharmaceutical manufacturers to accelerate retrofit cycles across their installed base.
Growth Catalysts
- Pharmaceutical containment mandates:The US FDA's guidance on handling potent compounds requires absolute isolation during aseptic processing, driving replacement demand for legacy valve systems in sterile manufacturing suites.
- Specialty chemical corridor expansion:Germany's Rhine chemical processing belt is retrofitting isolation infrastructure as producers add high-potency active pharmaceutical ingredient lines to existing multi-product facilities.
- Helium leak rate standards:Metal-to-metal sealing interfaces achieving 10⁻⁶ mbar·l/s certification are becoming baseline specifications for new biopharma installations, expanding addressable market for premium valve architectures.
Market Restraints
- Specialty alloy supply concentration:Corrosion-resistant alloys for aggressive chemical service depend on limited European and Japanese foundry capacity, creating input cost volatility and extended lead times.
- REACH elastomer restrictions:The EU's chemical framework bans certain fluoropolymer formulations, forcing manufacturers to requalify alternative sealing compounds and delaying product certifications.
- PTFE cost structure:Fluoropolymer-lined variants command premium positioning, but raw material price swings compress margin predictability for suppliers serving water treatment and chemical processing segments.
Strategic Opportunities
- Predictive diagnostics integration:Digital valve monitoring platforms are automating maintenance scheduling, creating recurring revenue streams through subscription-based performance contracts.
- Biopharma ultra-high purity demand:Cell and gene therapy manufacturing requires isolator valves with enhanced surface finish specifications, opening premium positioning for specialized engineering subsidiaries.
- India pharmaceutical manufacturing:CDSCO's alignment with international GMP standards is accelerating isolator valve deployment in contract manufacturing organizations serving export markets.
Industry Challenges
- Welding certification scarcity:Orbital welding expertise for high-purity stainless steel valve assemblies remains concentrated among specialized technicians, constraining production scaling for biopharma orders.
- Legacy system integration:Retrofitting isolator valves into existing containment infrastructure requires custom actuation interfaces, extending project timelines and engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isolator Valves Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valve, Butterfly Valve, Gate Valve, Check Valve Material: Stainless Steel, PVC, Brass, PTFE Application: Pharmaceutical, Food & Beverage, Chemical Processing, Water Treatment End User: Manufacturers, Hospitals, Research Institutions, Mining |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Crane Co., Schlumberger Limited, IMI plc, Weir Group PLC, KSB SE & Co. KGaA, Parker Hannifin Corporation, Spirax-Sarco Engineering plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isolator Valves Market Shifts & Advancements
Digital valve ecosystems are automating condition monitoring and predictive maintenance workflows, compressing traditional service intervals and restructuring vendor-customer relationships around performance guarantees rather than hardware transactions.
Smart actuation with embedded pressure and temperature sensors is automating real-time seat integrity verification, eliminating manual leak testing protocols. Biopharma manufacturers with continuous processing lines are deploying these systems to maintain sterile barrier validation without production interruptions. The technology is automating compliance documentation generation, reducing audit preparation burden for quality assurance teams.
REACH compliance deadlines are accelerating qualification of perfluoroelastomer alternatives for critical sealing applications. European valve suppliers are reformulating compound portfolios to maintain market access while preserving helium leak rate performance. Germany's chemical processing sector faces the most immediate requalification burden as legacy elastomer inventories deplete.
Buyer concentration among large pharmaceutical OEMs is consolidating procurement authority and demanding extended warranty terms. Tier-one manufacturers are unbundling hardware from service contracts, forcing mid-tier suppliers to compete on total lifecycle cost rather than unit price. This pattern is most pronounced in North American and Western European markets where facility consolidation has reduced the number of qualified bidders per project.
Isolator Valves Market Segmentation
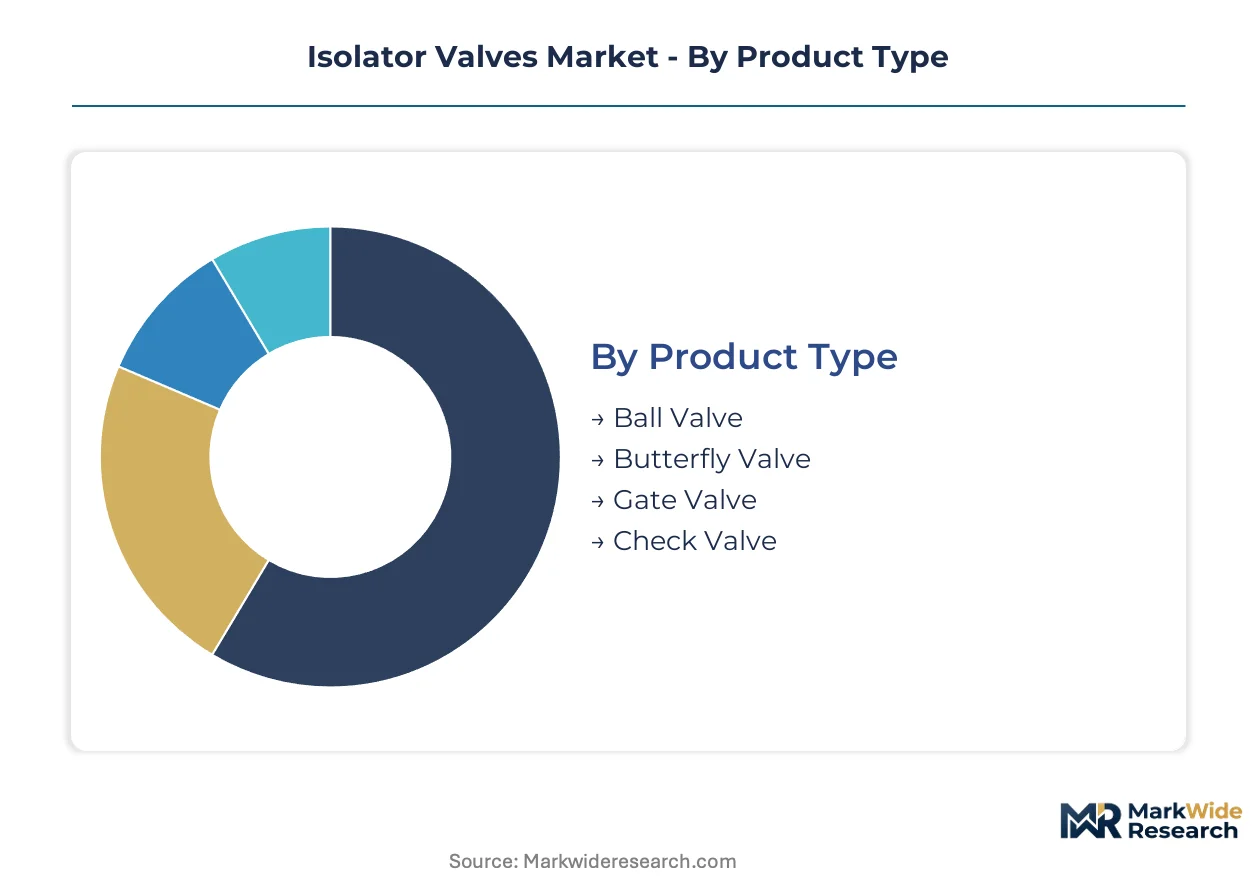
Isolator valve procurement patterns diverge sharply across process industries, with sealing integrity requirements and media compatibility dictating material selection and actuation architecture. Understanding these segment boundaries clarifies where specification premiums concentrate versus where cost engineering dominates purchasing decisions.
Product Type:
Quarter-turn valve architectures concentrate manufacturing capacity among specialized forging and casting houses serving high-pressure containment applications.
- Ball Valve:Spherical closure elements deliver bubble-tight shutoff through floating or trunnion-mounted designs, with metal-seated variants achieving the helium leak rates demanded by potent compound handling in US pharmaceutical suites. Demand concentrates in aseptic processing installations where FDA containment guidance mandates absolute isolation during batch operations.
- Butterfly Valve:Concentric and double-offset disc configurations offer compact face-to-face dimensions for space-constrained containment isolators, with laminated PTFE seats providing chemical inertness. Germany's Rhine chemical corridor drives retrofit demand as specialty producers reconfigure multi-product facilities for high-potency API lines.
- Gate Valve:Rising and non-rising stem designs provide straight-through flow paths with minimal pressure drop, suited to slurry handling in mining extraction circuits.
- Check Valve:Swing, lift, and piston configurations prevent backflow in multi-stage water treatment trains without external actuation.
Ball valves absorb the bulk of installed capacity in pharmaceutical containment; butterfly valves are expanding most quickly in chemical processing retrofits.
Material:
Corrosion resistance hierarchies and surface finish specifications segment supplier capabilities across pharmaceutical purity tiers and industrial durability requirements.
- Stainless Steel:Austenitic grades 316L and 304L dominate biopharma specifications, with electropolished internal surfaces below 20 Ra microinches required for cell and gene therapy manufacturing. REACH compliance pressures are accelerating qualification of low-cobalt formulations for European medical device applications.
- PTFE:Virgin and filled fluoropolymer linings provide universal chemical resistance against acids, caustics, and solvents, with permeation-resistant variants commanding specification in chlorine dioxide generation systems. Raw material price volatility from fluorspar supply concentration complicates margin forecasting for lined valve producers.
- PVC:Schedule 80 and CPVC formulations serve cost-sensitive water treatment infrastructure where chloride resistance outweighs metallic pressure ratings.
- Brass:Dezincification-resistant alloys persist in low-pressure instrumentation and sampling applications requiring machinability and thermal conductivity.
Stainless steel claims the largest share of specification value; PTFE-lined configurations are climbing the fastest in aggressive chemical service.
Application:
Regulatory stringency gradients separate markets where validation documentation burdens justify premium sourcing from commodity procurement environments.
- Pharmaceutical:Isolator valves in sterile manufacturing suites must maintain containment integrity across SIP/CIP cycles, with steam sterilization compatibility and drainability requirements shaping body cavity geometries. US FDA guidance on potent compound handling is accelerating replacement cycles for legacy soft-seated installations that cannot achieve metal-to-metal sealing performance.
- Chemical Processing:High-potency API containment and multi-product cross-contamination prevention drive specification for zero-leakage sealing in Germany's specialty chemical corridor along the Rhine.
- Food & Beverage:3-A sanitary standards and EHEDG guidelines dictate surface finish and crevice-free construction for aseptic dairy and beverage processing.
- Water Treatment:Chloramine and ozone disinfection protocols favor inert elastomer selections in municipal distribution and industrial reuse systems.
Pharmaceutical applications command the highest specification premiums; chemical processing is gaining share fastest as potent compound manufacturing expands.
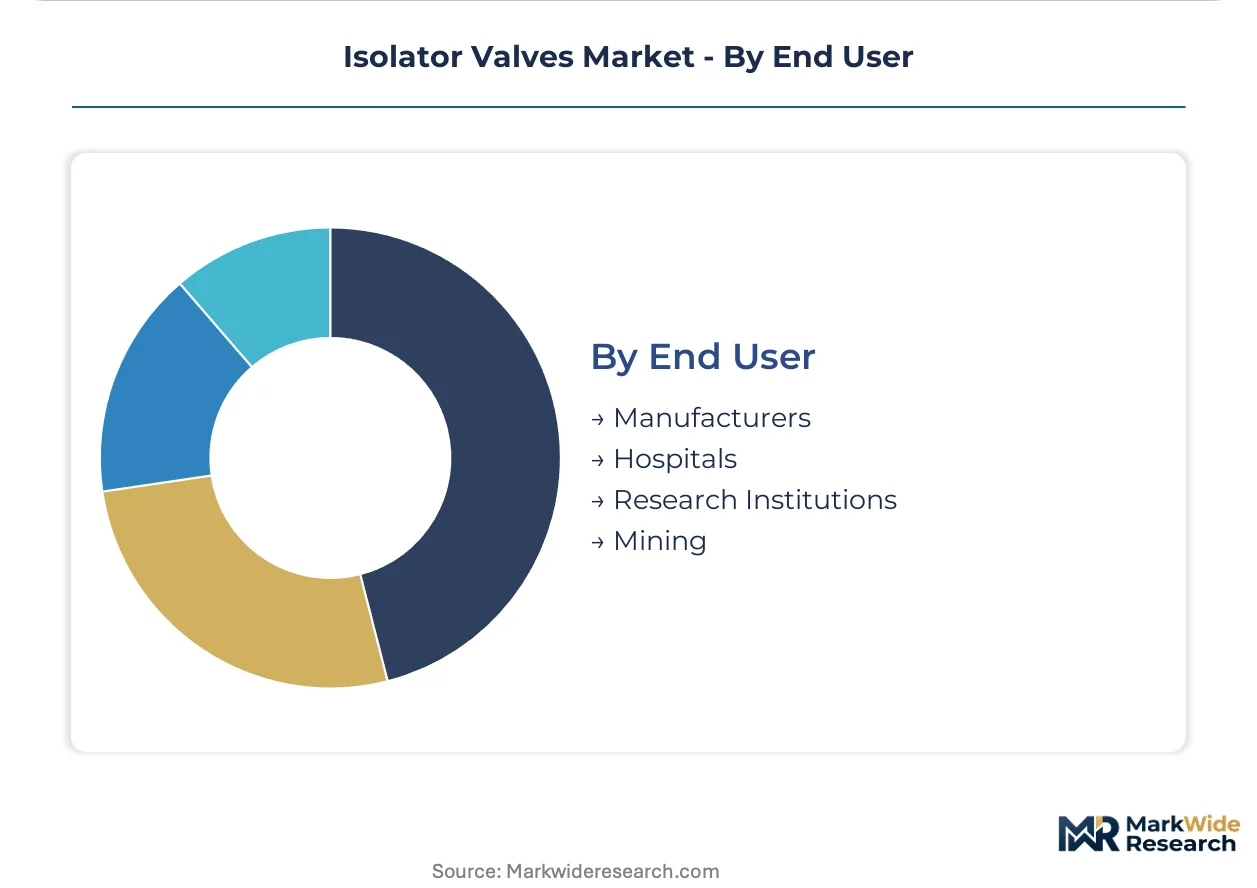
End User:
Procurement authority concentration and technical specification capability vary dramatically across integrated manufacturers versus fragmented maintenance operations.
- Manufacturers:Pharmaceutical and chemical producers with captive engineering staffs develop proprietary valve specifications binding suppliers to custom actuation interfaces and extended validation protocols. Predictive maintenance subscriptions are restructuring vendor relationships toward performance guarantees rather than hardware transactions.
- Hospitals:Compounding pharmacies and nuclear medicine facilities require isolator valves for radiopharmaceutical containment, with ALARA principles driving remote handling specifications.
- Research Institutions:University and government laboratories prioritize flexibility and rapid procurement over lifecycle optimization in containment infrastructure.
- Mining:Slurry handling and heap leach operations demand abrasion-resistant metallurgies with minimal maintenance access requirements.
Manufacturers represent the dominant procurement volume; hospitals are expanding fastest as radiopharmaceutical production localizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European foundries supply specialty alloys to valve fabricators worldwide, while US pharmaceutical manufacturers consume the highest specification units. Asian contract manufacturers are scaling production for mid-tier chemical processing applications.
Germany
The Rhine chemical corridor drives retrofit demand as specialty producers add high-potency API lines to existing multi-product facilities. REACH elastomer restrictions force requalification of alternative sealing compounds for valve suppliers serving European markets. Ludwigshafen and Leverkusen concentrate containment infrastructure upgrades for potent compound manufacturing.
United States
FDA containment guidance for potent compounds accelerates replacement cycles across sterile manufacturing suites. EPA leak detection protocols tighten fugitive emission thresholds for chemical processing installations. New Jersey and Massachusetts biopharma clusters deploy metal-to-metal sealing valves achieving 10⁻⁶ mbar·l/s helium certification.
India
CDSCO alignment with international GMP standards accelerates isolator valve deployment in contract manufacturing organizations. Pharmaceutical export growth drives specification upgrades for sterile processing infrastructure. Gujarat and Maharashtra host the fastest-growing concentration of containment retrofit projects serving regulated markets.
China
NMPA regulatory convergence with ICH guidelines elevates sealing integrity requirements for domestic biopharma production. Chemical processing expansion along the Yangtze River Delta demands corrosion-resistant valve architectures. Shanghai and Suzhou pharmaceutical parks specify stainless steel isolator systems for cell therapy manufacturing.
Japan
PMDA sterile manufacturing standards enforce rigorous containment validation for biopharmaceutical production. Aging chemical processing infrastructure requires replacement of legacy soft-seated isolation systems. Osaka and Tokyo pharmaceutical manufacturing zones concentrate demand for ultra-high purity valve specifications.
Isolator Valves Market Competitive Landscape
Top-tier vendors anchor premium pharmaceutical and chemical containment applications, while mid-tier fabricators compete on lead time and customization for industrial process markets. The competitive structure stratifies across three archetypes: diversified industrial conglomerates with valve divisions, specialized flow control pure-plays, and regional fabrication houses serving maintenance markets. Consolidation pressure intensifies as large pharmaceutical OEMs consolidate procurement authority and demand extended warranty terms. Strategic partnerships between valve suppliers and actuator manufacturers are accelerating smart diagnostics integration.
Among diversified industrial conglomerates, Emerson Electric Co., Flowserve Corporation, and IMI plc occupy positions representing distinct competitive vectors. Emerson exemplifies the digital ecosystem approach through predictive diagnostics platforms. Flowserve represents backward integration into specialty alloy supply chains. IMI anchors premium positioning through engineering subsidiaries focused on ultra-high purity applications.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Crane Co. |
| Schlumberger Limited |
| IMI plc |
| Weir Group PLC |
| KSB SE & Co. KGaA |
| Parker Hannifin Corporation |
| Spirax-Sarco Engineering plc |
| Others |
Supply & Pricing Matrix
Fluorspar price volatility cascades through PTFE-lining costs into three-tier pricing structure across premium, standard, and economy levels, with helium-certified metal-seated valves commanding specification premiums while commodity water-treatment units face margin compression from buyers consolidating procurement authority.
Pricing Analysis
Margin tightening in standard-grade stainless steel valves reflects REACH-driven elastomer requalification costs and extended certification timelines. Premium-mid-economy pricing differentiation separates metal-to-metal sealing architectures achieving 10⁻⁶ mbar·l/s helium leak rates from soft-seated alternatives and PVC-lined economy units. Cost-down pressure on mid-tier suppliers accelerates as pharmaceutical OEMs unbundle hardware from predictive maintenance subscriptions. Water treatment municipalities exhibit highest price sensitivity; cell and gene therapy manufacturers show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical buyer demand, while regional distributors serve maintenance-driven replacement markets. Specialty alloy supply concentrates in Germany, Japan, and the United States, drawing from limited foundry capacity for corrosion-resistant grades. Raw material inputs hinge on fluorspar concentrate, cobalt-bearing stainless formulations, and perfluoroelastomer precursors. Single-source vulnerability in European foundry capacity for 316L electropolished castings creates structural risk. Distribution runs through authorized valve service centers for validation documentation compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isolator valves market sits in a technology-transition phase, with smart actuation platforms bearing embedded pressure and temperature sensors displacing manual leak-testing protocols across continuous bioprocessing lines.
For Market Incumbents: To counter buyer consolidation among large pharmaceutical OEMs demanding extended warranty terms, anchor defensibility through backward integration into specialty alloy casting for corrosive service valves and deepen predictive diagnostics platform penetration to restructure relationships around performance guarantees rather than hardware transactions.
For New Entrants and Emerging Players: Capture white-space opportunity in India's CDSCO-aligned contract manufacturing organizations, where GMP infrastructure upgrades outpace established supplier capacity. Target radiopharmaceutical containment applications in hospital compounding pharmacies as ALARA principles drive remote-handling specifications. Lead with rapid orbital welding certification to bypass incumbent technician scarcity constraints.
For Investors and Strategic Acquirers: Distressed-cycle entries favor engineering subsidiaries with ultra-high purity biopharma capabilities in Germany, where REACH elastomer restrictions force requalification burdens on undercapitalized fabricators. Watch helium leak rate certification adoption curves as inflection indicator for premium valve architecture demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Diagnostics Platform Integration | Emerson's Plantweb ecosystem demonstrates recurring revenue capture from predictive maintenance subscriptions. |
| Specialty Alloy Backward Integration | Flowserve's captive foundry capacity insulates margin from European and Japanese supply concentration. |
| Ultra-High Purity Engineering Subsidiary Acquisition | IMI's Bimba unit captures cell and gene therapy surface finish premiums above 20 Ra microinches. |
| Orbital Welding Technician Certification Program | Biopharma production scaling constraints create first-mover advantage in qualified high-purity assembly capacity. |
| REACH-Compliant Elastomer Compound Portfolio Reformulation | Germany's chemical processing corridor faces immediate requalification burden as legacy inventories deplete. |
Research Methodology
Independent corroboration across valve procurement managers at pharmaceutical OEMs, maintenance directors at chemical processing facilities, and aftermarket service heads at regional distributors underwrites the qualitative findings. Primary interviews with plant engineers specifying containment infrastructure, GPO contracts managers consolidating hospital radiopharmaceutical procurement, and technical R&D directors qualifying sealing compounds combined with secondary validation from FDA guidance documents, EPA leak detection protocols, ECHA REACH substance restrictions, and SEC 10-K filings from listed flow control manufacturers. Bottom-up unit economics and top-down industry spend estimates triangulate market sizing.
Rate-of-change decomposition across product type, material grade, application regulatory stringency, and end-user procurement authority structures the analytical framework. Volume and value outputs reflect segment-level CAGRs derived from installed base replacement cycles, retrofit project pipelines, and new facility commissioning rates across the projection horizon. Modeled inputs include helium leak rate certification adoption curves, REACH compliance deadline impacts on elastomer formulation switches, and CDSCO GMP alignment progress in Indian contract manufacturing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to specialty alloy foundry capacity expansion, fluoropolymer raw material price trajectories, and regulatory divergence between FDA containment guidance and EU MDR traceability requirements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Flanges Market
Valves
Axial and Radial Seals Market
Valves
Global Valves in Chemical Market
Valves
Emergency Shutdown Valves Market
Valves
Global Plug Valve Market
Valves
Steel Cylinder Market
Valves
Global Fluid Management Systems Market
Valves
US Water & Wastewater Valves Market
Valves
Sanitary Valves Market
Valves
Global Globe Valve Market
Valves
Supply Stop Valves Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Europe Industrial Valves Market
Valves
Pipeline Pigging Equipment Market
Valves
Subsea Valves Market
Valves
Subsea Control System Market