
 Toothbrush Sanitizer Market | 2026-2036
Toothbrush Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Toothbrush Sanitizer Market Analytics
Portable UV-C certification tiers above 99.9 percent pathogen elimination is reorganizing the competitive landscape for premium placement. Koninklijke Philips N.V. leverages its medical-grade UV heritage to anchor credibility in clinical-adjacent household segments. Ningbo Seago Electric Co., Ltd dominates manufacturing scale, supplying private-label and branded channels across Asia and Europe. Tao Clean specializes in design-forward countertop formats that command shelf positioning in specialty retail.
A toothbrush sanitizer is a consumer hygiene device that employs UV-C light emission, ozone generation, thermal disinfection, or electrolytic action to reduce microbial load on toothbrush bristles and handles, typically operating within a sealed chamber for timed cycles of 60 to 120 seconds. Its primary commercial purpose is to mitigate oral-pathogen transmission risk in domestic and institutional settings where moisture retention encourages bacterial proliferation. UV Sanitizers occupy the dominant value position due to consumer familiarity and declining LED module costs, while Ozone Sanitizers represent the fastest-expanding technology segment as manufacturers seek differentiation beyond wavelength specifications. Dental Clinits within the End User dimension concentrate margin pools through bulk procurement and brand endorsement effects that cascade into household purchasing decisions.
The FDA regulates sanitization claims for devices marketed with medical-adjacent efficacy language in the United States, while the EU Green Deal and REACH frameworks in Europe constrain material composition and end-of-life disposal pathways for plastic-intensive housing designs. China's SAMR enforces GB standards for electrical safety and ozone emission thresholds that shape export eligibility for domestic manufacturers. Stakeholders must monitor divergence between regional efficacy-testing protocols and emerging restrictions on mercury-containing UV lamps as LED-based alternatives achieve cost parity.
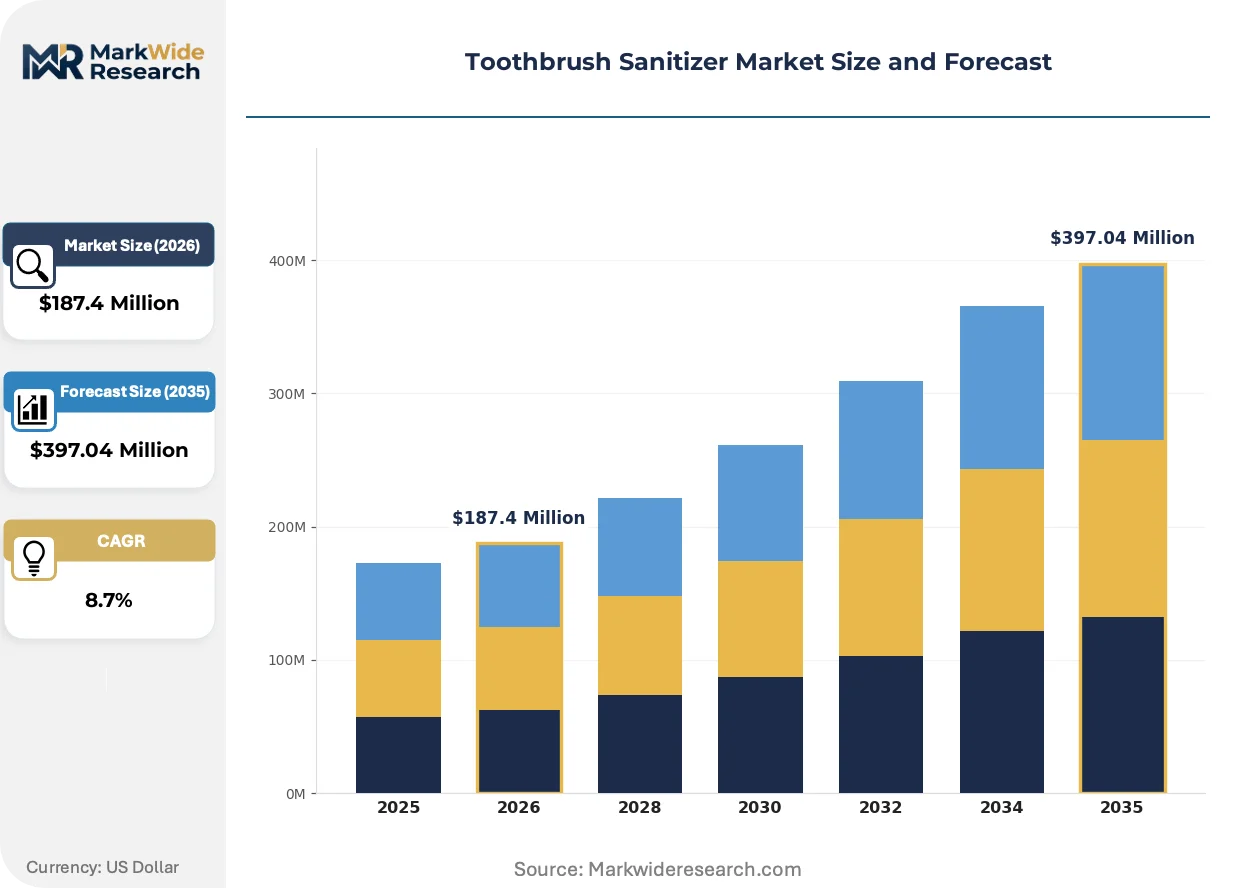
Market Dynamics
UV-C LED miniaturization is compressing unit costs below legacy mercury-lamp thresholds, unlocking household penetration while simultaneously fragmenting manufacturer margins across private-label and branded channels.
Growth Catalysts
- REACH Phase-Out Mandates:Europe's restriction on mercury-containing UV lamps accelerates LED module substitution, creating regulatory pull for solid-state sanitization hardware.
- Dental Clinic Procurement:Institutional bulk purchasing concentrates volume and generates brand endorsement effects that cascade into domestic consumer decisions.
- GB Standard Harmonization:China's SAMR electrical safety and ozone emission protocols streamline export eligibility for domestic manufacturers targeting Asia-Pacific distribution.
Market Restraints
- LED Module Cost Volatility:Semiconductor substrate pricing fluctuations constrain margin stability for mid-tier manufacturers dependent on imported chip supply.
- Private-Label Channel Concentration:Ningbo Seago Electric's manufacturing dominance concentrates supply risk within a single production cluster.
- Ozone Emission Thresholds:SAMR's GB standards impose technical ceilings on differentiation for ozone-based sanitization technologies.
Strategic Opportunities
- India Household Underpenetration:Oral hygiene device adoption remains nascent in urban Indian households, presenting first-mover positioning for countertop formats.
- UV-C and IoT Convergence:Sensor-enabled cycle tracking and usage analytics create subscription revenue potential beyond hardware margins.
- Specialty Retail Channel Expansion:Design-forward placement in apothecary and wellness chains commands price premiums unavailable through mass-market distribution.
Industry Challenges
- Photometric Calibration Expertise Gap:UV-C dosage verification requires specialized optical engineering talent scarce outside medical device and semiconductor industries.
- Multi-Jurisdiction Certification Timelines:FDA 510(k) pathways for medical-adjacent claims run parallel to EU MDR conformity assessments, extending time-to-revenue for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toothbrush Sanitizer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Sanitizers, Ozone Sanitizers, Heat Sanitizers, Chemical Sanitizers Technology: UV-C Light, Ozone Generation, Thermal Disinfection, Electrolytic Disinfection End User: Households, Dental Clinics, Hospitality, Health Institutions Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Ningbo Seago Electric Co., Ltd, Tao Clean, Koninklijke Philips N.V., UVNIA, Puretta, Conair, Wellness Oral Care, Pursonic, Dastmalchi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toothbrush Sanitizer Market Evolving Landscape
Sanitization hardware is diverging into clinical-grade certification tiers and design-forward lifestyle positioning, with technology choices increasingly signaling buyer identity rather than pure functional utility.
UV-C LED technology is bifurcating the competitive landscape into medical-grade efficacy claims and aesthetic-driven lifestyle products. Dental clinics and hygiene-conscious households are adopting 275nm wavelength modules at divergent price points. This split is compressing mid-tier positioning and forcing manufacturers to commit to either clinical credibility or design differentiation.
REACH substance restrictions and the EU Green Deal are constraining plastic-intensive housing designs and end-of-life disposal pathways. Manufacturers are responding with modular architectures and bio-based polymer substitution. Premium countertop formats face the steepest compliance cost escalation, accelerating material innovation investment.
Buyer preference is rotating toward visible efficacy verification and transparent cycle mechanics. Specialty retail and direct-to-consumer channels are displacing mass-market placement for premium-tier products. Germany and South Korea exhibit the strongest certification-driven purchasing behavior, with consumers prioritizing independent laboratory validation over brand heritage.
Toothbrush Sanitizer Market Segmentation
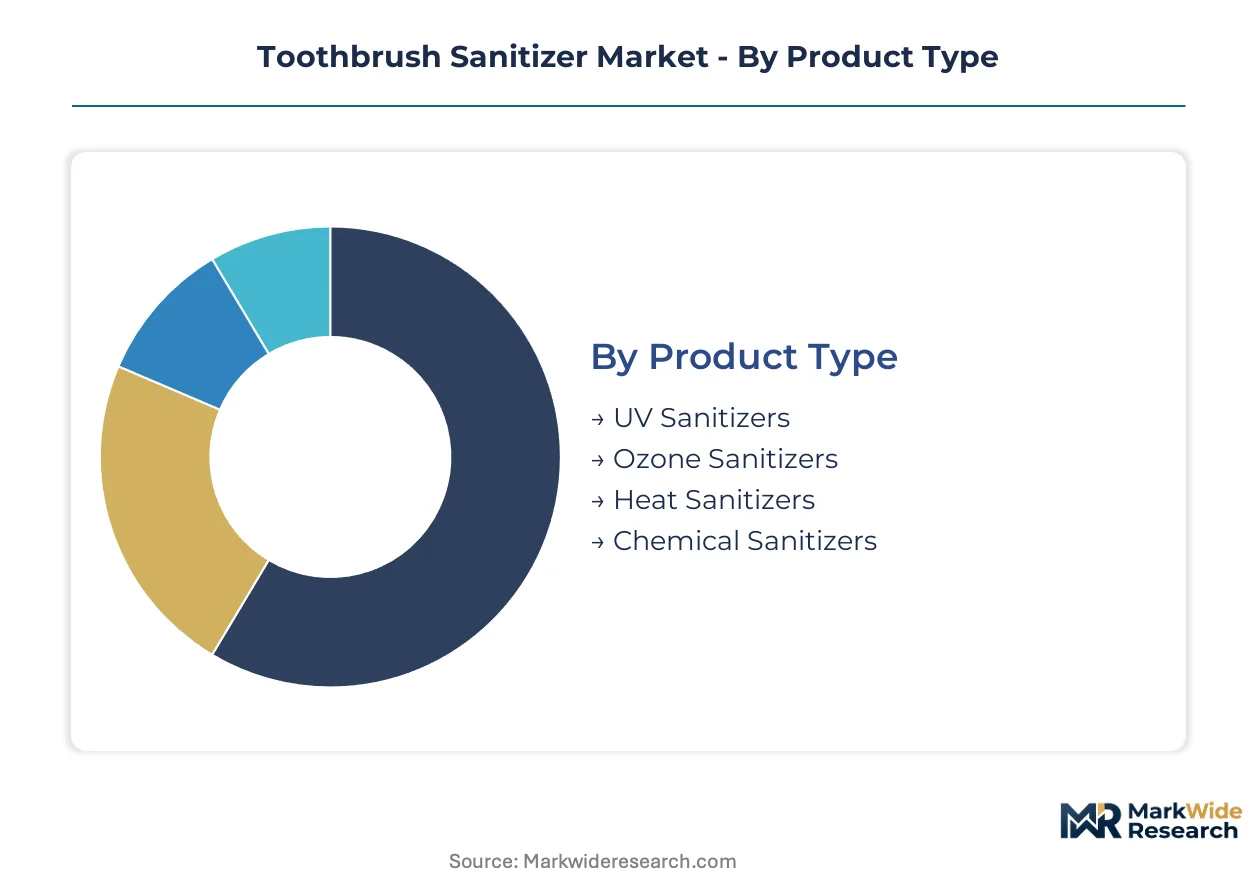
Segmentation in toothbrush sanitizers reveals how technology choices, procurement channels, and end-use contexts fragment margin capture across the value chain. Manufacturers must align R&D investment and distribution strategy with where pricing power actually concentrates.
Product Type:
Margin pools concentrate in UV-based formats where LED module cost compression has unlocked household penetration without collapsing premium positioning.
- UV Sanitizers:Solid-state 275nm LED modules dominate commercial volume due to consumer familiarity and declining semiconductor substrate costs. Dental clinics in Germany and South Korea drive specification-grade procurement that validates efficacy claims cascading into domestic premium tiers.
- Ozone Sanitizers:Corona-discharge and electrolytic ozone generation differentiate beyond wavelength specifications, though SAMR emission thresholds constrain technical ceilings. Hospitality procurement in China rotates toward these formats for chemical-free positioning in guest amenities.
- Heat Sanitizers:Thermal disinfection via resistive heating elements serves price-sensitive segments where UV module costs remain prohibitive.
- Chemical Sanitizers:Antimicrobial rinse solutions and tablet-based systems occupy travel-format niches with minimal hardware attachment.
UV Sanitizers hold installed capacity. Ozone Sanitizers is rotating up the share rankings.
Technology:
Technology selection determines regulatory pathway complexity and certification timeline duration across FDA, REACH, and GB standard jurisdictions.
- UV-C Light:Mercury-vapor lamp phase-out under REACH mandates accelerates LED substitution, with 275nm solid-state modules achieving cost parity. Philips leverages medical-grade heritage to anchor clinical-adjacent credibility.
- Ozone Generation:Electrolytic and corona-discharge methods expand fastest as manufacturers seek differentiation beyond photometric specifications. China's SAMR enforces strict emission thresholds shaping export eligibility.
- Thermal Disinfection:Resistive heating elements serve economy-tier positioning where semiconductor supply volatility disrupts UV-C LED availability.
- Electrolytic Disinfection:In-situ hypochlorous acid generation from salt water appeals to chemical-averse households in water-scarce regions.
UV-C Light commands specification-grade procurement. Ozone Generation is climbing the fastest among emerging technology segments.
End User:
End-user concentration determines whether volume scales through institutional procurement or fragments across dispersed household decision-making.
- Households:Countertop and portable formats dominate as hygiene protocol integration accelerates in daily routines. Urban Indian households present first-mover positioning opportunities for design-forward formats.
- Dental Clinics:Bulk procurement concentrates margin pools and generates endorsement effects that cascade into domestic purchasing decisions across Germany and South Korea.
- Hospitality:Guest amenity specifications in China and UAE drive ozone-format adoption for chemical-free positioning.
- Health Institutions:Hospital procurement remains nascent due to competing sterilization infrastructure and infection control protocols.
Dental Clinics anchor premium pricing validation. Households is expanding most quickly as LED cost compression unlocks mass-market penetration.
Distribution Channel:
Channel selection determines whether manufacturers capture design premiums or compete on logistics efficiency and trade terms.
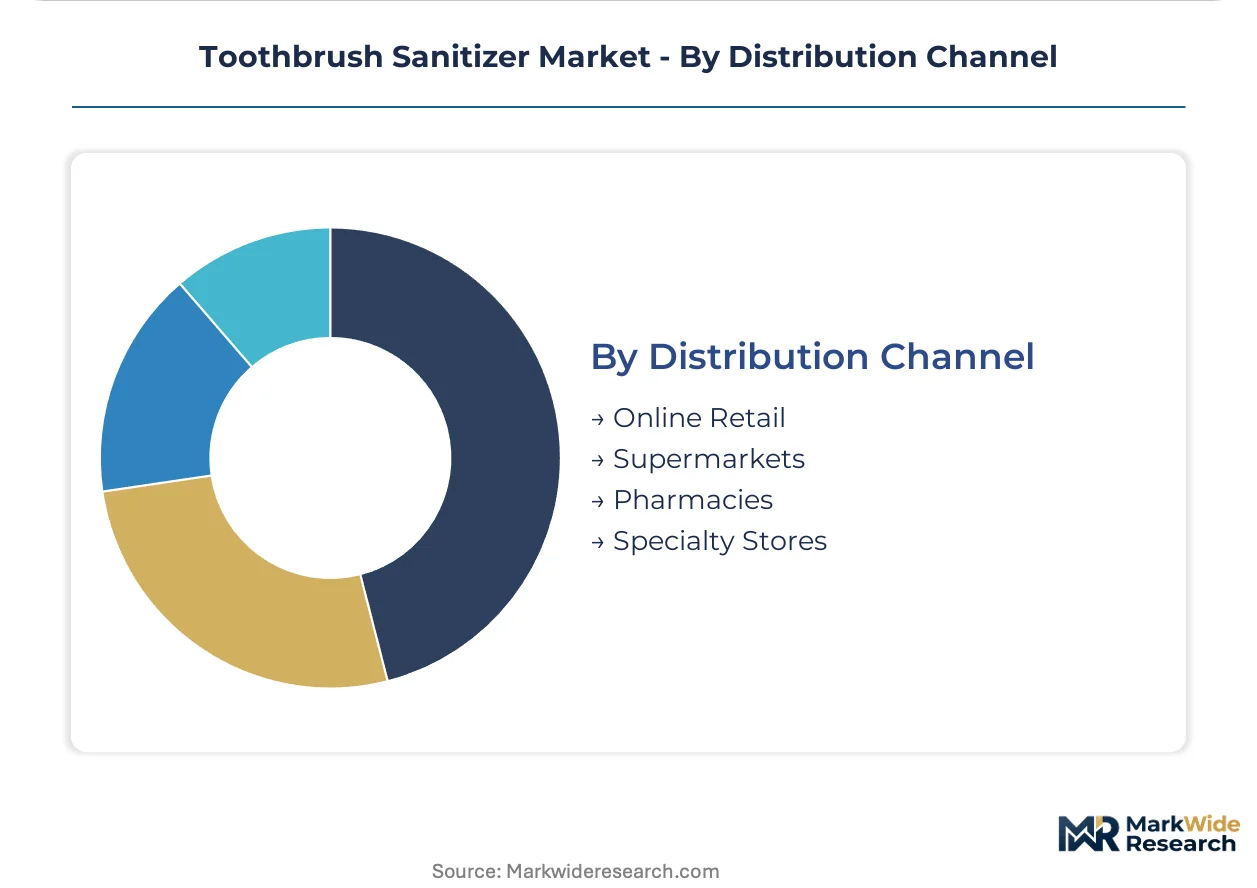
- Online Retail:Direct-to-consumer platforms enable specification transparency and independent laboratory validation display that commands price premiums unavailable through mass-market placement.
- Supermarkets:Mass-market shelf space concentrates volume for private-label suppliers like Ningbo Seago Electric, compressing branded margin potential.
- Pharmacies:Apothecary and wellness chain placement in Germany validates clinical-adjacent efficacy claims through pharmacist endorsement.
- Specialty Stores:Design-forward positioning in lifestyle and wellness chains commands shelf premiums for aesthetic-driven formats from Tao Clean and comparable specialists.
Supermarkets hold volume throughput. Online Retail is gaining share fastest as verification-transparent purchasing displaces mass-market discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export eligibility hinges on divergent certification timelines across major demand centers. China's manufacturing clusters supply private-label volume to European and North American distributors while domestic consumption concentrates in premium-tier urban households. Import-dependent markets in South Asia and the Middle East rotate toward ozone-format alternatives as UV-C LED module costs compress.
China
SAMR enforces GB standards for electrical safety and ozone emission thresholds that shape both domestic placement and export certification. Ningbo and Shenzhen manufacturing clusters dominate private-label production for European and North American distribution channels. Yangtze River Delta fabricators supply UV-C LED modules at declining unit costs.
Germany
REACH substance restrictions and the EU Green Deal constrain plastic-intensive housing designs while accelerating mercury-lamp phase-out. Apothecary channel placement validates clinical-adjacent efficacy claims through pharmacist endorsement. Bavaria concentrates premium-tier procurement from dental clinic networks.
South Korea
MFDS certification requirements and K-BEAUTY hygiene protocol integration drive specification-grade household adoption. Seoul Capital Area households prioritize independent laboratory validation over brand heritage. Gyeonggi-do manufacturing clusters serve domestic demand and regional export to Southeast Asia.
United States
FDA 510(k) pathways for medical-adjacent claims extend time-to-revenue for new entrants while EPA ozone emission guidelines shape product formulation. California and New York metro areas concentrate design-forward countertop format demand. Texas and Florida distribution hubs handle mass-market logistics for private-label imports.
India
BIS electrical safety certification and DGFT import tariff structures constrain price-sensitive household penetration. Maharashtra and Karnataka urban centers present first-mover positioning for countertop formats as oral hygiene device adoption accelerates. Delhi-NCR dental clinic procurement generates endorsement effects for domestic premium tiers.
Toothbrush Sanitizer Market Competitive Landscape
Listed leaders compete with private specialists across certification credibility and manufacturing scale. The vendor base splits between medical-grade heritage anchors and design-forward lifestyle specialists, with private-label fabricators occupying the mid-tier volume position. Three archetypes dominate: clinical-credibility anchors, manufacturing-scale private-label suppliers, and aesthetic-driven premium specialists. Competitive moves concentrate on M&A for technology access and capacity expansion in Ningbo and Shenzhen production clusters.
Within the manufacturing-scale tier, Ningbo Seago Electric Co., Ltd exemplifies private-label dominance across Asian and European distribution channels. Tao Clean occupies a position among design-forward specialists commanding shelf premiums in specialty retail. Koninklijke Philips N.V. anchors the clinical-credibility archetype through medical-grade UV heritage. These three representations capture the structural divergence between specification-grade procurement and aesthetic-driven household purchasing.
| Leading Market Players |
|---|
| Ningbo Seago Electric Co., Ltd |
| Tao Clean |
| Koninklijke Philips N.V. |
| UVNIA |
| Puretta |
| Conair |
| Wellness Oral Care |
| Pursonic |
| Dastmalchi |
| Others |
Value Network & Pricing Analysis
FDA 510(k) certification pathways gate both supply qualification and price differentiation simultaneously, with medical-adjacent efficacy claims commanding premiums while extending time-to-revenue for manufacturers lacking clinical heritage. This regulatory filtering compresses mid-tier positioning and forces supply chain decisions toward either premium validation or volume efficiency.
Pricing Analysis
Dental clinic procurement anchors a three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale as primary differentiation drivers. Price erosion runs through private-label supermarket channels as Ningbo Seago Electric's manufacturing dominance compresses branded margin potential. Household buyers exhibit highest price sensitivity, while dental clinics prioritize independent laboratory validation over cost.
Supply Chain Analysis
Yangtze River Delta LED module fabrication anchors supply concentration across China, South Korea, and Germany, with semiconductor substrate sourcing from Taiwan and Japan creating upstream dependencies. Single-source vulnerability concentrates in Ningbo manufacturing clusters serving private-label volume. Distribution runs through supermarket mass-market channels for economy tiers and specialty retail for premium placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The toothbrush sanitizer market is recovering from semiconductor supply cyclicality as UV-C LED substrate pricing normalizes and household penetration accelerates.
For Market Incumbents: Compound clinical credibility through MFDS and FDA dual-certification investment to defend against ozone-format entrants seeking differentiation beyond wavelength specifications. Deepen backward integration into 275nm LED module sourcing to offset semiconductor substrate volatility disrupting mid-tier margins.
For New Entrants and Emerging Players: Subscription-enabled cycle tracking and usage analytics represent a service-layer gap where incumbents under-serve hygiene-conscious households. Urban Indian households present the most penetrable geography for design-forward countertop formats through direct-to-consumer validation display.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ozone-generation technology as electrolytic methods achieve manufacturing scale. Acquisition targets should screen for modular architecture capabilities enabling REACH compliance without complete product redesign. The signal to watch is SAMR emission threshold tightening that would obsolete corona-discharge inventory.
| Strategic Initiative | Industry Significance |
|---|---|
| UV-C LED Module Backward Integration | Captive semiconductor supply from Yangtze River Delta fabricators insulates margin from substrate volatility. |
| MFDS-FDA Dual Certification Pathway | Dual regulatory validation unlocks premium placement in Seoul Capital Area and California metro demand clusters. |
| IoT-Enabled Subscription Layer Launch | Sensor-enabled cycle tracking creates recurring revenue beyond hardware margins in hygiene-conscious households. |
| Specialty Retail Channel Expansion | Apothecary placement in Germany validates clinical-adjacent claims through pharmacist endorsement effects. |
| Bio-Based Polymer Housing Transition | Modular architectures with bio-based substitution preempt REACH plastic-intensive design restrictions. |
Research Methodology
Cross-validation between primary interviews with dental clinic procurement managers, UV-C LED module engineers, and specialty retail category buyers anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, SAMR GB standard publications, and EU REACH substance restriction updates. Bottom-up demand modeling triangulates against top-down manufacturing capacity estimates from Ningbo and Shenzhen production clusters.
Sensitivity analysis around semiconductor substrate pricing and regulatory timeline compression shapes the analytical framework across the analysis window. Segmentation dimensions span sanitization technology, end-user procurement context, and distribution channel format. CAGRs derive from installed base penetration curves and replacement cycle assumptions calibrated against dental clinic bulk procurement patterns.
Forecasts assume regulatory continuity in FDA, REACH, and SAMR regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as mercury-lamp phase-out deadlines and LED cost parity inflection evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Elderly Walker Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Nursing Products Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Isolation Gowns Market