
 Contraceptive Sponges Market | 2026-2036
Contraceptive Sponges Market Size, Share, and Industry Trends Forecast 2026-2036
Contraceptive Sponges Market Outlook
Multi-pack bundling with spermicide refills is hardening as the dominant retail configuration, replacing single-unit purchases in pharmacies and online channels. Mayer Laboratories leverages its brand strength to sustain shelf presence across North American drugstore chains. Innothera anchors European distribution through pharmacy-exclusive positioning, while SheCare competes on direct-to-consumer subscription models that bypass traditional retail markups.
A contraceptive sponge is a soft, porous device typically manufactured from polyurethane foam or natural sea sponge material, impregnated with spermicide such as nonoxynol-9 and designed for vaginal insertion prior to intercourse to block and chemically immobilize sperm. Foam sponges dominate unit volume due to established manufacturing scale and lower per-unit production costs, though biodegradable sponges represent the fastest-growing product type as environmental regulations tighten plastic content restrictions across the European Union. Distribution through pharmacies still captures the largest margin pool because of pharmacist counseling requirements and insurance reimbursement pathways, while online retail is displacing supermarket channels among younger demographics seeking privacy.
The FDA regulates contraceptive sponges as Class II medical devices requiring premarket notification, while the EU Medical Device Regulation mandates notified body certification and post-market surveillance for all vaginal barrier products sold in member states. India's Central Drugs Standard Control Organization enforces spermicide potency testing and packaging label standards that determine import eligibility and domestic manufacturing licenses. Stakeholders must monitor evolving OTC switching pathways and biodegradability certification standards as these frameworks increasingly determine which product formats gain shelf access and reimbursement eligibility.
Market Dynamics
Biodegradable polyurethane formulations are rewriting material specifications as EU plastic restrictions tighten, forcing manufacturers to requalify supply chains and recertify products under MDR notified body oversight.
Growth Catalysts
- CDSCO spermicide potency standards:India's Central Drugs Standard Control Organization mandates uniform testing protocols that streamline import eligibility for barrier contraceptives, accelerating product registration timelines for foreign manufacturers.
- Clinic network densification:Government-funded reproductive health programs in low-resource settings are expanding physical distribution infrastructure, placing subsidized products within walking distance of previously underserved populations.
- Nonoxynol-9 microencapsulation:Advanced spermicide delivery systems extend effective protection windows and reduce irritation profiles, improving user compliance rates among sensitive demographics.
Market Restraints
- Polyether polyol price volatility:Foam sponge manufacturers face margin compression from petrochemical feedstock fluctuations, with no viable near-term bio-based alternatives at equivalent production scale.
- Single-supplier spermicide concentration:Three chemical producers control nonoxynol-9 active pharmaceutical ingredient supply, creating vulnerability to production interruptions or quality enforcement actions.
- Latex allergy substitution threat:Polyisoprene and nitrile barrier alternatives capture users with polyurethane sensitivity, fragmenting the non-hormonal contraceptive category.
Strategic Opportunities
- Direct-to-consumer subscription channels:Privacy-seeking younger demographics bypass pharmacy counseling requirements through automated replenishment models, capturing margin previously allocated to retail intermediaries.
- FDA OTC switching pathway:The over-the-counter reclassification framework for hormonal and non-hormonal methods creates precedent for expanded retail availability without prescription barriers.
- Biodegradable certification premiums:TUV Austria and BPI compostability standards enable price stratification against conventional foam products in environmentally regulated jurisdictions.
Industry Challenges
- MDR post-market surveillance compliance:EU Medical Device Regulation mandates ongoing clinical follow-up and adverse event reporting that strains quality management systems of smaller manufacturers.
- Sterilization validation capex:Gamma irradiation or ethylene oxide terminal sterilization requires dedicated facility investment or contract sterilizer relationships with extended lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contraceptive Sponges Market |
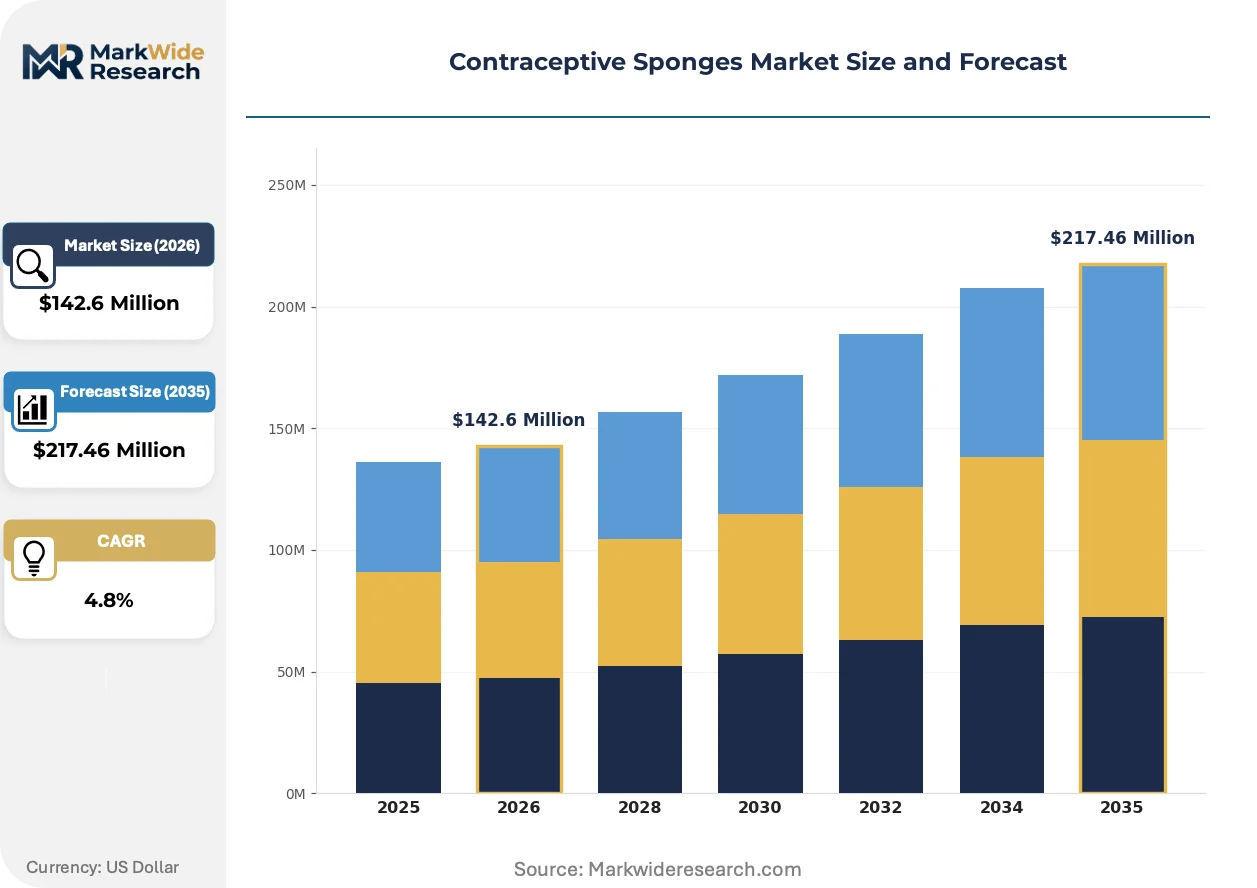
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $217.46 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Sponges, Non-Foam Sponges, Biodegradable Sponges, Traditional Sponges Distribution Channel: Pharmacies, Online Retail, Supermarkets, Clinics End User: Women, Health Clinics, Hospitals, Family Planning Centers Price Tier: Economical, Mid-Range, Premium, Luxury |
| Companies Covered | Mayer Laboratories, Inc., Tree of Life Pharma Ltd., Innothera, Bayer AG, CooperSurgical, Inc., Alvogen, SheCare, GTSimulators, Instacart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contraceptive Sponges Market Strategic Shifts
Material science advances and regulatory pathway evolution are converging to reshape product formats, distribution access, and user engagement models across the contraceptive sponge category.
Plant-derived polyurethane from castor oil feedstocks is rewriting biodegradability benchmarks for vaginal barrier products. German chemical specialists have scaled pilot production to commercial volumes, supplying device manufacturers seeking TUV Austria compostability certification. This material transition is compressing product development cycles as brands race to secure shelf placement ahead of 2027 EU single-use plastic restrictions.
REACH microplastics restrictions are forcing reformulation of conventional foam sponges containing synthetic polymer fragments. The European Chemicals Agency enforcement timeline requires notified body recertification for existing products, diverting technical resources from innovation pipelines. Manufacturers with early biodegradable registrations are capturing pharmacy shelf space as distributors anticipate compliance-driven assortment changes.
Subscription-based replenishment is displacing episodic pharmacy purchasing among urban millennials and Gen Z users. Digital health platforms bundle contraceptive sponges with telehealth consultations and cycle tracking applications, consolidating previously fragmented wellness spending. This channel shift concentrates most visibly in North American metropolitan markets where insurance reimbursement for over-the-counter methods remains limited.
Contraceptive Sponges Market Segmentation
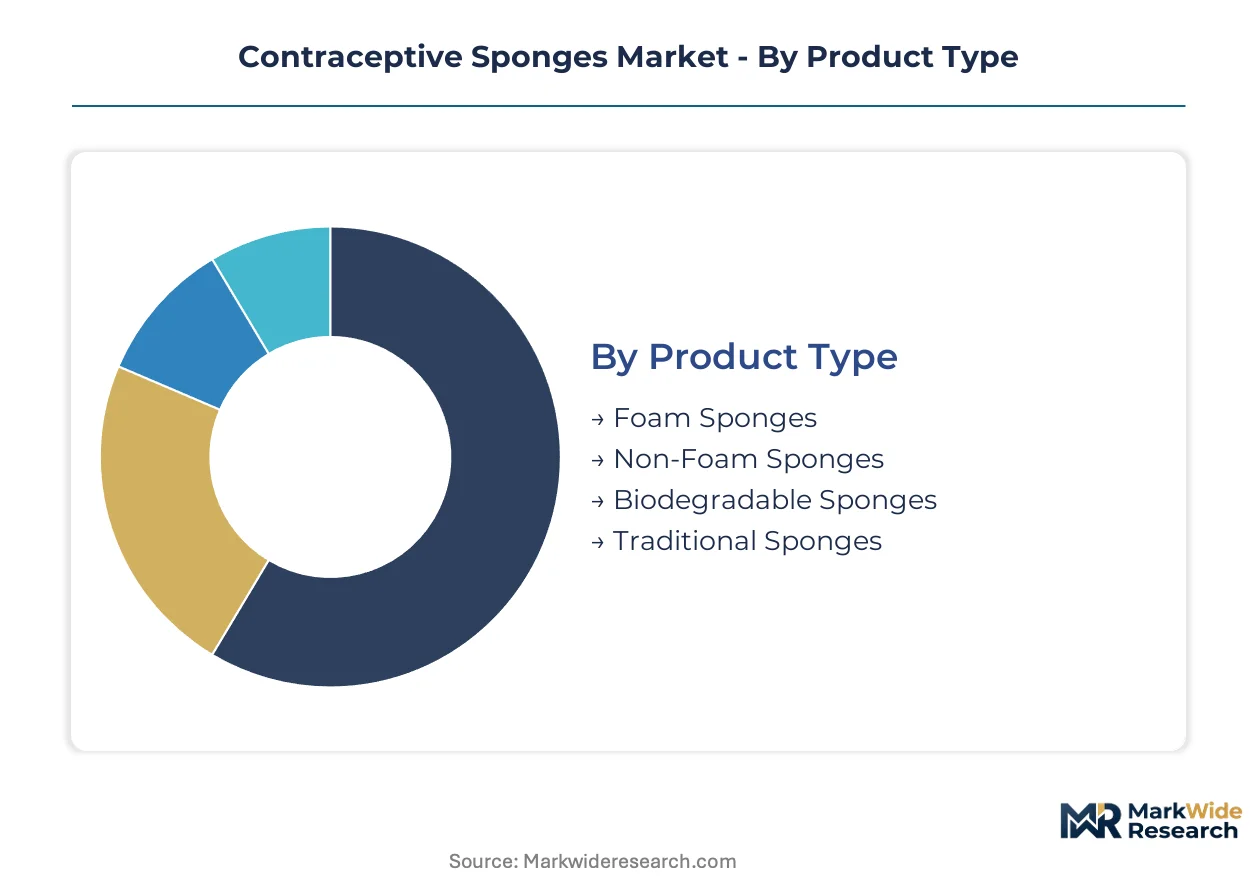
Product format diversity and channel fragmentation create distinct margin pools across the contraceptive sponge category. Material composition, sterility requirements, and reimbursement pathways segment manufacturing capabilities and competitive positioning.
Product Type:
Standardization dominates foam-based manufacturing while biodegradable variants demand specialized feedstock qualification and compostability certification.
- Foam Sponges:Manufactured from polyurethane foam impregnated with nonoxynol-9 spermicide, these devices leverage established injection molding and foam expansion processes. Demand concentrates in India through government-funded reproductive health programs distributing subsidized units via public health infrastructure, constrained by polyether polyol price volatility from petrochemical feedstock fluctuations.
- Biodegradable Sponges:Plant-derived polyurethane from castor oil feedstocks enables TUV Austria compostability certification ahead of EU single-use plastic restrictions. German chemical specialists have scaled pilot production to commercial volumes, with manufacturers racing to secure pharmacy shelf placement before enforcement timelines tighten.
- Non-Foam Sponges:Alternative barrier materials including natural sea sponge derivatives serve niche sensitivity markets.
- Traditional Sponges:Early-generation products without integrated spermicide delivery persist in limited regional markets.
Leading the category by volume: Foam Sponges. Expanding most quickly: Biodegradable Sponges.
Distribution Channel:
Channel selection determines margin capture, with counseling requirements and reimbursement pathways fragmenting access models.
- Pharmacies:Pharmacist counseling requirements and insurance reimbursement pathways sustain the largest margin pool. Innothera anchors European distribution through pharmacy-exclusive positioning, capturing premium placement through notified body certification under EU MDR.
- Online Retail:Privacy-seeking younger demographics bypass pharmacy counseling through automated replenishment models. SheCare competes on direct-to-consumer subscription formats that bypass traditional retail markups, concentrating in North American metropolitan markets where OTC reimbursement remains limited.
- Supermarkets:Mass-market accessibility without professional guidance captures price-sensitive episodic purchasers.
- Clinics:Government-funded programs in low-resource settings place subsidized products within walking distance of underserved populations.
Capturing highest margins: Pharmacies. Displacing supermarket channels fastest: Online Retail.
End User:
User type dictates sterility validation requirements and procurement authority structures.
- Women:Individual consumers drive direct-to-consumer channel growth through privacy-seeking purchasing behavior.
- Health Clinics:Institutional procurement with bulk purchasing power and sterilization validation requirements.
- Hospitals:Gamma irradiation or ethylene oxide terminal sterilization mandates strain quality management systems.
- Family Planning Centers:Government-funded infrastructure expansion targets underserved populations with subsidized distribution.
Procurement authority concentrates with: Health Clinics. Fastest channel shift: Women via subscription models.
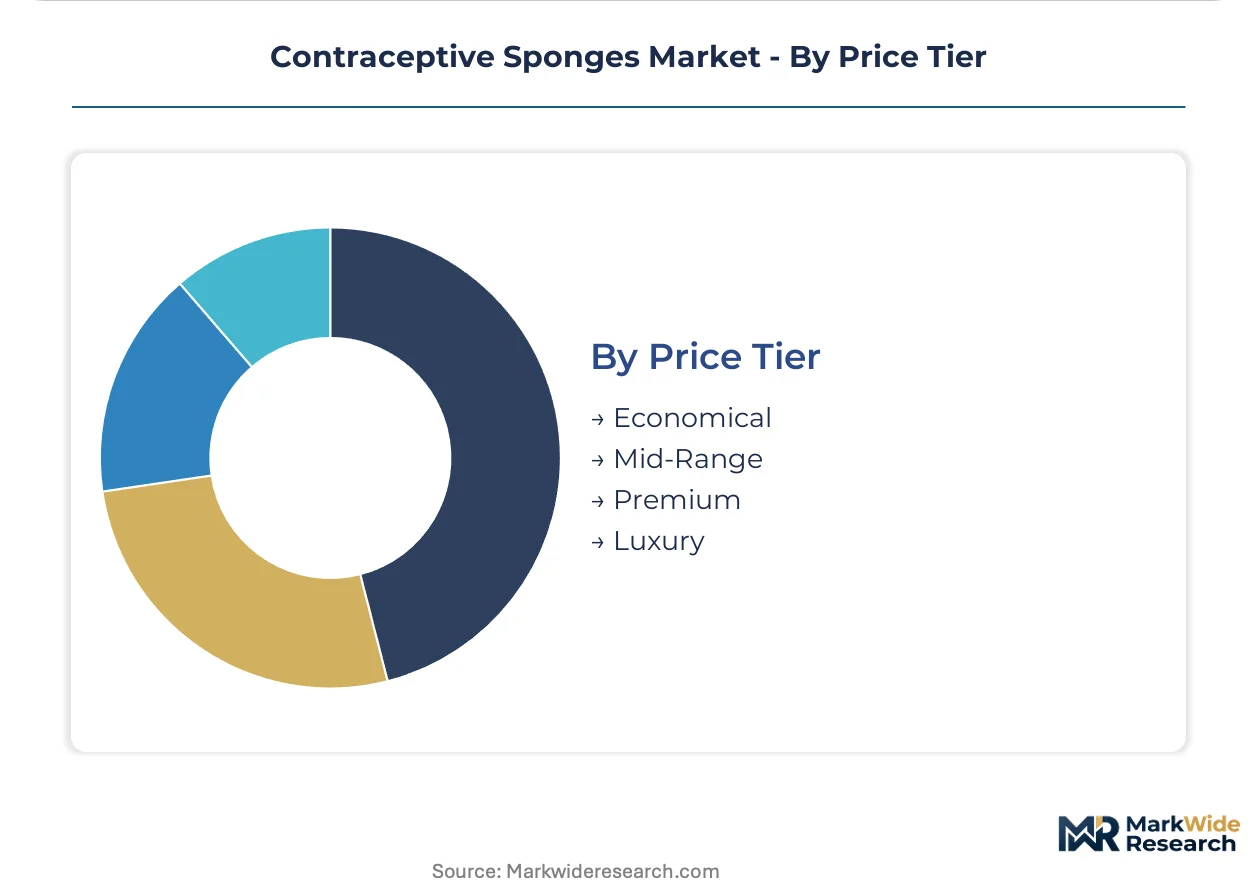
Price Tier:
Certification grade and material composition stratify pricing architecture across retail and institutional channels.
- Premium:Biodegradable certification and EU MDR notified body compliance enable price stratification against conventional foam products.
- Mid-Range:Standard foam sponges with established spermicide potency testing dominate pharmacy shelf presence.
- Economical:Government-subsidized products distributed through public health infrastructure in India and comparable markets.
- Luxury:Limited positioning through specialized wellness platforms bundling telehealth consultations.
Volume concentration: Economical tier via subsidized programs. Steepest expansion trajectory: Premium tier on biodegradability certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and India while consumption concentrates in subsidized distribution networks across South Asia and direct-to-consumer channels in North America. Regulatory divergence between FDA OTC pathways and EU MDR certification timelines fragments product registration strategies. Sub-regional variation in reimbursement policy determines which material formats achieve sustainable shelf placement.
United States
Direct-to-consumer subscription models capture privacy-seeking millennials in metropolitan markets. FDA Class II medical device oversight maintains pharmacist counseling requirements for pharmacy distribution. Mayer Laboratories sustains shelf presence across national drugstore chains through established brand equity.
Germany
REACH microplastics enforcement accelerates biodegradable polyurethane adoption ahead of 2027 restrictions. EU Medical Device Regulation mandates notified body recertification for conventional foam products. Chemical specialists in the Rhine-Ruhr region scale castor oil-derived feedstocks to commercial volumes.
India
Government-funded reproductive health programs distribute subsidized foam sponges through public health infrastructure. CDSCO spermicide potency testing streamlines import eligibility for foreign manufacturers. Mumbai and Delhi manufacturing clusters supply domestic demand while targeting export registration.
France
Pharmacy-exclusive positioning captures premium margins through professional counseling requirements. ANSM vigilance reporting integrates with EU MDR post-market surveillance mandates. Lyon-based distributors anticipate assortment shifts toward compostability-certified alternatives.
United Kingdom
Online retail displacement of supermarket channels concentrates among urban demographics seeking discretion. MHRA recognition of EU MDR certifications maintains transitional market access for continental suppliers. London health tech platforms bundle barrier contraceptives with telehealth consultation services.
Contraceptive Sponges Market Competitive Environment
The competitive structure tilts toward brand-dependent incumbents with established pharmacy networks rather than manufacturing-scale leaders. Three archetypes dominate: multinational pharmaceutical diversifiers with regulatory affairs depth, regional pharmacy-channel specialists with notified body certifications, and direct-to-consumer challengers with subscription infrastructure. Competitive moves concentrate on biodegradable material requalification and MDR recertification timelines rather than capacity expansion.
Among North American brand holders, Mayer Laboratories and SheCare occupy distinct positioning vectors. Mayer Laboratories exemplifies the pharmacy-dependent incumbent archetype with sustained shelf presence across drugstore chains. SheCare represents the direct-to-consumer challenger model with subscription-based replenishment that bypasses traditional retail markups. Innothera anchors the European specialist tier through pharmacy-exclusive distribution under EU MDR compliance.
| Leading Market Players |
|---|
| Mayer Laboratories, Inc. |
| Tree of Life Pharma Ltd. |
| Innothera |
| Bayer AG |
| CooperSurgical, Inc. |
| Alvogen |
| SheCare |
| GTSimulators |
| Instacart |
| Others |
Value Chain & Pricing Dynamics
Polyether polyol feedstock costs cascade through foam sponge manufacturing tiers, compressing margins at the economical end while biodegradable castor oil alternatives command certification premiums in EU-regulated channels.
Pricing Analysis
Margin tightening in the economical tier reflects petrochemical input volatility and concentrated government procurement in India. Three-tier pricing structure across premium, standard, and economy levels stratifies by biodegradability certification and EU MDR compliance status. Price differentiation hinges on TUV Austria compostability credentials and notified body certification investment. Clinic networks exhibit lowest price sensitivity due to subsidized program funding, while direct-to-consumer subscribers absorb premium positioning for privacy and convenience.
Supply Chain Analysis
Returns and quality failure flows remain minimal given single-use device classification, though batch recall protocols strain German and Indian manufacturing nodes. Supply concentrates in Germany for castor oil-derived polyurethane and India for conventional foam expansion. Raw material dependencies span nonoxynol-9 API from three chemical producers, gamma irradiation sterilization services, and REACH-compliant foam formulations. Single-source spermicide concentration creates vulnerability to production interruptions. Distribution runs through pharmacy wholesale networks in Europe, direct fulfillment centers in North America, and government logistics infrastructure in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contraceptive sponge category is executing a material-transition phase as plant-derived polyurethane displaces petrochemical foam feedstocks ahead of EU single-use plastic enforcement.
For Market Incumbents: Cement pharmacy shelf presence through early MDR recertification completion before 2027 compliance deadlines strand conventional foam inventory. Secure backward integration into castor oil feedstock supply through German chemical specialist partnerships to defend margin position against biodegradable certification cost inflation. Prioritize notified body relationship investment over capacity expansion. For New Entrants and Emerging Players: FDA OTC switching pathway in the United States opens a window for direct-to-consumer subscription models that bypass incumbent pharmacy networks. Target privacy-seeking millennial demographics in metropolitan markets with automated replenishment bundled with telehealth services. Pursue white-space registration in CDSCO streamlined import categories for barrier contraceptives. For Investors and Strategic Acquirers: First commercial TUV Austria compostability certification among mid-tier manufacturers is the leading indicator that biodegradable product lines will capture pharmacy assortment slots ahead of enforcement timelines. Position acquisition screening around EU MDR compliance depth and castor oil supply contracts rather than foam capacity scale. Monitor ECHA microplastics restriction implementation pace for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Transition | Castor oil-derived polyurethane secures TUV Austria certification ahead of EU plastic restrictions. |
| MDR Recertification Completion | Notified body approval maintains pharmacy channel access under tightened post-market surveillance. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures margin from privacy-seeking demographics in reimbursement-limited markets. |
| CDSCO Import Registration | Streamlined spermicide potency testing accelerates market entry into government-funded Indian distribution. |
| Nonoxynol-9 Microencapsulation R&D | Extended protection windows improve user compliance and differentiate against latex barrier substitutes. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced with primary interviews spanning regulatory affairs directors at notified bodies, procurement managers at government family planning programs, pharmacy category buyers, biomedical engineers at sterilization facilities, and supply chain planners at polyurethane feedstock producers. Bottom-up demand modeling from clinic distribution volumes and prescription audit data triangulated against top-down macroeconomic indicators.
Granularity-level modeling segmented volume and value outputs by material composition, distribution channel, price tier, and end-user procurement authority across the projection horizon. CAGRs derived from regression analysis against historical regulatory approval timelines and subsidy program expansion rates. Forecast inputs incorporated EU MDR transition pacing, CDSCO registration velocity, and petrochemical feedstock price elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for biodegradable polyurethane scale-up would alter the outlook if German chemical specialists fail to achieve commercial volume targets. Practitioners should monitor ECHA enforcement timeline announcements and FDA OTC switching precedent decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Nursing Products Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Ejiao Health Products Market