
 Nursing Products Market | 2026-2036
Nursing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Nursing Products Market Intelligence
Subscription-based firmware upgrades for wearable breast pumps is decoupling hardware margins from recurring revenue streams. Elvie leverages in-house app ecosystems to sustain direct-to-consumer engagement beyond the initial device purchase. Medela anchors professional-grade pump rentals through hospital discharge programs, while Lansinoh competes in retail pharmacy channels with disposable nursing pad assortments.
Nursing products encompass medical-grade devices, disposable supplies, and digital health tools engineered for lactation support, wound management, and patient monitoring in clinical and home settings. Silicone valve assemblies in electric pumps must maintain negative pressure between 150 and 250 mmHg per ISO 60601 safety specifications for neonatal care applications. Patient monitoring equipment leads absolute revenue contribution among product type segments, reflecting capital intensity and replacement cycles in acute care settings. Telehealth solutions within the technology dimension represent the fastest-expanding margin pool, as remote lactation consulting and post-operative monitoring shift reimbursement toward per-session software licensing.
FDA 510(k) clearances govern wearable breast pump classifications in the United States, while the EU MDR and CE marking requirements extend conformity assessment obligations for electrical medical devices sold in Europe. Health Canada and the TGA enforce parallel standards that shape export timelines for manufacturers seeking multi-jurisdiction approvals. Stakeholders must monitor evolving digital therapeutics designations, as regulators in multiple geometries weigh whether app-connected nursing devices qualify for separate software-as-medical-device pathways.
Market Dynamics
Value-based reimbursement frameworks are compressing procurement cycles for connected nursing devices, forcing manufacturers to bundle software licensing with hardware sales to capture recurring revenue streams.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearances for wearable lactation devices in the United States are shortening commercialization timelines from 18 months to under 12 months for qualified submissions.
- German statutory coverage expansion:Statutory health insurance reimbursement for breastfeeding support devices drives above-average household penetration rates compared to neighboring markets.
- Silicone valve precision manufacturing:Advances in medical-grade silicone molding enable consistent negative pressure performance between 150 and 250 mmHg per ISO 60601 specifications.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer supply chains concentrate among three dominant chemical suppliers, exposing pump manufacturers to input cost volatility.
- EU MDR conformity assessment bottlenecks:Extended notified body capacity constraints delay CE marking timelines for electrical nursing devices by 6-9 months versus pre-2021 baselines.
- Manual expression persistence:Zero-cost manual breastfeeding techniques remain prevalent in price-sensitive segments, limiting addressable market expansion for powered devices.
Strategic Opportunities
- Telehealth lactation consulting:Per-session software licensing models for remote breastfeeding support create new margin pools outside device hardware sales.
- Home care provider consolidation:Aggregated procurement by multi-state home health networks enables direct vendor relationships bypassing traditional distribution.
- Digital therapeutics designation pathways:Regulatory frameworks in the United States and Europe are converging on software-as-medical-device classifications for app-connected pumps.
Industry Challenges
- Biomedical firmware engineering scarcity:Cross-functional talent combining IEC 62304 software lifecycle expertise with lactation physiology knowledge commands premium compensation.
- Multi-jurisdiction approval synchronization:Parallel FDA, Health Canada, and TGA submissions require dedicated regulatory affairs capacity without guaranteed alignment of review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nursing Products Market |
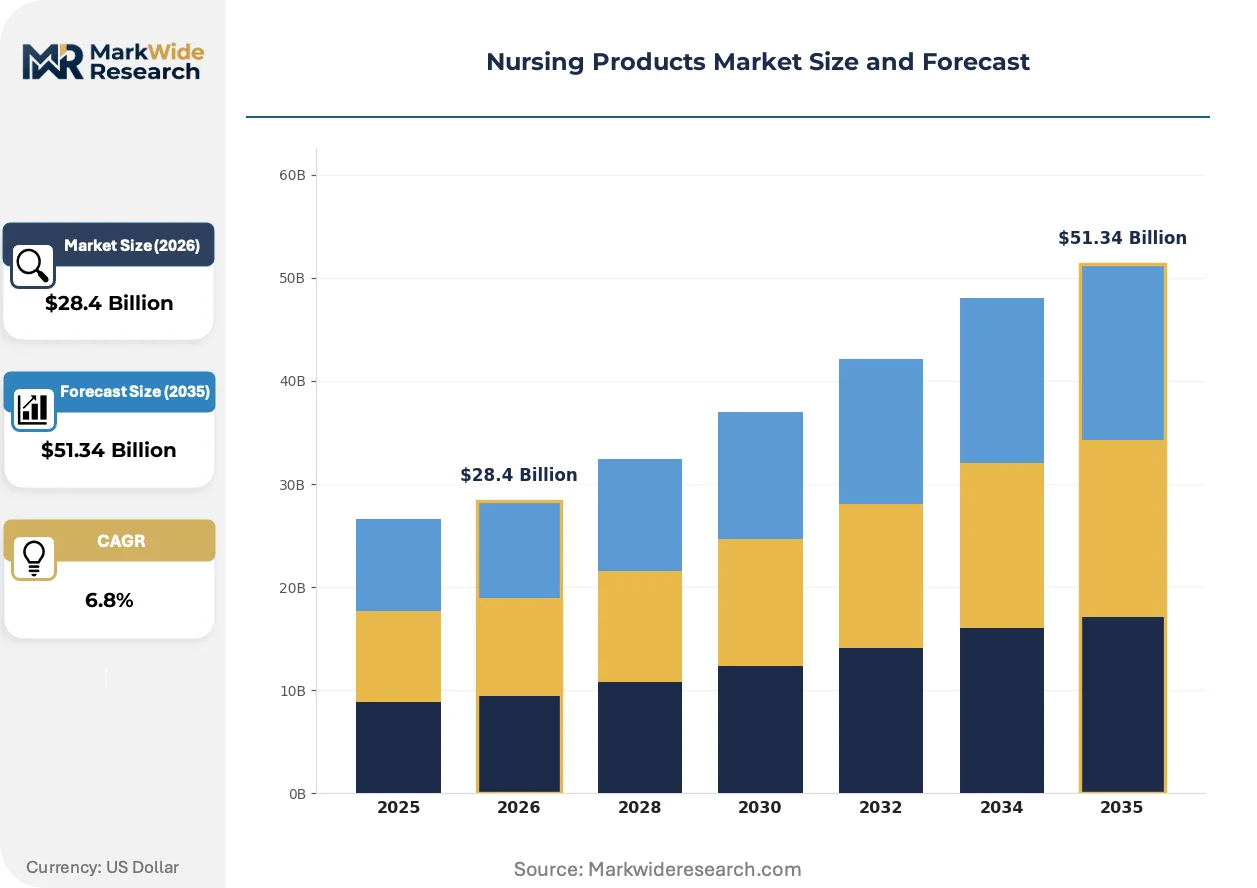
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nursing Pads, Wound Care Supplies, IV Supplies, Patient Monitoring Equipment End User: Hospitals, Home Care Providers, Nursing Homes, Clinics Application: Critical Care, Post-Operative Care, Ambulatory Care, Geriatric Care Technology: Telehealth Solutions, Wearable Devices, Smart Beds, Mobile Health Apps |
| Companies Covered | Medela, Philips Avent, Spectra Baby USA, Ameda, Pigeon Corporation, Koninklijke Philips NV, Lansinoh, Elvie, Haakaa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nursing Products Market Strategic Shifts & Innovations
Sensor miniaturization and cloud connectivity are dissolving the boundary between discrete medical devices and continuous health monitoring platforms in maternal care settings.
Wearable breast pump technology is converging with consumer electronics supply chains, leveraging smartphone-grade accelerometers and pressure sensors originally developed for fitness tracking applications. Hospital discharge planners and direct-to-consumer buyers now expect app ecosystems as standard features rather than premium add-ons. This convergence is compressing development cycles and forcing traditional medical device manufacturers to adopt consumer electronics release cadences.
The EU MDR and FDA digital therapeutics frameworks are diverging on software validation requirements, creating compliance complexity for manufacturers seeking simultaneous transatlantic approvals. MDR technical documentation demands for clinical evidence are extending review timelines for app-connected devices. European notified bodies are applying stricter scrutiny to cybersecurity documentation than their United States counterparts.
Subscription firmware upgrade models are displacing one-time hardware transactions as the primary customer relationship mechanism. Direct-to-consumer channels capture post-purchase engagement through in-app lactation coaching and personalized pumping schedules. Germany and the United States exhibit the most pronounced shift toward recurring revenue models in household procurement patterns.
Nursing Products Market Segmentation
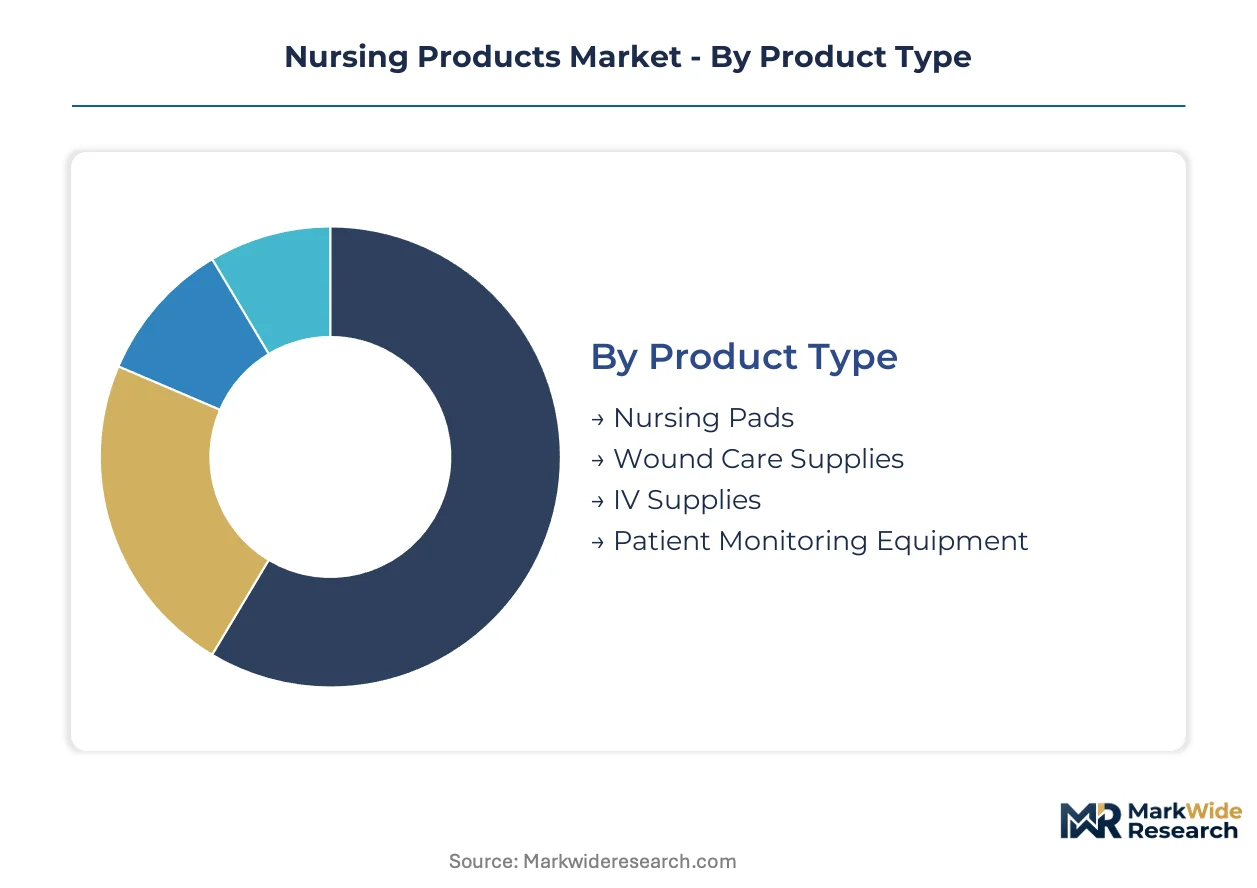
Segmentation in nursing products reveals distinct procurement behaviors across clinical and home settings. Supply chain configuration varies sharply between capital-intensive monitoring equipment and consumable disposables. Understanding these divides enables targeted channel strategies and regulatory positioning.
Product Type:
Specialty elastomer supply chains concentrate among three dominant chemical suppliers, exposing pump manufacturers to input cost volatility across all product categories.
- Patient Monitoring Equipment:Capital-intensive devices with embedded sensors and cloud connectivity dominate hospital procurement budgets. Acute care settings in Germany and the United States drive replacement cycles as value-based reimbursement mandates connected infrastructure.
- Wound Care Supplies:Advanced dressings incorporating antimicrobial agents and moisture management layers serve post-surgical and chronic wound protocols. Home care provider consolidation in multi-state networks is compressing distributor margins through direct vendor relationships.
- Nursing Pads:Disposable absorbent products with superabsorbent polymer cores address lactation leakage management. Retail pharmacy channels and direct-to-consumer subscriptions sustain volume.
- IV Supplies:Precision-molded connectors and safety-engineered needle systems reduce bloodstream infection risk. FDA 510(k) clearances govern material biocompatibility validations.
Patient monitoring equipment absorbs the bulk of installed capacity; telehealth-integrated wearable devices within this category are expanding most quickly.
End User:
Procurement authority is fragmenting across institutional purchasers and direct-to-consumer buyers with diverging price sensitivities.
- Hospitals:Integrated delivery networks negotiate enterprise contracts for capital equipment and high-volume disposables. Capital budgets prioritize patient monitoring systems with ISO 60601 safety certifications.
- Home Care Providers:Multi-state networks aggregate demand for connected monitoring systems as reimbursement shifts toward per-patient episode payments. Telehealth lactation consulting creates new software licensing revenue streams.
- Clinics:Outpatient facilities favor portable, rental-compatible breast pumps and disposable supply bundles. German statutory insurance coverage accelerates device penetration.
- Nursing Homes:Long-term care operators prioritize pressure injury prevention supplies and fall monitoring technologies. Medicaid reimbursement constraints limit premium product adoption.
Hospitals command the largest share of capital expenditure; home care providers are gaining share fastest as site-of-care migration accelerates.
Application:
Clinical acuity determines device specifications, with regulatory scrutiny intensifying for neonatal and critical care applications.
- Critical Care:Multi-parameter monitors and closed-system suction devices require continuous negative pressure calibration between 150 and 250 mmHg. FDA and EU MDR impose parallel validation requirements.
- Post-Operative Care:Wound drainage systems and pain management pumps support recovery protocols. German hospitals lead adoption of disposable closed-incision negative pressure therapy.
- Ambulatory Care:Lightweight, battery-operated pumps and single-use supplies enable same-day discharge. Retail pharmacy channels capture recurring consumable purchases.
- Geriatric Care:Pressure redistribution surfaces and incontinence management products address age-related conditions. Reimbursement through Medicare and Medicaid shapes price ceilings.
Critical care applications anchor premium pricing; post-operative monitoring is climbing the fastest as surgical volume shifts to outpatient settings.
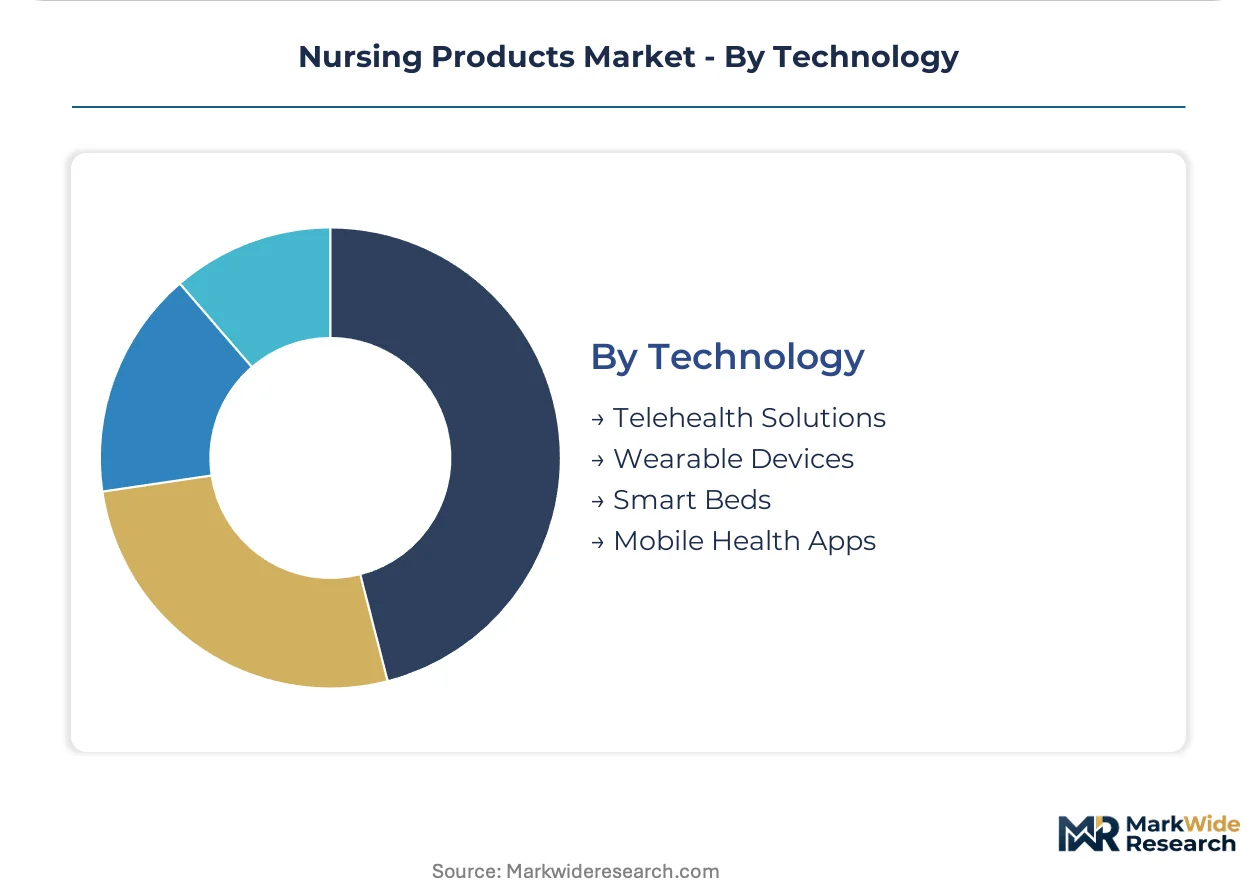
Technology:
Consumer electronics supply chains are converging with medical device manufacturing, compressing development cycles for sensor-enabled products.
- Telehealth Solutions:Per-session software licensing for remote lactation consulting and post-operative monitoring creates margin pools outside hardware sales. EU MDR cybersecurity documentation demands exceed FDA requirements.
- Wearable Devices:Smartphone-grade accelerometers and pressure sensors enable continuous lactation tracking and vital sign monitoring. Elvie and competitors leverage in-house app ecosystems for direct-to-consumer engagement.
- Smart Beds:Integrated pressure mapping and automated repositioning reduce hospital-acquired pressure injuries. Capital budgets limit penetration to tertiary centers.
- Mobile Health Apps:Software-as-medical-device pathways remain unsettled across FDA and European regulators. Firmware upgrade subscriptions decouple recurring revenue from initial hardware transactions.
Wearable devices capture the steepest expansion trajectory; telehealth solutions are absorbing the bulk of new software investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in medical-grade silicone processing clusters while consumption spreads across reimbursement-rich markets. The United States and Germany absorb premium device volumes through favorable coverage frameworks. Asian production hubs supply component assemblies to branded device assemblers in North America and Europe.
United States
FDA 510(k) pathway acceleration for wearable lactation devices compresses commercialization timelines below twelve months for qualified submissions. Hospital discharge programs and direct-to-consumer channels drive parallel demand for professional-grade pumps and app-connected wearables. The Boston-Cambridge medical device corridor anchors firmware engineering talent pools for IEC 62304-compliant software development.
Germany
Statutory health insurance reimbursement for breastfeeding support devices sustains above-average household penetration compared to neighboring markets. EU MDR conformity assessment bottlenecks extend CE marking timelines six to nine months beyond pre-2021 baselines. The Baden-Württemberg precision manufacturing cluster supplies medical-grade silicone valve assemblies for electric pump producers.
China
NMPA medical device registration requirements shape export timelines for manufacturers seeking multi-jurisdiction approvals. Domestic demand for disposable nursing supplies expands through retail pharmacy and e-commerce channels. The Yangtze River Delta concentrates contract manufacturing capacity for silicone component molding and sensor assembly.
Japan
PMDA quality management system inspections enforce parallel standards that delay market entry for foreign device manufacturers. Aging demographics sustain demand for patient monitoring equipment in long-term care settings. The Kansai region hosts specialized elastomer suppliers serving regional pump assembly operations.
Australia
TGA medical device regulations enforce cybersecurity documentation requirements for app-connected nursing products. Telehealth reimbursement frameworks enable per-session software licensing for remote lactation consulting. Sydney and Melbourne anchor home care provider networks consolidating procurement for connected monitoring systems.
Nursing Products Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent margin structures in the nursing products sector. The market fragments across hospital-grade equipment rentals, retail pharmacy disposables, and direct-to-consumer wearables with embedded software ecosystems. Strategic archetypes separate into legacy medical device incumbents, consumer electronics crossovers, and specialized lactation technology pure-plays. Dominant competitive moves include subscription firmware upgrades that decouple recurring revenue from hardware transactions and backward integration into medical-grade silicone supply chains.
Within the connected wearable tier, Elvie exemplifies direct-to-consumer engagement through in-house app ecosystems. Medela occupies a position anchoring professional-grade pump rentals through hospital discharge programs. Lansinoh sits within retail pharmacy channels competing on disposable nursing pad assortment breadth.
| Leading Market Players |
|---|
| Medela |
| Philips Avent |
| Spectra Baby USA |
| Ameda |
| Pigeon Corporation |
| Koninklijke Philips NV |
| Lansinoh |
| Elvie |
| Haakaa |
| Others |
Cost & Logistics Intelligence
Captive production of medical-grade silicone valve assemblies anchors supply positions for pump manufacturers while simultaneously determining pricing power across the nursing products sector. Manufacturers with in-house molding capabilities in Germany and the United States command premium positioning against competitors dependent on contract suppliers.
Pricing Analysis
Margin tightening in wearable breast pumps reflects the shift from transactional hardware sales toward subscription firmware models. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital-grade devices from direct-to-consumer wearables and unconnected manual alternatives. Price differentiation rests on ISO 60601 certification tier and after-sales service bundling. Home care providers exhibit highest price sensitivity due to per-patient episode reimbursement constraints.
Supply Chain Analysis
CE marking and FDA 510(k) qualification requirements gate supplier entry, concentrating component sourcing among validated medical device manufacturers in Germany, the United States, and China. Specialty elastomer feedstock draws from three dominant chemical suppliers, creating single-source vulnerability for silicone valve assemblies. Distribution runs through hospital procurement networks, retail pharmacy chains, and direct-to-consumer platforms with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nursing products sector is becoming a vertical-integration race, with manufacturers pursuing captive control over medical-grade silicone supply chains to defend margin positions against input cost volatility.
For Market Incumbents: Extend firmware subscription ecosystems to lock in recurring revenue beyond initial device transactions. Backward integration into silicone valve molding capacity mitigates supply concentration risk among specialty elastomer suppliers. Hospital discharge program relationships require reinforcement against direct-to-consumer entrants building app-based engagement platforms. For New Entrants and Emerging Players: Price-sensitive home care networks in multi-state configurations represent the most penetrable buyer archetype for connected monitoring systems. Telehealth lactation consulting software licensing creates white-space margin pools outside hardware-dominated competitive arenas. Regulatory affairs capacity investment accelerates multi-jurisdiction approval timelines against established competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by consumer electronics platforms seeking healthcare market entry. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. Digital therapeutics designation approvals signal inflection points for software-as-medical-device valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Migration | Recurring revenue decouples manufacturer economics from replacement cycle timing. |
| Medical-Grade Silicone Backward Integration | Captive valve molding insulates margin positions from specialty elastomer cost volatility. |
| Hospital System Partnership | Discharge program placement anchors professional-grade pump rental volumes. |
| Telehealth Platform Development | Per-session licensing captures margin pools outside hardware transaction boundaries. |
| Multi-Jurisdiction Regulatory Capacity | Parallel FDA, EU MDR, and Health Canada submissions compress commercialization timelines. |
Research Approach
Independent corroboration across hospital procurement managers, biomedical firmware engineers, lactation consultants, and GPO contracts managers underwrites the qualitative findings. Secondary validation incorporates FDA 510(k) filings, EU MDR technical documentation, hospital supply chain databases, and statutory health insurance reimbursement schedules. Bottom-up demand modeling triangulates against top-down market sizing across product type, end user, application, and technology dimensions.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation modeling spans patient monitoring equipment, wound care supplies, nursing pads, and IV supplies by hospital, home care provider, clinic, and nursing home end users. CAGRs derive from replacement cycle analysis, reimbursement trajectory assessment, and connected device adoption curve interpolation. Telehealth software licensing and wearable sensor integration serve as industry-specific forecast inputs.
Revisions become necessary when FDA digital therapeutics pathways diverge from EU MDR software validation requirements, or when specialty elastomer supply disruptions alter input cost assumptions. Forecasts reflect documented assumptions about reimbursement framework stability and regulatory timeline convergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Australia Hair Transplant Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Consumer Healthcare Market