
 GCC Healthcare Packaging Market | 2026-2036
GCC Healthcare Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Healthcare Packaging Market Intelligence
Saudi Arabia's packaging industrial zone development near Riyadh is reconfiguring supply chain geography for the GCC healthcare sector. Amcor leverages its regional film extrusion and converting footprint to serve pharmaceutical cold-chain requirements. Huhtamaki anchors flexible packaging supply through its UAE-based operations, competing on barrier performance and sterilization compatibility. Gerresheimer specializes in glass primary packaging for injectables, sustaining quality certifications that Gulf-based drug manufacturers require for export markets.
GCC healthcare packaging encompasses materials and container systems engineered to maintain sterility, stability, and tamper evidence for pharmaceuticals and medical devices, with specifications including oxygen transmission rates below 0.1 cc/m²/day and moisture vapor barriers critical for hygroscopic drug formulations. Primary packaging commands the deepest margin pools due to direct drug-contact compliance burdens and validation requirements, while flexible packaging technology expands fastest as pre-filled syringes and blister packs displace rigid formats in chronic disease therapies. Plastic materials dominate volume across the GCC, though glass retains structural importance in biologics and high-value parenteral segments where extractables and leachables testing protocols are most stringent.
SFDA serialization mandates, UAE's MOHAP track-and-trace requirements, and Gulf Standardization Organization harmonization efforts collectively elevate barrier specifications and authentication feature adoption across the region. These frameworks shape procurement decisions by forcing pharmaceutical manufacturers to qualify packaging suppliers against evolving compliance checklists rather than cost alone. Stakeholders must monitor how Saudi localization incentives reshape supplier geography and whether UAE free-zone logistics hubs retain packaging conversion dominance as domestic Saudi capacity scales.
Market Dynamics
Saudi Arabia's Vision 2030 localization mandates are compressing GCC pharmaceutical packaging supply chains, forcing multinational drug manufacturers to requalify domestic suppliers against SFDA serialization standards rather than rely on established UAE free-zone converters.
Growth Catalysts
- SFDA serialization mandates:Saudi Arabia's track-and-trace requirements for pharmaceutical packaging are compelling manufacturers to upgrade authentication features and barrier specifications across primary and secondary packaging tiers.
- Biologics cold-chain expansion:Temperature-sensitive therapies including mRNA vaccines and monoclonal antibodies are proliferating across Gulf hospital networks, elevating demand for validated thermal packaging with precise stability profiles.
- Domestic industrial zone development:Saudi packaging clusters near Riyadh and Jeddah are attracting film extrusion and converting investments that reduce import dependency for pharmaceutical manufacturers.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices, tied to regional crude differentials, inject margin uncertainty into flexible packaging production economics across GCC converter operations.
- Glass primary packaging concentration:Borosilicate vial and ampoule supply remains concentrated among European and Asian specialty glassmakers, creating qualification bottlenecks for Saudi injectables manufacturers.
- Extractables testing burden:USP <1664> and ICH Q3D guidelines impose extended validation timelines on elastomeric closure and plastic container suppliers serving biologics segments.
Strategic Opportunities
- Kuwait and Oman market penetration:Underdeveloped domestic packaging capacity in these GCC states creates first-mover advantages for Saudi and UAE converters with established SFDA and MOHAP certifications.
- Pre-filled syringe format conversion:Chronic disease therapies for diabetes and rheumatoid arthritis are shifting from vial-and-syringe to ready-to-use presentations, opening specialized filling and packaging service contracts.
- Gulf Standardization Organization harmonization:Cross-border regulatory alignment initiatives are streamlining multi-country product registrations, reducing packaging artwork and compliance cost duplication.
Industry Challenges
- Serialization equipment retrofitting:Pharmaceutical packaging lines require hardware and software upgrades to accommodate aggregation hierarchies and tamper-evident features, compressing capital deployment timelines.
- Barrier film formulation expertise:Multi-layer coextrusion and metallization capabilities for oxygen transmission rates below 0.1 cc/m²/day remain concentrated among a narrow supplier base, constraining local technology transfer.
- Cold-chain validation documentation:Temperature mapping and stability studies for insulated shipper systems demand specialized thermal engineering talent scarce across GCC technical institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Healthcare Packaging Market |
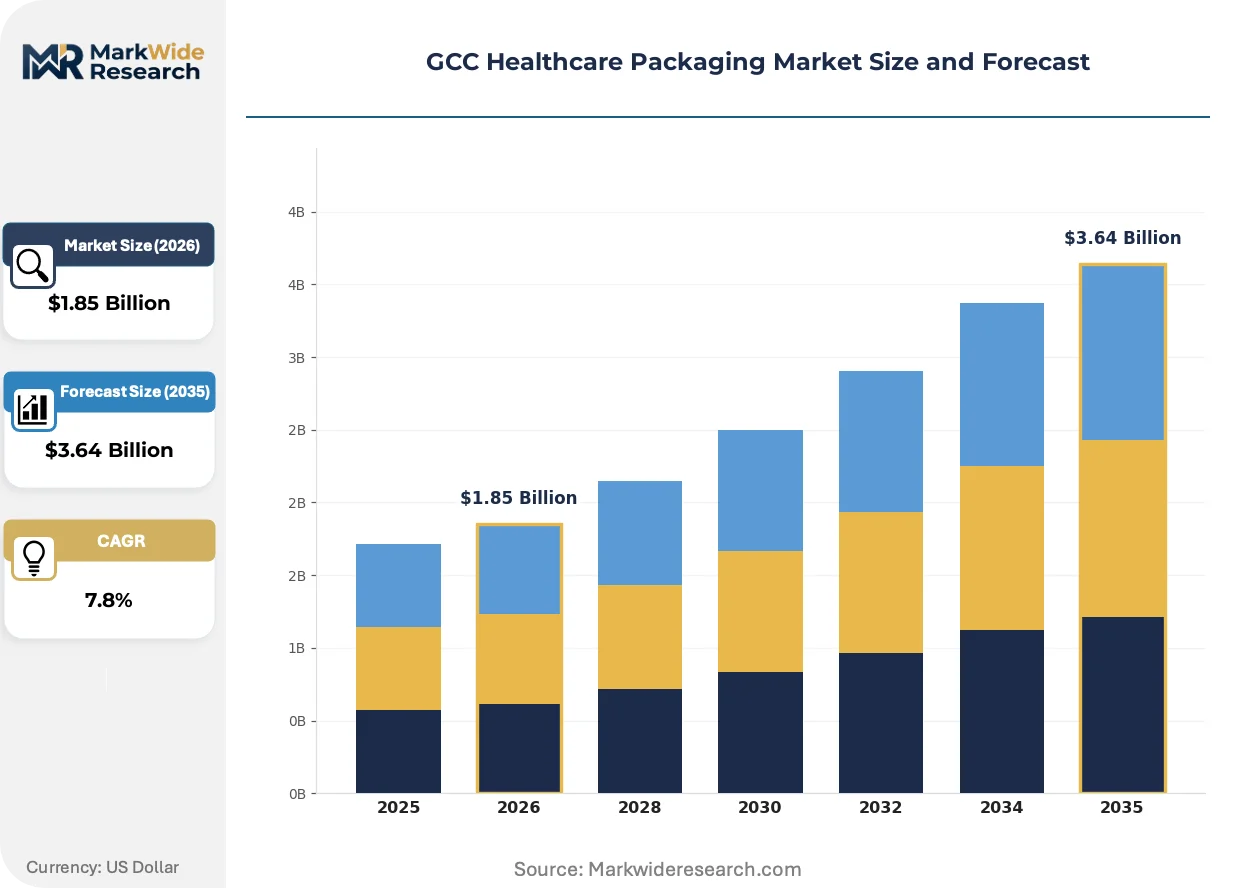
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Bulk Packaging Material: Plastic, Glass, Metal, Paperboard End User: Pharmaceutical Manufacturers, Medical Device Companies, Hospitals, Contract Packaging Technology: Flexible Packaging, Rigid Packaging, Tubular Packaging, Vacuum Packaging |
| Companies Covered | Huhtamaki, Berry Global, Amcor, Arabian Packaging, Mondi, Gerresheimer, CCL Industries, West Pharmaceutical Services, AptarGroup, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Healthcare Packaging Market Strategic Shifts & Innovations
Pharmaceutical packaging across the Gulf is converging on patient-centric formats and digital authentication layers, with material science and regulatory compliance advancing in parallel rather than sequence.
Active barrier films incorporating desiccant polymers and oxygen scavengers are migrating from high-value biologics toward oral solid dosage presentations. Generic drug manufacturers in Saudi Arabia are adopting these materials to extend shelf life in high-humidity climates. The technology is migrating from premium injectable segments into chronic disease maintenance therapies, compressing the cost differential between standard and enhanced barrier configurations.
SFDA's 2023 serialization enforcement timeline and MOHAP's equivalent track-and-trace requirements are mandating aggregation capabilities across secondary and tertiary packaging levels. Pharmaceutical manufacturers must now implement line-level hardware for case-and-pallet coding or risk distribution suspension. Saudi domestic producers are responding fastest, integrating vision systems and reject mechanisms ahead of UAE-based importers facing requalification delays.
Hospital procurement consortia across Riyadh, Jeddah, and Dammam are consolidating purchasing authority for high-volume parenteral and oncology products. This buyer concentration is displacing fragmented distributor networks that historically specified packaging formats. The shift is most visible in Saudi Arabia's National Unified Procurement Company contracts, where standardization clauses now override individual hospital preferences for container closure systems.
GCC Healthcare Packaging Market Segmentation
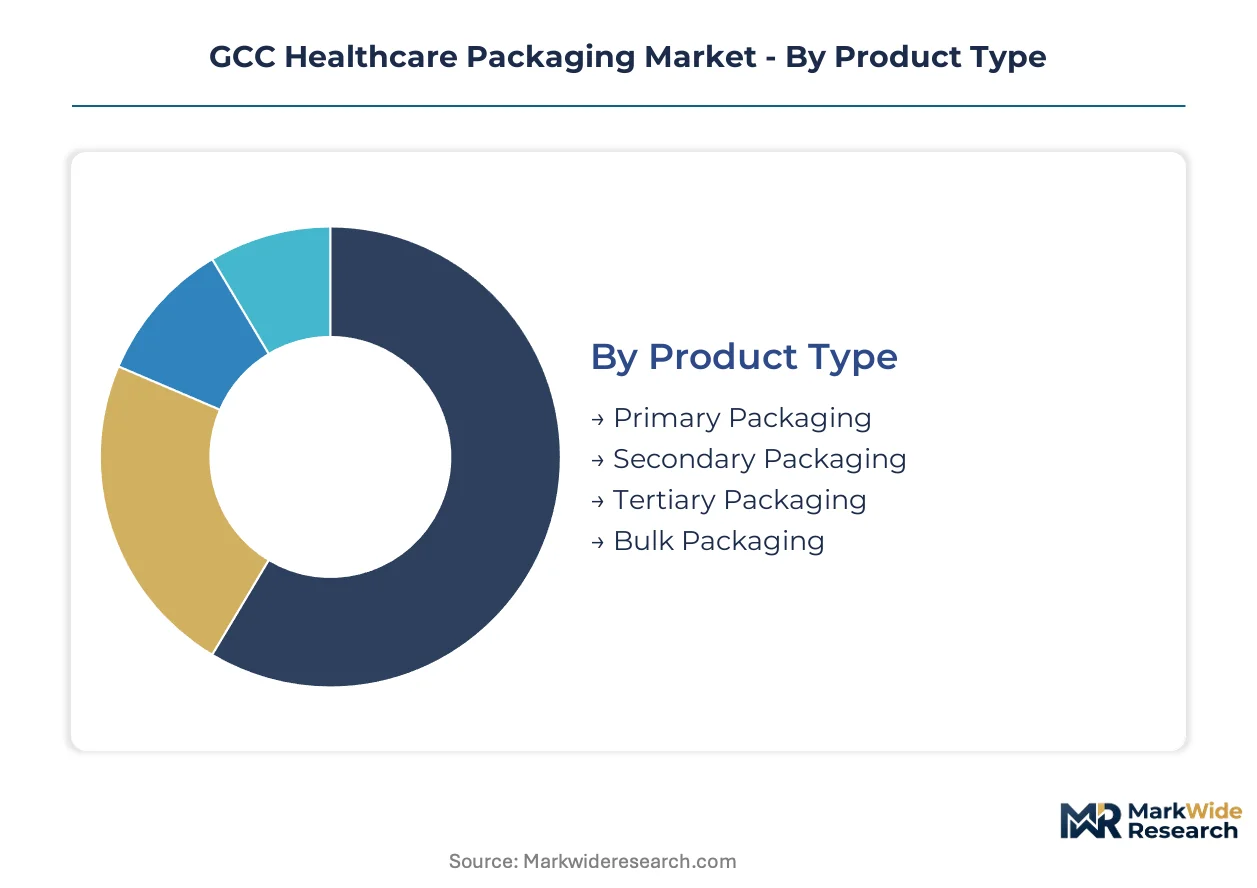
Segmentation reveals how GCC healthcare packaging procurement diverges across regulatory compliance tiers, material performance requirements, and supply chain proximity mandates. Each dimension carries distinct margin profiles and qualification barriers that shape supplier selection.
Product Type:
After-sales validation intensity escalates dramatically from tertiary through primary tiers, with direct drug-contact packaging demanding extended stability studies and extractables documentation that inflate service costs.
- Primary Packaging:Vials, ampoules, syringes, and blister packs maintain direct pharmaceutical contact. SFDA serialization mandates and USP compliance protocols concentrate procurement among Saudi and UAE suppliers with validated cleanroom operations.
- Secondary Packaging:Cartons, labels, and leaflets incorporate aggregation hierarchies for track-and-trace compliance. Demand clusters around Riyadh industrial zones where domestic converters exploit localization incentives.
- Tertiary Packaging:Shippers and cases for distribution protection require temperature mapping documentation for cold-chain therapies. Kuwait and Oman hospital networks source predominantly from Saudi and UAE converters.
- Bulk Packaging:Large-volume containers for active pharmaceutical ingredients and excipients prioritize chemical resistance and UN certification for hazardous material transport.
By volume, Secondary Packaging leads. By growth pace, Primary Packaging is ahead.
Material:
Cost tier stratification separates commodity resins from specialty substrates, with borosilicate glass and high-barrier films commanding 3-5x polypropylene pricing and extended supplier qualification timelines.
- Plastic:Polypropylene, polyethylene, and polyester films dominate flexible formats through multi-layer coextrusion achieving oxygen transmission below 0.1 cc/m²/day. Saudi film extrusion investments near Jubail are compressing import dependency.
- Glass:Borosilicate and soda-lime compositions serve parenteral and oral liquid segments where extractables testing under USP limits qualification to European and Asian specialty manufacturers.
- Metal:Aluminum foils and aerosol cans provide absolute moisture and light barriers for inhalation products and sensitive topicals.
- Paperboard:Pharmaceutical-grade folding cartons with tamper-evident features satisfy secondary packaging requirements at lowest unit cost.
Plastic captures the largest volume share. Glass exhibits the steepest expansion trajectory driven by biologics proliferation.
End User:
Customer type determines specification stringency, with pharmaceutical manufacturers imposing validation protocols that contract packagers and hospitals rarely replicate.
- Pharmaceutical Manufacturers:Multinational drug producers and Saudi domestic firms drive demand for primary packaging with full regulatory documentation. SFDA serialization enforcement compels line-level aggregation investments.
- Medical Device Companies:Sterilization compatibility and shelf-life validation requirements concentrate procurement among converters with ISO 13485 certification.
- Hospitals:National Unified Procurement Company consolidation across Riyadh, Jeddah, and Dammam is standardizing container specifications for high-volume parenterals.
- Contract Packaging:Third-party fill-finish and packaging service providers demand flexible formats and rapid format changeover capabilities.
Pharmaceutical Manufacturers absorb the highest unit volumes. Contract Packaging is gaining share fastest as outsourcing expands.
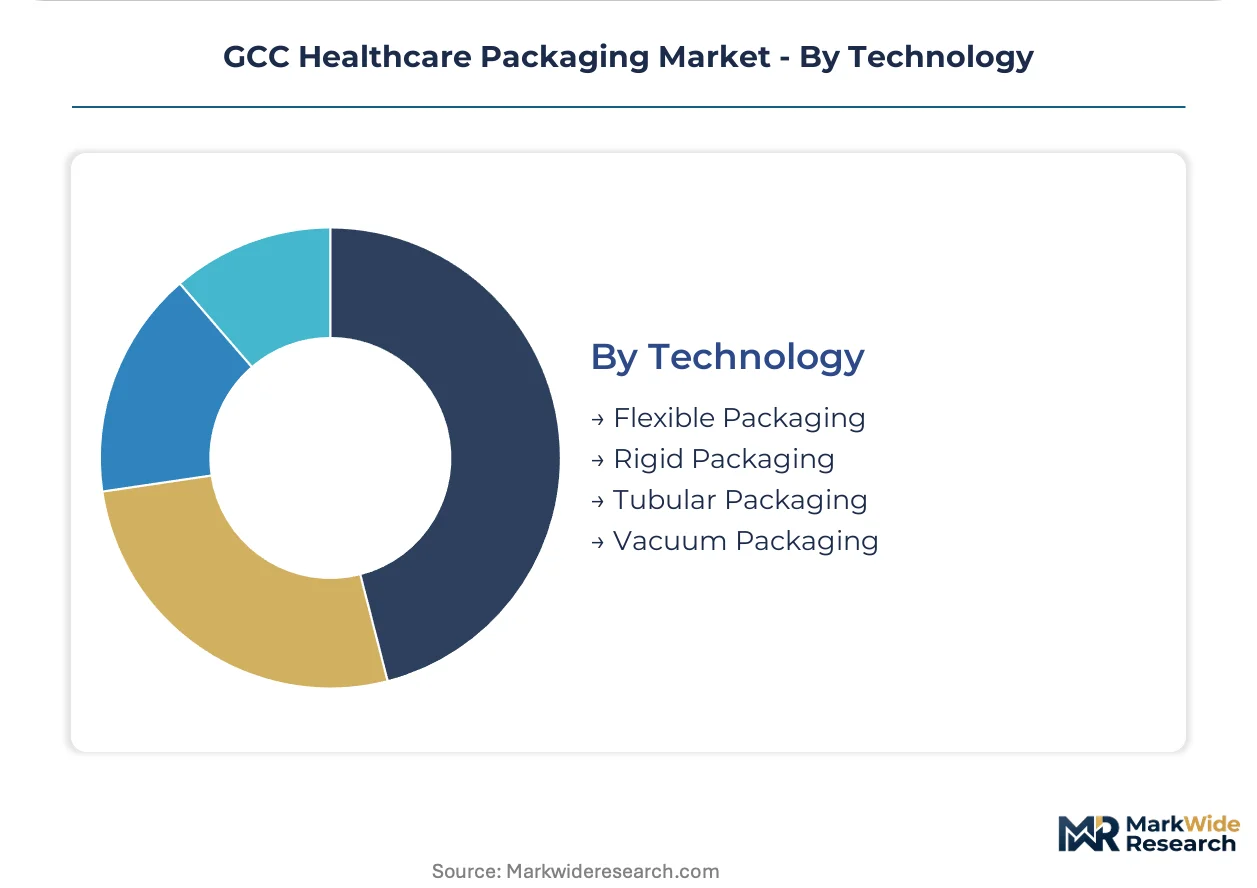
Technology:
Maturity gradients separate established rigid formats from advancing flexible solutions, with pre-filled syringes and cold-chain shippers representing technology migration frontiers.
- Flexible Packaging:Blister films, pouches, and sachets displace rigid alternatives in chronic disease therapies. Metallization and coextrusion expertise remains concentrated among Amcor and Huhtamaki regional operations.
- Rigid Packaging:Bottles, jars, and vials retain dominance in liquid formulations and high-value injectables where dimensional stability is critical.
- Tubular Packaging:Collapsible aluminum and plastic tubes serve semi-solid dermatological and ophthalmic preparations.
- Vacuum Packaging:Modified atmosphere configurations extend shelf life for hygroscopic and oxygen-sensitive drug substances.
Rigid Packaging maintains volume leadership. Flexible Packaging is expanding most quickly as format conversion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging conversion capacity clusters in Saudi Arabia and the UAE, with Riyadh industrial zones and Dubai free zones commanding distinct supply chain roles. SFDA and MOHAP regulatory frameworks are forcing pharmaceutical manufacturers to requalify suppliers against localization mandates.
Saudi Arabia
Domestic pharmaceutical production under Vision 2030 is accelerating demand for validated primary packaging with serialization compliance. SFDA mandates on track-and-trace aggregation are compelling line-level equipment investments across Riyadh and Jeddah manufacturing clusters. The King Salman Park industrial zone near Riyadh is attracting film extrusion investments that reduce import dependency for flexible barrier formats.
United Arab Emirates
MOHAP's harmonized traceability requirements are elevating authentication specifications for secondary packaging sourced through Dubai and Sharjah logistics hubs. Free-zone converters retain advantage in rapid format changeover for multinational drug manufacturers. Jebel Ali pharmaceutical logistics corridors are integrating tertiary cold-chain validation services for temperature-sensitive biologics distribution.
Kuwait
Hospital procurement centralization through the Ministry of Health is consolidating packaging specifications for high-volume parenteral products. The country's national pharmaceutical regulator is adopting SFDA-aligned serialization timelines for imported medicines. Domestic packaging capacity remains underdeveloped, creating sourcing dependencies on Saudi and UAE converters with established Gulf certifications.
Oman
Public-private hospital networks in Muscat and Salalah are expanding biologics storage infrastructure that demands validated thermal packaging. The Sultanate's pharmaceutical distribution framework lacks domestic conversion capacity, forcing reliance on cross-border suppliers. Special Economic Zone at Duqm is attracting packaging logistics investments to serve regional re-export requirements.
Qatar
Hamad Medical Corporation's consolidated procurement authority is standardizing container closure systems for oncology and chronic disease therapies. The national health regulator maintains stringent import documentation requirements that favor suppliers with pre-existing SFDA or EMA certifications. Ras Laffan industrial corridor remains peripheral to pharmaceutical packaging conversion, concentrating demand on Doha-based distribution channels.
GCC Healthcare Packaging Market Key Industry Players
Multinational material science conglomerates and regional flexible packaging specialists split the market across distinct capability tiers. Consolidation pressure intensifies as SFDA serialization mandates force pharmaceutical manufacturers to reduce supplier counts in favor of validated partners. Three archetypes dominate: integrated film-to-package converters with regional extrusion assets, European glass primary packaging specialists with Gulf distribution partnerships, and diversified healthcare packaging platforms with multi-material portfolios. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as localization incentives reshape procurement geography.
Within the integrated converter tier, Amcor and Huhtamaki exemplify archetypes leveraging regional film extrusion and metallization capabilities to serve pharmaceutical barrier requirements. Gerresheimer occupies a position representing European glass primary packaging specialists that sustain quality certifications Gulf-based drug manufacturers require for export market access. These three anchors illustrate how multinational packaging platforms with pre-existing regulatory documentation are capturing share as Saudi localization mandates compress supplier qualification timelines.
| Leading Market Players |
|---|
| Huhtamaki |
| Berry Global |
| Amcor |
| Arabian Packaging |
| Mondi |
| Gerresheimer |
| CCL Industries |
| West Pharmaceutical Services |
| AptarGroup |
| Others |
Cost & Logistics Intelligence
Jebel Ali pharmaceutical logistics corridors anchor GCC healthcare packaging cost dynamics, compressing margin pools for UAE-based converters while Saudi domestic capacity expansion under Vision 2030 redraws price differentiation across primary and secondary packaging tiers. Freight consolidation through Dubai free zones concentrates supply chain power among established operators, forcing new entrants to absorb premium logistics costs or sacrifice barrier performance specifications.
Pricing Analysis
SFDA serialization mandates dictate the pricing tier structure across the GCC healthcare packaging landscape. Three-tier pricing structure across premium, standard, and economy levels separates validated primary packaging with full extractables documentation from basic secondary formats and unqualified imports. Certification grade and volume scale drive price differentiation, with SFDA-compliant suppliers commanding substantial premiums over MOHAP-only certified alternatives. Cost compression in standard-tier flexible packaging is intensifying because Saudi film extrusion investments near Jubail are expanding domestic supply. Contract packaging service providers exhibit the highest price sensitivity, while multinational pharmaceutical manufacturers prioritize qualification over unit cost.
Supply Chain Analysis
Tariff exposure between European specialty glassmakers and Saudi injectables manufacturers dominates supply chain risk architecture for GCC healthcare packaging. Geographic supply concentration centers on Germany, Italy, and China for borosilicate vials and ampoules, while Saudi Arabia and the UAE anchor regional film extrusion and converting capacity. Raw material dependencies rest on polypropylene and polyethylene resins from regional petrochemical complexes, metallized films from Asian suppliers, and pharmaceutical-grade paperboard from European mills. Single-source vulnerability pervades high-barrier coextrusion technology, where multi-layer film expertise remains concentrated among a narrow supplier base. Distribution runs through Dubai free-zone logistics hubs and Riyadh industrial zone clusters, with tertiary cold-chain validation services increasingly co-located at Jebel Ali pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible format substitution threatens rigid packaging incumbents as pre-filled syringes and blister packs displace vial-and-syringe presentations across chronic disease therapies, forcing established suppliers to defend positioning through barrier technology investments and regulatory qualification depth.
For Market Incumbents: Entrench serialization-ready capacity through backward integration into film extrusion assets near Riyadh and Jeddah manufacturing clusters. Prioritize USP compliance documentation depth to maintain qualification advantages as SFDA enforcement timelines compress supplier approval windows. Defend against flexible format substitution by acquiring metallization and coextrusion expertise that generic drug manufacturers require for high-humidity climate shelf-life extension. For New Entrants and Emerging Players: Build out cold-chain validation service capabilities targeting Kuwait and Oman hospital networks, where domestic packaging capacity gaps create first-mover advantages for converters with established Gulf certifications. Kuwait's Ministry of Health procurement centralization offers the most penetrable entry point, with standardization clauses displacing fragmented distributor networks. Pursue specialized filling and packaging service contracts for pre-filled syringe format conversion as diabetes and rheumatoid arthritis therapies shift from vial-and-syringe to ready-to-use presentations. For Investors and Strategic Acquirers: Regional flexible packaging specialists with SFDA pre-qualification represent the most attractive acquisition archetype for exposure to Saudi localization incentives. Long-term viability hinges on whether domestic Saudi capacity scales sufficiently to displace UAE free-zone logistics dominance or instead fragments procurement across parallel supply chains. Monitor Gulf Standardization Organization harmonization progress as the critical inflection signal, with cross-border regulatory alignment initiatives capable of streamlining multi-country product registrations and reducing packaging artwork cost duplication.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captures margin pools from polypropylene resin conversion near Jubail petrochemical complexes. |
| SFDA Pre-Qualification Investment | Compresses supplier approval timelines for pharmaceutical manufacturers facing serialization enforcement. |
| Cold-Chain Validation Service Expansion | Addresses thermal engineering talent scarcity across GCC technical institutes for biologics distribution. |
| Pre-Filled Syringe Format Conversion | Aligns with chronic disease therapy shifts from vial-and-syringe to ready-to-use presentations. |
| Gulf Certification Harmonization | Reduces packaging artwork and compliance cost duplication across Saudi, UAE, and Kuwait regulatory frameworks. |
Research Approach
A standing panel of pharmaceutical packaging procurement managers, SFDA regulatory affairs specialists, hospital formulary directors, and flexible film extrusion engineers provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews captured procurement decision criteria, supplier qualification timelines, and serialization equipment retrofitting constraints. Secondary sources included SFDA guidance documents, MOHAP traceability requirements, Gulf Standardization Organization technical regulations, and pharmaceutical trade flow data from regional customs authorities. Bottom-up demand modeling triangulated against top-down market sizing from petrochemical feedstock consumption and packaging machinery import records.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for petrochemical price volatility and regulatory enforcement timing. Segmentation dimensions encompassed product type tier, material substrate, end-user category, and technology format, with additional granularity for cold-chain versus ambient distribution requirements. CAGRs derived from fitted growth curves against historical pharmaceutical production and packaging machinery capacity expansion. Industry-specific forecast inputs included biologics pipeline data from regional hospital networks and Vision 2030 healthcare localization investment disclosures.
Practitioners should monitor SFDA serialization enforcement timelines, petrochemical feedstock price corridors, and Gulf Standardization Organization harmonization progress for early signals of forecast revision. Forecasts reflect assumptions regarding regulatory implementation pace, domestic capacity scaling, and multinational pharmaceutical manufacturer sourcing preferences. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Nursing Products Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Organ Care Products Market