
 Smoking Cessation Aids Market | 2026-2036
Smoking Cessation Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Smoking Cessation Aids Market Outlook
Combination therapy bundling is repositioning consumer choice toward integrated patch-and-lozenge regimens over standalone products. Johnson & Johnson leverages its pharmaceutical heritage to sustain dominance in transdermal nicotine delivery systems. Pfizer Inc. anchors its portfolio through prescription-grade varenicline formulations, while GlaxoSmithKline plc competes aggressively across over-the-counter gum and lozenge segments.
Smoking cessation aids encompass pharmacological and behavioral interventions designed to reduce nicotine dependence, with nicotine replacement therapy products typically delivering controlled doses of 7–21 mg nicotine through transdermal, oral, or pulmonary routes to alleviate withdrawal symptoms. Prescription medications such as varenicline function as partial nicotinic receptor agonists, modulating dopamine release to reduce craving severity. Nicotine Replacement Therapy leads volume globally due to established safety profiles and broad OTC availability, while Digital Solutions represent the fastest-expanding segment as smartphone-based cognitive behavioral therapy applications integrate with wearable biosensors to personalize tapering protocols. Prescription Medications retain concentrated margin pools despite narrower distribution, reflecting proprietary formulation protections and clinician gatekeeping requirements.
The FDA regulates smoking cessation pharmaceuticals under New Drug Application pathways with post-market surveillance mandates, while the EMA enforces centralized marketing authorization through its Committee for Medicinal Products for Human Use. REACH compliance governs nicotine purity thresholds and excipient safety documentation for products distributed across European Economic Area member states. Stakeholders must monitor evolving digital therapeutics classification frameworks, as regulators in multiple jurisdictions deliberate whether app-based behavioral interventions warrant medical device or wellness product designation.
Market Dynamics
Employer-sponsored health plan integration is restructuring smoking cessation aid procurement, with pharmacy benefit managers consolidating purchasing power and steering formulary placement toward combination NRT regimens over standalone products.
Growth Catalysts
- Workplace Wellness Mandates:Large employers in the United States are embedding nicotine replacement therapy into preventive care benefits, expanding covered lives for transdermal patches and prescription varenicline.
- REACH Compliance Thresholds:ECHA-mandated nicotine purity documentation is professionalizing supply chains across European Economic Area member states, filtering out substandard excipient suppliers.
- Smartphone-Based CBT Integration:Digital therapeutics developers are pairing cognitive behavioral therapy applications with wearable biosensors to personalize tapering protocols and extend adherence duration.
Market Restraints
- API Concentration Risk:Varenicline active pharmaceutical ingredient production clusters among a limited set of contract manufacturers in India and China, exposing supply continuity to single-site disruptions.
- FDA Labeling Friction:Post-market surveillance mandates for neuropsychiatric adverse events have tightened prescription protocols, elongating prescriber education cycles and dampening new patient starts.
- Heat-Not-Burn Substitution:Tobacco heating devices are capturing nicotine-dependent consumers seeking reduced-harm alternatives without clinical cessation protocols, eroding the addressable patient pool for pharmaceutical interventions.
Strategic Opportunities
- Medicaid Expansion States:United States jurisdictions with expanded eligibility are adding smoking cessation to mandatory preventive services, opening bulk procurement channels for NRT gum and lozenge formats.
- Digital Therapeutics Reimbursement:Germany's DiGA fast-track pathway for prescription digital health applications is creating precedent for app-based behavioral interventions to secure statutory health insurance coverage.
- Transdermal-Oral Convergence:Patch-and-lozenge combination kits are capturing share from monotherapy users, with integrated tapering algorithms enabling personalized nicotine weaning schedules.
Industry Challenges
- Behavioral Science Talent Scarcity:Digital health developers face acute shortages of clinical psychologists and addiction specialists capable of translating evidence-based protocols into adaptive software architectures.
- Dual Classification Uncertainty:Regulators in multiple jurisdictions remain undecided on whether CBT applications warrant medical device or wellness product designation, freezing capital commitment for platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoking Cessation Aids Market |
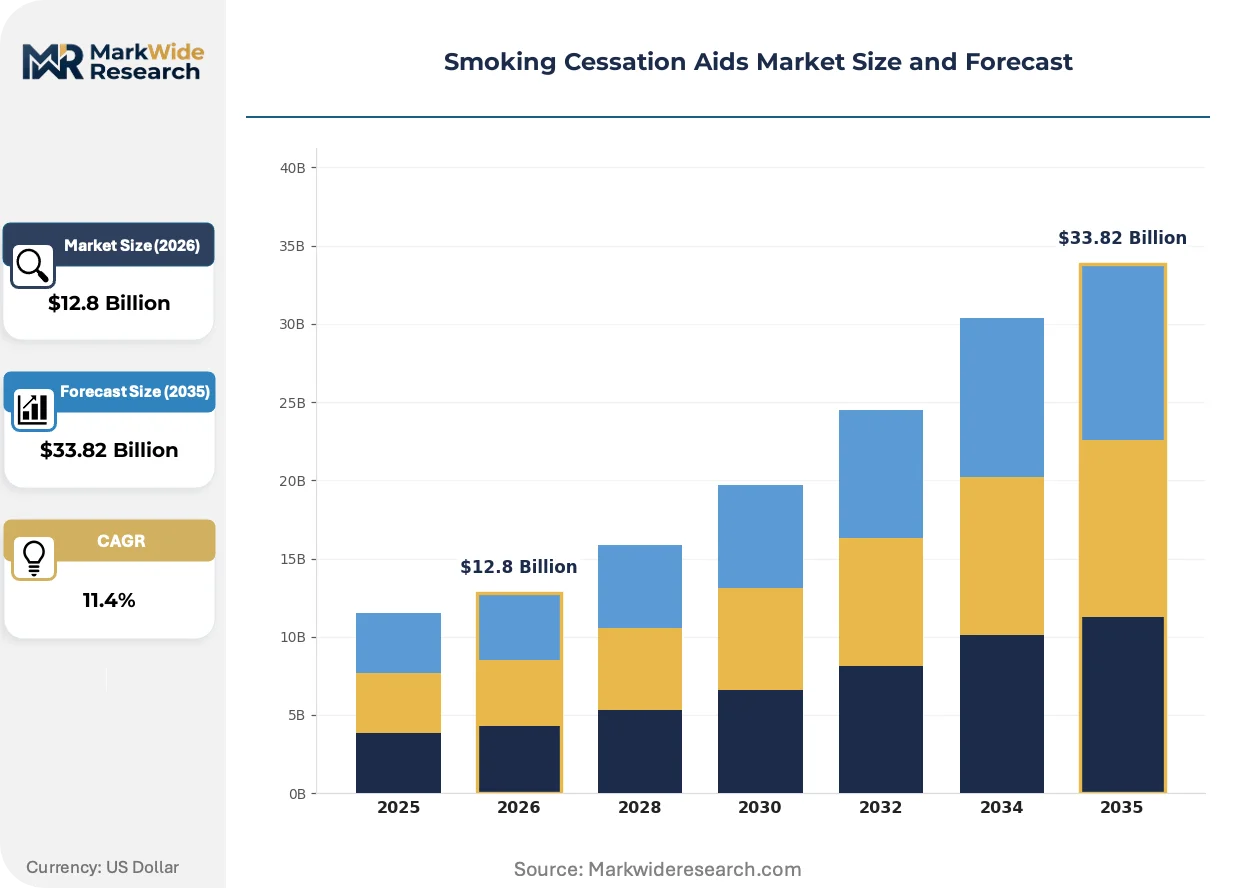
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nicotine Replacement Therapy, Prescription Medications, Behavioral Therapy, Digital Solutions Delivery Mode: Patch, Gum, Inhaler, Lozenge User Demographics: Adults, Teens, Pregnant Women, Heavy Smokers Distribution Channel: Pharmacies, Online Retail, Hospitals, Health Clinics |
| Companies Covered | Johnson & Johnson, Philip Morris International Inc., Pfizer Inc., Dr. Reddy's Laboratories Ltd, Perrigo Company plc, GlaxoSmithKline plc, British American Tobacco plc, Cipla Ltd, Haleon plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoking Cessation Aids Market Strategic Shifts
Sensor-enabled personalization is displacing one-size-fits-all dosing paradigms, with biometric feedback loops enabling dynamic nicotine tapering that responds to real-time withdrawal symptom intensity.
Transdermal delivery systems are unifying microprocessor-controlled release mechanisms with skin-adhesion polymers that adjust permeability based on transepidermal water loss measurements. Employer health plans are piloting these smart patches for high-risk employee cohorts. The technology is unifying pharmacokinetic precision with adherence monitoring, compressing relapse windows through algorithm-driven dose modulation.
EMA's Committee for Medicinal Products for Human Use has centralized marketing authorization requirements for combination nicotine products, mandating unified safety documentation across patch, gum, and lozenge formats. Manufacturers must now submit integrated pharmacovigilance plans rather than product-specific dossiers. Smaller OTC brands lacking regulatory affairs infrastructure are withdrawing from European Economic Area distribution.
Integrated care networks are consolidating smoking cessation procurement under single vendor contracts that bundle NRT products with telehealth coaching and biometric monitoring. Pharmacy benefit managers are displacing retail pharmacy dispensing with direct-to-patient mail fulfillment for 90-day combination regimens. This pattern concentrates most visibly in United States Medicare Advantage plans targeting COPD and cardiovascular risk reduction quality metrics.
Smoking Cessation Aids Market Segmentation
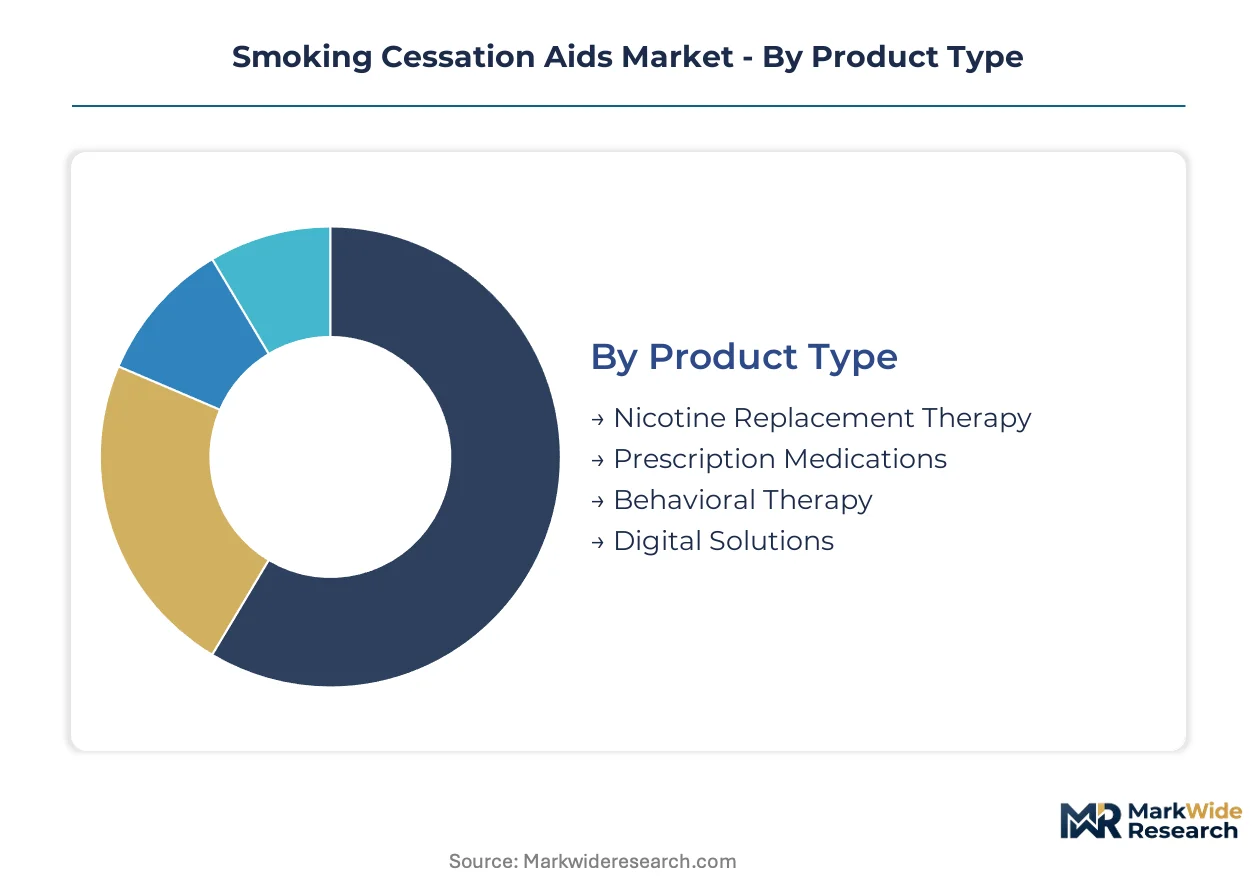
Smoking cessation aid manufacturers allocate capital unevenly across product architectures, with transdermal systems and digital platforms demanding divergent investment profiles. Segmentation clarity reveals where formulation complexity, regulatory burden, and reimbursement pathways concentrate margin capture.
Product Type:
Transdermal patch manufacturing requires the heaviest upfront capital outlays for precision coating lines and skin-adhesion polymer R&D, while digital therapeutics demand specialized behavioral science talent rather than physical plant.
- Nicotine Replacement Therapy:Transdermal patches, gums, and lozenges deliver controlled nicotine doses of 7–21 mg through established pharmacokinetic profiles. Demand clusters in United States employer-sponsored health plans where pharmacy benefit managers favor OTC availability and bulk procurement of combination regimens.
- Prescription Medications:Varenicline formulations function as partial nicotinic receptor agonists modulating dopamine release to attenuate craving severity. Clinician gatekeeping and FDA post-market surveillance mandates for neuropsychiatric adverse events restrict distribution to controlled channels, preserving concentrated margin pools despite narrower patient access.
- Behavioral Therapy:Cognitive behavioral protocols delivered through individual or group counseling sessions. Medicaid expansion states increasingly mandate coverage as preventive services.
- Digital Solutions:Smartphone-based CBT applications paired with wearable biosensors for personalized tapering. Germany's DiGA fast-track pathway is creating reimbursement precedent for statutory health insurance coverage.
Most installed capacity flows through Nicotine Replacement Therapy. Expansion is steepest in Digital Solutions.
Delivery Mode:
Patch systems command premium pricing through polymer science differentiation, whereas gum and lozenge formats compete on manufacturing scale and flavor formulation agility.
- Patch:Microprocessor-controlled release mechanisms now integrate with skin-adhesion polymers adjusting permeability based on transepidermal water loss measurements. United States Medicare Advantage plans pilot these smart patches for high-risk employee cohorts targeting COPD quality metrics.
- Gum:Rapid buccal absorption delivers nicotine spikes addressing acute withdrawal episodes. European Economic Area distribution is consolidating as EMA unified safety documentation requirements filter out smaller OTC brands lacking regulatory affairs infrastructure.
- Inhaler:Pulmonary delivery mimics behavioral rituals of smoking while providing metered nicotine dosing. Hospital formularies favor this modality for inpatient cessation protocols.
- Lozenge:Dissolvable formats enable discreet use in workplace settings. Combination kits pairing lozenges with patches are displacing monotherapy users through integrated tapering algorithms.
Patch manufacturing absorbs the majority of specialized polymer R&D spending. Inhaler volumes are climbing the fastest as hospital procurement consolidates.
User Demographics:
Heavy smokers generate the highest per-patient revenue through combination therapy requirements, while pregnant women impose the strictest safety documentation burdens on manufacturers.
- Adults:The core addressable population spans employed cohorts accessing workplace wellness benefits and individual purchasers through retail pharmacies. United States integrated care networks bundle NRT products with telehealth coaching for this demographic.
- Teens:Regulatory restrictions on nicotine marketing and prescribing protocols limit commercial access. Pediatric labeling requirements extend clinical trial timelines for manufacturers seeking adolescent indications.
- Pregnant Women:Risk-benefit calculations favor behavioral interventions over pharmacological approaches due to teratogenic concerns. FDA pregnancy category classifications constrain varenicline utilization.
- Heavy Smokers:Patients consuming more than one pack daily require escalated dosing protocols and extended treatment durations. Combination patch-and-lozenge regimens dominate prescribing patterns for this cohort.
Adult users account for the largest prescription volume. Heavy smokers are gaining share fastest as combination therapy protocols expand.
Distribution Channel:
Pharmacy benefit managers are restructuring channel economics by displacing retail dispensing with direct-to-patient mail fulfillment for 90-day combination regimens.
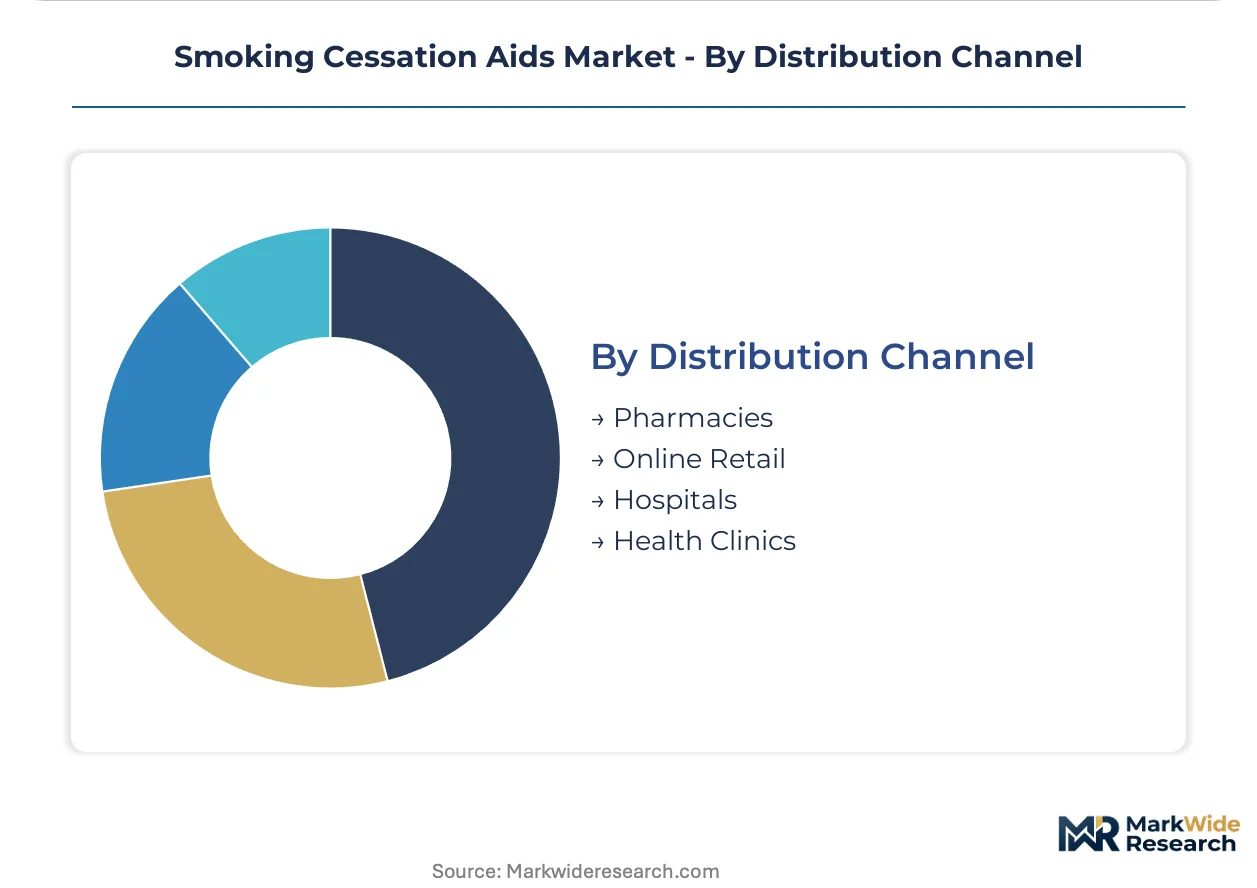
- Pharmacies:Community and retail locations provide immediate access for acute withdrawal episodes. OTC nicotine gum and lozenge formats generate the highest foot traffic conversion rates.
- Online Retail:Subscription models for patch refills and digital therapeutics platforms bypass traditional dispensing infrastructure. Privacy preferences drive adoption among employed professionals.
- Hospitals:Inpatient cessation protocols initiated during acute cardiac or pulmonary events capture patients at maximum motivation. Discharge planning integrates prescription varenicline with outpatient behavioral referrals.
- Health Clinics:Federally qualified health centers and community health centers serve Medicaid-eligible populations in expansion states. Bulk procurement channels for NRT gum and lozenge formats are opening through these facilities.
Pharmacies retain the deepest installed fulfillment infrastructure. Online Retail is expanding most quickly as privacy-conscious consumers bypass physical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smoking cessation aids industry traces its commercial origins to transdermal nicotine patch development in the United States during the early 1990s, with subsequent regulatory approvals in Europe and Asia-Pacific establishing multinational distribution frameworks. Workplace wellness mandates and pharmaceutical reimbursement policies now determine regional penetration rates.
United States
Integrated care networks and pharmacy benefit managers consolidate procurement power, steering formulary placement toward combination NRT regimens. FDA post-market surveillance mandates for neuropsychiatric adverse events tighten prescription protocols for varenicline. The Boston-Cambridge corridor hosts digital therapeutics developers pairing CBT applications with wearable biosensors.
Germany
Statutory health insurance coverage decisions drive adoption of prescription cessation aids, with the DiGA fast-track pathway creating reimbursement precedent for app-based behavioral interventions. EMA centralized marketing authorization requirements filter substandard OTC brands from distribution. Berlin anchors digital health startup clusters developing personalized tapering algorithms.
United Kingdom
NHS smoking cessation services integrate NRT products with behavioral counseling, generating consistent demand through primary care trusts. MHRA alignment with EMA safety documentation standards professionalizes supply chains. London's pharmaceutical corridor concentrates regulatory affairs expertise for combination product dossiers.
India
Contract manufacturing clusters in Hyderabad and Mumbai produce varenicline active pharmaceutical ingredients for global pharmaceutical companies. CDSCO marketing authorization requirements govern nicotine replacement therapy imports. Domestic OTC distribution networks expand gum and lozenge availability through pharmacy retail chains.
Japan
PMDA approval pathways for smoking cessation pharmaceuticals maintain stringent efficacy documentation requirements, limiting rapid product entry. Employer-sponsored health screening programs incorporate nicotine dependence assessment. The Kansai region hosts polymer science research facilities advancing transdermal delivery technologies.
Smoking Cessation Aids Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory sophistication. The market structures around three tiers: multinational pharmaceutical conglomerates with proprietary delivery technologies, generic manufacturers competing on manufacturing scale, and emerging digital therapeutics developers seeking reimbursement validation. Consolidation pressures intensify as pharmacy benefit managers demand single-vendor contracts bundling products with coaching services. Strategic moves center on regulatory dossier harmonization across jurisdictions and backward integration into active pharmaceutical ingredient supply.
Within the multinational pharmaceutical tier, Johnson & Johnson and Pfizer Inc. exemplify divergent strategic positions—one leveraging consumer health heritage in transdermal systems, the other anchoring prescription-grade portfolios through clinician-gated distribution. GlaxoSmithKline plc occupies a hybrid position spanning OTC gum and lozenge segments with established retail pharmacy presence. These three entities represent distinct archetypes: integrated health conglomerate, prescription-focused pharmaceutical developer, and diversified consumer healthcare operator.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Philip Morris International Inc. |
| Pfizer Inc. |
| Dr. Reddy's Laboratories Ltd |
| Perrigo Company plc |
| GlaxoSmithKline plc |
| British American Tobacco plc |
| Cipla Ltd |
| Haleon plc |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up generic manufacturers anchor the mid-tier supply base, consolidating patch and gum production capacity while enforcing cost discipline that compresses margins for standalone OTC brands. This ownership pattern concentrates bargaining power with pharmacy benefit managers, who leverage formulary placement to extract volume rebates that reshape downstream pricing hierarchies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market, with Johnson & Johnson's transdermal systems commanding brand premiums against private-label alternatives. Price differentiation hinges on FDA approval tier and polymer science sophistication, with smart patches sustaining premiums while commodity gum formats face cost compression from Indian contract manufacturers. Pricing pressure stems from Medicaid bulk procurement mandates, which favor lowest-bidder economics for 90-day combination regimens. Employer-sponsored health plans exhibit lowest price sensitivity, while uninsured retail purchasers drive economy-tier volume.
Supply Chain Analysis
Direct-to-patient mail fulfillment channels handle Medicare Advantage and employer-plan demand, displacing retail pharmacy dispensing for maintenance therapy. Active pharmaceutical ingredient production clusters in India and China, with varenicline synthesis concentrated among Hyderabad contract manufacturers. Polymer feedstocks for transdermal systems draw from German and Japanese specialty chemical suppliers. Single-source vulnerability in varenicline API supply exposes continuity risk from Indian manufacturing disruptions. Distribution runs through pharmacy benefit manager networks that consolidate purchasing across integrated care systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workplace wellness mandates and Medicaid expansion create a stable compounder profile, with employer-sponsored coverage embedding smoking cessation into recurring preventive care benefits that sustain demand through economic cycles.
For Market Incumbents: To counter heat-not-burn device substitution, Johnson & Johnson and Pfizer should deepen backward integration into nicotine API supply while accelerating smart patch R&D to differentiate pharmacological cessation from tobacco harm reduction. Channel control through exclusive pharmacy benefit manager contracts represents the critical defensive lever.
For New Entrants and Emerging Players: The gap between premium smart-patch pricing and economy gum tiers opens white-space targeting of Medicaid expansion states with combination kit offerings that bundle behavioral coaching. Digital therapeutics developers should pursue Germany's DiGA pathway as reimbursement precedent, then replicate the model in United States Medicare Advantage plans.
For Investors and Strategic Acquirers: Pharmaceutical conglomerates with consumer health divisions are the most active acquirer in this space, seeking digital therapeutics platforms to complement legacy NRT portfolios. Target acquisition archetypes include FDA-cleared CBT applications with existing payer contracts. Watch for EMA centralized marketing authorization rulings on combination product safety documentation as inflection signals for European market access costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA unified dossier requirements for combination NRT products filter substandard competitors from European distribution. |
| Backward Integration | Captive varenicline API production mitigates single-source concentration risk from Indian contract manufacturers. |
| Platform Integration | Smart patch-biosensor-CBT app convergence enables personalized tapering algorithms that extend adherence duration. |
| Reimbursement Strategy | Medicaid preventive service mandates in expansion states open bulk procurement channels for combination regimens. |
| Strategic Partnership | Pharmacy benefit manager single-vendor contracts bundle NRT products with telehealth coaching for employer plans. |
Study Parameters
Multiple input streams — regulatory filings, formulary databases, and pharmaceutical trade data — were reconciled through bottom-up and top-down triangulation. Primary interviews with pharmacy benefit managers, regulatory affairs directors at multinational pharmaceutical companies, formulary placement specialists, and digital therapeutics developers informed demand-side dynamics. Secondary validation drew from FDA New Drug Application filings, EMA centralized marketing authorization records, ClinicalTrials.gov protocols, and CMS Medicaid expansion state documentation.
Data-stream reconciliation anchored volume and value outputs across the analysis window, with segmentation modeling across product type, delivery mode, user demographics, and distribution channel dimensions. CAGRs were derived from trend extrapolation of employer-sponsored coverage expansion, Medicaid enrollment patterns, and digital therapeutics reimbursement precedent. Forecast inputs included workplace wellness mandate adoption curves and EMA pharmacovigilance documentation timelines for combination products.
Caveats apply where FDA neuropsychiatric labeling revisions or EMA safety documentation threshold changes could materially shift the outlook. Forecasts reflect assumptions about employer health plan benefit design stability and digital therapeutics classification clarity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Global Life Science Products Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Isolation Gowns Market