
 Global Healthcare Distribution Market | 2026-2036
Global Healthcare Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Distribution Market Foresight
Hospital procurement is shifting toward consolidated purchasing of specialty pharmaceuticals and biologics, compressing traditional generic volumes. McKesson Corporation leverages its direct-to-pharmacy automation networks to anchor high-value oncology distribution. Cencora competes through centralized specialty pharmacy services that sustain margin density in rare-disease categories. Cardinal Health differentiates via proprietary inventory analytics that control hospital formulary spend.
Healthcare distribution encompasses the physical movement, storage, and traceability of pharmaceuticals, medical devices, and clinical supplies from manufacturer to point of care, requiring temperature-validated cold chain infrastructure with continuous electronic monitoring. Its primary purpose is ensuring product integrity, regulatory compliance, and timely availability across acute and ambulatory settings. Pharmaceutical products occupy the largest value pool due to patent-protected pricing and stringent handling protocols, while cold chain logistics represents the fastest-growing service type as cell and gene therapies expand. Wholesale distributors retain structural dominance in channel control, though third-party logistics providers are capturing share in last-mile hospital delivery.
The FDA enforces track-and-trace serialization through the Drug Supply Chain Security Act, while the EU's Falsified Medicines Directive mandates end-to-end verification codes on prescription packs, compelling distributors to upgrade scanning infrastructure. The WHO's prequalification standards for temperature-controlled transport shape market access for vaccines and biologics in emerging supply routes. Stakeholders must monitor how serialization deadlines and carbon-accounting rules for pharmaceutical logistics reshape capital allocation toward compliant warehouse networks.
Market Dynamics
Specialty pharmaceutical cold chain infrastructure is forcing wholesale distributors to reallocate capital from generic volume throughput toward temperature-validated storage networks that handle cell and gene therapies.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization mandates compel distributors to deploy track-and-trace scanning infrastructure, creating recurring demand for compliance technology upgrades across wholesale networks.
- Biologics manufacturing concentration:Massachusetts, North Carolina, and Switzerland host dense clusters of biologics production facilities, generating localized demand for specialized last-mile distribution services.
- EU Falsified Medicines Directive:End-to-end verification requirements on prescription packs drive investment in authentication infrastructure throughout European wholesale channels.
Market Restraints
- Refrigerant input volatility:Cold chain operations depend on hydrofluorocarbon refrigerants subject to F-Gas Regulation phase-down schedules, compressing margin predictability for temperature-controlled logistics providers.
- Single-source equipment dependency:Validated thermal packaging for cell therapies relies on proprietary phase-change materials from limited qualified suppliers, concentrating supply risk.
- Substitution by direct manufacturer distribution:Oncology and rare-disease manufacturers are building captive distribution capabilities, bypassing traditional wholesale channels for high-value therapies.
Strategic Opportunities
- India's cold chain gap:Temperature-controlled vaccine distribution infrastructure remains underdeveloped outside major metros, creating white space for WHO-prequalified logistics networks.
- Real-time location systems convergence:Integration of IoT sensors with blockchain verification is modularizing custody documentation, enabling premium service tiers for high-value biologics.
- Japan's regenerative medicine pipeline:PMDA-accelerated approval pathways for iPSC-derived therapies are expanding demand for cryogenic distribution capabilities.
Industry Challenges
- Qualified personnel scarcity:GDP (Good Distribution Practice) certification requirements for handling temperature-sensitive biologics outpace available trained warehouse operators, extending onboarding timelines.
- Legacy warehouse management system integration:Serialization data streams from FDA-mandated track-and-trace protocols conflict with existing ERP architectures, requiring expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Distribution Market |
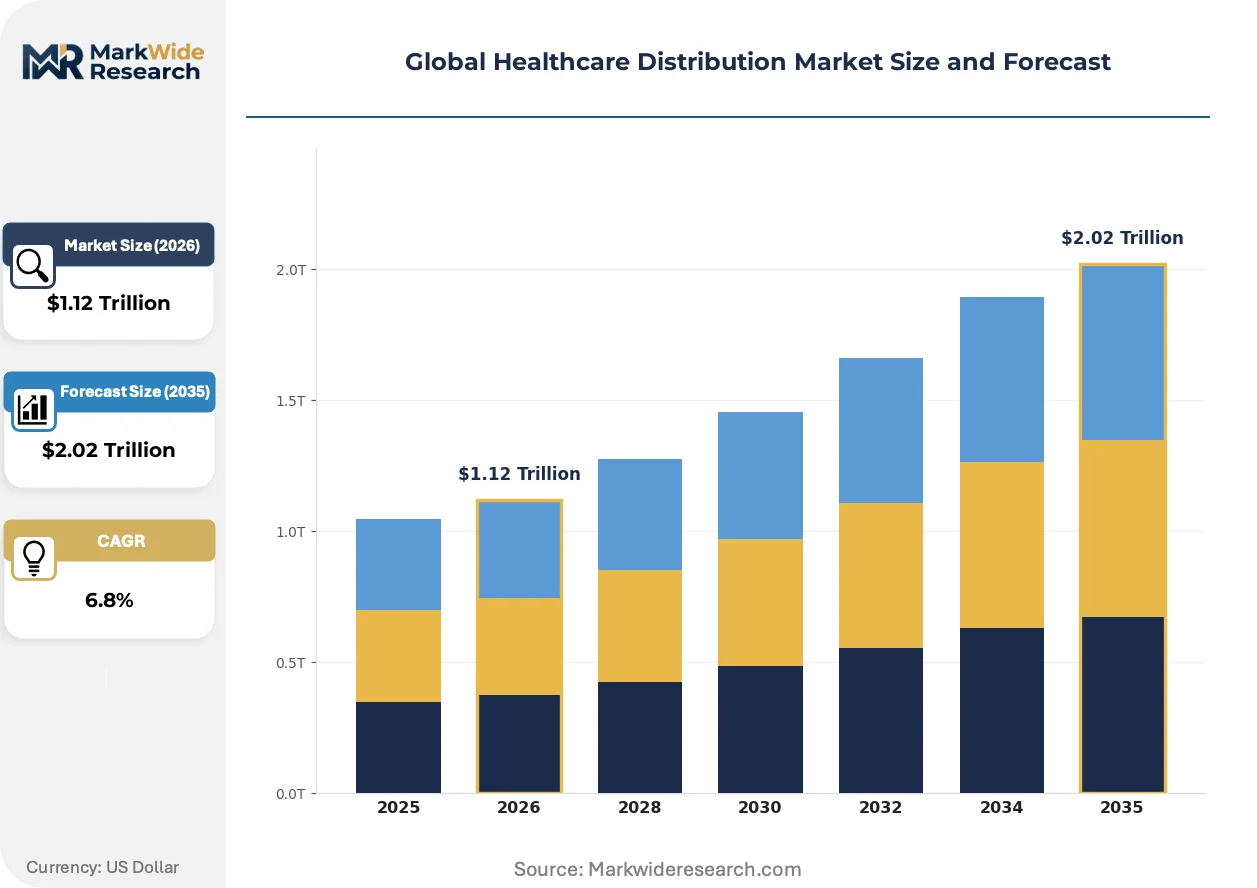
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $2.02 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Medical Devices, Diagnostic Equipment, Laboratory Supplies, Personal Protective Equipment Distribution Channel: Wholesale Distributors, Direct Sales, Online Pharmacies, Retail Pharmacies, Third-Party Logistics End User: Hospitals, Clinics, Diagnostic Centers, Home Healthcare Services, Nursing Facilities Service Type: Inventory Management, Cold Chain Logistics, Order Fulfillment, Supply Chain Consulting, Transportation Management |
| Companies Covered | McKesson Corporation, Cencora, Cardinal Health, Owens & Minor, PHOENIX Group, Shanghai Pharmaceutical Group, Medline Industries, Henry Schein, FFF Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Distribution Market Shifts & Advancements
Distribution networks are reconfiguring around patient-centric therapy administration, compressing traditional hospital-centric supply models into direct-to-site delivery for specialized treatments.
Modular cold chain containers with embedded IoT telemetry are modularizing temperature assurance for cell and gene therapies. Hospital pharmacy buyers in the United States and Germany are adopting these units for on-site storage of CAR-T inventories. The technology is modularizing what previously required centralized specialty pharmacy infrastructure, enabling distributed administration sites.
REACH authorization requirements for pharmaceutical packaging materials are restricting polymer compositions used in secondary containers. Distributors serving EU markets must validate alternative barrier films that maintain product stability. Cold chain service providers with pre-validated compliant packaging are capturing preferential contracts from manufacturers.
Hospital formulary committees are consolidating purchasing authority for specialty pharmaceuticals into centralized procurement functions, displacing decentralized pharmacy buying. Integrated delivery networks in the United States are unbundling distribution services from drug pricing, negotiating transparent logistics fees separately from product acquisition costs. This pattern is most pronounced in oncology and immunology categories where biosimilar competition intensifies price scrutiny.
Global Healthcare Distribution Market Segmentation
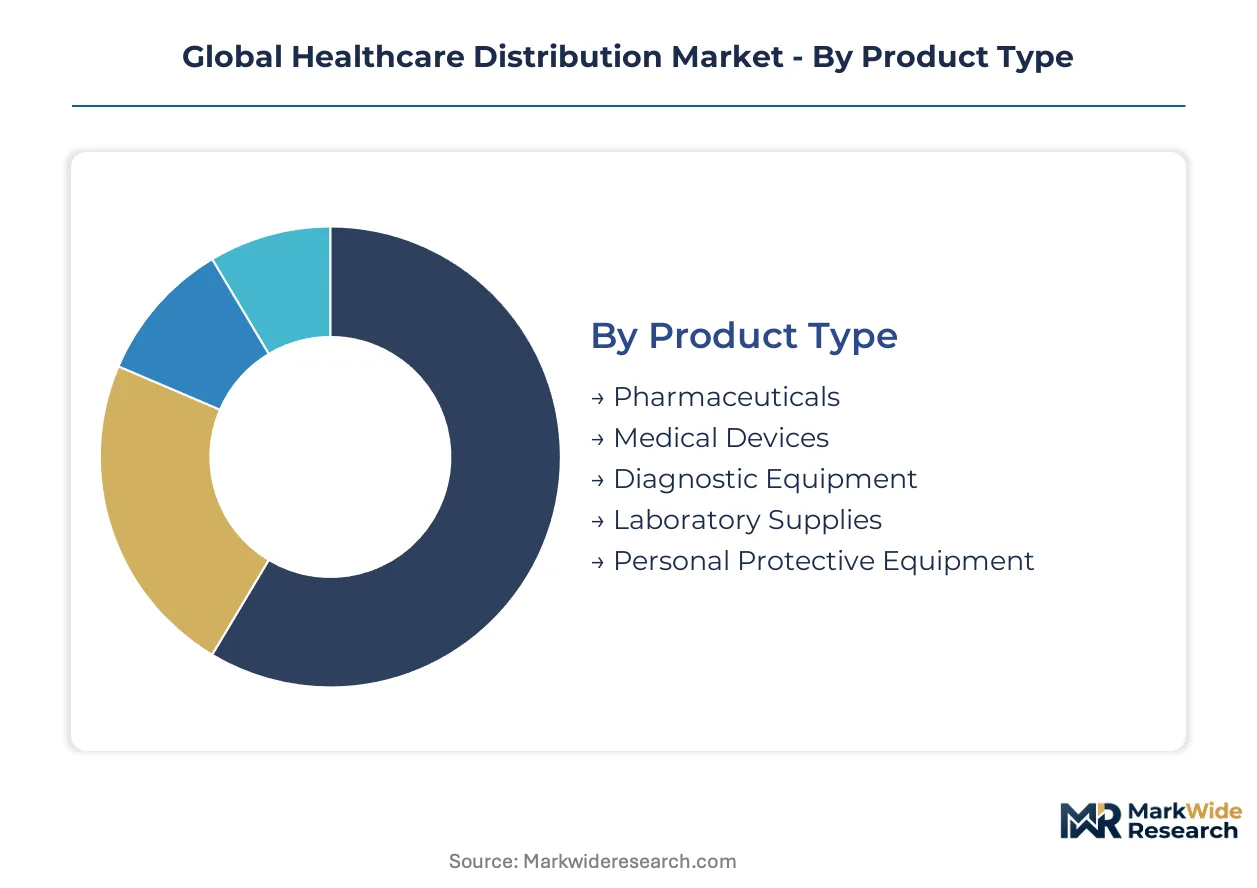
Segmentation in healthcare distribution separates capital deployment strategies from revenue capture opportunities. Product mix and channel structure determine which players capture margin in temperature-sensitive versus commodity flows.
Product Type:
Pharmaceuticals demand the heaviest capital investment due to serialization infrastructure and validated cold storage requirements.
- Pharmaceuticals:Patent-protected small molecules and biologics require continuous temperature monitoring and FDA-compliant track-and-trace systems. Hospital procurement in the United States and Germany concentrates spending here as oncology and immunology portfolios expand.
- Medical Devices:Implantables and surgical instruments move through consignment inventory models that tie up distributor working capital. Demand clusters around cardiac and orthopedic procedure volumes in tertiary hospitals.
- Diagnostic Equipment:Capital equipment with extended sales cycles and installation protocols.
- Laboratory Supplies:Consumables with high purchase frequency but compressed margins.
- Personal Protective Equipment:Standardized products with price-sensitive hospital contracting.
Pharmaceuticals absorb the bulk of installed capacity; cold chain-enabled biologics within this segment are expanding most quickly.
Distribution Channel:
Channel selection determines regulatory burden and customer intimacy levels, with direct models capturing high-value therapy flows.
- Wholesale Distributors:McKesson and Cencora maintain national warehousing networks with DEA-controlled substance licenses. These incumbents face margin pressure as manufacturers bypass them for specialty therapies.
- Direct Sales:Oncology and rare-disease manufacturers deploy captive field forces and temperature-controlled vehicles to hospital infusion centers. Switzerland and Massachusetts host dense clusters of such operations.
- Online Pharmacies:Digital platforms with automated dispensing and last-mile delivery partnerships.
- Retail Pharmacies:Community-based dispensing with limited cold chain reach.
- Third-Party Logistics:Asset-light providers specializing in hospital dock-to-dock delivery.
Wholesale distributors retain the deepest infrastructure footprint; direct sales channels are gaining share fastest in high-value categories.
End User:
End-user concentration shapes inventory positioning, with acute care sites demanding the most responsive replenishment cycles.
- Hospitals:Integrated delivery networks in the United States consolidate formulary purchasing through centralized procurement functions. These buyers unbundle logistics fees from drug acquisition costs, pressuring distributor transparency.
- Clinics:Ambulatory settings with limited on-site storage drive demand for frequent small-lot delivery.
- Diagnostic Centers:Imaging and pathology facilities with reagent supply requirements.
- Home Healthcare Services:Patient-administered therapies requiring direct-to-patient cold chain.
- Nursing Facilities:Long-term care with generic-heavy medication profiles.
Hospitals command the largest logistics spend per site; home healthcare services are climbing the fastest as infusion therapy shifts to residential settings.
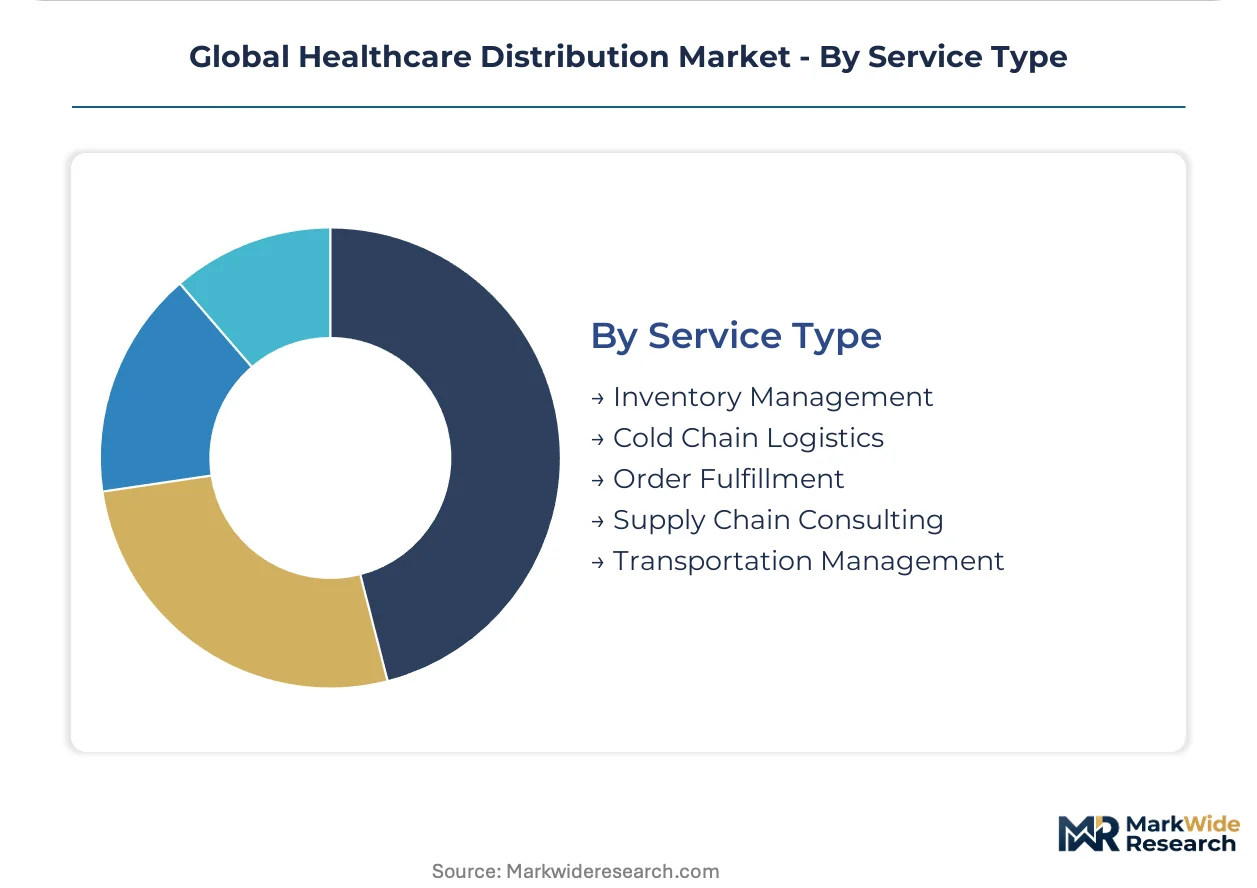
Service Type:
Service tiering separates commodity transportation from value-added offerings that manufacturers and providers will pay premiums to secure.
- Cold Chain Logistics:Cryogenic and refrigerated transport with GDP certification and real-time IoT telemetry. Cell and gene therapy manufacturers in Japan and Switzerland contract these services under stringent qualification protocols.
- Inventory Management:Vendor-managed inventory and consignment models that reduce hospital working capital needs.
- Order Fulfillment:Same-day and next-day delivery with barcode verification.
- Supply Chain Consulting:Network optimization and demand forecasting for manufacturers.
- Transportation Management:Route planning and carrier procurement for non-temperature-controlled freight.
Cold chain logistics captures the steepest expansion trajectory as regenerative medicine pipelines mature; inventory management retains the broadest installed base across hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing clusters concentrate supply-side infrastructure in Massachusetts, North Carolina, and Switzerland, while aging demographics in Germany, Japan, and China drive consumption-side distribution demand.
United States
Integrated delivery networks in Texas and Florida consolidate specialty pharmaceutical procurement through centralized formulary committees. The FDA's Drug Supply Chain Security Act mandates track-and-trace serialization upgrades across wholesale networks. Massachusetts hosts dense biologics manufacturing clusters that generate localized cold chain demand for cell and gene therapies.
Germany
Hospital pharmacy buyers in Bavaria and North Rhine-Westphalia unbundle logistics fees from drug acquisition costs under pressure from biosimilar competition. The EU's Falsified Medicines Directive enforces end-to-end verification codes on prescription packs throughout wholesale channels. The Rhine-Main region anchors European distribution infrastructure for temperature-sensitive oncology products.
China
Chronic disease prevalence in coastal provinces intensifies pressure on pharmaceutical distribution infrastructure serving tertiary hospitals. The NMPA tightens Good Distribution Practice standards for vaccine cold chain logistics. Shanghai Pharmaceutical Group leverages regional hub networks to penetrate underserved western provinces.
Japan
PMDA-accelerated approval pathways for iPSC-derived therapies expand demand for cryogenic distribution capabilities in Kanto and Kansai regions. The country's national pharmaceutical regulator enforces stringent temperature validation protocols for regenerative medicine shipments. Osaka-based biotech clusters drive specialized last-mile delivery requirements for clinical trial materials.
India
Temperature-controlled vaccine distribution infrastructure remains underdeveloped outside Mumbai, Delhi, and Bangalore metros. CDSCO alignment with WHO prequalification standards shapes market access for imported biologics. Hyderabad's vaccine manufacturing corridor generates outbound cold chain demand for international distribution.
Global Healthcare Distribution Market Competitive Landscape
Top-tier vendors anchor national warehousing networks with DEA-controlled substance licenses, while mid-tier specialists concentrate on regional cold chain capabilities. Wholesale distributors face margin compression as manufacturers bypass traditional channels for high-value therapies. Three archetypes dominate: integrated wholesale networks, specialty pharmacy service providers, and third-party logistics operators. M&A activity targets cold chain infrastructure assets, while strategic partnerships with biologics manufacturers secure long-term distribution contracts.
Among North American wholesale distributors, McKesson Corporation, Cencora, and Cardinal Health exemplify the integrated network archetype. McKesson leverages direct-to-pharmacy automation infrastructure. Cencora occupies a position in centralized specialty pharmacy services. Cardinal Health represents the analytics-driven formulary management segment. These three entities collectively illustrate how scale, specialization, and technology differentiation separate viable competitors from commodity logistics providers.
| Leading Market Players |
|---|
| McKesson Corporation |
| Cencora |
| Cardinal Health |
| Owens & Minor |
| PHOENIX Group |
| Shanghai Pharmaceutical Group |
| Medline Industries |
| Henry Schein |
| FFF Enterprises |
| Others |
Supply & Pricing Matrix
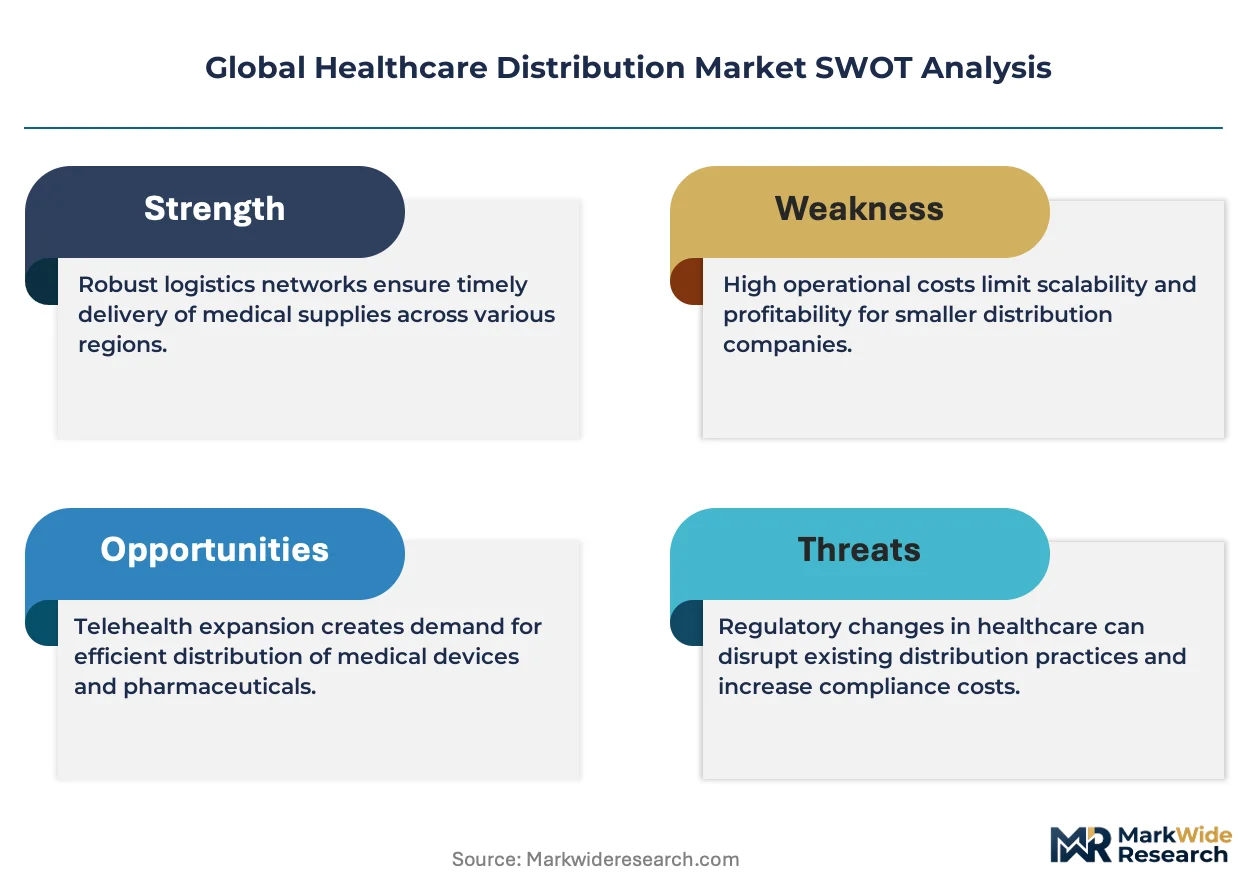
Cold chain certification tiers bifurcate the market into GDP-validated premium services and commodity generic distribution, with this divergence manifesting in both pricing power and warehouse network configuration. Manufacturers of cell and gene therapies in Massachusetts and Switzerland pay substantial premiums for cryogenic handling protocols, while generic pharmaceutical flows compete on spot pricing with minimal value-added services.
Pricing Analysis
Lead-time compression commands premium pricing in the specialty pharmaceutical tier, with same-day delivery to hospital infusion centers carrying significant markups over standard next-day schedules. Three-tier pricing structure across premium, standard, and economy levels separates GDP-certified cold chain services from temperature-monitored standard freight and unvalidated generic transport. Pricing pressure stems from biosimilar competition in oncology categories, compressing margins for traditional wholesale distributors. Hospital procurement committees demonstrate highest price sensitivity in generic categories, while rare-disease manufacturers show minimal elasticity for qualified cold chain services.
Supply Chain Analysis
Workforce scarcity for GDP-certified operators constrains capacity expansion in Massachusetts, North Carolina, and Switzerland, where biologics manufacturing clusters concentrate. Supply chains draw from proprietary phase-change material suppliers in Germany and Japan for validated thermal packaging, alongside domestic refrigerant producers subject to F-Gas Regulation phase-down schedules. Single-source dependency for qualified cold chain equipment creates vulnerability to regulatory restriction on hydrofluorocarbon availability. Distribution runs through wholesale networks with DEA-controlled substance licenses, though direct manufacturer channels are capturing high-value therapy flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as serialization compliance costs and cold chain capital requirements force sub-scale distributors toward exit or acquisition. FDA Drug Supply Chain Security Act mandates are accelerating this pressure by imposing infrastructure investments that smaller players cannot absorb.
For Market Incumbents: To counter manufacturer bypass of wholesale channels, deploy backward integration into specialty pharmacy services and deepen cold chain capacity in biologics manufacturing clusters. McKesson Corporation and Cencora demonstrate this playbook through direct-to-pharmacy automation and centralized rare-disease distribution. Lock in long-term contracts with cell and gene therapy developers before captive distribution capabilities mature.
For New Entrants and Emerging Players: Begin with India's temperature-controlled vaccine distribution gap outside Mumbai, Delhi, and Bangalore metros, where WHO-prequalified logistics networks remain underdeveloped. Target third-party logistics partnerships with regional hospital systems seeking dock-to-dock delivery alternatives to wholesale incumbents. Build GDP-certified cold chain capabilities as the primary go-to-market credential.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier cold chain specialists given PMDA-accelerated regenerative medicine approvals in Japan and cryogenic distribution demand expansion. Long-term viability favors asset-light operators with modular IoT-enabled container technology over capital-heavy warehouse networks. Watch for inflection in direct manufacturer distribution announcements as signal of wholesale channel displacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Acquisition | GDP-certified warehouse networks in Massachusetts and Switzerland capture biologics manufacturing proximity premiums. |
| Track-and-Trace Technology Deployment | FDA-mandated serialization upgrades create recurring compliance revenue streams across wholesale networks. |
| Specialty Pharmacy Service Integration | Centralized rare-disease distribution sustains margin density as generic volumes commoditize. |
| Direct-to-Site Delivery Partnership | Hospital infusion center relationships bypass traditional wholesale channels for oncology therapies. |
| Modular IoT Container Development | Embedded telemetry enables distributed CAR-T administration without centralized specialty pharmacy investment. |
Research Methodology
Independent corroboration across hospital procurement managers, pharmaceutical supply chain directors, and cold chain logistics operators underwrites the qualitative findings in this analysis. Primary interviews with formulary committee members, GDP-certified warehouse supervisors, and biologics manufacturing supply chain leads combined with secondary validation from FDA DSCSA guidance documents, EMA falsified medicines directives, and WHO prequalification standards. Bottom-up capacity assessments and top-down spending pattern analysis triangulate market sizing across temperature-controlled and ambient distribution segments.
Rate-of-change decomposition separates volume growth from mix shift toward higher-value cold chain services across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end-user setting, and service tier, with additional granularity on regulatory compliance requirements by geography. CAGRs derive from installed base expansion in biologics manufacturing clusters and penetration rates for serialization infrastructure. Forecast inputs incorporate PMDA approval pathway velocity for regenerative medicines and F-Gas Regulation phase-down schedules affecting refrigerant availability.
Underlying measurement precision varies by segment; cold chain logistics carries tighter precision than commodity generic distribution due to visible contract structures and qualification protocols. Forecasts reflect assumptions on manufacturer distribution channel selection and regulatory deadline adherence. Material deviation in FDA enforcement intensity or biologics manufacturing location decisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Medical Products Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Nursing Products Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Smoking Cessation Aids Market