
 Europe Blood and Blood Components Market | 2026-2036
Europe Blood and Blood Components Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Blood and Blood Components Market Analysis
Component processing and pathogen-reduction service revenue is rewriting margin economics across the value chain. Grifols S.A. leverages its plasma fractionation footprint to sustain high-throughput output across Iberian and Central European nodes. Octapharma AG anchors specialized protein concentrate supply for hemophilia and immunodeficiency indications. NHS Blood and Transplant competes on volume reliability through its vertically integrated collection-to-distribution architecture.
Blood and blood components comprise cellular and plasma-derived therapeutic materials collected from voluntary donors, processed under controlled temperature conditions, and screened for infectious markers before clinical use. Whole blood separates into red blood cells, platelets, and plasma fractions, each requiring distinct storage parameters ranging from refrigerated to frozen states. Plasma dominates value contribution due to fractionation into immunoglobulins and albumin for chronic disease management. Red blood cells maintain the highest transfusion volume across surgery and trauma care applications, though platelet segments are gaining share in oncology support protocols. Research laboratories represent an emerging demand node as cell therapy manufacturing expands its feedstock requirements.
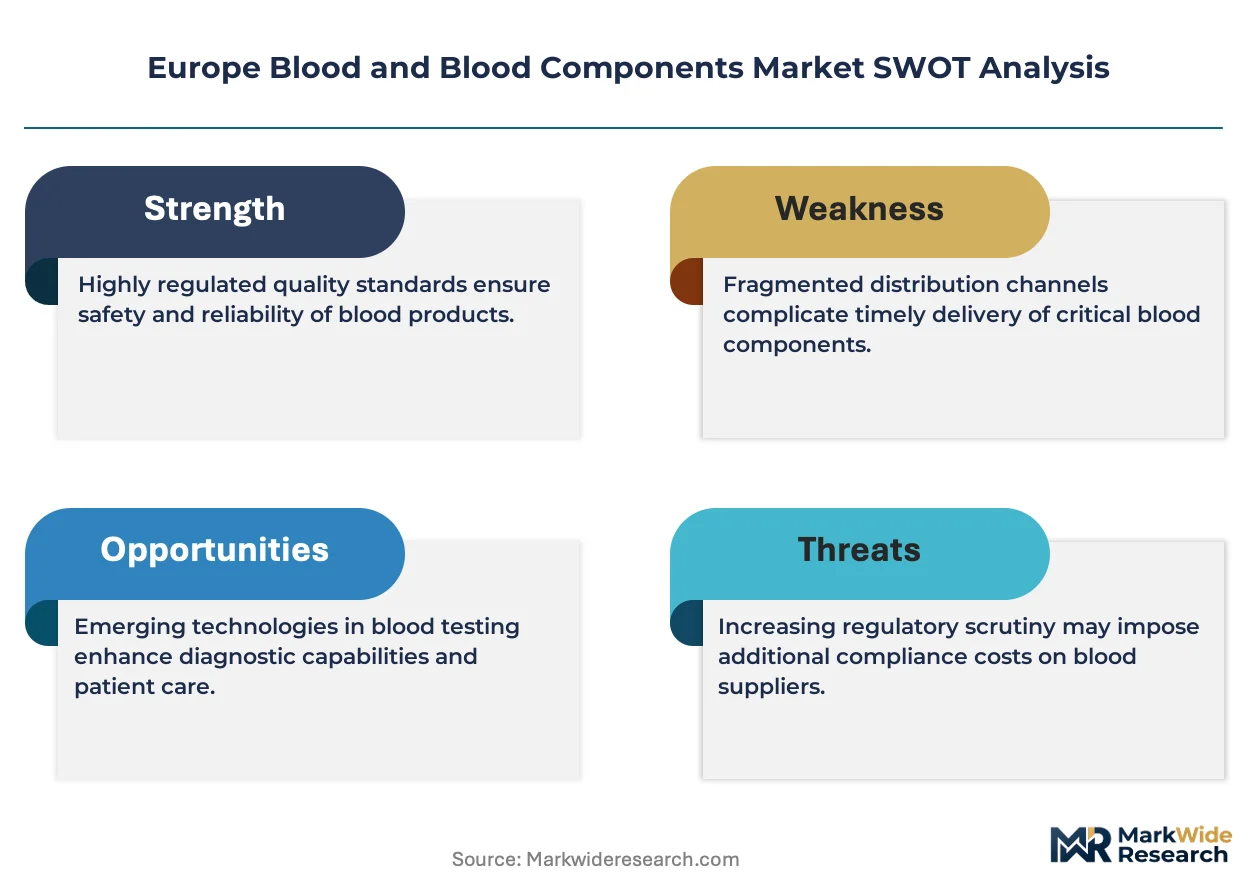
EMA oversight of blood product quality standards intersects with EU Blood Directive harmonization requirements and national health authority licensing across member states, creating a layered compliance environment that favors operators with established quality management systems. The F-Gas Regulation and CE marking requirements for automated collection devices further shape equipment procurement decisions. Stakeholders must weigh pathogen inactivation technology investments against evolving reimbursement frameworks for processed versus standard blood components.
Market Dynamics
The EU Blood Directive revision is compressing collection-to-clinic timelines while mandating universal pathogen inactivation, forcing blood establishments to retool processing infrastructure across member states.
Growth Catalysts
- Immunotherapy expansion:CAR-T manufacturing facilities in Germany and France require platelet and plasma feedstock at volumes exceeding traditional transfusion medicine, pulling supply toward cell therapy producers.
- F-Gas Regulation compliance:Cold-chain equipment upgrades across Spain and Italy are modernizing storage infrastructure, reducing spoilage rates in plasma fractionation nodes.
- CE marking acceleration:Automated apheresis devices with integrated leukoreduction are shortening donor session times, expanding eligible donor pools in urban collection centers.
Market Restraints
- Plasma dependency on US imports:European fractionators source over half of raw plasma from US-paid donor networks, exposing margin structures to transatlantic logistics volatility and tariff exposure.
- Donor base stagnation:Aging demographics in Italy and Poland are shrinking the voluntary donor pool faster than recruitment campaigns replenish it, constraining collection volume growth.
- Albumin substitution pressure:Synthetic colloid solutions for volume expansion in trauma protocols are displacing plasma-derived albumin in select Eastern European hospital formularies.
Strategic Opportunities
- Romania and Bulgaria hospital network buildout:EU cohesion funds are financing regional blood bank infrastructure in underserved Southeast European catchment areas, creating first-mover collection contracts.
- Pathogen-reduced platelet mandate:The EU Blood Directive's 2025 implementation timeline for bacterial screening and inactivation is mandating technology upgrades that favor operators with installed amotosalen or riboflavin systems.
- Research laboratory channel:Cell therapy CDMOs in Belgium and the Netherlands are contracting directly with blood establishments for GMP-grade starting material, bypassing traditional hospital distribution.
Industry Challenges
- Qualified technician scarcity:Specialized immunohematology and apheresis operator certifications require 18-24 month training pipelines that blood establishments struggle to fill across Scandinavia and the Baltics.
- Legacy IT integration:National donor registries in France, Germany, and the UK operate on incompatible data architectures, complicating cross-border emergency supply coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Blood and Blood Components Market |
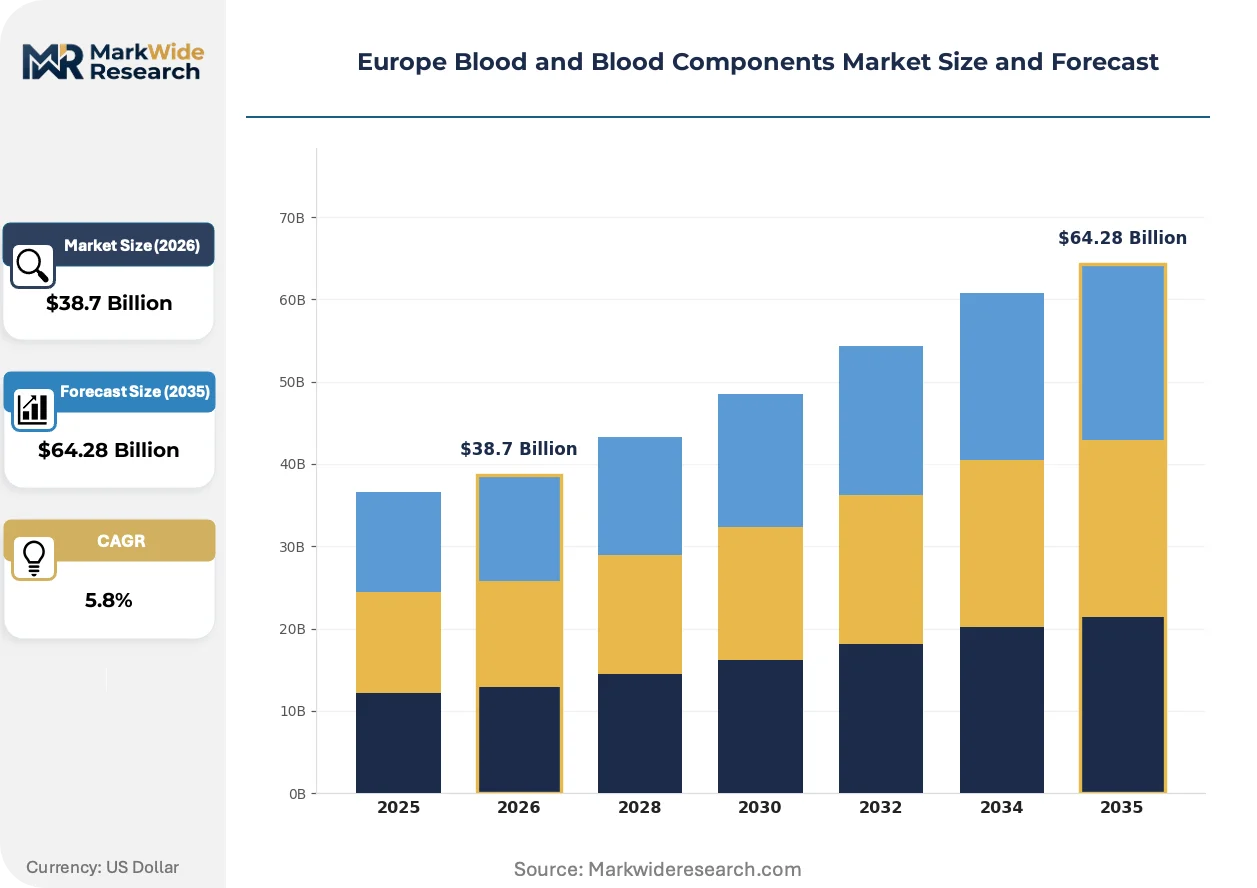
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Blood, Plasma, Red Blood Cells, Platelets Application: Transfusion, Surgery, Trauma Care, Cancer Treatment End User: Hospitals, Blood Banks, Clinics, Research Laboratories Delivery Mode: Direct Delivery, Transport Logistics, Cold Chain, Online Ordering |
| Companies Covered | Grifols S.A., MacoPharma International GmbH, NHS Blood and Transplant, European Blood Alliance, Northern Ireland Blood Transfusion Service, Becton, Dickinson & Co., Cerus Corporation, Octapharma AG, Policlinico of Milan, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Blood and Blood Components Market Emerging Trajectories
Processing technology and donor management systems are converging to reshape how blood components move from collection to clinical application, with automation and data integration as the dominant vectors.
Automated whole blood processing with integrated leukoreduction is collapsing manual separation workflows that previously required multiple handling steps and separate filtration stages. Blood establishments in the Netherlands and Denmark are deploying these closed systems at scale, reducing labor hours per unit by half while compressing contamination risk windows. The structural consequence is margin pressure on smaller regional blood banks lacking capital for platform upgrades.
REACH and the EU Green Deal are tightening chemical disclosure requirements for plasticizer-containing blood bags and tubing sets, forcing manufacturers toward bio-based alternatives. Component suppliers must reformulate PVC formulations or shift to ethylene vinyl acetate copolymers, with ECHA substance evaluation driving substitution timelines. Blood establishments in Germany and Austria are prioritizing suppliers with certified sustainable polymer supply chains in procurement specifications.
Hospital blood bank inventory management is migrating to vendor-managed consignment models, with suppliers placing automated refrigerated storage units on customer premises and retaining ownership until point-of-use. This shifts working capital burden from stretched hospital finance departments to fractionators and blood establishments, with the model most advanced in Swiss and Austrian integrated delivery networks. The arrangement is compressing traditional distributor margins while locking in volume commitments through exclusive supply contracts.
Europe Blood and Blood Components Market Segmentation
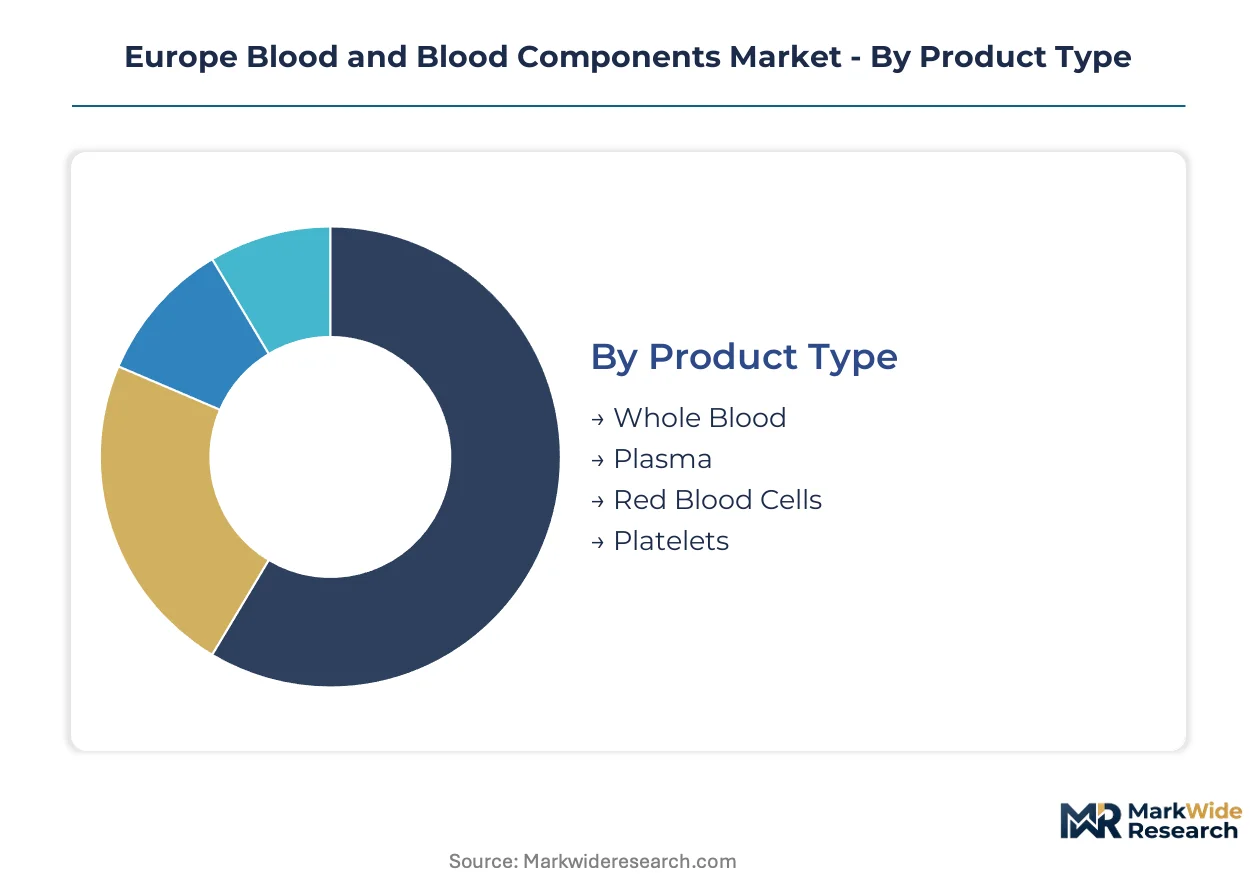
Blood component turnover varies dramatically by product type, with platelets requiring five-day rotation cycles while plasma fractions sustain multi-year frozen storage. Understanding these velocity differentials shapes inventory financing, cold-chain infrastructure sizing, and margin capture strategies across European blood establishments.
Product Type:
Cycle times compress from years to days across this spectrum, with frozen plasma at one extreme and room-temperature platelets at the other.
- Plasma:Source material for immunoglobulin and albumin fractionation, stored frozen at -25°C for up to 36 months. Demand concentrates in German and Spanish fractionation facilities where chronic disease management protocols drive immunoglobulin consumption.
- Platelets:Five-day shelf life at 20-24°C with continuous agitation creates the tightest logistics constraints. Oncology centers in France and Belgium pull supply toward CAR-T manufacturing feedstock as cell therapy production scales.
- Whole Blood:Twenty-one to thirty-five day refrigerated shelf life supports military and rural emergency protocols where component separation is impractical.
- Red Blood Cells:Forty-two day refrigerated storage dominates transfusion volume for surgical and trauma applications across Western European hospital networks.
Red blood cells anchors the volume base while platelets gains share at the steepest rate.
Application:
Reimbursement intensity and clinical outcome metrics separate high-margin therapeutic applications from commodity transfusion services.
- Cancer Treatment:Myelosuppressive chemotherapy and hematopoietic stem cell transplantation create sustained platelet and plasma demand. German university hospitals are expanding apheresis collection capacity to serve in-house oncology protocols.
- Trauma Care:Massive transfusion protocols favor balanced component ratios with plasma and platelets administered alongside red blood cells. Regional trauma networks in Italy and Spain are standardizing blood bank staffing for 24/7 activation.
- Surgery:Elective procedures allow pre-operative autologous donation and directed donation programs, reducing allogeneic transfusion exposure.
- Transfusion:Chronic anemia management in thalassemia and sickle cell populations requires scheduled red blood cell exchange programs.
Cancer treatment commands premium pricing while trauma care expands most quickly as regional systems consolidate.
End User:
Customer sophistication and regulatory burden scale from research laboratories with GMP-grade specifications to high-volume hospital transfusion services.
- Hospitals:Integrated blood bank infrastructure with cross-matching capabilities and therapeutic apheresis services. French public hospital networks are consolidating blood bank operations into regional hub-and-spoke configurations.
- Research Laboratories:Cell therapy CDMOs in Belgium and the Netherlands contract directly for leukapheresis starting material, bypassing traditional distribution channels.
- Blood Banks:National collection services with vertically integrated testing, processing, and distribution architectures.
- Clinics:Outpatient transfusion centers for chronic anemia and hemophilia prophylaxis, dependent on regional blood bank supply contracts.
Hospitals retain the dominant volume position while research laboratories climb the fastest as cell therapy manufacturing scales.
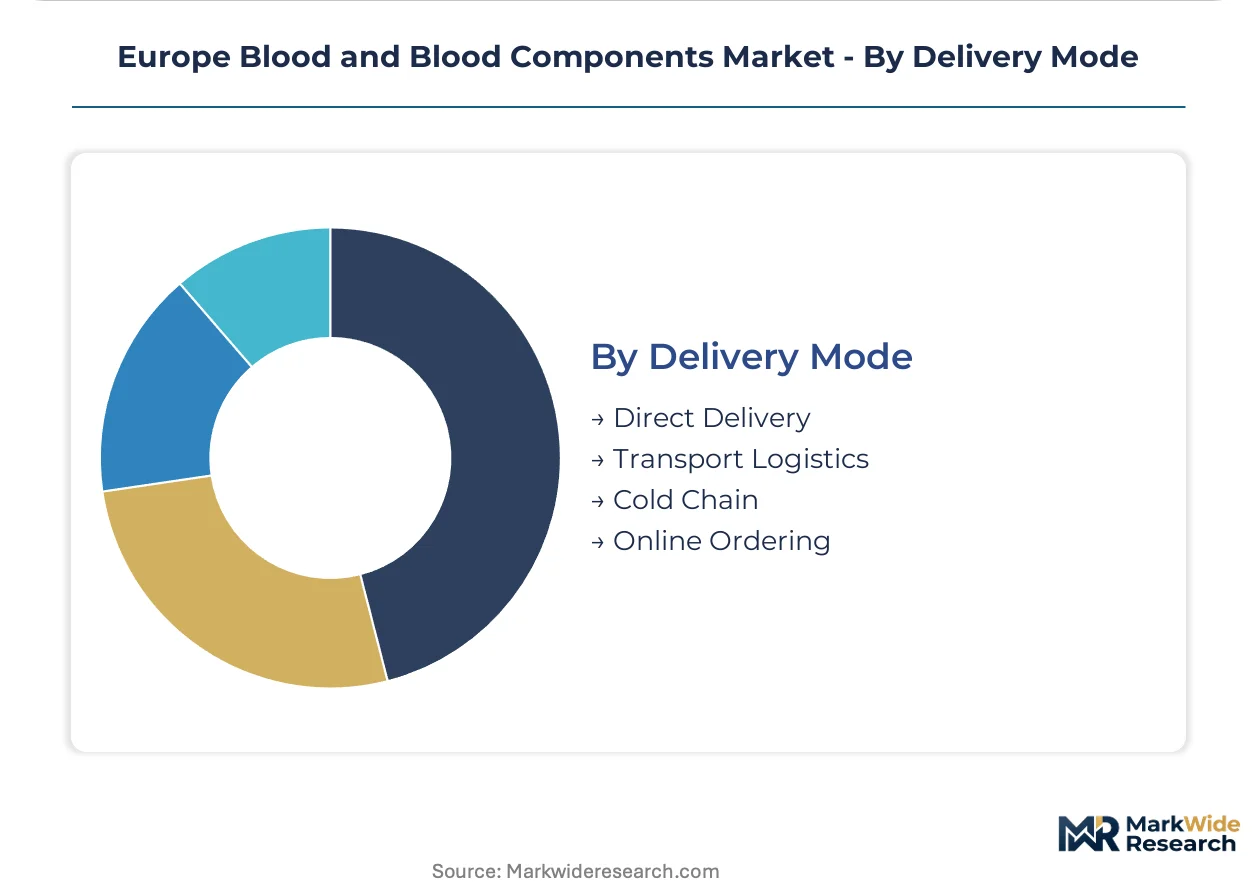
Delivery Mode:
Temperature integrity requirements and urgency tiers segment logistics capabilities from routine scheduled replenishment to emergency helicopter transport.
- Cold Chain:Validated 2-8°C and frozen transport with continuous temperature monitoring and deviation documentation. EMA GDP guidelines mandate qualification of third-party logistics providers across all member states.
- Direct Delivery:Hospital-based blood bank inventory with consignment models transferring ownership at point-of-use, most advanced in Swiss and Austrian integrated delivery networks.
- Transport Logistics:Scheduled courier services for inter-facility transfers and regional distribution from processing centers.
- Online Ordering:Electronic blood bank inventory management with automated reorder triggers and real-time availability visibility.
Cold chain underpins safety compliance while direct delivery reshapes working capital allocation fastest across European hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across European blood markets. German hospital networks absorb premium pathogen-reduced components with minimal resistance, while Polish and Romanian procurement offices negotiate aggressively on standard red blood cell unit costs.
Germany
Oncology centers in Munich and Heidelberg drive platelet demand for CAR-T manufacturing feedstock. The German Medical Devices Act (MPG) transposes MDR requirements for automated collection device certification. Bavarian blood establishments are consolidating testing laboratories into regional hubs serving multiple university hospitals.
France
Parisian hospital networks maintain the densest apheresis collection capacity per capita in Europe. ANSM enforces bacterial screening mandates ahead of the EU Blood Directive timeline. The Île-de-France region hosts specialized plasma fractionation capacity serving chronic immunodeficiency patient populations.
United Kingdom
NHS Blood and Transplant operates the continent's most vertically integrated collection-to-distribution architecture. MHRA oversight of blood product quality standards intersects with national hemovigilance reporting requirements. Scottish blood processing facilities are upgrading cold-chain infrastructure to reduce plasma wastage rates.
Spain
Catalan blood banks face donor recruitment pressure from aging Barcelona metropolitan demographics. F-Gas Regulation compliance deadlines are accelerating refrigeration equipment replacement across Madrid and Valencia processing centers. Andalusian regional health services are piloting vendor-managed inventory models for hospital blood bank consignment.
Italy
Lombardy trauma networks consume disproportionate platelet volumes for massive transfusion protocols. ECHA substance evaluation is driving blood bag manufacturers toward bio-based polymer alternatives. Policlinico of Milan anchors specialized hemophilia treatment capacity with dedicated factor concentrate supply chains.
Europe Blood and Blood Components Market Vendor Landscape
Capability concentration sits with specialized fractionators possessing plasma protein purification expertise; scale advantage sits with national blood services commanding donor base access. The market structures around three tiers: multinational plasma processors with cross-border fractionation networks, state-affiliated collection monopolies with territorial exclusivity, and equipment-technology vendors supplying processing automation. Consolidation pressure is mounting as pathogen inactivation mandates require capital upgrades that smaller regional blood banks cannot self-finance.
Within the multinational processor tier, Grifols S.A. and Octapharma AG occupy positions defined by Iberian and Central European plasma fractionation footprints respectively. NHS Blood and Transplant exemplifies the state-integrated model with captive donor recruitment and hospital distribution control. Among technology suppliers, Cerus Corporation and Becton, Dickinson & Co. represent the pathogen reduction and automated collection device archetypes that blood establishments must source to meet tightening EU regulatory standards.
| Leading Market Players |
|---|
| Grifols S.A. |
| MacoPharma International GmbH |
| NHS Blood and Transplant |
| European Blood Alliance |
| Northern Ireland Blood Transfusion Service |
| Becton, Dickinson & Co. |
| Cerus Corporation |
| Octapharma AG |
| Policlinico of Milan |
| Others |
Supply Flow & Price Mechanics
Transatlantic tariff exposure on US-sourced raw plasma determines both tiered pricing spreads across European fractionators and the shape of supply chain investments in domestic collection infrastructure. Blood establishments face margin compression when import costs spike, forcing differentiation between premium pathogen-reduced components and standard inventory.
Pricing Analysis
Service and extended supply contracts drive lifetime value more than per-unit component sales. Three-tier pricing structure across premium pathogen-reduced, standard processed, and economy unmodified components separates German university hospitals from Polish regional clinics. Price differentiation rests on CE marking tier and integrated leukoreduction certification. Cost compression in standard red blood cell units is intensifying because synthetic colloid substitutes displace plasma-derived albumin in Eastern European trauma protocols. Polish procurement offices exhibit highest price sensitivity; Swiss integrated delivery networks absorb premiums with minimal negotiation.
Supply Chain Analysis
Fractionation capacity concentrates at Grifols Iberian nodes and Octapharma Central European facilities. Geographic supply concentration spans Germany, Spain, and Austria for plasma processing, with Italy and France anchoring platelet agitation and distribution. Raw material dependencies include US-paid donor plasma, bio-based polymer blood bags compliant with REACH, and riboflavin pathogen inactivation reagents. Single-source vulnerability on transatlantic plasma shipments threatens margin stability. Distribution runs through national blood services with hospital consignment models transferring ownership at point-of-use.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic colloid volume expanders and recombinant protein substitutes threaten plasma-derived albumin demand, forcing incumbents to defend substitution economics through clinical outcome differentiation.
For Market Incumbents: Pre-empt synthetic displacement by embedding pathogen-reduced plasma into massive transfusion protocols where clinical guidelines favor allogeneic components. Secure backward integration into domestic apheresis collection across Romania and Bulgaria before EU cohesion fund infrastructure matures. Grifols and Octapharma must lock hospital consignment contracts in Swiss and Austrian networks to freeze out challenger fractionators. For New Entrants and Emerging Players: Southeast European hospital network buildout in Romania and Bulgaria represents the most penetrable entry point where EU cohesion funds finance greenfield blood bank infrastructure. Cell therapy CDMO channels in Belgium and Netherlands offer direct contracting bypass of established distribution. A GMP-grade leukapheresis specialization with research laboratory accreditation unlocks premium pricing unavailable to commodity transfusion suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scale operators with installed pathogen inactivation technology. Long-term viability across the analysis window hinges on regulatory compliance infrastructure rather than collection volume alone. Acquisition targets should display amotosalen or riboflavin system deployment and captive donor base access. Monitor EU Blood Directive implementation timelines as inflection signals for technology upgrade spending waves.| Strategic Initiative | Industry Significance |
|---|---|
| Pathogen Inactivation Technology Deployment | Amotosalen and riboflavin systems satisfy EU Blood Directive mandates ahead of enforcement deadlines. |
| Domestic Plasma Collection Expansion | Apheresis center buildout in Germany and France reduces transatlantic import dependency and tariff exposure. |
| Cell Therapy CDMO Partnership | Direct GMP-grade supply contracts with Belgian and Dutch manufacturers bypass traditional hospital distribution. |
| Hospital Consignment Model Rollout | Swiss and Austrian integrated delivery networks transfer working capital burden from customers to suppliers. |
| Bio-Based Polymer Supply Chain Certification | REACH-compliant blood bag sourcing from certified sustainable polymer chains meets ECHA evaluation timelines. |
Methodological Framework
Desk research of EMA regulatory filings, EU Blood Directive implementation documents, and national health authority licensing records preceded structured interviews with blood establishment operations directors, plasma fractionation executives, hospital transfusion service chiefs, and cell therapy manufacturing supply chain managers. Primary fieldwork combined with secondary validation against hospital procurement databases, GPO contracts, and blood component utilization statistics. Bottom-up collection volume modeling and top-down fractionation capacity assessment provided cross-verification.
Assumptions held fixed include EU Blood Directive implementation timelines, F-Gas Regulation compliance deadlines, and REACH substance evaluation schedules; variables tested included transatlantic logistics cost scenarios and synthetic colloid substitution rates. Segmentation modeling spanned product type, application, end user, and delivery mode dimensions across the projection horizon. CAGRs derived from hospital admission trend extrapolation, oncology protocol expansion rates, and cell therapy manufacturing feedstock demand curves.
Macroeconomic conditions sit as an overlay; deviation in transatlantic trade policy, EU cohesion fund disbursement pacing, or healthcare reimbursement austerity would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation and substitution technology penetration. Quarterly review of plasma import volumes, pathogen inactivation system installation rates, and synthetic colloid formulary adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Organ Care Products Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Italy Hand Sanitizer Market