
 Menstrual Sponge Market | 2026-2036
Menstrual Sponge Market Size, Share, and Industry Trends Forecast 2026-2036
Menstrual Sponge Market Analytics
Greece is fragmenting as Mediterranean sea sponge harvesting expands to meet raw material needs for natural menstrual sponge producers. Jade and Pearl leverages its Florida-based processing operations to control quality across Atlantic supply chains. Poseidon Sponge anchors its competitive position through deep ties to Aegean diving cooperatives. Natural Intimacy differentiates via organic certification protocols that command premium positioning in British and German retail channels.
Menstrual sponges are absorbent, porous marine or synthetic structures inserted intravaginally to collect menstrual flow, typically measuring 5-7 centimeters in diameter and designed for single-use or reusable cycles depending on material composition. Natural sponges derived from marine species offer biodegradability but require rigorous sanitization, while synthetic variants use medical-grade polyurethane for controlled absorbency and shape retention. Reusable sponges lead margin pools due to consumer lifetime value and subscription retention models, though biodegradable sponges attract fastest-growing demand from zero-waste retail channels. Online retail now dominates volume for first-time buyers, while specialty stores sustain premium pricing through tactile product education and fitting consultation.
The FDA classifies menstrual sponges as Class II medical devices requiring 510(k) clearance for synthetic variants, while the EU Medical Device Regulation mandates biocompatibility testing for all intravaginal products sold in member states. REACH compliance shapes material selection for European manufacturers, restricting certain polyurethane catalysts and dye compounds. Stakeholders must monitor evolving state-level legislation in the United States, where California and New York advance ingredient disclosure mandates that could reshape labeling requirements across national distribution networks.
Market Dynamics
EU Green Deal mandates for sustainable personal care products are compressing product development cycles while accelerating raw material substitution toward biodegradable marine and plant-based alternatives.
Growth Catalysts
- EU Medical Device Regulation (MDR):Biocompatibility testing requirements for intravaginal products are elevating quality standards that premium natural sponge producers already meet, creating competitive separation from unregulated imports.
- Zero-waste retail channels:Specialty stores in Germany and France are building consumer education infrastructure that reduces purchase hesitation for first-time reusable sponge buyers.
- Aegean diving cooperatives:Expanded Mediterranean sea sponge harvesting capacity is securing raw material supply for natural product manufacturers serving British and German premium channels.
Market Restraints
- Input cost volatility:Wild-harvested marine sponge supply fluctuates with Aegean Sea temperature patterns and diving season constraints, compressing margin predictability for natural product lines.
- REACH compliance friction:Restricted polyurethane catalysts and dye compounds limit formulation flexibility for synthetic sponge producers targeting European distribution.
- Substitution threat:Medical-grade silicone menstrual cups offer comparable reusability with lower sanitization complexity, capturing price-sensitive segments in urban British markets.
Strategic Opportunities
- Subscription retention models:Direct-to-consumer platforms in the United Kingdom are building predictable revenue streams through reusable sponge replacement cycles and companion product bundles.
- Organic certification tailwinds:EU Green Deal procurement guidelines for sustainable personal care create preferential channel access for certified natural sponge producers in French and German institutional purchasing.
- Telehealth integration:Gynecological telehealth platforms in Germany are incorporating menstrual sponge fitting consultations into remote care protocols, expanding addressable market reach beyond traditional retail.
Industry Challenges
- Sanitization protocol standardization:Absence of unified boiling duration and antimicrobial additive guidelines across EU member states creates consumer confusion and compliance inconsistency for reusable product lines.
- 510(k) clearance timelines:FDA Class II medical device pathways for synthetic sponge variants extend commercialization schedules by 18-24 months, constraining capital efficiency for US market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menstrual Sponge Market |
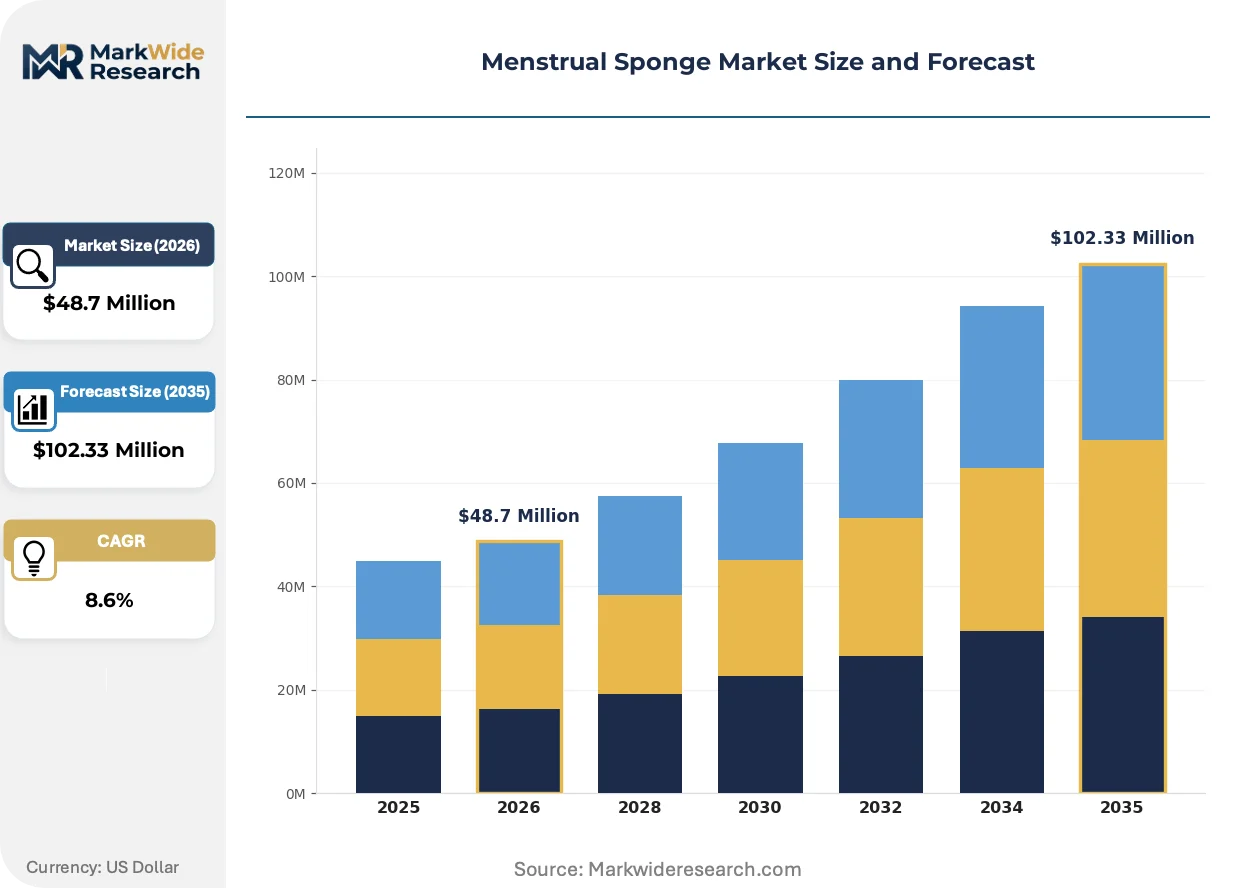
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $102.33 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sponges, Synthetic Sponges, Biodegradable Sponges, Reusable Sponges Material: Organic Cotton, Polyurethane, Silk, Synthetics Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores Size: Small, Medium, Large, Extra Large |
| Companies Covered | Jade and Pearl, Poseidon Sponge, Natural Intimacy, The Sea Sponge Company, Levant Natural Sponges, Thinx, Diva International Inc., Essity, Eco Femme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menstrual Sponge Market Evolving Landscape
Material science advances in biodegradable polymers and marine cultivation techniques are restructuring competitive advantage away from synthetic formulation expertise toward sustainable sourcing credentials.
Plant-derived cellulose sponges processed with enzymatic rather than chemical softening are rendering obsolete petroleum-based polyurethane cores in premium European segments. German and French buyers aged 25-34 are switching formats at accelerating pace as organic certification protocols validate performance parity. This substitution is compressing R&D investment returns for legacy synthetic producers while rewarding backward integration into cultivated marine supply.
REACH restrictions on specific polyurethane catalysts and dye compounds are forcing synthetic sponge manufacturers to reformulate entire product lines for European market access. The regulation is eliminating cost-competitive gray-market imports while creating certification moats for compliant producers. British retailers are responding by consolidating supplier relationships around REACH-verified manufacturers with documented biocompatibility testing.
Specialty stores are unbundling tactile product education from transaction completion, using fitting consultation appointments to build subscription conversion pipelines. German urban consumers are migrating from pharmacy impulse purchases toward scheduled specialty store visits with trained staff guidance. This behavioral shift is most visible in Berlin and Munich, where zero-waste retailers report higher lifetime value from consultation-origin customers versus online-only acquisitions.
Menstrual Sponge Market Segmentation
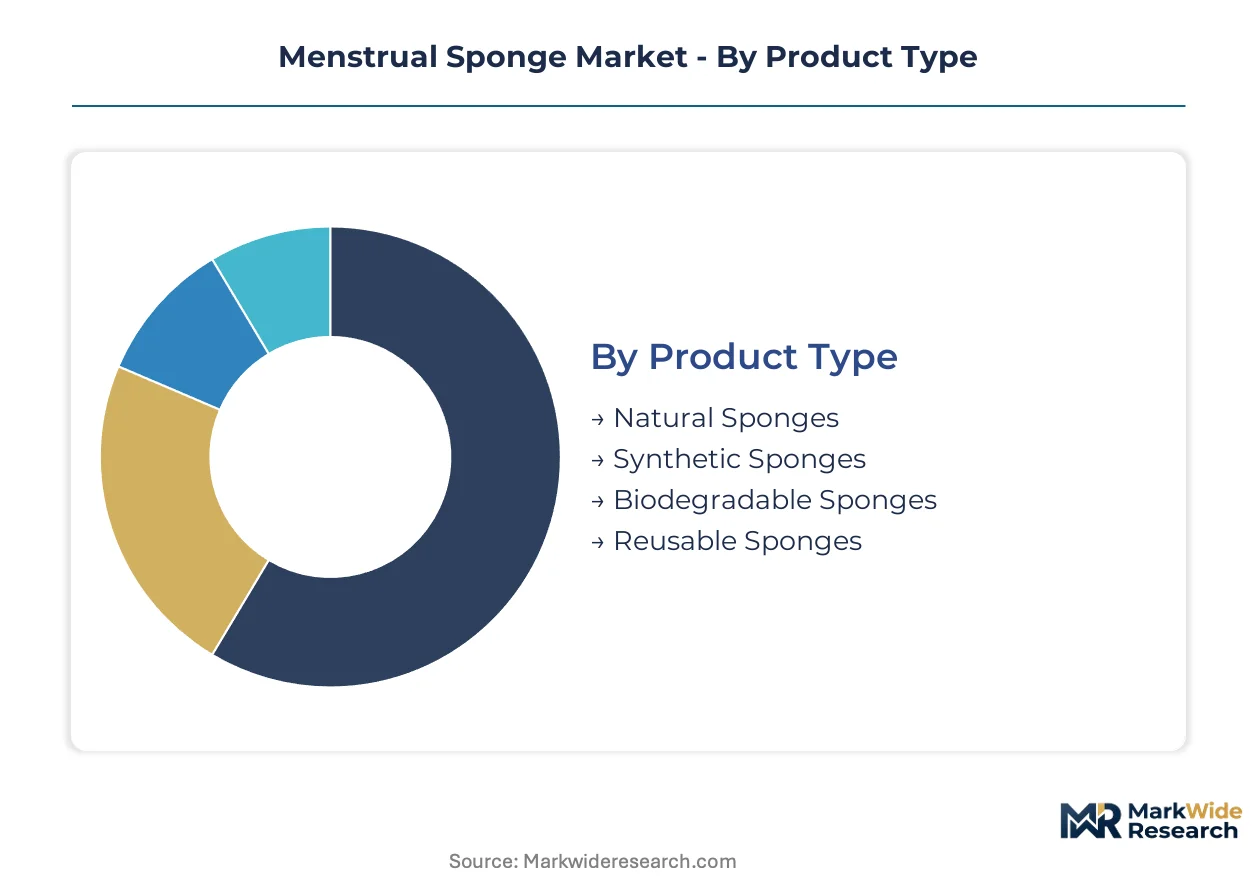
Segmentation in the menstrual sponge market reveals divergent margin architectures and customer acquisition economics across material science and channel strategies. Product type and distribution channel together determine lifetime value profiles, with reusable formats and specialty retail commanding premium positioning through education-intensive purchase journeys.
Product Type:
After-sales-service intensity varies sharply across product types, with reusable formats demanding ongoing sanitization guidance and replacement scheduling that synthetic single-use alternatives bypass entirely.
- Natural Sponges:Harvested marine sponges from Mediterranean and Caribbean waters require rigorous boiling protocols and periodic replacement cycles. Demand concentrates in German and French premium natural product channels where organic certification validates sourcing ethics and biocompatibility.
- Synthetic Sponges:Medical-grade polyurethane constructions deliver controlled absorbency and dimensional stability through standardized manufacturing. British urban consumers favor these for predictable performance, though REACH catalyst restrictions are forcing formulation overhauls for EU market access.
- Biodegradable Sponges:Plant-derived cellulose cores processed with enzymatic softening are displacing petroleum-based alternatives in zero-waste retail.
- Reusable Sponges:Multi-cycle marine or synthetic designs generate highest customer lifetime value through subscription replenishment models.
By volume, synthetic sponges lead due to manufacturing scale. By growth pace, biodegradable sponges are expanding most quickly as EU Green Deal procurement guidelines reshape material preferences.
Material:
Cost tier stratification in raw materials directly maps to finished product positioning, with cultivated marine and certified organic inputs commanding 3-4x the input cost of commodity polyurethane.
- Organic Cotton:GOTS-certified fiber layers provide hypoallergenic interfaces for sensitive users. British and German buyers aged 25-34 are switching toward cotton-lined hybrids as dermatological concerns reshape purchase criteria.
- Polyurethane:Medical-grade foam cores dominate synthetic production with tunable porosity and shape retention. REACH restrictions on specific catalysts and dye compounds are eliminating cost-competitive gray-market imports while creating certification moats for compliant producers.
- Silk:Protein-based fiber coatings reduce friction and irritation in premium positioning tiers.
- Synthetics:Blended petroleum-derived materials serve economy segments with shorter replacement cycles.
Polyurethane retains volume leadership. Silk and organic cotton are climbing the fastest as tactile comfort and chemical-free positioning reshape premium segment preferences.
Distribution Channel:
Channel selection determines customer education depth and subscription conversion potential, with tactile consultation formats outperforming transactional digital acquisition for reusable product lines.
- Online Retail:Direct-to-consumer platforms dominate first-time buyer acquisition through privacy-preserving purchase journeys. German telehealth integrations are expanding addressable reach beyond traditional retail by incorporating fitting consultations into remote care protocols.
- Pharmacies:Impulse-oriented shelf placement captures convenience-driven replenishment in urban British markets.
- Supermarkets:Mass-market visibility sustains synthetic single-use volume through price-competitive positioning.
- Specialty Stores:Zero-waste retailers in Berlin and Munich unbundle tactile education from transaction completion, building subscription pipelines through scheduled fitting appointments.
Online retail leads by volume through privacy convenience. Specialty stores are gaining share fastest as zero-waste retail infrastructure matures in German and French urban centers.
Size:
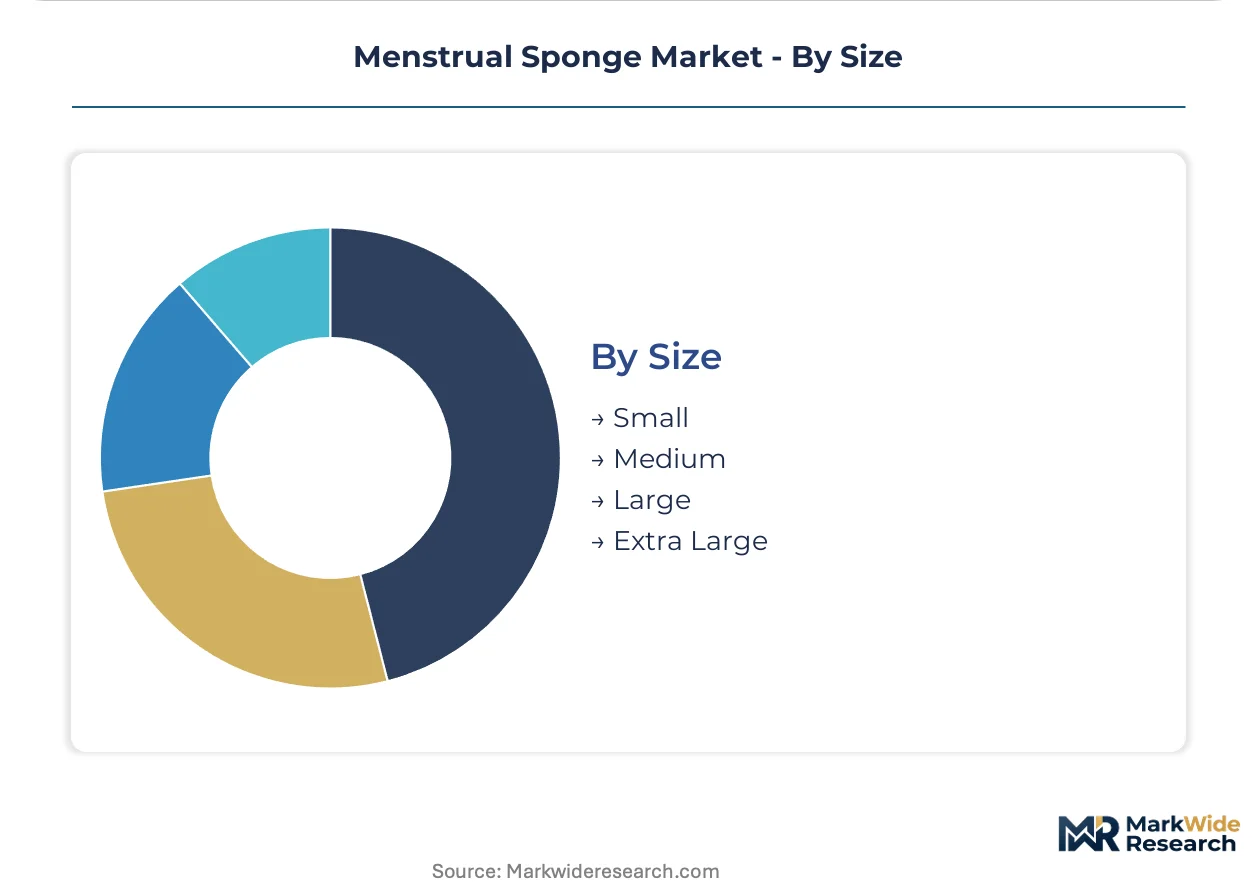
Volume concentration in medium and large formats reflects demographic averaging, while small and extra-large segments serve underserved anatomical extremes with limited competitive attention.
- Small:4-5 centimeter diameter formats serve adolescent and perimenopausal segments with lighter flow profiles. British gynecological telehealth platforms are normalizing size-specific fitting guidance that reduces trial-and-error abandonment.
- Medium:5-6 centimeter standard sizing captures the majority of adult users through retail assortment defaults.
- Large:6-7 centimeter designs address heavier flow days and postpartum requirements.
- Extra Large:7+ centimeter specialty formats serve high-volume needs with limited retail availability.
Medium and large sizes dominate volume through demographic averaging. Small formats are expanding most quickly as teen-focused education initiatives and telehealth fitting protocols reduce purchase hesitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers treat menstrual sponges as certified natural products demanding organic validation, while British buyers prioritize telehealth-guided fitting protocols that reduce trial-and-error abandonment. This consumption-mix differential shapes divergent channel strategies across European markets.
Germany
Zero-waste retail infrastructure in Berlin and Munich drives specialty store consultations that build subscription retention for reusable formats. The EU Medical Device Regulation mandates biocompatibility testing that elevates quality standards for natural sponge imports. Baden-Württemberg hosts analytical testing laboratories serving REACH-compliant manufacturers seeking European market access.
United Kingdom
Gynecological telehealth platforms normalize remote fitting guidance that expands addressable market reach beyond traditional pharmacy channels. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance for intravaginal products that shapes importer diligence requirements. London concentrates direct-to-consumer platform headquarters leveraging privacy-preserving purchase journeys for first-time buyers.
France
Organic certification protocols command premium positioning in Parisian natural product retail channels where EU Green Deal procurement guidelines create institutional purchasing preferences. The French National Agency for Food, Environmental and Occupational Health Safety monitors cosmetic-grade material safety for marine-derived personal care inputs. Provence-Alpes-Côte d'Azur hosts Mediterranean sea sponge processing operations serving Atlantic supply chains.
United States
State-level ingredient disclosure mandates in California and New York reshape labeling requirements that propagate across national distribution networks. The FDA classifies synthetic sponge variants as Class II medical devices requiring 510(k) clearance that extends commercialization timelines. Florida anchors Atlantic processing operations controlling quality for natural product lines.
Greece
Aegean diving cooperatives expand Mediterranean sea sponge harvesting capacity to secure raw material supply for natural product manufacturers. The Greek Ministry of Rural Development and Food regulates marine resource extraction that shapes seasonal harvesting constraints. The Dodecanese Islands concentrate traditional sponge diving operations with deep ties to European premium channel suppliers.
Menstrual Sponge Market Competitive Landscape
Capability concentration sits with marine sourcing specialists controlling Aegean supply chains; scale advantage sits with direct-to-consumer platforms building subscription retention models. The market structures around three tiers: heritage Mediterranean harvesters, Florida-based quality controllers, and British-German certification specialists. Two dominant competitive moves are backward integration into cultivated marine supply and telehealth partnership development for remote fitting protocols.
Within the heritage harvester tier, Poseidon Sponge exemplifies Aegean cooperative anchoring through deep ties to diving collectives. Jade and Pearl occupies a position as Florida-based quality controllers leveraging Atlantic processing operations. Natural Intimacy sits within the certification-specialist archetype commanding premium positioning in British and German retail channels through organic validation protocols.
| Leading Market Players |
|---|
| Jade and Pearl |
| Poseidon Sponge |
| Natural Intimacy |
| The Sea Sponge Company |
| Levant Natural Sponges |
| Thinx |
| Diva International Inc. |
| Essity |
| Eco Femme |
| Others |
Value Network & Pricing Analysis
Aegean diving cooperatives controlling Mediterranean sea sponge harvests concentrate upstream margin capture, while downstream pricing power accrues to British and German certification specialists commanding premium positioning through organic validation protocols.
Pricing Analysis
Long-term offtake contracts with Aegean cooperatives anchor input cost predictability for natural sponge producers, though spot-market exposure persists for wild-harvested marine supply subject to seasonal diving constraints. Three-tier pricing structure across premium certified-organic, standard natural, and economy synthetic levels separates buyers by certification grade and sanitization protocol complexity. Pricing pressure stems from REACH-compliant polyurethane reformulation costs compressing synthetic producer margins. German zero-waste retail channels exhibit lowest price sensitivity due to education-intensive consultation formats, while British pharmacy impulse buyers show highest elasticity.
Supply Chain Analysis
Extended payment terms from German specialty retailers to domestic distributors are cascading upstream, squeezing working capital for Aegean cooperative suppliers dependent on seasonal harvest cash flows. Raw material supply concentrates in Greece, Florida processing operations, and British certification facilities. Marine sponge biomass, medical-grade polyurethane, and GOTS-certified organic cotton constitute critical input dependencies. Single-source vulnerability runs through Aegean diving cooperative concentration, where temperature-driven harvest volatility disrupts supply continuity. Distribution runs through direct-to-consumer platforms for first-time acquisition, with specialty stores capturing replenishment cycles through subscription bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic marine sourcing capability represents the scarcest strategic asset, with fewer than five validated suppliers capable of meeting EU Medical Device Regulation biocompatibility standards for premium channel access.
For Market Incumbents: Pre-empt silicone menstrual cup substitution by embedding telehealth fitting partnerships into direct-to-consumer platforms, while securing exclusive offtake agreements with expanding Aegean diving cooperatives before harvest capacity tightens. Backward integration into cultivated marine sponge operations in the Dodecanese Islands reduces wild-harvest dependency. For New Entrants and Emerging Players: Small-format reusable sponges for adolescent and perimenopausal segments in British urban markets represent the most penetrable entry point, given limited competitive attention and telehealth-guided fitting protocols reducing trial-and-error abandonment. German zero-waste retail channels in secondary cities offer whitespace for specialty store partnerships with scheduled consultation formats. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Florida-based quality controllers possessing Atlantic processing infrastructure and FDA 510(k) clearance pathways. Five-to-ten year viability hinges on EU Green Deal procurement guideline expansion into institutional purchasing. The signal to watch is Aegean cooperative harvest permit issuance velocity, indicating raw material supply elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivated Marine Supply | Captive sponge cultivation in the Dodecanese Islands insulates against Aegean wild-harvest volatility. |
| Telehealth Partnership Development | German gynecological platforms incorporating remote fitting consultations expand addressable market reach. |
| REACH Compliance Certification | Verified biocompatibility testing unlocks preferential access to French and German premium retail channels. |
| Subscription Retention Model Launch | Direct-to-consumer replacement cycles in the United Kingdom build predictable revenue streams. |
| Organic Certification Protocol Investment | EU Green Deal procurement guidelines create institutional purchasing advantages for validated natural producers. |
Research Methodology
A spread of perspectives from Aegean diving cooperative representatives, German zero-waste retail buyers, British gynecological telehealth platform operators, and FDA regulatory consultants converged on the working assumptions shaping this analysis. Primary fieldwork with specialty store operators and natural product distributors was cross-referenced against EU Medical Device Regulation submission databases, REACH compliance registries, ECHA chemical restriction updates, and customs trade data for Mediterranean sponge imports. Bottom-up volume estimates from channel-level stocking data were triangulated against top-down expenditure flows from national health account surveys.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by material science, distribution channel economics, and size-specific fitting protocol adoption rates. The analytical framework projected value expansion through reusable format lifetime value calculations and biodegradable substitution elasticity. CAGRs were derived from segment-level growth rate differentials weighted by current volume shares. Aegean harvest yield variability and EU Green Deal procurement guideline implementation velocity served as key forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending patterns, marine ecosystem temperature anomalies, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about certification protocol adoption curves and cooperative harvest capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Elderly Walker Market
Healthcare Products
Nursing Products Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Medical Products Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Global Life Science Products Market