
 Self-Clinching Fasteners Market | 2026-2036
Self-Clinching Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Clinching Fasteners Market Insights
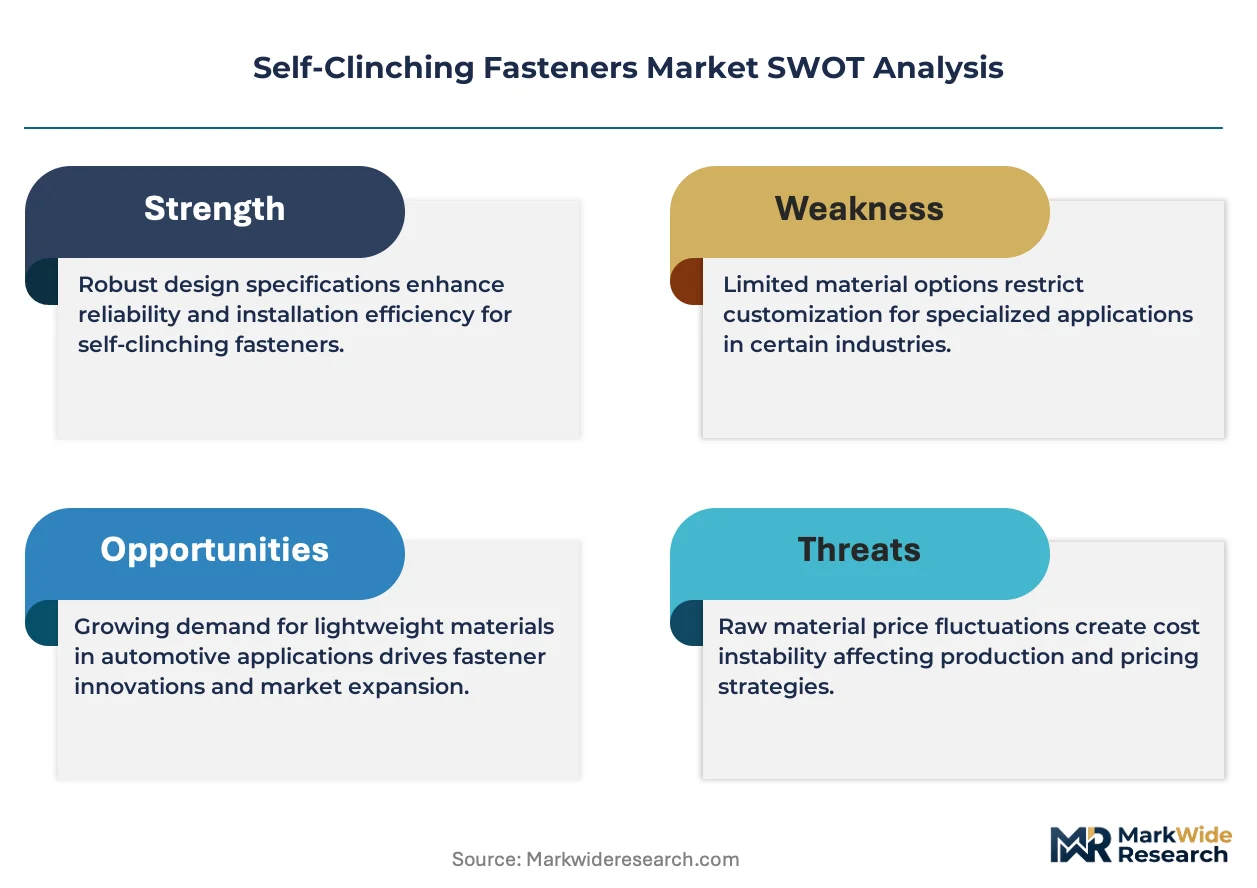
The capital-intensity gap between captive forging operations and outsourced fastener sourcing is collapsing as OEMs demand tighter lot traceability. PennEngineering & Manufacturing Corp leverages its captive cold-heading capacity to anchor long-term aerospace contracts. Böllhoff Group competes through distributed service hubs that position technical sales engineers inside customer plants. Sherex Fastening Solutions differentiates via deep specialization in clinch-to-install torque control for electric vehicle battery trays.
Self-clinching fasteners are mechanical devices that create permanent, load-bearing threads in thin ductile metal sheets through controlled radial displacement during installation, typically requiring access from only one side and achieving pull-out strengths exceeding parent material yield. These components serve critical joining functions where welded or loose hardware would fail due to space constraints, vibration, or thermal cycling. Stainless steel variants command premium positioning in medical device and aerospace applications where ASTM F593 compliance governs corrosion resistance. Aluminum grades capture expanding volume in electronics housings as OEMs pursue gram-level weight reductions. Steel remains the mature volume foundation across automotive chassis and industrial equipment.
ISO 898-1 governs mechanical properties of carbon and alloy steel fasteners, while ASTM F593/F594 specifies stainless steel chemistry and strength grades that shape material selection for North American aerospace and medical OEMs. The EU Machinery Directive and CE marking requirements enforce thread-retention and vibration-resistance standards that filter non-compliant suppliers from European industrial channels. Stakeholders must monitor evolving EV platform architectures and battery enclosure designs, as cell-to-pack integration eliminates traditional module frames and redirects fastener demand toward thermal management plates and structural cooling channels.
Market Dynamics
Cell-to-pack battery architectures are eliminating traditional module frames and redirecting fastener demand toward thermal management plates and structural cooling channels, forcing suppliers to requalify products for new load paths and vibration profiles.
Growth Catalysts
- EV Battery Enclosure Demand:Electric vehicle manufacturers require high-strength clinching solutions for aluminum battery trays as cell-to-pack designs proliferate across automotive platforms.
- REACH Material Transitions:European ECHA enforcement is accelerating stainless steel and aluminum grade adoption as cadmium-plated alternatives face phase-out deadlines.
- Miniaturization in Electronics:Consumer device OEMs specify micro-clinch fasteners for smartphone and tablet housings where space constraints prohibit traditional threaded inserts.
Market Restraints
- Alloy Steel Price Volatility:Nickel and chromium input costs swing with commodity markets, compressing margins on carbon steel fastener production.
- Tooling Concentration Risk:Precision cold-heading equipment suppliers cluster in Germany and Japan, creating single-source vulnerability for tier-two fastener manufacturers.
- Weld Substitution Threat:Laser welding advances in thin-gauge aluminum applications displace clinch fasteners in non-structural electronics enclosures.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for mobile phone and component production create virgin demand for precision fastening in Noida and Chennai clusters.
- Medical Device Miniaturization:ASTM F593-compliant stainless micro-fasteners penetrate surgical instrument and diagnostic equipment enclosures.
- Solar Tracker Structural Channels:Utility-scale photovoltaic installations specify corrosion-resistant clinch hardware for aluminum tracker frames in desert environments.
Industry Challenges
- Cold-Heading Technician Shortage:Specialized die maintenance and setup skills retire faster than vocational programs replace them in mature manufacturing regions.
- Multi-Specification Qualification Burden:OEMs demand simultaneous ISO 898-1, ASTM F593, and customer-specific testing, extending new product approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Clinching Fasteners Market |
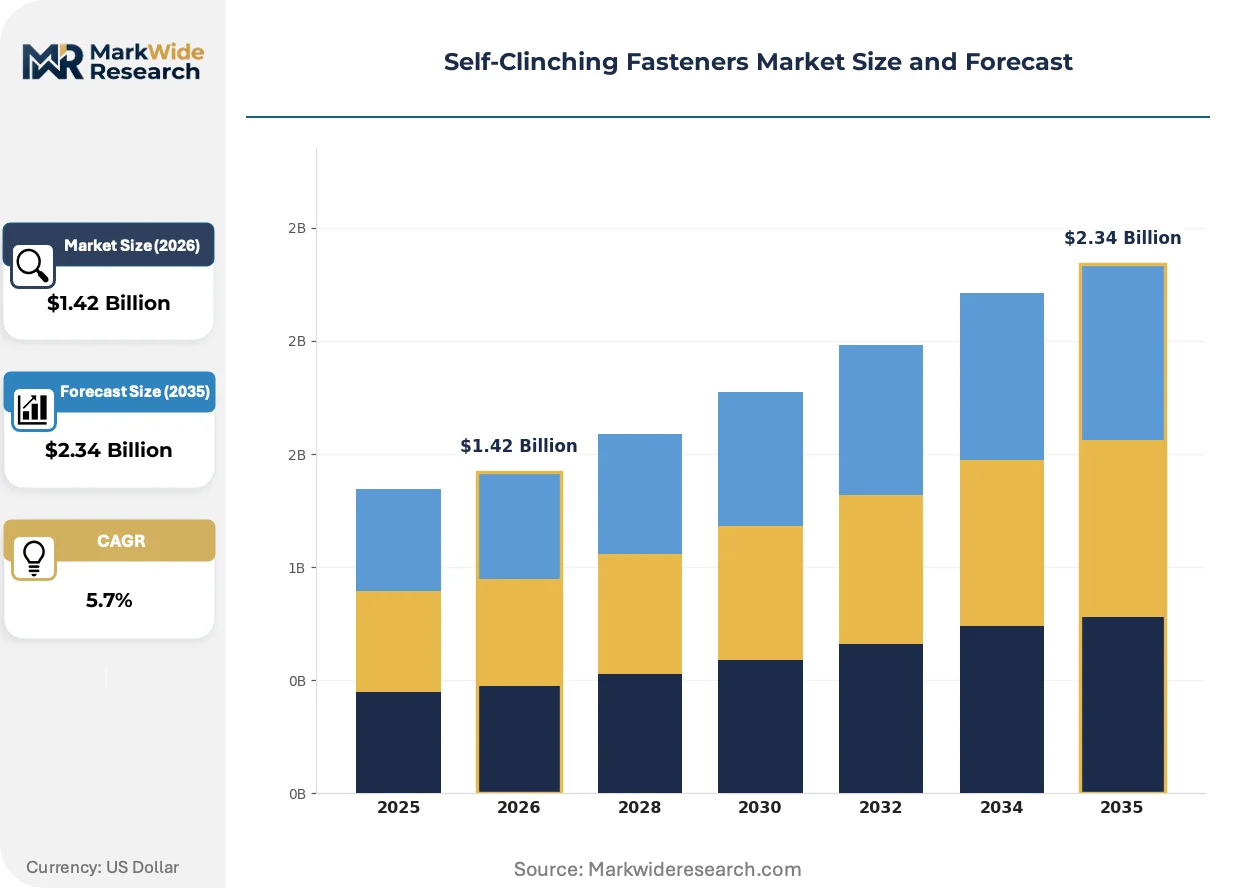
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.34 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Rivets, Studs, Nuts, Screws Material: Steel, Aluminum, Stainless Steel, Plastic Application: Electronics, Automotive, Aerospace, Medical Devices End User: OEMs, Tier-1 Suppliers, Manufacturers, Aftermarket Providers |
| Companies Covered | SFS Group AG, Spirol International Corporation, PennEngineering & Manufacturing Corp, Bossard AG, Sherex Fastening Solutions, Böllhoff Group, Acument Global Technologies, ARaymond Tinnerman Industrial, Inc., Stanley Black & Decker, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Clinching Fasteners Market Trends and Innovations
Fastener technology is compressing installation footprints while regulatory chemistry restrictions and procurement centralization reshape supplier relationships across precision manufacturing sectors.
Micro-clinch fastener designs are miniaturizing thread-forming hardware below M2.5 dimensions for wearable electronics and implantable medical devices. Apple and Samsung suppliers in Shenzhen and Seoul specify these components for magnesium alloy watch housings. The technology is miniaturizing enclosure design constraints and enabling gram-level weight targets previously unattainable with conventional inserts.
REACH Annex XVII restrictions on hexavalent chromium conversion coatings are forcing coating transitions to trivalent alternatives or stainless steel substrate migration. German automotive suppliers face 2025 compliance deadlines for chassis hardware. North American aerospace OEMs are accelerating ASTM F594 qualification programs to maintain European market access.
Consolidated procurement through tier-one system integrators is displacing direct OEM sales for standard fastener categories. Foxconn and Jabil now specify approved vendor lists for electronics clinch hardware, compressing supplier counts. This concentration is most visible in Taiwan and Guangdong contract manufacturing corridors where purchasing power aggregates.
Self-Clinching Fasteners Market Segmentation
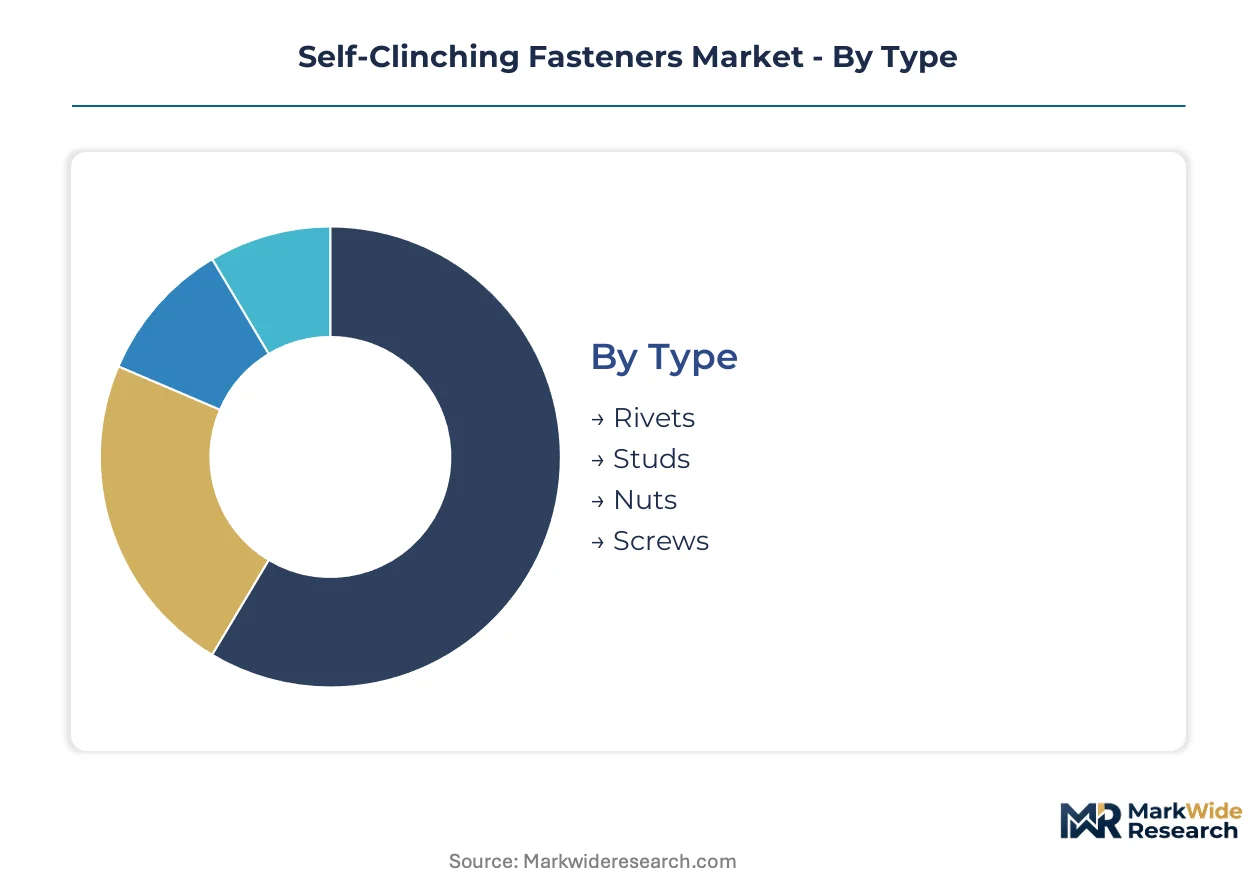
Self-clinching fastener procurement splits sharply across material specifications, installation geometries, and compliance tiers. Understanding these fault lines reveals where technical differentiation commands pricing power versus where volume commoditization dominates.
Type:
Margin pools concentrate in high-retention geometries where pull-out strength specifications justify premium positioning over standard hardware.
- Nuts:Threaded inserts with knurled shanks displace welded nuts in thin-gauge aluminum battery trays. EV manufacturers in Germany and China specify these for cell-to-pack enclosures where vibration resistance is mandatory.
- Studs:Externally threaded posts enable single-side installation for grounding and component mounting. Aerospace OEMs in the United States demand these for avionics racks requiring ASTM F593 compliance.
- Rivets:Permanent blind fasteners serve non-removable joints in consumer electronics housings.
- Screws:Self-tapping variants capture cost-sensitive industrial equipment applications.
The dominant share belongs to Nuts, while Studs is closing the gap fastest.
Material:
Cost tier stratification runs from commodity carbon steel through corrosion-resistant alloys to engineered plastics, with regulatory chemistry mandates accelerating grade migration.
- Stainless Steel:Austenitic grades meeting ASTM F593/F594 specifications anchor medical device and aerospace procurement. ECHA enforcement on hexavalent chromium coatings is pushing German automotive suppliers toward these substrates for chassis hardware.
- Steel:Carbon and alloy grades governed by ISO 898-1 remain the volume foundation across automotive chassis and industrial machinery.
- Aluminum:Lightweight variants capture electronics enclosure demand where gram-level reductions matter.
- Plastic:Specialized polymers serve isolated electrical and corrosion-proof applications.
Steel retains volume leadership, though Stainless Steel is expanding most quickly on regulatory tailwinds.
Application:
Customer type determines specification intensity, with certified end-uses demanding lot traceability that filters out commodity suppliers.
- Electronics:Micro-clinch hardware below M2.5 dimensions penetrates smartphone and wearable housings. Shenzhen and Seoul manufacturing clusters specify these for magnesium alloy enclosures.
- Automotive:Battery tray fasteners for cell-to-pack architectures redirect demand toward thermal management plates. OEMs in China and Germany lead platform adoption.
- Aerospace:ASTM F593-compliant stainless components serve structural and avionics applications.
- Medical Devices:Biocompatible grades penetrate surgical instrument and diagnostic equipment enclosures.
Electronics holds the largest installed base, while Automotive is climbing the fastest on EV platform proliferation.
End User:
Supply concentration shapes procurement leverage, with consolidated purchasing through tier-one integrators compressing vendor counts.
- OEMs:Direct specification authority resides with major automotive and electronics brand owners. Foxconn and Jabil now maintain approved vendor lists that aggregate purchasing power across Taiwan and Guangdong corridors.
- Tier-1 Suppliers:System integrators translate OEM requirements into volume contracts.
- Manufacturers:Contract fabrication shops source standard grades through distributor channels.
- Aftermarket Providers:MRO and repair channels serve replacement demand with looser specification requirements.
OEMs command specification authority, though Tier-1 Suppliers are gaining procurement centralization fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision manufacturing corridors while Chinese volume producers compete on scale. German suppliers command 15-20% premiums for REACH-compliant stainless grades. Chinese producers leverage Ningbo and Dongguan clusters to capture electronics enclosure contracts.
United States
Aerospace OEMs in Seattle and Wichita drive ASTM F593-compliant stainless demand for avionics racks. FAA airworthiness directives thread through procurement specifications for structural applications. Southern California electronics contract manufacturers specify micro-clinch hardware below M2.5 for wearable device magnesium housings.
Germany
Automotive battery tray fasteners for cell-to-pack architectures redirect supplier qualification efforts toward thermal management plates. ECHA enforcement on hexavalent chromium coatings accelerates substrate migration to austenitic stainless grades. Stuttgart and Wolfsburg manufacturing corridors anchor chassis hardware specification authority for European OEMs.
China
EV platform proliferation across BYD and CATL supply chains generates demand for high-retention clinch nuts in aluminum battery enclosures. MIIT new energy vehicle mandates shape fastener performance requirements for vibration resistance. Shenzhen and Dongguan electronics clusters specify micro-clinch components for smartphone and tablet magnesium alloy housings.
Japan
Precision equipment manufacturers in Nagoya and Osaka specify JIS-compliant stainless fasteners for semiconductor fabrication tool enclosures. METI carbon neutrality roadmaps pressure material transitions toward recyclable aluminum grades. Toyota City automotive suppliers requalify clinch hardware for solid-state battery platform architectures.
India
PLI scheme incentives for mobile phone production create virgin demand for precision fastening in Noida and Chennai manufacturing corridors. BIS certification requirements filter non-compliant suppliers from electronics contract manufacturing channels. Tamil Nadu and Karnataka clusters attract Foxconn and Dixon suppliers specifying approved vendor lists for clinch hardware.
Self-Clinching Fasteners Market Competitive Landscape
Concentration sits with diversified fastening conglomerates possessing captive cold-heading capacity and captive aerospace certification. The vendor base stratifies across three tiers: integrated multinationals with die-forging assets, regional specialists with application engineering proximity, and commodity distributors serving MRO channels. Dominant competitive moves include backward integration into precision heading equipment and strategic partnerships with tier-one system integrators consolidating procurement authority.
Among Swiss and German fastening conglomerates, SFS Group AG and Bossard AG exemplify the integrated multinational archetype with die-forging assets and global distribution networks. PennEngineering & Manufacturing Corp occupies a position within the North American precision specialist tier, while Böllhoff Group represents the application-engineering proximity model with technical sales positioning inside customer plants. Sherex Fastening Solutions anchors the deep-specialization segment focused on torque-controlled installation systems.
| Leading Market Players |
|---|
| SFS Group AG |
| Spirol International Corporation |
| PennEngineering & Manufacturing Corp |
| Bossard AG |
| Sherex Fastening Solutions |
| Böllhoff Group |
| Acument Global Technologies |
| ARaymond Tinnerman Industrial, Inc. |
| Stanley Black & Decker, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cold-heading capacity utilization above 85% in German and Japanese precision forging clusters creates natural price floors for ASTM F593-compliant stainless grades. Scale economies in captive die production anchor premium positioning for aerospace-certified hardware while squeezing margin recovery for tier-two commodity suppliers.
Pricing Analysis
Configured-to-order pricing for REACH-compliant stainless fasteners commands 15-20% premiums over standard carbon steel catalog pricing. Price differentiation rests on certification tier and lot traceability depth, with OEM-approved vendor list status justifying sustained margin capture. Cost compression in carbon steel grades is intensifying because nickel and chromium input volatility compresses spot-contract margins. Contract manufacturers in Guangdong corridors exhibit highest price sensitivity, whereas FAA-certified aerospace OEMs demonstrate lowest elasticity due to requalification costs.
Supply Chain Analysis
Germany and Japan anchor precision cold-heading equipment manufacturing, feeding die technology downstream to fastener producers in China and Taiwan. Raw material flows draw from nickel-chromium alloy suppliers in South Korea and stainless steel mills in Germany. Single-source vulnerability concentrates in precision heading equipment where German and Japanese OEMs control 90% of installed base. Distribution runs through tier-one system integrator approved vendor lists that aggregate procurement across Taiwan and Guangdong contract manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Foxconn and Jabil procurement centralization, compressing supplier counts and elevating specification authority for tier-one integrators.
For Market Incumbents: Compound captive cold-heading capacity advantages by securing long-term aerospace contracts with lot-traceability requirements that filter commodity competitors. Invest in REACH-compliant stainless substrate migration before ECHA enforcement deadlines eliminate cadmium-plated alternatives. Channel control through technical sales engineers positioned inside customer plants defends against distributor disintermediation. For New Entrants and Emerging Players: Lead with torque-controlled installation system specialization for EV battery tray applications where cell-to-pack architectures create virgin qualification opportunities. Target Noida and Chennai electronics manufacturing clusters where PLI scheme incentives attract first-time precision fastening demand. Go-to-market through approved vendor list penetration at tier-one integrators rather than direct OEM sales cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among captive-forging specialists with aerospace certification and long-term platform contracts. Five-to-ten-year viability favors integrated multinationals with die-forging assets over pure distribution plays. Monitor EV platform architecture shifts as inflection signal—cell-to-pack adoption rates determine thermal management plate fastener demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Heading Equipment | German and Japanese equipment OEMs control precision die technology that determines fastener quality tiers. |
| REACH-Compliant Coating Transition | ECHA enforcement deadlines force substrate migration to austenitic stainless grades for European automotive access. |
| Tier-One Integrator Partnership | Foxconn and Jabil approved vendor lists aggregate purchasing power across Taiwan and Guangdong corridors. |
| Micro-Clinch Capacity Expansion | Shenzhen and Seoul wearable device manufacturers specify M2.5-below hardware for magnesium alloy enclosures. |
| Aerospace Certification Investment | FAA airworthiness directives thread through procurement specifications for structural avionics rack applications. |
Research Methodology
Desk research of trade association filings, customs records, and SEC 10-K disclosures preceded structured interviews with fastener procurement managers at tier-one automotive suppliers, cold-heading equipment OEMs, and aerospace quality directors. Primary fieldwork with plant engineers and die maintenance technicians validated capacity utilization assumptions. Secondary sources included ASTM and ISO standards documentation, ECHA regulatory filings, and MIIT new energy vehicle mandates. Bottom-up segment sizing triangulated against top-down industry association aggregates.
Variance decomposition across material grade, application intensity, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include fastener type, substrate specification, end-use industry, and OEM tier. CAGRs derived from installed base growth rates and content-per-vehicle trajectories for EV platforms. Forecast inputs incorporated cell-to-pack architecture adoption curves and REACH compliance deadline schedules.
Forecasts assume regulatory continuity in EU REACH enforcement and FAA certification pathways; material policy shifts would require re-modeling. Specific risks include laser welding substitution in thin-gauge aluminum and cold-heading technician shortage in mature manufacturing regions. Recalibration cycles align with material shifts in EV platform architectures and ECHA enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Digital Cutting Machine Market
Tools
China Power Tools Market
Tools
United States Machine Tools Market
Tools
Core Shooter Machine Market
Tools
Welding Guns Market
Tools
2D Laser Cutting Machine Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Dumpy Level Market
Tools
Set Screw Market
Tools
Automatic Lathe Machines Market
Tools
Broaching Tools Market
Tools
Handheld Blower Market
Tools
Cordless Bandsaw Sander Market
Tools
Level Floats Market
Tools
Woodworking CNC Tools Market
Tools
Stationary Wood Planer Market