
 Orbital Sanders Market | 2026-2036
Orbital Sanders Market Size, Share, and Industry Trends Forecast 2026-2036
Orbital Sanders Market Analytics
ISO 28927-3 certification for hand-held power sander vibration emission is collapsing the competitive field to manufacturers with dedicated testing labs and capital reserves. Bosch leverages its captive motor and battery ecosystem to control cordless platform development costs. Makita sustains channel dominance through its breadth of 18V LXT-compatible sanders stocked at industrial distributors. Festool differentiates via integrated dust extraction systems that command price premiums in European professional markets.
An orbital sander employs an eccentric bearing mechanism that drives a circular sanding pad in a random orbit pattern, typically operating at 4,000–12,000 orbits per minute to minimize visible scratch marks on finished surfaces. Battery-powered sanders now lead product type growth as lithium-ion cell energy density improvements extend runtime to match corded equivalents in medium-duty cycles. Within applications, automotive refinishing occupies the highest margin pool due to clearcoat-grade finish requirements that justify premium tool and consumable expenditures. Woodworking remains the volume anchor, though price compression intensifies at the contractor-grade tier where DeWalt and Milwaukee compete aggressively.
OSHA's Respirable Crystalline Silica standard compels manufacturers to integrate HEPA-class dust collection, while the EU Machinery Directive enforces vibration exposure limits that shape product design priorities for European export compliance. EPA regulations on volatile organic compounds from refinishing solvents indirectly tighten surface preparation standards, elevating tool precision requirements. Stakeholders must monitor battery platform consolidation dynamics and decide whether to anchor R&D spending on cordless runtime extension or dust capture integration as the primary professional differentiator.
Market Dynamics
Battery platform consolidation and OSHA silica enforcement are compressing vendor margins while elevating dust extraction and cordless runtime as the twin axes of professional differentiation.
Growth Catalysts
- OSHA Respirable Crystalline Silica Standard:Mandatory HEPA-class dust collection integration drives replacement cycles across United States construction and refinishing trades.
- Lithium-ion energy density gains:Cell chemistry improvements extend cordless sander runtime to parity with corded tools in medium-duty woodworking cycles.
- Woodworking shops:Furniture manufacturers and millwork operations in the United States anchor volume demand through fleet standardization on contractor-grade platforms.
Market Restraints
- Rare earth magnet supply concentration:Neodymium sourcing dependency on Chinese processing facilities creates motor cost volatility for brushless DC platforms.
- ISO 28927-3 vibration testing:Certification requirements for hand-held sander emission measurement demand capital-intensive lab infrastructure that excludes smaller manufacturers.
- Manual sanding kits:Low-cost pneumatic and hand sanding alternatives retain share in emerging economy price-sensitive segments.
Strategic Opportunities
- Automotive refinishing:Clearcoat-grade finish requirements in collision repair chains justify premium tool and consumable positioning.
- EU Machinery Directive vibration limits:Stricter exposure thresholds create export compliance demand for low-emission sander designs.
- Tool rental channels:Proliferation of equipment rental platforms opens access to occasional-use professional and serious DIY segments.
Industry Challenges
- Vibration metrology expertise:ISO 28927-3 compliance demands specialized testing personnel that outstrip current labor pool depth.
- Battery platform interoperability:Cross-brand cell and charger incompatibility fragments fleet purchasing decisions and complicates contractor inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orbital Sanders Market |
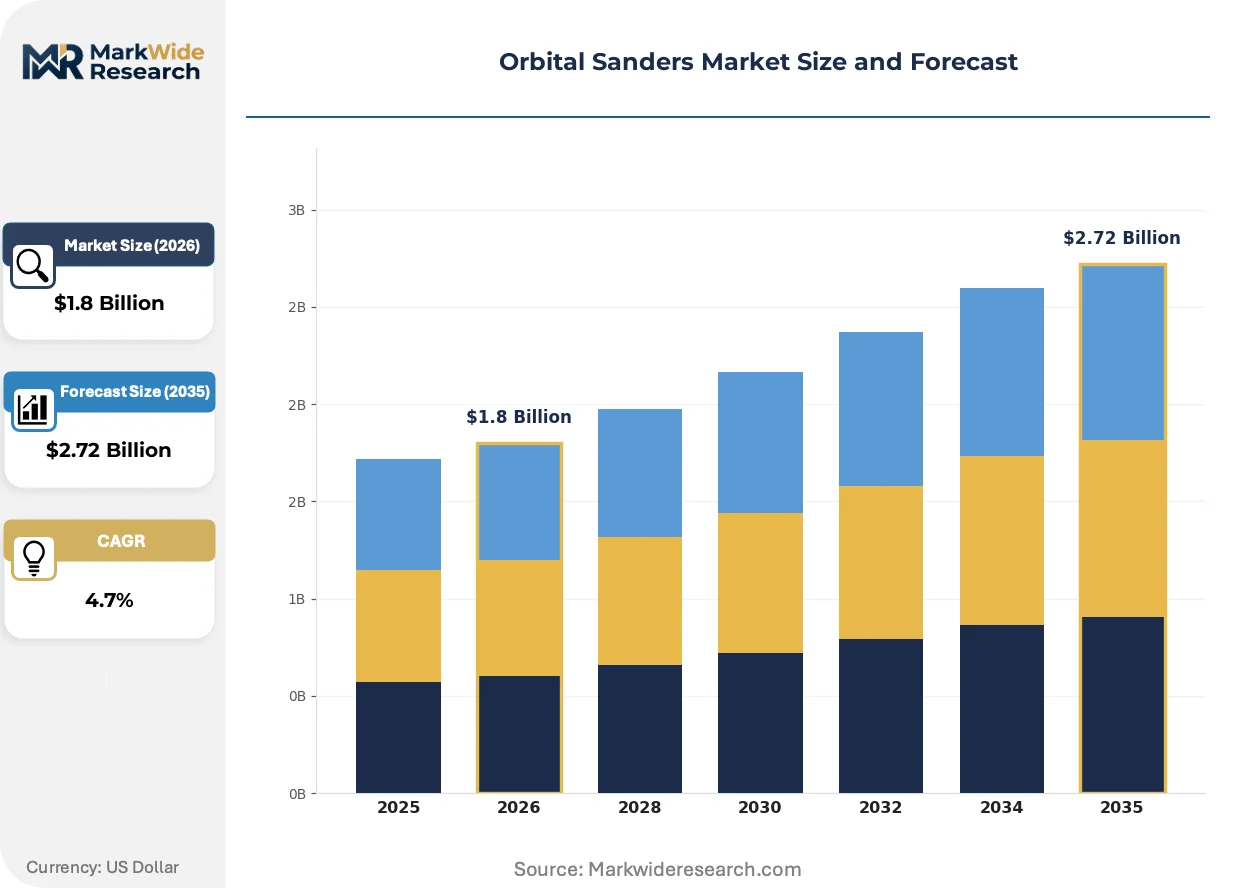
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Sanders, Pneumatic Sanders, Battery-Powered Sanders, Manual Sanders Application: Woodworking, Automotive Refinishing, Metal Fabrication, Surface Preparation End User: Contractors, DIY Enthusiasts, Furniture Manufacturers, Construction Companies Size: Small, Medium, Large, Extra Large |
| Companies Covered | Milwaukee, Festool, Bosch, Hutchins Manufacturing Company, Makita, DeWalt, Black & Decker, Metabo HPT, Mirka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orbital Sanders Market Evolving Landscape
Orbital sander design is pivoting toward integrated dust extraction and cordless runtime parity, with regulatory compliance and battery chemistry advancing in lockstep.
Brushless DC motor architecture is miniaturizing. These compact electromagnetic systems deliver corded-equivalent torque density in 18V and 12V battery formats. Professional contractors in United States commercial construction are specifying brushless platforms for silica-compliant job sites. The technology is miniaturizing motor housings while maintaining 4,000–12,000 OPM performance envelopes, compressing tool weight and extending single-hand operation duration.
EPA volatile organic compound regulations on refinishing solvents are tightening surface preparation standards. These rules indirectly mandate finer abrasive sequences and more precise tool control. Automotive refinishing shops in California and Michigan are responding with random-orbit sanders specified for 400-grit and finer progression work, elevating tool precision requirements above contractor-grade norms.
Industrial distributors are unbundling sander and dust extractor procurement. Buyers now specify extraction systems separately from power tools, forcing sander OEMs to certify universal hose compatibility. This pattern concentrates in United States professional channels where OSHA enforcement has normalized extractor presence on job sites, shifting competitive emphasis from bundled kits to interoperable component design.
Orbital Sanders Market Segmentation
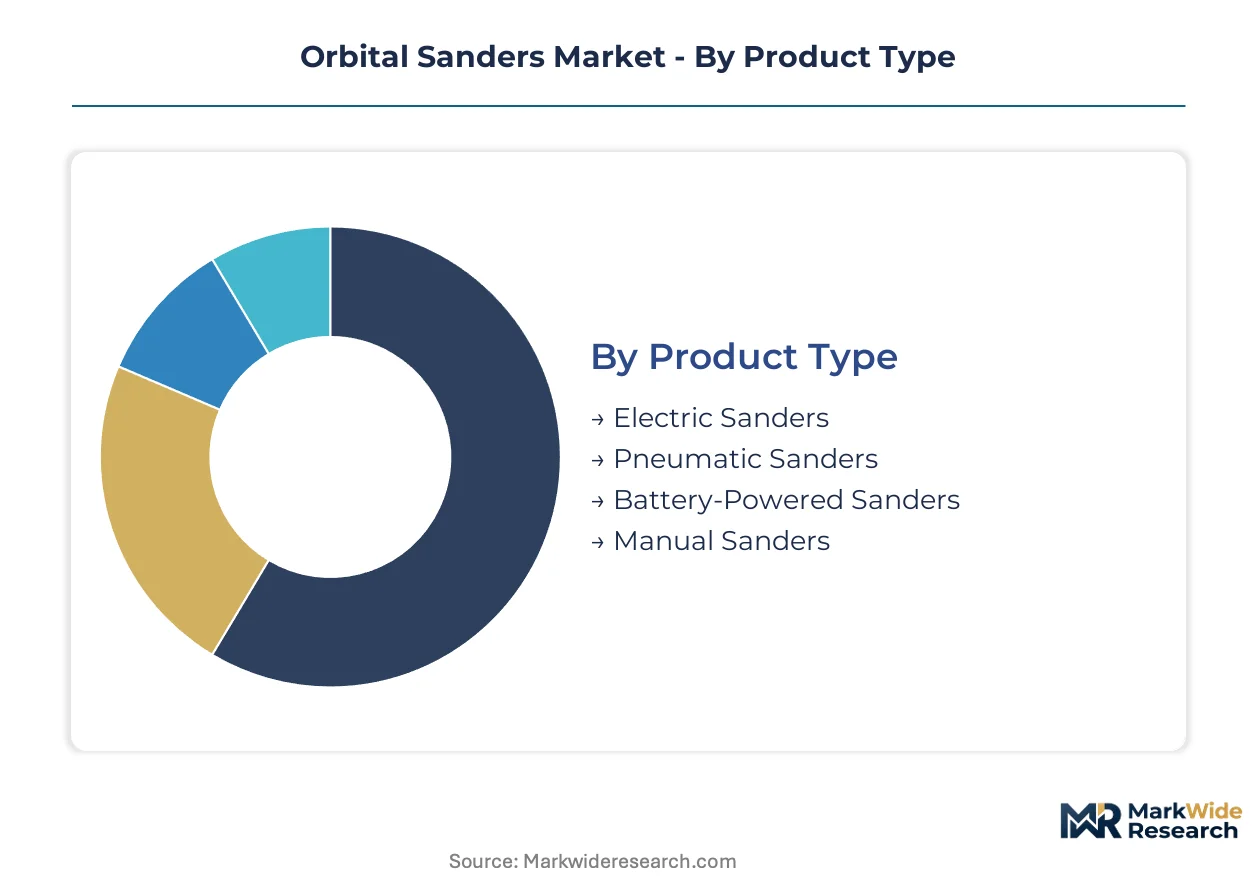
Orbital sander purchasing decisions fragment across power source preferences, finish quality requirements, and fleet standardization protocols. Understanding where margin pools concentrate within each dimension reveals which specifications command price premiums versus which segments face commodity pressure.
Product Type:
Margin pools concentrate in cordless platforms where battery ecosystem lock-in sustains pricing power, while pneumatic tools compete on total cost of ownership in fixed-shop environments.
- Electric Sanders:Corded AC-motor designs deliver sustained power output for continuous-duty industrial cycles. Furniture manufacturers in the United States specify these for millwork production lines where uninterrupted runtime outweighs mobility requirements, though OSHA silica compliance now mandates integrated dust ports that add cost.
- Battery-Powered Sanders:Lithium-ion cell chemistry improvements have extended runtime to match corded equivalents in medium-duty woodworking applications. Contractors in United States commercial construction are standardizing fleet purchases on 18V and 20V platforms, creating replacement-cycle revenue through battery degradation and platform ecosystem loyalty.
- Pneumatic Sanders:Compressed-air systems dominate automotive refinishing booths where explosion-proof operation is mandatory and compressor infrastructure exists.
- Manual Sanders:Hand-powered blocks and sheets retain share in emerging economy price-sensitive segments and touch-up work.
The dominant share belongs to electric sanders, while battery-powered sanders are closing the gap fastest.
Application:
Volume concentrates in material removal and smoothing workflows, but profit per unit peaks where surface finish specifications are unforgiving.
- Automotive Refinishing:Clearcoat-grade finish requirements in collision repair chains justify premium tool and consumable expenditures. Shops in California and Michigan specify random-orbit sanders capable of 400-grit and finer progression work, elevating precision requirements above contractor-grade norms and supporting three-tier pricing stratification.
- Woodworking:Furniture manufacturers and millwork operations anchor volume demand through fleet standardization on contractor-grade platforms. United States woodworking shops are replacing aging fleets to meet OSHA silica dust exposure limits, driving replacement cycles across cabinet, fixture, and architectural millwork segments.
- Metal Fabrication:Weld seam grinding and surface conditioning applications demand aggressive stock removal with coated abrasive durability.
- Surface Preparation:Coating removal and substrate profiling for refinishing operations spans residential, commercial, and industrial maintenance workflows.
Woodworking claims the volume anchor position, though automotive refinishing is expanding most quickly as collision repair consolidation elevates equipment standards.
End User:
Procurement authority and technical specification knowledge vary sharply between professional trades and consumer purchasers.
- Contractors:Commercial construction tradespeople in the United States prioritize cordless platform interoperability and silica-compliant dust extraction, accepting premium pricing for OSHA-compliant job site operation.
- Furniture Manufacturers:Millwork and production furniture operations standardize on corded electric sanders for continuous-duty cycles, with procurement decisions driven by total cost of ownership and service network proximity.
- Construction Companies:General contractors and specialty trades manage mixed fleets across rough carpentry and finish work applications.
- DIY Enthusiasts:Consumer purchasers respond to retail channel placement and bundled accessory kits, with price sensitivity highest in this segment.
Furniture manufacturers hold the dominant share, while contractors are gaining share fastest as cordless platform adoption accelerates.
Size:
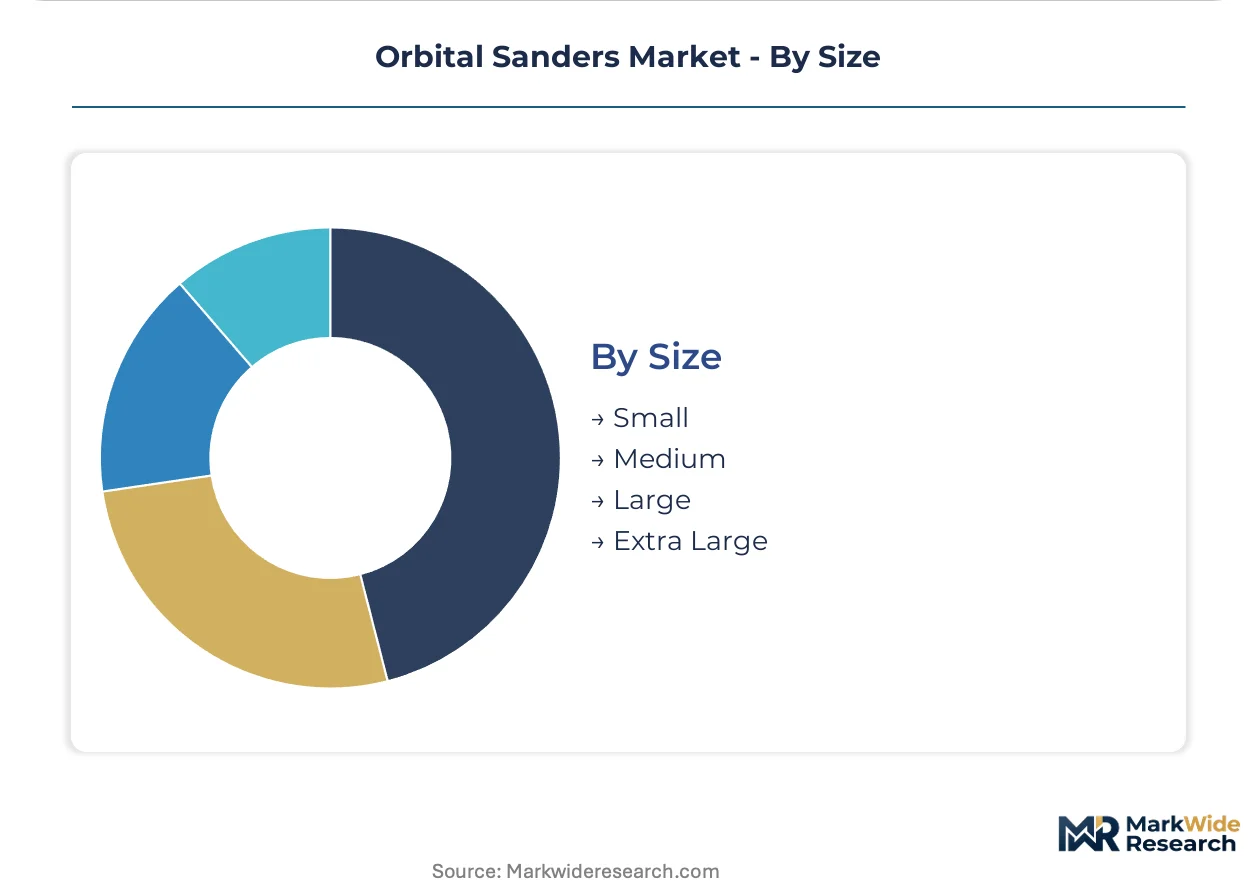
Pad diameter determines stock removal rate, finish quality, and operator fatigue trade-offs across application types.
- Medium:Five-inch and six-inch pad diameters balance material removal efficiency with maneuverability in cabinet and furniture work. United States woodworking shops specify this format for fleet standardization, creating volume concentration that supports competitive pricing.
- Small:Three-inch and smaller pads access confined contours and detailed trim work. Automotive refinishing shops employ these for door jambs, body lines, and complex curves where larger pads cannot conform.
- Large:Eight-inch and nine-inch formats accelerate flat surface processing in panel and tabletop applications.
- Extra Large:Specialized drywall and floor sanding equipment occupies niche commercial applications with distinct competitive dynamics.
Medium size pads command the dominant share, while small pads are climbing the fastest as automotive refinishing precision requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional contractors in the United States drive premium cordless platform adoption, while European manufacturers respond to Machinery Directive vibration limits and Asian production centers supply cost-optimized pneumatic tools to emerging markets.
United States
OSHA silica enforcement compels HEPA-class dust extraction integration across commercial construction and woodworking trades. Contractors in California and Michigan specify random-orbit sanders for automotive refinishing clearcoat work. Fleet standardization on 18V and 20V battery platforms concentrates procurement authority with national industrial distributors.
Germany
The EU Machinery Directive enforces hand-held power tool vibration exposure thresholds that shape export-compliant product design. Stuttgart and Munich anchor automotive supplier networks demanding precision surface preparation equipment. Professional channels emphasize integrated dust extraction systems that command price premiums in collision repair chains.
China
Domestic furniture manufacturing and export-oriented woodworking operations absorb volume production of corded electric sanders. Zhejiang and Guangdong provinces host component suppliers for brushless DC motor assemblies. Cost-optimized pneumatic tools from these manufacturing clusters serve Southeast Asian and Latin American price-sensitive segments.
Japan
Automotive OEM supply relationships in Aichi Prefecture sustain demand for clearcoat-grade finishing equipment. METI industrial standards influence regional specifications for vibration emission and dust collection efficiency. Tokyo-Osaka distribution corridors channel premium tool imports to professional refinishing operations.
India
Bureau of Indian Standards certification requirements for power tool safety create compliance barriers for unorganized sector imports. Maharashtra and Gujarat furniture manufacturing clusters drive corded sander volume as contractor-grade cordless adoption lags. Price-sensitive construction trades retain manual and pneumatic alternatives in tier-2 and tier-3 cities.
Orbital Sanders Market Competitive Landscape
Player mix skews toward diversified power tool conglomerates with captive battery ecosystems and specialized surface preparation manufacturers with premium positioning. Market structure concentrates around three strategic tiers: battery platform owners leveraging ecosystem lock-in, vibration-compliant specialists serving European professional channels, and cost-optimized pneumatic fabricators supplying emerging economies. Dominant competitive moves include cordless runtime extension R&D and dust extraction integration partnerships with industrial vacuum OEMs.
Among diversified power tool conglomerates, Bosch GmbH, Makita Corporation, and DeWalt (Stanley Black & Decker Inc.) exemplify the battery platform archetype. These entities anchor professional channel presence through 18V and 20V ecosystem standardization. Festool Group occupies a position within the premium integrated-systems tier, while Mirka Ltd. represents specialization in dust-free sanding technology. Milwaukee Tool (Techtronic Industries) sits within the contractor-grade cordless expansion segment alongside Metabo HPT (Koki Holdings).
| Leading Market Players |
|---|
| Milwaukee |
| Festool |
| Bosch |
| Hutchins Manufacturing Company |
| Makita |
| DeWalt |
| Black & Decker |
| Metabo HPT |
| Mirka |
| Others |
Value Network & Pricing Analysis
Sixty-day neodymium magnet inventory cycles in Guangdong motor assembly plants tether pricing power to rare earth processing concentration in Chinese state-owned refineries. Contractors in the United States face escalating cordless platform costs when magnet spot markets tighten, while European OEMs absorb Machinery Directive compliance premiums through captive vibration-testing infrastructure.
Pricing Analysis
Cost-plus contracts with quarterly neodymium price indexation dominate brushless DC motor procurement from Zhejiang suppliers. Pricing stratifies across premium, standard, and economy tiers based on ISO 28927-3 certification status and dust extraction integration depth. Cost compression in contractor-grade cordless sanders intensifies as DeWalt and Milwaukee discount 20V platform entry tools to capture fleet standardization. DIY enthusiasts exhibit highest price sensitivity, while automotive refinishing shops accept three-tier premiums for clearcoat-grade precision.
Supply Chain Analysis
Port congestion on Shanghai-Los Angeles trade lanes elevates inbound logistics costs for lithium-ion cell shipments bound for Milwaukee and Chicago battery assembly plants. Brushless motor production draws from neodymium processing in China, copper winding supply in Chile, and semiconductor controller fabrication in Taiwan. Single-source vulnerability concentrates in Chinese rare earth magnet refining. Distribution runs through industrial distributors like Grainger and MSC Direct to United States commercial construction fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA silica enforcement and lithium-ion energy density gains are reshaping competitive positioning in professional surface preparation equipment. The window for strategic repositioning narrows as battery platform consolidation accelerates.
For Market Incumbents: Fortify cordless ecosystem lock-in by backward integration into battery cell sourcing and expanding ISO 28927-3 certified testing capacity. Defend against pneumatic tool displacement in automotive refinishing by bundling HEPA-class dust extraction at marginal cost. Prioritize channel control through exclusive industrial distributor arrangements. For New Entrants and Emerging Players: Anchor in tool rental channels serving occasional-use professionals and serious DIY segments where brand loyalty remains unformed. Target emerging economy woodworking clusters in India and Southeast Asia with cost-optimized corded electric platforms. Pursue white-label partnerships with established battery platform owners to bypass cell chemistry R&D barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because OSHA and EU Machinery Directive compliance costs are collapsing the vendor field to capitalized specialists. Acquisition targets include vibration-metrology laboratories and dust-extraction technology specialists serving collision repair chains. Watch battery platform interoperability standards as the signal for ecosystem consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | 18V and 20V ecosystem lock-in captures replacement-cycle revenue through cell degradation. |
| HEPA Dust Extraction Integration | OSHA silica compliance mandates elevate tool-plus-extractor bundled positioning in United States channels. |
| Vibration Testing Lab Acquisition | ISO 28927-3 certification capacity becomes scarce competitive moat as smaller vendors exit. |
| Tool Rental Channel Partnership | Equipment rental platforms access occasional-use professionals without direct sales force investment. |
| Rare Earth Magnet Supply Agreement | Long-term neodymium offtake contracts hedge motor cost volatility from Chinese processing concentration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with power tool product managers, industrial distributor category buyers, OSHA compliance officers, and automotive refinishing shop owners; and secondary validation through SEC 10-K filings, customs trade databases, and ISO certification registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Across the projection horizon, the analytical framework modeled power source type, application workflow, end-user procurement authority, and pad diameter format as core segmentation dimensions. CAGRs derived from regression analysis against construction spending indices, furniture production volumes, and automotive collision repair throughput. Industry-specific inputs included lithium-ion cell energy density improvement curves and OSHA enforcement intensity scoring by United States metropolitan statistical area.
Underlying assumptions cover stable neodymium supply from Chinese processing facilities and sustained OSHA silica standard enforcement, with deviation risk concentrated in battery chemistry disruption and trade policy volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
GCC Machine Tools Market
Tools
North America Power Tools Market
Tools
Rocket Wrench Market
Tools
Reamer Market
Tools
Mechanical Hand Tools Market
Tools
Set Screw Market
Tools
Global DC Torque Tool Market
Tools
Automatic Lathe Machines Market
Tools
Gouging Torch Market
Tools
End Milling Machine Market
Tools
Portable Grinders Market
Tools
Foldable Ladder Market
Tools
Steel Measuring Tape Market
Tools
Hacksaw Blades Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Tool Storage Market