
 Assembly Fastening Tool Market | 2026-2036
Assembly Fastening Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Assembly Fastening Tool Market Analysis
Tool-as-a-service leasing is fragmenting the competitive landscape for capital-intensive fastening equipment. Atlas Copco leverages its rental fleet network to capture mid-tier manufacturers previously priced out of precision tool ownership. Stanley Black & Decker sustains broad channel control through multi-brand distribution spanning professional and industrial tiers. Robert Bosch GmbH anchors its position in cordless electric fastening through proprietary battery platform ecosystems.
Assembly fastening tools are mechanical or powered devices engineered to apply controlled torque for joining components, typically operating within precision tolerances of ±1-5% for critical applications. These tools serve industrial manufacturing by ensuring joint integrity, traceability, and repeatability in high-volume production environments. Pneumatic tools retain dominance in heavy automotive and aerospace applications where sustained high torque output justifies compressed air infrastructure investment. Electric tools, particularly cordless brushless models, represent the fastest-expanding segment as lithium-ion battery energy density improves and factory floor mobility requirements intensify. Hand tools persist as a mature margin pool in repair and commercial construction segments where capital constraints limit power tool adoption.
OSHA workplace safety mandates in the United States and REACH substance restrictions in Europe are elevating ergonomic and material compliance standards for tool manufacturers seeking market access. ISO 5393 and ISO 6789 calibration standards govern torque accuracy certification, creating compliance barriers for uncertified suppliers and service providers. Stakeholders must monitor how battery chemistry regulations and right-to-repair legislation reshape aftermarket service economics and product design roadmaps.
Market Dynamics
EU Battery Regulation torque compliance mandates are forcing automotive OEMs to replace legacy pneumatic systems with precision-calibrated electric fastening equipment across European EV assembly lines.
Growth Catalysts
- REACH substance restrictions:European manufacturers must retrofit tool fleets to eliminate restricted materials, triggering replacement cycles for compliant battery-powered alternatives.
- Battery pack architecture:EV manufacturers require 40% more fastening points per vehicle than internal combustion platforms, expanding tool density on assembly lines.
- Germany:Stuttgart and Wolfsburg manufacturing clusters concentrate capital equipment investment, absorbing premium precision tool capacity.
Market Restraints
- Lithium-ion cell costs:Battery chemistry price volatility compresses margins for cordless tool manufacturers dependent on cylindrical cell supply.
- Compressed air infrastructure:Heavy automotive plants in Detroit and Turin face sunk-cost constraints blocking full electrification of fastening systems.
- ISO 5393 calibration:Third-party certification requirements create 6-12 month market entry barriers for uncertified Asian suppliers.
Strategic Opportunities
- India PLI scheme:Domestic manufacturing incentives for automotive and electronics assembly create virgin demand for mid-tier precision tools.
- Tool-as-a-service models:Leasing platforms capture small-batch manufacturers in Poland and Czech Republic previously excluded by capital constraints.
- Brushless motor-battery convergence:Integration of high-torque density motors with solid-state battery prototypes enables cordless penetration into aerospace applications.
Industry Challenges
- Mechatronics technician scarcity:Factory floors lack personnel capable of diagnosing integrated torque-angle monitoring systems in smart tools.
- Legacy system integration:Plant engineers struggle to retrofit Industry 4.0 data-logging capabilities onto 1990s-vintage pneumatic controllers without full line shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assembly Fastening Tool Market |
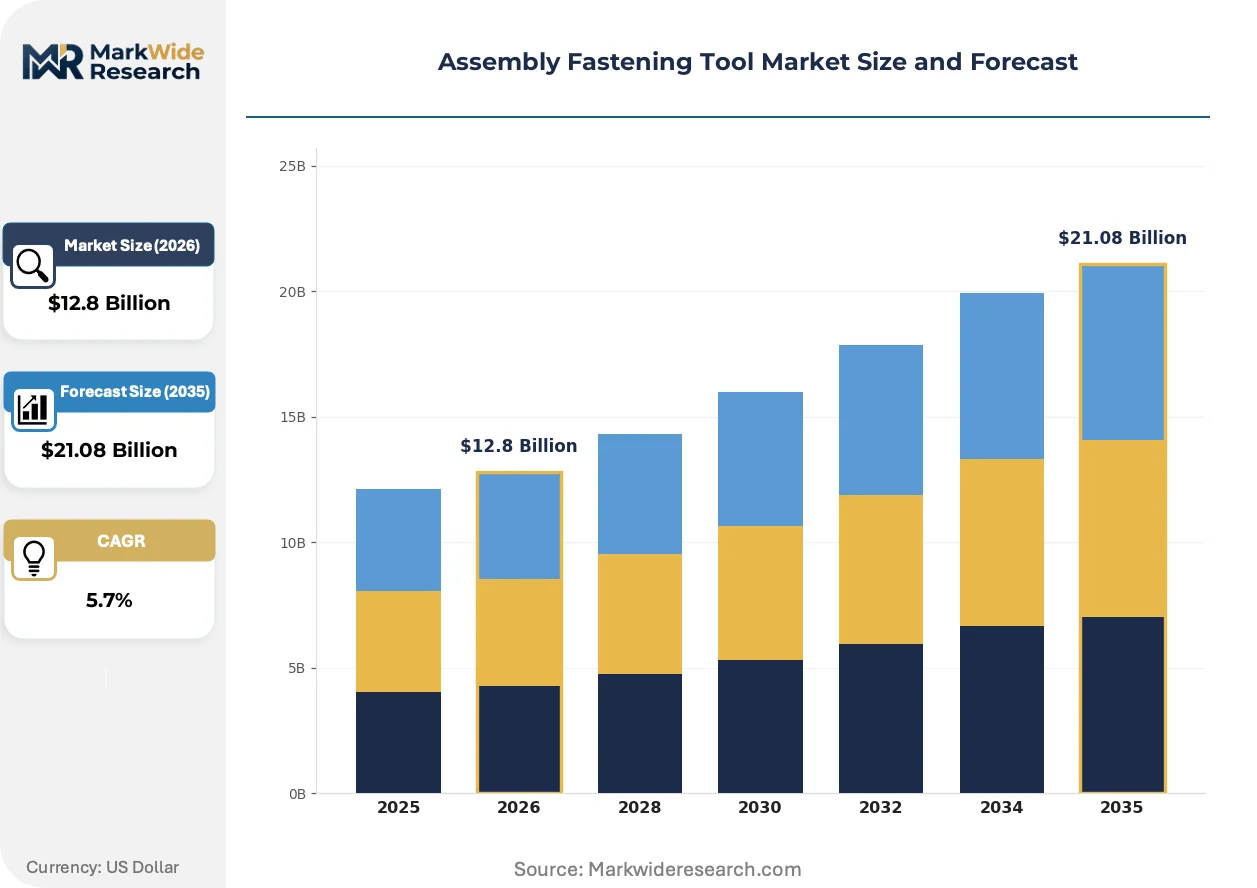
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Tools, Hand Tools, Pneumatic Tools, Electric Tools End User: Aerospace, Automotive OEMs, Construction, Electronics Technology: Electric, Pneumatic, Hydraulic, Manual Application: Residential, Industrial, Commercial, Repair |
| Companies Covered | Stanley Black & Decker, Atlas Copco, Robert Bosch GmbH, Ingersoll Rand, Hilti Corporation, Makita Corporation, Snap-on Incorporated, Apex Tool Group, Chicago Pneumatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assembly Fastening Tool Market Emerging Trajectories
Digital torque traceability and cordless power density are converging to redefine factory floor mobility requirements and joint quality assurance protocols across precision manufacturing.
Brushless DC motor technology is collapsing the performance gap between cordless electric and pneumatic fastening systems in high-torque automotive applications. Tier-1 suppliers in Germany and Japan are adopting 1,000+ Nm cordless models for chassis assembly. This convergence is collapsing the historical infrastructure advantage of compressed air in heavy manufacturing.
EU Battery Regulation mandatory carbon footprint declarations for industrial batteries are forcing tool manufacturers to redesign supply chains and select cell suppliers based on lifecycle emissions data. Assembly plants in France and Spain now require battery documentation traceability. Cordless tool OEMs are responding by securing European cell assembly partnerships.
Outcome-based contracting is displacing capital purchase models among mid-volume manufacturers seeking to transfer calibration and maintenance liability. German automotive suppliers and Mexican electronics assemblers increasingly specify torque accuracy guarantees rather than equipment ownership. This shift concentrates service capability requirements among fewer integrated vendors.
Assembly Fastening Tool Market Segmentation
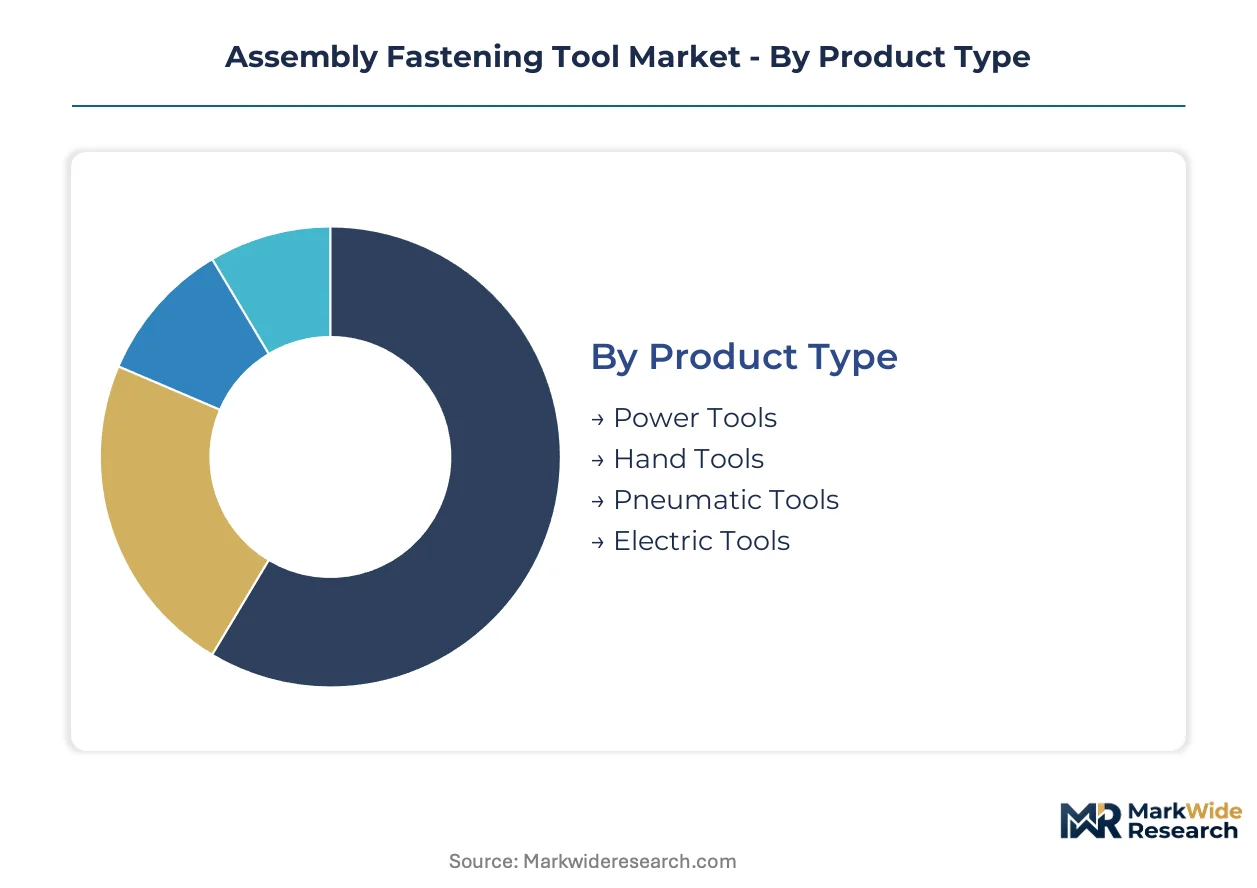
Fastening tool procurement cycles vary dramatically by segment, with cordless electric platforms turning over every 4-6 years while pneumatic infrastructure persists for 15-20 years. Understanding these replacement rhythms helps suppliers align inventory, service capacity, and financing products to actual customer behavior.
Product Type:
Cycle times compress from decades-long pneumatic installations to rapid cordless refresh cycles driven by battery degradation and motor wear patterns.
- Power Tools:Cordless brushless platforms with integrated torque-angle monitoring dominate new automotive line installations. Stuttgart and Wolfsburg OEMs specify these for EV battery pack assembly where ±3% accuracy meets EU Battery Regulation mandates.
- Hand Tools:Mechanical torque wrenches and click-type drivers serve calibration backup roles and capital-constrained repair operations. Demand persists in Eastern European construction markets where compressed air infrastructure remains sparse and electricity access unreliable.
- Pneumatic Tools:Sustained high-torque output (1,500+ Nm) justifies compressed air investment in heavy chassis assembly. Turin and Detroit plants retain these for legacy truck platforms where electrification economics fail.
- Electric Tools:Corded and cordless variants split by mobility requirements; battery energy density improvements now enable 800+ Nm output previously reserved for pneumatic systems. German Tier-1 suppliers are standardizing on 18V and 36V platforms for line flexibility.
Pneumatic tools dominate installed base across heavy manufacturing. Electric tools are where expansion concentrates.
End User:
Capital intensity and precision requirements stratify customers into three distinct procurement tiers with radically different vendor engagement models.
- Aerospace:AS9100-certified torque systems with full traceability documentation and 100% calibration records. Boeing and Airbus suppliers in Toulouse and Hamburg mandate digital data logging for every critical joint.
- Automotive OEMs:High-volume, low-mix production demands 99.97% uptime guarantees and rapid tool swap protocols. Battery electric platforms require 40% more fastening points per vehicle, expanding tool density on Stuttgart and Munich assembly lines.
- Construction:Price-sensitive, high-abuse environments favor robust pneumatic impact wrenches and durable hand tools. German commercial builders prioritize ergonomic certification to comply with workplace safety mandates.
- Electronics:Precision torque control below 5 Nm for circuit board assembly and miniature fastener applications. Czech Republic and Poland contract manufacturers drive demand for programmable electric screwdrivers with ESD protection.
Automotive OEMs absorb the highest absolute tool volumes. Electronics assembly is climbing the fastest as reshoring accelerates.
Technology:
Energy transfer mechanisms determine infrastructure requirements, maintenance burden, and the feasibility of Industry 4.0 integration.
- Electric:Brushless DC motors with lithium-ion power cells enable untethered operation and embedded torque sensors. Solid-state battery prototypes promise 50% energy density gains for aerospace cordless adoption.
- Pneumatic:Compressed air systems deliver consistent high torque but anchor factories to fixed infrastructure. Italian and US Midwest plants face sunk-cost constraints blocking full electrification.
- Hydraulic:Extreme torque applications (3,000+ Nm) in heavy machinery and wind turbine assembly where electric and pneumatic systems fail. German offshore wind installers specify these for tower flange bolting.
- Manual:Click-type and beam-style torque wrenches serve calibration standards, field service, and low-volume repair. REACH substance restrictions are forcing material retrofits in European-manufactured units.
Pneumatic technology holds the largest legacy footprint. Electric systems are gaining share fastest across all new line builds.
Application:
Usage intensity and regulatory exposure separate commercial and industrial demand from intermittent residential and repair consumption.
- Residential:DIY cordless drill-drivers and basic impact tools sold through retail channels. German home improvement retailers emphasize battery platform compatibility to lock repeat purchases.
- Industrial:Continuous-duty precision tools with predictive maintenance contracts and guaranteed uptime clauses. Mexican electronics assemblers increasingly specify outcome-based torque accuracy guarantees rather than equipment ownership.
- Commercial:General construction and facility maintenance requiring durability over precision. Polish and Czech mid-tier manufacturers lease tools through service platforms to bypass capital constraints.
- Repair:Mobile service tools with calibration certification for warranty compliance. German automotive service chains demand ISO 6789-traceable equipment for EV battery servicing under manufacturer warranty terms.
Industrial applications command the highest service attachment rates. Repair segments are expanding most quickly as EV fleet maintenance requirements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for automotive and electronics manufacturing is redirecting procurement toward mid-tier precision tools. Germany's EU Battery Regulation compliance mandates are forcing EV assembly line retrofits. China's dual carbon goals are accelerating factory electrification away from pneumatic systems.
Germany
Stuttgart and Wolfsburg automotive clusters absorb premium cordless fastening capacity for EV battery pack assembly. KBA enforces torque specification traceability under EU Battery Regulation carbon footprint rules. Munich-based Tier-1 suppliers are standardizing 18V and 36V platforms for line flexibility.
United States
Detroit heavy truck plants retain pneumatic infrastructure for legacy platforms while EV startups in Austin and California adopt cordless systems. OSHA workplace safety mandates elevate ergonomic certification requirements for tool procurement. Southeast electronics contract manufacturers in Tennessee and South Carolina are leasing precision tools through service platforms.
China
MIIT industrial upgrading guidelines favor brushless electric tools over compressed air in Yangtze River Delta manufacturing zones. Dual carbon targets are pressuring Shenzhen and Suzhou assembly plants to dismantle pneumatic infrastructure. NMPA-style quality enforcement is tightening calibration documentation for export-oriented suppliers.
India
Maharashtra and Gujarat automotive hubs are expanding tool procurement under PLI scheme domestic manufacturing incentives. BIS certification requirements are blocking uncertified Asian suppliers from government-linked contracts. Chennai electronics assemblers are creating virgin demand for programmable electric screwdrivers with ESD protection.
Japan
METI factory automation subsidies are accelerating cordless adoption in Nagoya and Osaka automotive supplier networks. JIS torque accuracy standards create compliance barriers for non-certified imports. Precision tool demand concentrates in Aichi Prefecture where Toyota and Honda maintain dense supplier ecosystems.
Assembly Fastening Tool Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The market structure consolidates around three archetypes: diversified industrial conglomerates with multi-brand distribution, precision-focused specialists with rental fleet networks, and battery-platform ecosystem builders. M&A activity targets calibration service capabilities. Geographic expansion into Indian and Mexican manufacturing corridors accelerates.
Within the diversified industrial tier, Stanley Black & Decker and Atlas Copco represent contrasting scale strategies. Robert Bosch GmbH anchors the battery-platform ecosystem archetype through proprietary 18V and 36V systems. These three players exemplify how channel control, service infrastructure, and energy storage integration define competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Atlas Copco |
| Robert Bosch GmbH |
| Ingersoll Rand |
| Hilti Corporation |
| Makita Corporation |
| Snap-on Incorporated |
| Apex Tool Group |
| Chicago Pneumatic |
| Others |
Supply Flow & Price Mechanics
Cylindrical lithium-ion cell production concentrates in China, South Korea, and Japan, anchoring margin capture at the battery pack tier and compressing cordless tool OEMs into assembly and firmware layers. Pricing power downstream depends on calibration service bundling and ISO 5393 certification tiers rather than hardware differentiation alone.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with ISO 5393-accurate tools commanding service-attach premiums from German automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels stratifies by torque accuracy, battery platform compatibility, and aftermarket calibration coverage. Cost compression in mid-tier cordless segments intensifies because cylindrical cell price volatility transfers directly to BOM costs. Electronics contract manufacturers in Eastern Europe exhibit highest price sensitivity, while aerospace suppliers in Toulouse and Hamburg accept premium positioning for AS9100 traceability documentation.
Supply Chain Analysis
Export controls on brushless motor controllers and high-precision torque sensors limit technology flows from Germany and Japan to uncertified Asian assemblers. Manufacturing concentrates in China for battery cells, Germany for precision mechanical components, and Japan for sensor electronics. Raw material dependencies span neodymium for rare-earth magnets, lithium carbonate for cathodes, and specialty steel alloys for drive trains. Single-source vulnerability runs through cylindrical cell supply from concentrated Asian producers. Distribution runs through OEM direct procurement for automotive Tier 1s and rental fleet networks for mid-volume commercial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The assembly fastening tool market rewards service-attach models where calibration and predictive maintenance contracts expand recurring revenue faster than cordless platform hardware sales. Leasing platforms and outcome-based torque guarantees represent the fastest-climbing revenue layers.
For Market Incumbents: Harden calibration service infrastructure against emerging tool-as-a-service competitors by securing ISO 17025-accredited laboratory networks in Stuttgart and Detroit. Deepen backward integration into solid-state battery cell partnerships to reduce cylindrical supply exposure. Channel control through multi-brand distribution remains defensible against specialist rental entrants only if firmware update cadence matches customer uptime requirements. For New Entrants and Emerging Players: Mid-market electronics assemblers in Poland and the Czech Republic represent the most penetrable entry point, with capital constraints excluding them from precision tool ownership and creating leasing demand. Programmable electric screwdrivers with ESD protection for circuit board assembly offer lower certification barriers than automotive-grade systems. Go-to-market through existing industrial equipment rental platforms bypasses direct sales force buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across tool-as-a-service sub-segments as fleet utilization software reduces working capital requirements. Long-term viability favors vendors with integrated calibration capabilities and battery platform ecosystems over pure hardware manufacturers. Acquisition targets should display ISO 17025 service lab footprints and recurring revenue above forty percent of total sales. The signal to watch is EV battery pack architecture standardization, which would concentrate procurement authority at fewer OEMs and reward scale players.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | ISO 17025 accreditation in Stuttgart and Detroit secures EU Battery Regulation compliance contracts from automotive OEMs. |
| Solid-State Battery Partnership | European cell assembly agreements satisfy mandatory carbon footprint declarations under EU industrial battery rules. |
| Tool-as-a-Service Platform Launch | Leasing models capture Polish and Czech mid-tier manufacturers previously excluded by capital constraints. |
| Torque-Angle Monitoring Integration | Embedded sensors enable outcome-based contracting with Mexican electronics assemblers seeking accuracy guarantees. |
| Brushless Motor Controller Localization | Domestic production in India bypasses BIS certification barriers for government-linked PLI scheme contracts. |
Methodological Framework
The analysis maps cordless electric, pneumatic, hydraulic, and manual fastening platforms, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with industrial equipment stakeholders combined secondary validation through customs and trade data, SEC filings from diversified industrial conglomerates, ISO certification registries, and automotive production databases. Bottom-up tool shipment analysis and top-down manufacturing value-added estimates triangulate market sizing across product and end-use dimensions.
Assumptions held fixed include EU Battery Regulation torque compliance mandates, OSHA ergonomic enforcement trajectories, and lithium-ion cell cost curves; variables tested include solid-state battery commercialization timing, India PLI scheme disbursement rates, and REACH substance restriction expansion. The projection horizon spans product type, technology, end user, and application segments with regional production cluster overlays. CAGRs derive from replacement cycle analysis, with cordless platform refresh rates modeled separately from pneumatic infrastructure persistence. Industry-specific inputs include EV battery pack fastening point density per vehicle and aerospace AS9100 certification adoption curves.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, industrial capital expenditure cycles, or battery raw material prices would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Flooring Tools Market
Tools
End Mill Holder Market
Tools
Total Station Market
Tools
Handheld Engraving Machine Market
Tools
Belt File Sander Market
Tools
Cordless Power Drill Market
Tools
Global Vertical Grinding Machine Market
Tools
Drain Cleaning Equipment Market
Tools
Garden Digging Tools Market
Tools
Woodpecker Tools Market
Tools
Gear Honing Machines Market
Tools
Global Tools Storage Products Market
Tools
Industrial Floor Scrubber Market
Tools
Indexable Tool Inserts Market
Tools
Manual Cutting Equipment Market
Tools
Digital Laser Levels Market