
 Bottled Water Processing Equipment Market | 2026-2036
Bottled Water Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Water Processing Equipment Market Outlook
Multi-source procurement among large bottlers is consolidating as equipment buyers favor integrated system suppliers over discrete component vendors. GEA Group Aktiengesellschaft leverages its hygienic processing portfolio to anchor long-term service contracts with multinational beverage clients. Krones dominates turnkey line integration, while Xylem competes through advanced oxidation and UV treatment technologies for emerging market plants.
Bottled water processing equipment encompasses mechanical and chemical systems designed to treat, purify, sanitize, and package potable water for commercial distribution, typically operating at flow rates from 5,000 to 100,000 liters per hour with stainless steel construction meeting 3-A sanitary standards. Filtration systems and filling machines constitute the core capital expenditure for manufacturing plants, with reverse osmosis and ultraviolet treatment representing the fastest-growing technology pairing as bottlers replace legacy chlorination. Ozonation retains share among premium spring water bottlers seeking residual-free disinfection, while quality control equipment margins expand with inline spectroscopic monitoring adoption.
The US FDA enforces bottled water quality standards under 21 CFR 165.110, compelling equipment validation for contaminant removal claims, while the EU Drinking Water Directive and REACH chemical safety rules shape material selection for European installations. China's NMPA and GB standards mandate dual-barrier treatment for packaged drinking water, creating specification divergence that complicates cross-border equipment sales. Stakeholders must weigh regional certification burdens against platform standardization when configuring global manufacturing footprints.
Market Dynamics
Automated filling line expansion across Asia-Pacific bottling plants is compressing equipment replacement cycles and consolidating procurement toward integrated system suppliers capable of delivering multi-barrier treatment validation.
Growth Catalysts
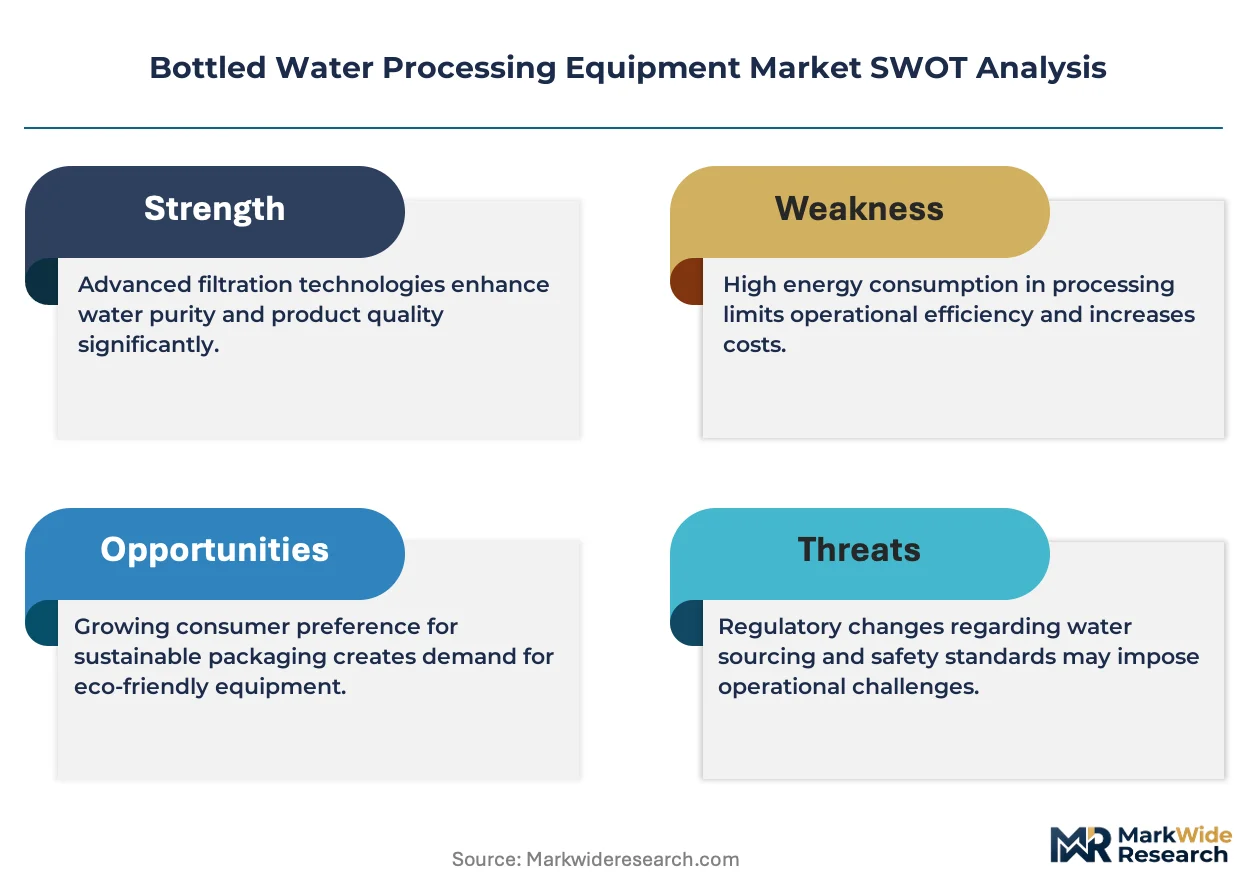
- China's NMPA dual-barrier mandate:Bottlers must deploy sequential disinfection technologies, forcing upgrades from single-stage chlorination to combined UV-ozone systems and expanding addressable equipment spend.
- Reverse osmosis membrane advances:Spiral-wound configurations now achieve 99.5% dissolved solid rejection at lower operating pressures, reducing energy costs for high-volume spring water processors in India and Indonesia.
- Municipal water variability:Inconsistent source quality across Chinese and Indian distribution networks compels premium processing investments to ensure batch consistency for multinational brand standards.
Market Restraints
- Stainless steel alloy volatility:316L sanitary-grade steel price swings directly compress equipment margins, particularly for mid-scale bottlers in Southeast Asia with limited forward-contracting capacity.
- Skilled technician scarcity:Advanced oxidation system maintenance requires certified specialists; training pipeline gaps in Vietnam and Philippines extend commissioning timelines and inflate service costs.
- REACH chemical compliance:EU material safety rules restrict certain sealant and coating chemistries, fragmenting component sourcing and complicating platform standardization for multinational equipment vendors.
Strategic Opportunities
- Indonesian archipelago expansion:Dispersed island populations with unreliable municipal infrastructure create demand for compact, containerized treatment skids serving regional bottling cooperatives.
- Inline spectroscopic monitoring:Real-time contaminant detection enables predictive maintenance contracts, shifting revenue from capital sales to recurring service streams with higher retention rates.
- India's PLI scheme for food processing:Domestic manufacturing incentives reduce import duties on locally assembled filling equipment, lowering total cost of ownership for mid-market bottlers.
Industry Challenges
- Legacy chlorination retrofit complexity:Existing plants face production downtime during multi-barrier system integration, requiring phased commissioning that strains working capital.
- Cross-border certification divergence:China's GB standards, FDA 21 CFR 165.110, and EU Drinking Water Directive specify incompatible validation protocols, forcing redundant engineering for global equipment platforms.
- Specialized commissioning engineer shortage:Multi-technology integration demands expertise spanning membrane filtration, UV reactor sizing, and ozone contactor design; talent pools concentrate in Germany and Italy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Water Processing Equipment Market |
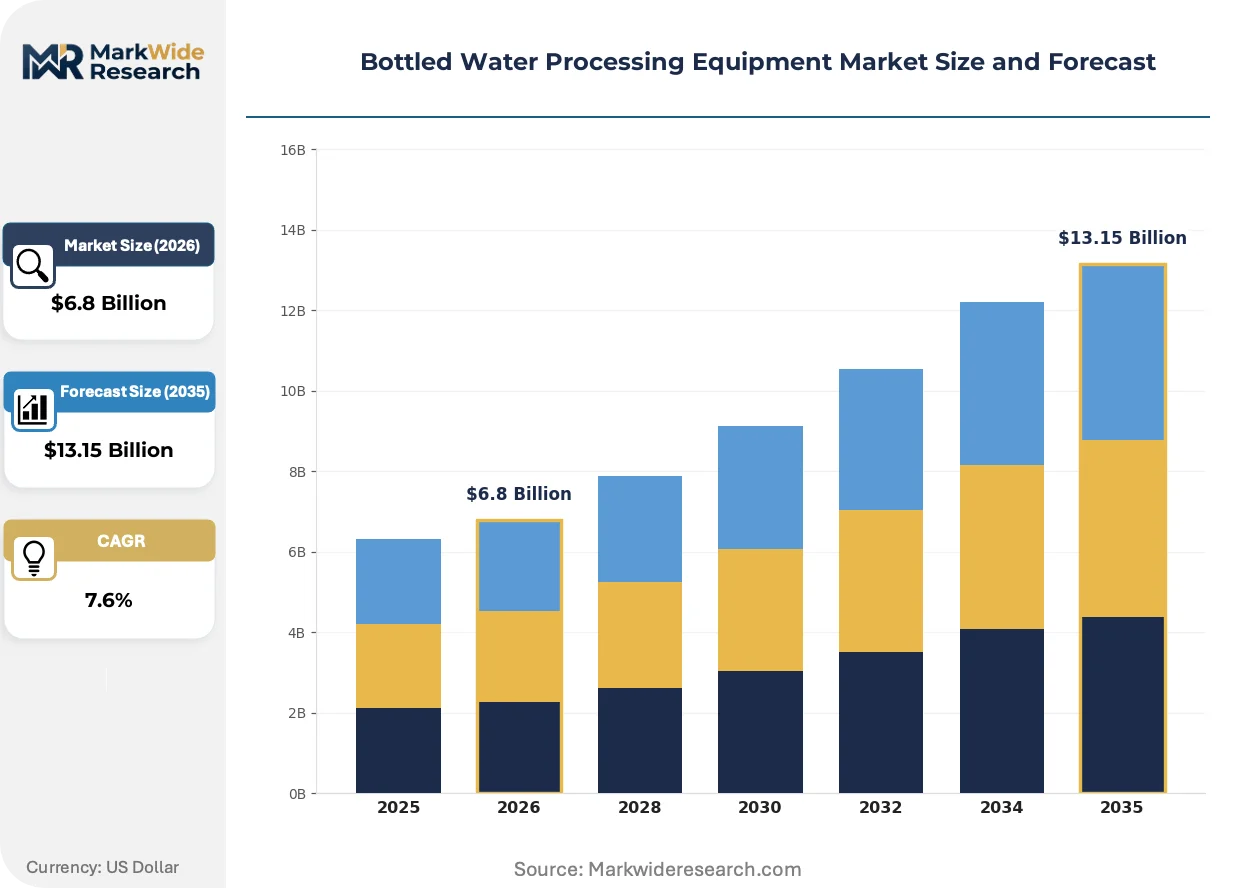
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, Sanitization Units, Filling Machines, Quality Control Equipment Technology: Reverse Osmosis, Ultraviolet Treatment, Ozonation, Microfiltration End User: Manufacturing Plants, Bottling Companies, Retail Outlets, Beverage Distributors Service Type: Installation Services, Maintenance Services, Consulting Services, Upgrade Services |
| Companies Covered | DuPont, GEA Group Aktiengesellschaft, Alfa Laval, SUEZ, Pall Corporation, The Dow Chemical Company, Krones, Xylem, Pentair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Water Processing Equipment Market Strategic Shifts
Equipment intelligence and modular architecture are rewriting competitive differentiation, as bottlers prioritize flexible capacity expansion over fixed-line investments and regulators tighten real-time quality verification requirements.
Membrane bioreactor pretreatment is rewriting conventional coagulation-flocculation sequences in surface water bottling plants. Indonesian and Vietnamese processors facing high-turbidity source water are adopting ceramic ultrafiltration ahead of reverse osmosis to reduce chemical consumption. This convergence is compressing civil works requirements and enabling faster site deployment for greenfield installations.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-based water chiller obsolescence in European bottling facilities. Magnetic bearing compressor technology and adiabatic cooling systems are capturing replacement demand as operators face mandatory refrigerant reclamation costs. German and Italian equipment integrators now specify natural refrigerant loops as default for new filling line contracts.
Service unbundling is fragmenting traditional turnkey procurement patterns among Asia-Pacific bottlers. Large multinationals now separate capital equipment purchase from long-term maintenance agreements, awarding aftermarket contracts to specialized regional service firms. This bifurcation is most pronounced in China's tier-two cities, where local integrators undercut OEM service pricing while multinational brands demand validated spare part traceability.
Bottled Water Processing Equipment Market Segmentation
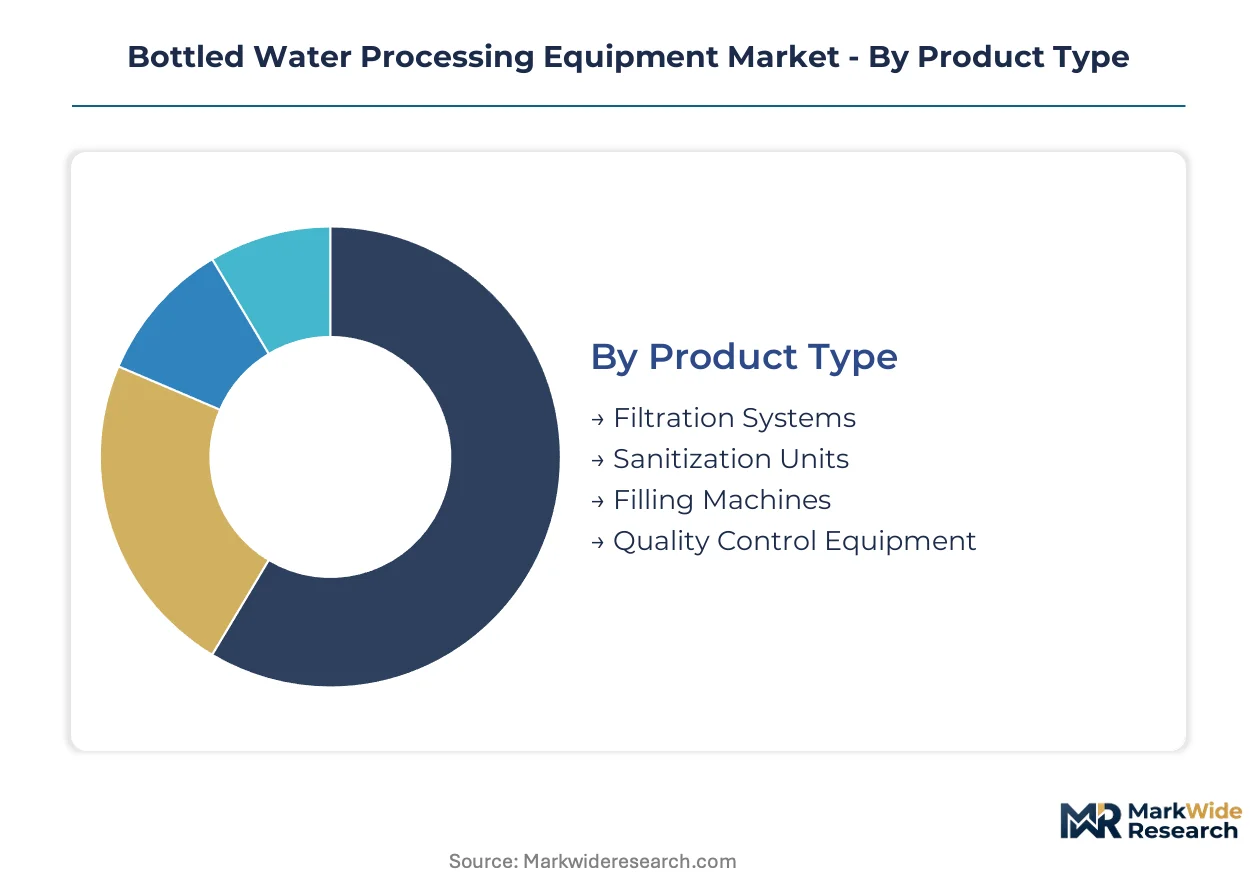
Equipment specification divergence across regulatory jurisdictions fragments procurement patterns. Bottlers configure processing lines around mandatory treatment sequences rather than operational efficiency alone. Segment concentration reflects where capital deployment intersects with compliance-driven technology refresh cycles.
Product Type:
Supply concentration clusters around integrated system architectures that bundle sequential treatment stages under single-source validation.
- Filtration Systems:Mechanical separation equipment employing reverse osmosis membranes, activated carbon beds, and multi-media pressure vessels to remove particulate and dissolved contaminants. Chinese manufacturing plants facing NMPA dual-barrier mandates drive specification intensity for ceramic ultrafiltration pretreatment ahead of final polishing stages.
- Sanitization Units:Chemical and physical disinfection systems including ozone contactors, UV reactors, and chlorine dosing skids designed to achieve log reduction targets. Bottling companies across Indonesia's archipelago prioritize compact ozone generators with integrated residual destruction for island-based cooperatives lacking technical infrastructure.
- Filling Machines:Rotary and linear configurations handling 5,000 to 100,000 liters per hour with aseptic or clean-fill protocols.
- Quality Control Equipment:Inline spectroscopic monitors, laboratory testing apparatus, and automated sampling systems for batch verification.
Today's leader: Filtration Systems. Tomorrow's challenger: Quality Control Equipment.
Technology:
Cost tier stratification separates premium membrane configurations from commodity chemical treatment alternatives.
- Reverse Osmosis:Spiral-wound membrane arrays achieving dissolved solid rejection above 99.5 percent at reduced operating pressures through advanced thin-film composite chemistry. Indian bottling companies exploit PLI scheme incentives to source locally assembled high-rejection systems for municipal water with high TDS variability.
- Ultraviolet Treatment:Medium-pressure and low-pressure amalgam lamp reactors delivering dose-dependent pathogen inactivation without chemical residuals. Manufacturing plants in Vietnam adopt UV-ozone sequential configurations to satisfy emerging market brand standards while minimizing chemical handling complexity.
- Ozonation:Corona discharge and UV-generated ozone systems providing residual-free disinfection for premium spring water positioning.
- Microfiltration:Cross-flow ceramic and polymeric membrane systems targeting bacteria and protozoa removal at lower energy intensity than reverse osmosis.
Reverse Osmosis commands current procurement volumes. Ultraviolet Treatment is climbing the fastest as dual-barrier mandates proliferate.
End User:
Volume concentration among multinational bottlers with standardized global specifications contrasts with fragmented regional cooperative demand.
- Manufacturing Plants:Greenfield and brownfield production facilities requiring turnkey processing line integration with civil works coordination. Chinese tier-one city installations specify fully automated CIP-compatible systems to minimize labor dependence amid wage inflation.
- Bottling Companies:Mid-scale enterprises operating single or multiple lines with batch flexibility requirements. Indonesian regional bottlers drive demand for containerized skids enabling rapid deployment across dispersed island populations.
- Retail Outlets:Point-of-sale water vending and refill stations with compact footprint constraints.
- Beverage Distributors:Third-party logistics providers with limited direct processing investment scope.
Bottling Companies anchor equipment procurement volumes. Manufacturing Plants represent the steepest expansion trajectory as multinational capacity scales.
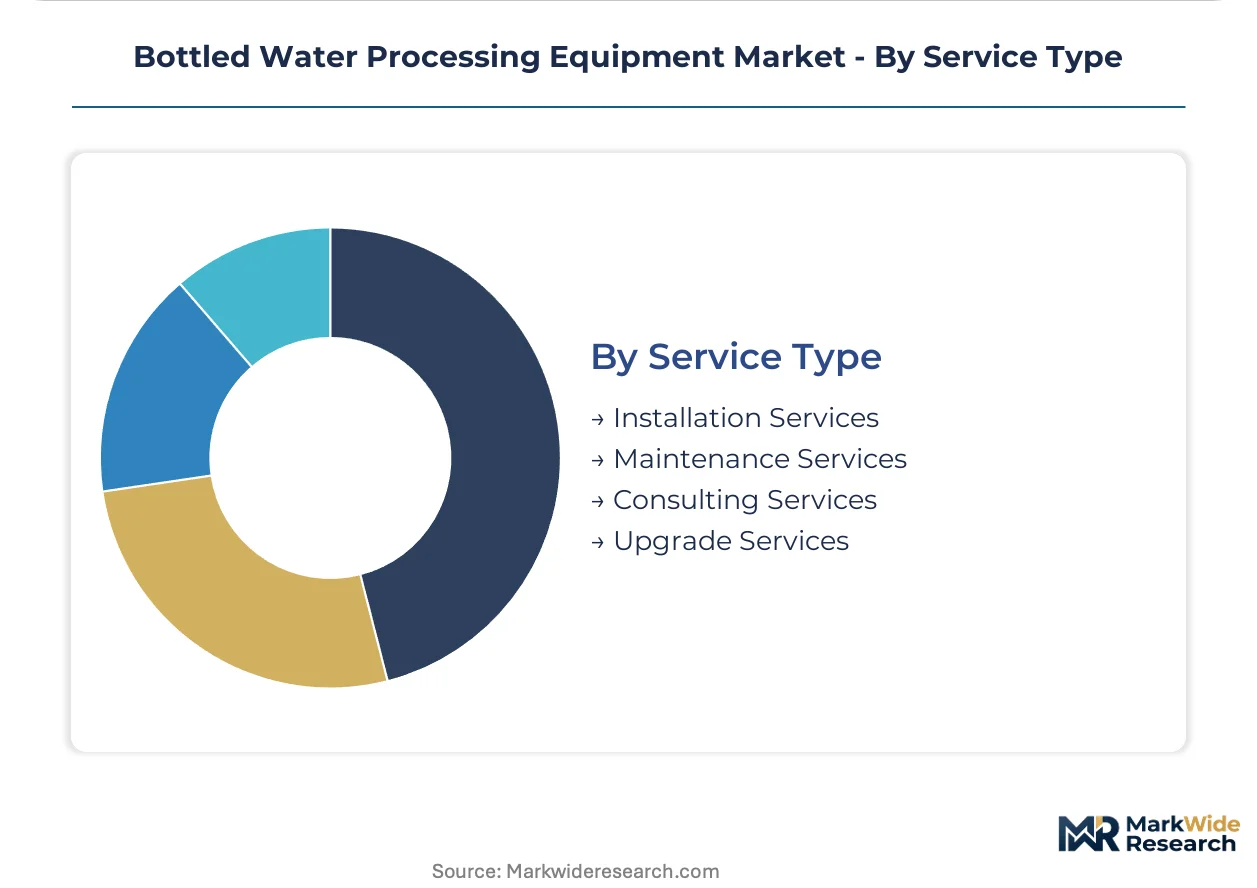
Service Type:
Margin concentration shifts from capital sales toward recurring revenue streams as aftermarket unbundling fragments traditional procurement.
- Maintenance Services:Preventive and corrective service contracts covering membrane replacement, lamp degradation monitoring, and calibration validation. Indian tier-two bottlers increasingly award these contracts to regional specialists undercutting OEM pricing while demanding traceable spare part documentation.
- Installation Services:Commissioning support including factory acceptance testing, site acceptance testing, and operator training. Philippine bottling projects face extended timelines due to certified technician scarcity for advanced oxidation system startup.
- Consulting Services:Regulatory compliance advisory and process optimization studies.
- Upgrade Services:Legacy chlorination retrofit and multi-barrier system integration for existing lines.
Maintenance Services capture recurring revenue priority. Upgrade Services face constraint from production downtime tolerance limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors equipment procurement intensity, with Shanghai and Jiangsu province bottlers deploying multi-barrier systems to satisfy NMPA dual-treatment mandates while expanding automated filling capacity for domestic and export brands.
China
Municipal water variability across tier-one and tier-two cities drives premium processing investments as bottlers seek batch consistency for multinational brand standards. NMPA regulations mandate sequential disinfection technologies, compelling upgrades from single-stage chlorination to combined UV-ozone configurations. Guangdong province bottlers in the Pearl River Delta concentrate procurement of ceramic ultrafiltration pretreatment systems ahead of reverse osmosis polishing stages.
India
High TDS variability in municipal supply networks compels reverse osmosis membrane deployment across Maharashtra and Karnataka manufacturing clusters. FSSAI packaged drinking water standards enforce multi-stage treatment validation, while the PLI scheme for food processing reduces import duties on locally assembled filling equipment. Gujarat-based bottlers exploit domestic manufacturing incentives to source high-rejection spiral-wound systems at lower total cost of ownership.
Indonesia
Dispersed island populations with unreliable municipal infrastructure create demand for compact, containerized treatment skids serving regional bottling cooperatives. The national food and drug regulator enforces dual-barrier treatment specifications for packaged drinking water, accelerating ozone generator deployment with integrated residual destruction. Java-based processors in Surabaya and Bandung prioritize rapid-deployment modular systems enabling capacity expansion across archipelago logistics constraints.
United States
Spring water bottlers in the Appalachian region and Pacific Northwest invest in ozonation systems for residual-free disinfection positioning premium brands. FDA enforcement of 21 CFR 165.110 compels equipment validation for contaminant removal claims, particularly for emerging contaminant monitoring. Texas and California manufacturing plants specify fully automated CIP-compatible lines to minimize labor dependence amid regional wage inflation pressures.
Germany
EU F-Gas Regulation phase-down schedules accelerate refrigerant-based water chiller obsolescence in Bavarian and North Rhine-Westphalian bottling facilities. REACH chemical safety rules restrict certain sealant and coating chemistries, fragmenting component sourcing for equipment integrators. Stuttgart and Munich industrial clusters specify natural refrigerant loops as default for new filling line contracts, with magnetic bearing compressor technology capturing replacement demand.
Bottled Water Processing Equipment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue containerized skid architectures for dispersed geographic markets. Market structure consolidates around integrated system suppliers capable of delivering multi-barrier treatment validation under single-source contracts. Three archetypes dominate: European hygienic processing specialists anchoring long-term service agreements, German-Italian turnkey line integrators controlling high-volume automated installations, and water technology multinationals competing through advanced oxidation and UV treatment platforms. Competitive intensity manifests through strategic partnerships for regional commissioning support and portfolio diversification into predictive maintenance service streams.
Within the integrated system tier, GEA Group Aktiengesellschaft and Krones exemplify divergent positioning strategies. GEA leverages its hygienic processing portfolio to anchor recurring service contracts with multinational beverage clients seeking validated spare part traceability. Krones occupies the turnkey line integration position, bundling sequential treatment stages under single-source validation protocols for greenfield manufacturing plants. Xylem represents the water technology archetype, competing through advanced oxidation and UV treatment platforms for emerging market installations requiring multi-barrier compliance without chemical handling complexity.
| Leading Market Players |
|---|
| DuPont |
| GEA Group Aktiengesellschaft |
| Alfa Laval |
| SUEZ |
| Pall Corporation |
| The Dow Chemical Company |
| Krones |
| Xylem |
| Pentair |
| Others |
Value Chain & Pricing Dynamics
Backward integration into membrane manufacturing anchors pricing power for European equipment integrators serving multinational bottlers with validated spare part traceability requirements. This captive supply of thin-film composite elements insulates margin structures from 316L stainless steel alloy volatility while compressing procurement cycles for high-rejection reverse osmosis configurations.
Pricing Analysis
Input-cost pass-through from specialty steel and ceramic membrane feedstocks governs equipment quotation structures across the forecast period. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated multi-barrier systems from single-stage chlorination retrofits and compact containerized skids. Cost compression in the standard tier is intensifying because Indian PLI scheme incentives expand domestic assembly capacity. Mid-scale Southeast Asian bottlers exhibit highest price sensitivity, while multinational brands with global specification mandates absorb premium validation costs without volume elasticity.
Supply Chain Analysis
Dual-sourcing requirements for UV lamp amalgams and ozone generator electrodes compel equipment vendors to qualify suppliers across Germany, Japan, and South Korea simultaneously. Component sourcing draws from specialty steel mills in Germany and Italy, ceramic membrane foundries in Japan, and electronic control module assemblers in South Korea. Single-source vulnerability concentrates in high-purity quartz sleeve manufacturing for UV reactor assemblies. Distribution runs through turnkey line integrators for greenfield manufacturing plants and regional service specialists for aftermarket maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift from capital equipment sales toward predictive maintenance service streams with higher retention rates and lower customer acquisition costs.
For Market Incumbents: Lock in long-term service contracts with multinational beverage clients by embedding inline spectroscopic monitoring hardware that enables recurring calibration and lamp replacement revenue. Deepen backward integration into membrane manufacturing to defend margin position against specialty steel price swings. Prioritize certification investment for China's NMPA dual-barrier validation protocols to preempt regional specialist encroachment in tier-two city markets.
For New Entrants and Emerging Players: Capture containerized skid demand from Indonesian archipelago bottling cooperatives lacking technical infrastructure for distributed island populations. Target compact ozone generator configurations with integrated residual destruction as the most penetrable product category. Pursue direct equipment leasing paired with remote monitoring subscriptions as the go-to-market angle to bypass upfront capital constraints among regional cooperatives.
For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service specialists because multinational OEMs are unbundling maintenance contracts and local integrators undercut validated spare part pricing. Five-to-ten year viability favors platforms consolidating Philippine and Vietnamese service networks where certified technician scarcity extends commissioning timelines. Watch NMPA enforcement intensity against single-stage chlorination plants as the inflection signal for upgrade services demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Inline spectroscopic monitoring shifts revenue from capital sales to recurring service streams with higher retention rates. |
| Backward Integration into Membrane Manufacturing | Captive thin-film composite production insulates margins from 316L stainless steel alloy price volatility. |
| Containerized Skid Product Line Expansion | Compact treatment systems address Indonesian archipelago logistics constraints for dispersed island cooperatives. |
| Dual-Barrier Certification Investment | NMPA validation protocols preempt regional specialist competition in China's tier-two city markets. |
| Regional Service Network Acquisition | Consolidation of Philippine and Vietnamese aftermarket specialists captures unbundled maintenance contract demand. |
Study Parameters
Bottom-up bottling company capacity modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with plant engineers, OEM procurement managers, aftermarket service heads, and regulatory compliance officers at NMPA and FSSAI intersected with secondary validation against customs records, SEC 10-K filings of listed equipment vendors, and national food and drug regulator enforcement disclosures. Triangulation across these sources ensures segmentation outputs reflect actual procurement patterns rather than vendor-reported aspirations.
Historical trendline analysis of filtration system and filling machine deployments established baseline growth trajectories across the projection horizon. The analytical framework models equipment demand by product type, technology pairing, end-user scale tier, and service attachment rate, with regional regulatory cluster as the cross-cutting dimension. CAGRs derive from least-squares fitting of normalized shipment data adjusted for local assembly incentives and import duty structures. Forecast inputs incorporate membrane replacement cycle compression and UV-ozone sequential configuration adoption curves.
Stainless steel alloy price spikes, NMPA enforcement delays, and skilled technician training pipeline gaps are the dominant revision risks to modeled equipment demand. Forecasts reflect assumptions about regulatory mandate implementation timelines and regional infrastructure investment continuity. Deviation in NMPA dual-barrier compliance deadlines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Food Disinfection Equipment Market