
 Alternative Protein Processing Equipment Market | 2026-2036
Alternative Protein Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Protein Processing Equipment Market Intelligence
China's significant investment in plant-based protein production capacity is rewriting the competitive landscape for equipment suppliers. Bühler Group leverages its expertise in extrusion technology to capture share in this expanding market. GEA Group AG differentiates through its integrated solutions for both wet and dry processing, while Tetra Pak International S.A. specializes in downstream processing for alternative dairy beverages.
Alternative protein processing equipment encompasses a range of machinery designed for transforming non-animal-derived raw materials into food ingredients. This includes systems capable of high-moisture extrusion to create fibrous textures, or homogenizers for stable plant-based milk emulsions. From a protein source perspective, plant-based inputs command the largest share, but equipment for mycoprotein and cultivated cellular sources shows rapid demand. Among equipment types, extruders are foundational, while specialized mixers and dryers are crucial for product differentiation.
Food safety and labeling regulations from the U.S. FDA and the European Food Safety Authority (EFSA) influence equipment design. Novel food approval frameworks, such as those governed by Singapore's Food Agency (SFA), set stringent requirements for process validation and hygienic design. Equipment manufacturers must therefore balance engineering for novel protein structures with compliance to an evolving, multi-jurisdictional regulatory environment.
Market Dynamics
The central force shaping the market is the rapid translation of food science into industrial-scale production. As food technology startups move from lab-bench formulations to commercial manufacturing, they create intense demand for novel processing equipment designed for specific protein structures.
Growth Catalysts
- Novel Food Frameworks:Regulatory pathways like Singapore's Food Agency (SFA) framework for novel foods create a clear, albeit stringent, route to market, incentivizing investment in equipment that meets high standards for process validation and hygienic design.
- Precision Fermentation Advances:Breakthroughs in precision fermentation enable the production of specific proteins and fats, driving demand for specialized bioreactors, downstream purification systems, and formulation equipment to handle these novel ingredients.
- Food Tech Hub Concentration:The clustering of alternative protein companies in regions like the Netherlands and the United States creates concentrated demand, allowing equipment suppliers to co-develop solutions and establish regional service expertise.
Market Restraints
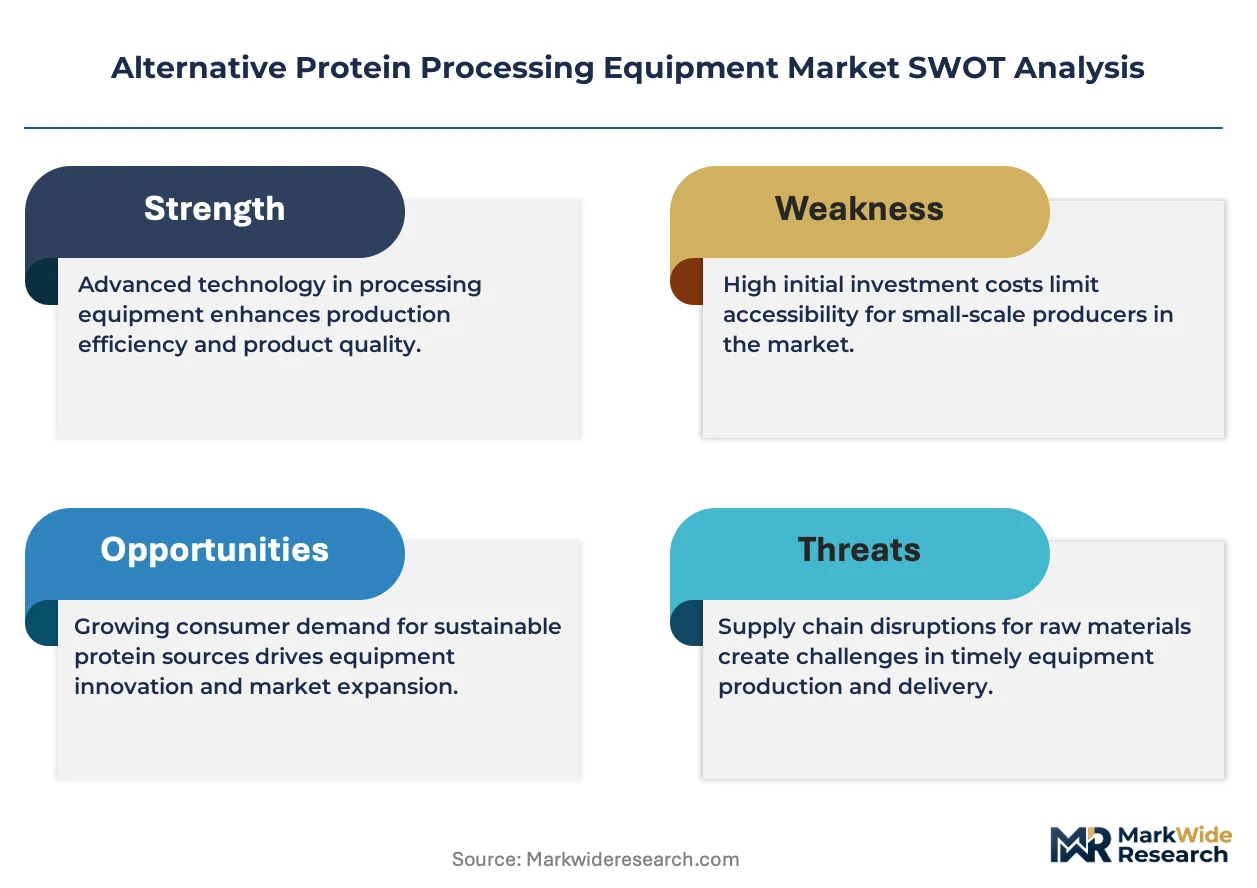
- High Capital Expenditure:The significant upfront investment required for specialized machinery, such as high-moisture extruders or industrial-scale bioreactors, presents a substantial barrier to entry and expansion for smaller food tech companies.
- Scaling-Up Bottlenecks:A primary technical restraint is the difficulty in scaling cultivated cellular product manufacturing from laboratory volumes to commercial production, which requires bioreactor designs that are not yet fully optimized or standardized.
- Regulatory Asynchronicity:Divergent timelines and data requirements between regulatory bodies like the U.S. FDA and the European Food Safety Authority (EFSA) for novel food approvals create design and compliance uncertainty for equipment manufacturers serving a global market.
Strategic Opportunities
- Equipment for Hybrid Products:A significant opportunity exists in developing integrated processing lines designed for hybrid products that combine plant-based, fermentation-derived, and cultivated ingredients to achieve superior taste and texture.
- Chinese Market Expansion:China's state-supported push for food self-sufficiency and protein diversification presents a major opportunity for equipment suppliers with expertise in building large-scale plant-based protein processing facilities.
- AI-Powered Process Optimization:Integrating artificial intelligence and machine learning sensors into processing lines offers a new frontier for providing real-time quality control, predictive maintenance, and yield optimization as a value-added service.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:A critical challenge is the shortage of engineers and technicians who possess the cross-disciplinary skills in both food science and industrial automation needed to operate and maintain advanced protein processing systems.
- Lack of Ingredient Standardization:The variable functional properties of novel inputs, such as different mycoproteins or plant protein isolates, complicate equipment design and require constant recalibration, hindering the development of true turnkey solutions.
- System Integration Complexity:Integrating new, specialized equipment for novel proteins with existing downstream packaging and legacy plant systems creates significant operational friction and can lead to unforeseen production bottlenecks for food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Protein Processing Equipment Market |
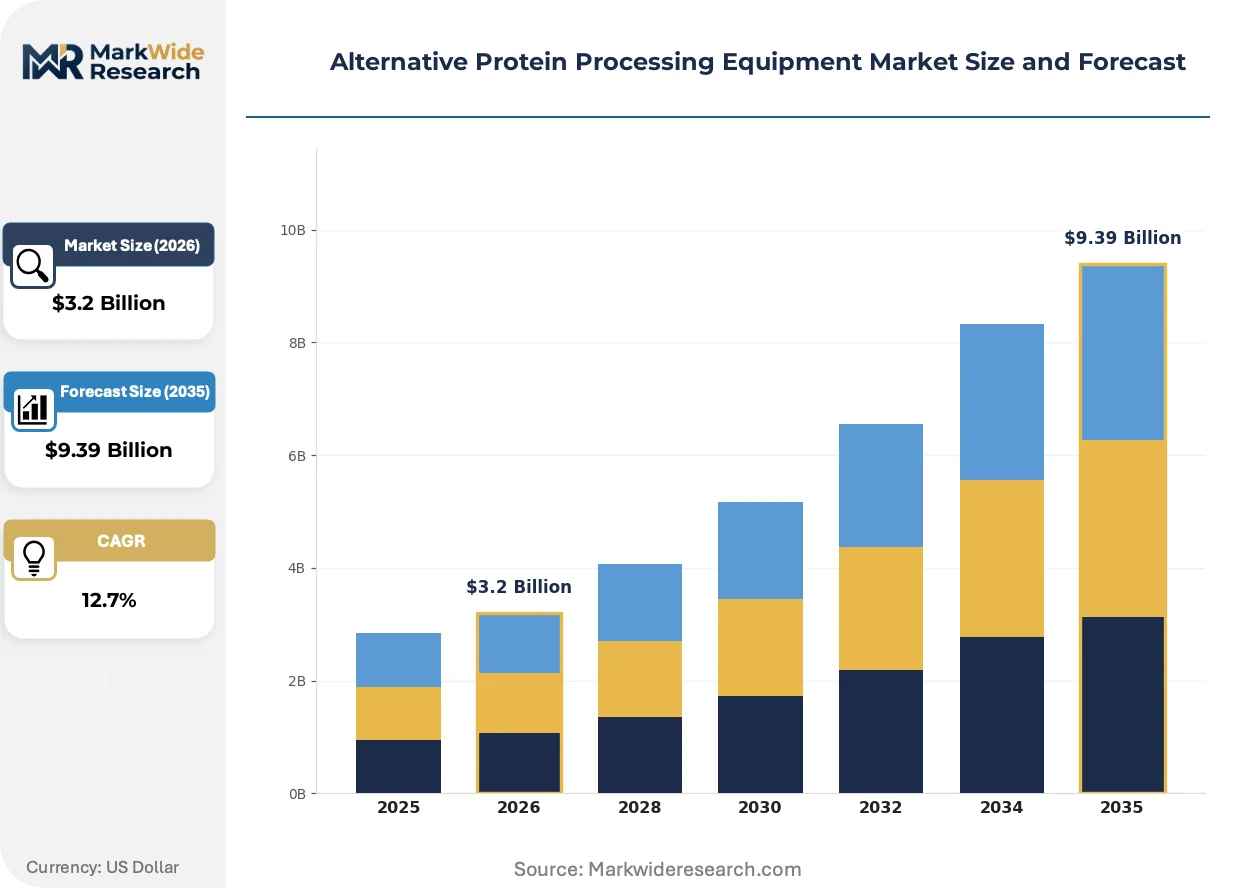
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $9.39 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Extruders, Homogenizers, Dryers, Mixers, Separators Protein Source: Plant-Based, Mycoprotein, Algae-Based, Insect-Based, Cultivated Cellular Application: Meat Alternatives, Dairy Substitutes, Protein Bars, Beverages, Snacks End User: Food Manufacturers, Ingredient Suppliers, Contract Processors, Research Institutes |
| Companies Covered | SPX Flow, Inc., Tetra Pak International S.A., Bühler Group, ANDRITZ AG, Hosokawa Micron Group, GEA Group AG, JBT Corporation, Coperion GmbH, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Protein Processing Equipment Market Strategic Shifts & Innovations
The market is defined by a pivot from adapting existing food processing machinery to engineering purpose-built systems. These new platforms are designed from the ground up to manipulate the unique rheological, biological, and textural properties of non-animal proteins.
High-moisture extrusion (HME) technology uses a twin-screw system with controlled heat and pressure to texturize plant proteins into fibrous structures that mimic muscle tissue. Food manufacturers focused on next-generation meat analogues are the primary adopters, seeking to improve product quality. The technology is collapsing the sensory gap between conventional meat and plant-based alternatives, enabling more convincing consumer products.
The European Food Safety Authority’s (EFSA) Novel Food Regulation imposes a rigorous pre-market safety assessment for ingredients without a history of consumption in the EU. This directly influences equipment design by requiring features that ensure process consistency, traceability, and hygienic operation to generate validation data. Equipment for mycoprotein and cultivated cell lines is most affected, as manufacturers must prove their process is safe and controllable.
A clear behavioral shift sees food producers moving from purchasing standalone equipment to sourcing integrated, end-to-end production lines. This trend challenges the traditional sales model of specialized component suppliers, favoring vendors who can act as system integrators and deliver a complete turnkey solution. This preference is most pronounced in new factory projects within the Netherlands and Singapore, where minimizing time-to-market is a primary competitive driver.
Alternative Protein Processing Equipment Market Segmentation
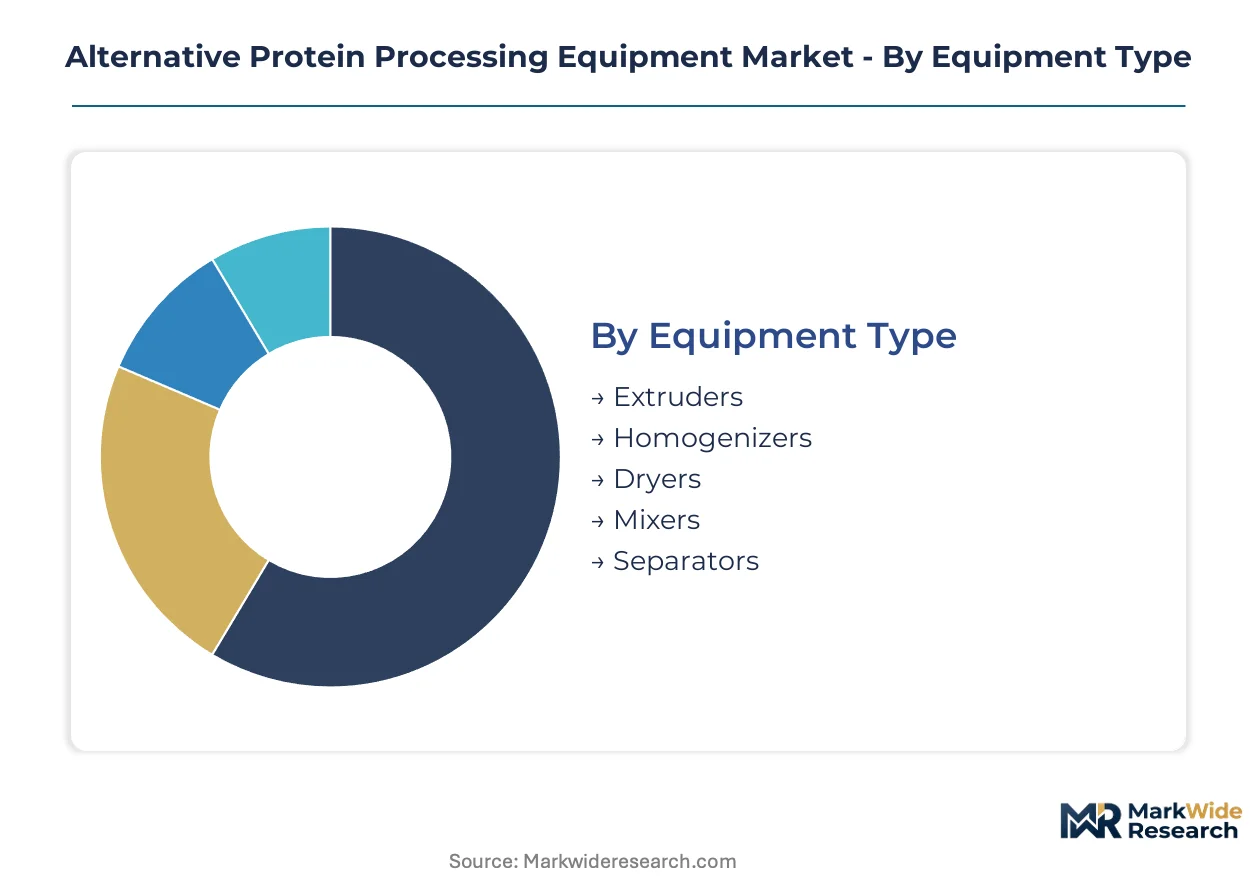
The alternative protein processing equipment market is segmented to reflect the diverse technologies, protein sources, applications, and end-users driving its expansion. This segmentation highlights the specialized machinery required to transform novel non-animal raw materials into consumer-ready food products. Understanding these distinctions is crucial for equipment manufacturers and food technologists.
Equipment Type:
The spectrum of equipment types addresses various stages of alternative protein processing, from initial ingredient preparation to final texturization and emulsion stability.
- Extruders:These systems use twin-screw technology with controlled heat and pressure to texturize plant proteins into fibrous structures, mimicking muscle tissue. Food manufacturers in the Netherlands and the United States primarily adopt extruders for next-generation meat analogues.
- Homogenizers:High-pressure homogenizers create stable plant-based milk emulsions by reducing particle size, preventing separation and improving mouthfeel. Demand for these systems is concentrated among dairy substitute producers in Singapore and European food tech hubs.
- Dryers:Industrial dryers remove moisture from protein concentrates and isolates, extending shelf life and preparing ingredients for further processing.
- Mixers:Specialized mixers ensure uniform blending of protein powders, liquids, and other ingredients, crucial for consistent product formulation.
- Separators:Centrifugal separators efficiently separate different components in liquid streams, vital for refining protein isolates from raw plant or fermentation broths.
The dominant share belongs to Extruders, while Homogenizers are exhibiting the steepest expansion trajectory.
Protein Source:
Protein source segmentation reveals the varying levels of adoption and processing complexity associated with different non-animal inputs in the food industry.
- Plant-Based:Derived from legumes, grains, or seeds, plant-based proteins command the largest market share due to established supply chains and consumer familiarity. Equipment for processing soy, pea, and wheat proteins sees widespread deployment across global food tech hubs.
- Cultivated Cellular:These proteins are grown from animal cells in bioreactors, requiring highly specialized and sterile processing equipment for cell proliferation and harvesting. Demand for cultivated cellular processing lines is emerging rapidly in Singapore and the United States.
- Mycoprotein:Produced through fungal fermentation, mycoproteins offer unique textural properties and require specific bioreactors and downstream purification systems.
- Algae-Based:Algae-derived proteins offer high nutritional value, necessitating specialized harvesting, drying, and extraction equipment.
- Insect-Based:Processing equipment for insect proteins focuses on efficient grinding, separation, and drying to produce protein flours or isolates.
This segment sees Plant-Based as a foundational input, with Cultivated Cellular poised for significant expansion.
Application:
Application segmentation illustrates how processing equipment is tailored to meet the specific functional and textural requirements of diverse alternative protein food products.
- Meat Alternatives:This application demands equipment capable of replicating the fibrous structure, chewiness, and mouthfeel of conventional meat products. High-moisture extruders and specialized texturizers are critical for creating convincing meat analogues.
- Dairy Substitutes:Processing lines for dairy substitutes focus on achieving smooth textures, stable emulsions, and appropriate viscosity for plant-based milks, yogurts, and cheeses. Homogenizers and aseptic filling systems are essential here.
- Protein Bars:Equipment for protein bar production includes precision mixers, formers, and enrobing machines to ensure consistent ingredient distribution and product shape.
- Beverages:Specialized blending, pasteurization, and filling equipment handles the unique rheological properties of protein-enriched drinks.
- Snacks:Processing machinery for alternative protein snacks often involves extrusion, drying, and flavoring systems to create appealing textures and flavors.
Demand concentration remains high for Meat Alternatives, with Dairy Substitutes demonstrating significant market pull.
End User:
The end-user segmentation highlights the distinct operational scales and technical requirements of various entities within the alternative protein value chain.
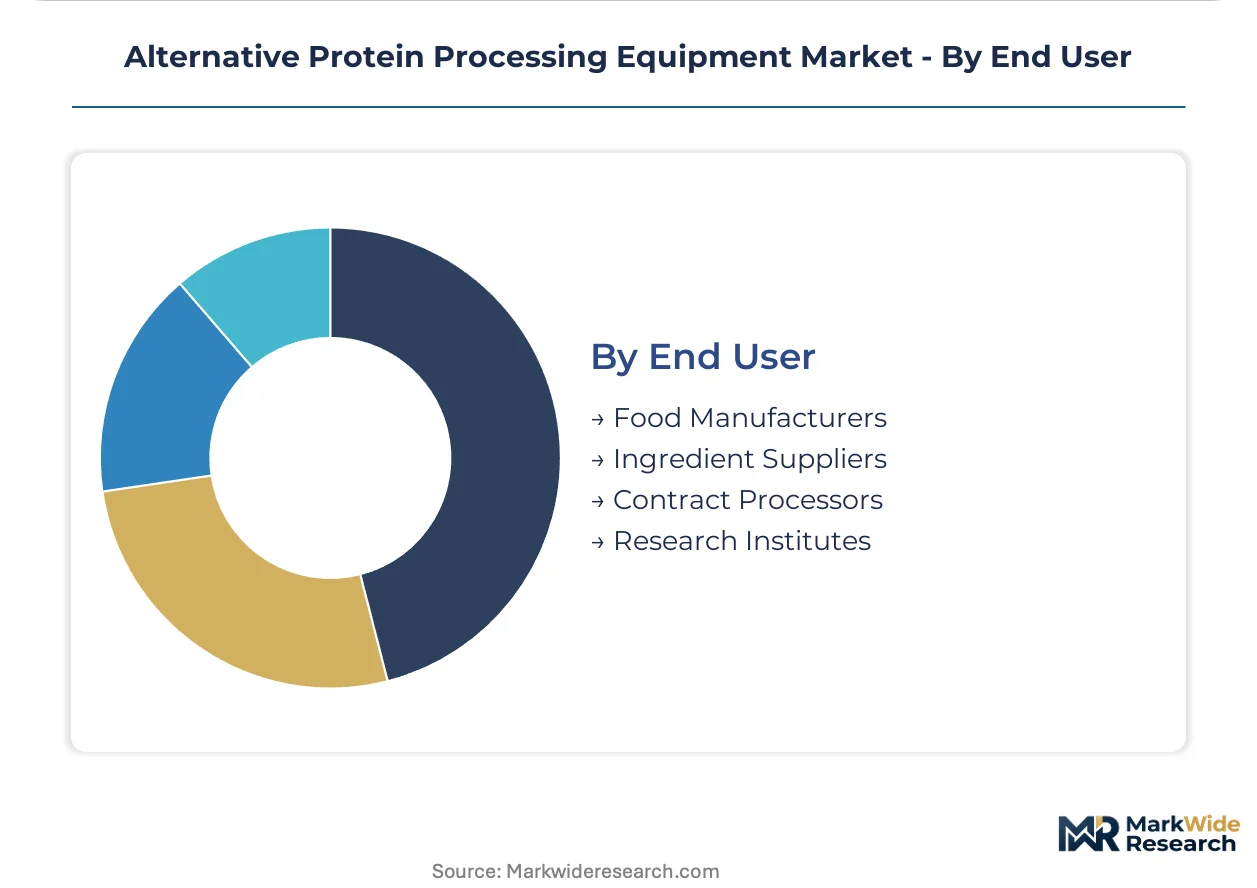
- Food Manufacturers:These entities utilize processing equipment to produce finished alternative protein products for direct consumer sales. Food manufacturers in Europe and North America represent the largest customer base for integrated processing lines.
- Ingredient Suppliers:Ingredient suppliers employ equipment to produce protein isolates, concentrates, and functional ingredients for other food companies. These suppliers require robust extraction and purification systems.
- Contract Processors:Contract processors offer specialized manufacturing services to smaller food tech startups, requiring versatile equipment capable of handling diverse formulations.
- Research Institutes:Academic and private research institutions use laboratory-scale and pilot equipment for novel protein development and process optimization.
While Food Manufacturers represent the largest customer base, Ingredient Suppliers play a critical role in upstream innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing expertise for alternative proteins concentrates in key food tech hubs globally. These regions drive innovation and scale-up for novel protein structures. The market's supply side is increasingly localized around these centers of demand.
United States
United States demand for cultivated cellular products and advanced meat alternatives remains high. The U.S. FDA's evolving regulatory pathways influence equipment design for novel food safety. California's Silicon Valley and Boston's biotech corridor host numerous food tech startups driving equipment innovation.
Netherlands
Dutch food manufacturers aggressively seek processing lines for hybrid products and dairy substitutes. The European Food Safety Authority (EFSA) Novel Food Regulation mandates stringent process validation. Wageningen Food Valley serves as a central hub for R&D and commercial scaling of alternative proteins.
Singapore
Singapore's market pulls specialized equipment for mycoprotein and cultivated cellular sources. The Singapore Food Agency (SFA) novel food approval framework accelerates market entry for compliant technologies. Its Biopolis research complex pioneers cellular agriculture and fermentation-derived protein processing.
China
China's robust investment in plant-based protein production capacity drives equipment procurement. Chinese GB standards for food safety and quality shape local machinery specifications. Major industrial zones like Shanghai and Beijing are seeing rapid expansion of large-scale processing facilities.
Germany
German food producers increasingly adopt high-moisture extrusion technology for meat analogues. European Union regulations, including EFSA guidelines, ensure hygienic design and traceability. The Rhine-Ruhr region and Bavaria house advanced engineering firms specializing in food processing machinery.
Alternative Protein Processing Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the alternative protein processing equipment market. The competitive landscape shows a tiered structure, with a few large players offering integrated solutions and numerous specialized vendors providing niche technologies. Companies pursue strategic partnerships to broaden their technology portfolios and engage in targeted capacity expansion to meet regional demand.
Specialists in integrated processing solutions, such as Bühler Group, leverage extensive extrusion expertise. GEA Group AG occupies a position emphasizing comprehensive wet and dry processing capabilities for diverse protein sources. Tetra Pak International S.A. represents a key player in downstream processing, particularly for alternative dairy beverages, offering aseptic filling and packaging lines.
| Leading Market Players |
|---|
| SPX Flow, Inc. |
| Tetra Pak International S.A. |
| Bühler Group |
| ANDRITZ AG |
| Hosokawa Micron Group |
| GEA Group AG |
| JBT Corporation |
| Coperion GmbH |
| Alfa Laval |
| Others |
Cost & Logistics Intelligence
Wageningen Food Valley's advanced R&D capacity directly influences the specialized equipment pricing in Europe, reflecting innovation costs and regional demand. This concentration of expertise shapes the pricing power of leading equipment manufacturers, balancing high capital expenditure with long-term operational value for food producers.
Pricing Analysis
The European Food Safety Authority’s (EFSA) Novel Food Regulation dictates the pricing tier structure for equipment requiring stringent process validation, such as bioreactors for mycoprotein. Hybrid pricing models combine project-based contracts for integrated processing lines with per-unit transactional pricing for specialized components. Price differentiation stems from customization levels for unique protein structures and the inclusion of comprehensive after-sales service packages. Pricing pressure stems from the high capital expenditure required for advanced machinery, particularly for smaller food tech startups. Large food manufacturers, prioritizing long-term operational efficiency, exhibit lower price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are crucial for supporting the procurement of high-value alternative protein processing equipment. Geographic supply concentration for core manufacturing components draws from Germany, the United States, and Japan, known for precision engineering. The supply chain relies on specialized alloys, industrial automation systems, and high-performance sensors. Single-source vulnerability for certain highly specialized components presents a structural supply chain risk. Distribution channels operate via direct sales models for integrated turnkey solutions and through specialized distributor networks for individual component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense against conventional animal products. Incumbents must navigate the accelerating shift towards plant-based and novel protein sources by offering compelling processing solutions.
For Market Incumbents:Harden core extrusion and homogenization technologies through continuous R&D, focusing on AI-powered process optimization for real-time quality control. Expand regional service expertise in key food tech hubs like Singapore and the Netherlands to address localized demand and regulatory nuances. Form strategic partnerships with bioprocess engineering firms to overcome talent scarcity and enhance capabilities in cultivated cellular and precision fermentation equipment. This approach mitigates threats from evolving regulatory frameworks and the variable functional properties of novel inputs.
For New Entrants and Emerging Players:Pursue niche opportunities in specialized processing equipment for hybrid products that combine multiple protein sources. Target the contract processor segment, which requires versatile machinery capable of handling diverse formulations for smaller food tech startups. Develop modular, scalable solutions for cultivated cellular product manufacturing to address existing scaling-up bottlenecks. A go-to-market angle focusing on flexible, adaptable systems that can rapidly integrate new protein structures will capture early market share.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized equipment providers with proven capabilities in novel protein structures. Long-term viability is strong, driven by global food security and sustainability trends. Identify acquisition targets among niche specialists in downstream purification systems or AI-powered process control software. A critical signal to watch is the successful commercialization of large-scale cultivated cellular production facilities, indicating readiness for broader industrial adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Captures a major growth market driven by state-supported plant-based protein production. |
| AI-Powered Process Optimization Integration | Enhances real-time quality control and predictive maintenance for complex protein processing. |
| Strategic Partnerships for Turnkey Solutions | Addresses the market's preference for integrated, end-to-end production lines. |
| Bioprocess Engineering Talent Development | Mitigates the critical scarcity of cross-disciplinary skills required for advanced systems. |
| Hybrid Product Processing Line Development | Unlocks new revenue streams by enabling superior taste and texture for complex formulations. |
Research Approach
A spread of perspectives from food manufacturers, equipment engineers, food scientists, and regulatory specialists converged on the working assumptions for this study. Primary interviews with these industry stakeholders were rigorously validated against secondary data. Secondary sources included regulatory filings from the U.S. FDA, EFSA, and Singapore Food Agency, along with company annual reports and academic journals on food science. This approach facilitated both bottom-up and top-down triangulation of market insights.
Demand-supply balance formed the core of the analytical framework across the analysis window. The model integrated segmentation dimensions including equipment type, protein source, application, end-user, and regional food tech hub concentration. Compound annual growth rates were derived from historical growth trends and projected market penetration rates of alternative proteins. Key industry-specific forecast inputs included food tech investment trends and novel food approval rates in major markets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new technology providers or established food giants would shift outcomes. The analysis reflects assumptions regarding regulatory stability and technological progression in protein processing. Rapid regulatory shifts, unforeseen technological breakthroughs in protein synthesis, or significant macroeconomic downturns could revise the forecast.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Food Ultrasound Market