
 Butcher Equipment Market | 2026-2036
Butcher Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Butcher Equipment Market Outlook
Equipment leasing and managed service contracts is reconfiguring capital deployment for mid-sized meat processors that previously deferred automation investments. Marel leverages its integrated software-hardware platforms to sustain premium positioning in fully automatic portioning systems. Bettcher Industries specializes in handheld precision cutting tools that anchor its niche in high-volume beef and pork operations. JBT Corporation competes through thermal processing know-how that extends into complementary smoking and cooking equipment lines.
Butcher equipment encompasses cutting, grinding, stuffing, sealing, and portioning machinery engineered from food-grade stainless steel with IP65 washdown ratings and blade hardness exceeding 55 HRC for sustained edge retention in continuous commercial operations. Its primary purpose is to transform carcass and primal cuts into standardized retail or foodservice portions while maintaining cold-chain integrity and minimizing yield loss. Electric equipment dominates volume sales across food processing plants where throughput requirements exceed manual capacity, while fully automatic systems capture the fastest expansion as labor scarcity intensifies in industrialized meatpacking corridors. Vacuum sealers occupy a mature margin pool in retail butcher shops where shelf-life extension drives replacement cycles rather than capacity expansion.
USDA inspection protocols and FDA Food Safety Modernization Act requirements mandate sanitary design standards that disqualify legacy cast-aluminum equipment from licensed facilities, directly shaping replacement demand. CE marking under EU Machinery Directive 2006/42/EC and compliance with EN ISO 14159 hygiene standards create parallel technical barriers for equipment accessing European supermarket supply chains. Stakeholders must monitor how carbon accounting rules from EU Green Deal and emerging state-level energy efficiency mandates in California and Germany reshape equipment specification criteria for new procurement.
Market Dynamics
Automation pressure in meatpacking corridors is compressing equipment replacement cycles as processors confront chronic labor scarcity and FDA sanitary design mandates that disqualify legacy aluminum machinery from licensed facilities.
Growth Catalysts
- EU Green Deal carbon accounting:Equipment procurement criteria in Germany and France now embed energy efficiency benchmarks that accelerate replacement of thermal processing lines with regenerative systems.
- Supermarket automated portioning:Food retail consolidation across North America and Western Europe is standardizing throughput specifications that favor integrated cutting-sealing-stuffing lines over standalone units.
- Stainless steel IP65 washdown ratings:Material science advances in blade hardness exceeding 55 HRC are extending edge retention cycles and reducing downtime in continuous commercial operations.
Market Restraints
- Nickel price volatility:Austenitic stainless steel input costs fluctuate with Indonesian ore export quotas, compressing margin buffers for mid-tier equipment fabricators.
- German precision engineering concentration:High-specification drive systems and servo motors cluster in Baden-Württemberg supplier networks, creating single-source vulnerability for global equipment assemblers.
- CE marking timeline friction:EU Machinery Directive 2006/42/EC conformity assessment delays average 14-18 months for novel portioning robotics, freezing first-mover advantage in European supermarket supply chains.
Strategic Opportunities
- Brazilian beef export modernization:Underpenetrated automation in Minas Gerais and São Paulo processing corridors creates demand for semi-automatic primal breaking systems that bridge manual and fully automatic throughput tiers.
- California energy efficiency mandates:State-level Title 24 building standards are creating regulatory tailwinds for heat-recovery smoking equipment that reduces thermal processing energy intensity by 30-40%.
- Convergence of vision-guided robotics and blockchain traceability:Integrated platforms that link portion weight consistency to carcass-origin verification command premium positioning in QSR supply contracts.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of servo-driven portioning systems requires cross-trained personnel fluent in both mechanical blade alignment and PLC diagnostics, a skill combination concentrated in aging German and Japanese workforces.
- Legacy HACCP integration complexity:Retrofitting automated lines into facilities operating under 1990s-era USDA inspection protocols demands parallel workflow construction that doubles effective capex outlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butcher Equipment Market |
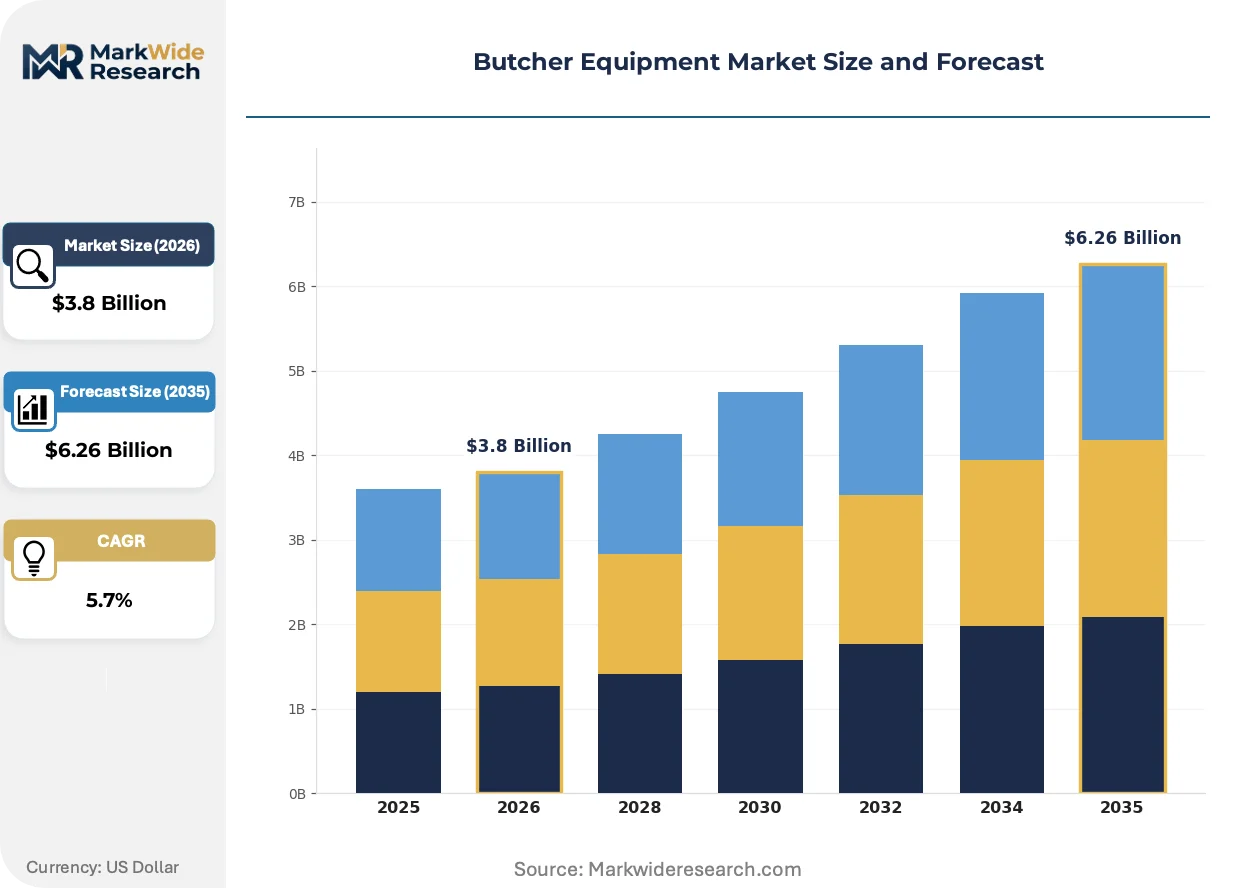
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Slicers, Sausage Stuffers, Meat Grinders, Vacuum Sealers Application: Retail Butcher Shops, Supermarkets, Food Processing Plants, Catering Services End User: Commercial Kitchens, Meat Distributors, Restaurants, Online Retailers Technology: Manual Equipment, Electric Equipment, Semi-Automatic Equipment, Fully Automatic Equipment |
| Companies Covered | Marel, JBT Corporation, GEA Group, Bizerba, The Middleby Corporation, Bettcher Industries, Sirman, Baader Group, Heat and Control, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butcher Equipment Market Strategic Shifts
Equipment architecture is converging around software-defined functionality where hardware platforms accept modular sensor and control upgrades without full line replacement, decoupling capital commitment from capability evolution.
Vision-guided robotic portioning is hybridizing optical recognition algorithms with pneumatic blade actuation to deliver sub-gram weight consistency in high-speed beef and pork breaking operations. Mid-sized processors in the US Great Plains and German Ruhr corridor are piloting these systems at 40-60 units annually. This convergence is hybridizing the competitive boundary between precision engineering specialists and industrial automation conglomerates, compressing the addressable market for standalone cutting equipment.
EU F-Gas Regulation phase-down schedules are mandating refrigerant transitions in vacuum cooling and crust-freezing subsystems that contact meat surfaces during portioning. Equipment OEMs must redesign heat exchanger architectures around CO2 or ammonia circuits, raising technical barriers for Asian fabricators seeking CE access. Cold-chain equipment lines serving Scandinavian and Benelux supermarket networks face the steepest redesign timelines due to earlier national phase-out commitments.
Equipment-as-a-service contracting is displacing outright purchase in North American mid-market processing facilities where capital rationing meets uncertain volume forecasts. Monthly per-kilogram throughput fees bundle maintenance, blade replacement, and software updates, transferring operational risk to OEM balance sheets. This model concentrates fastest in California and Texas protein processing corridors where private equity ownership prioritizes EBITDA stability over asset ownership.
Butcher Equipment Market Segmentation
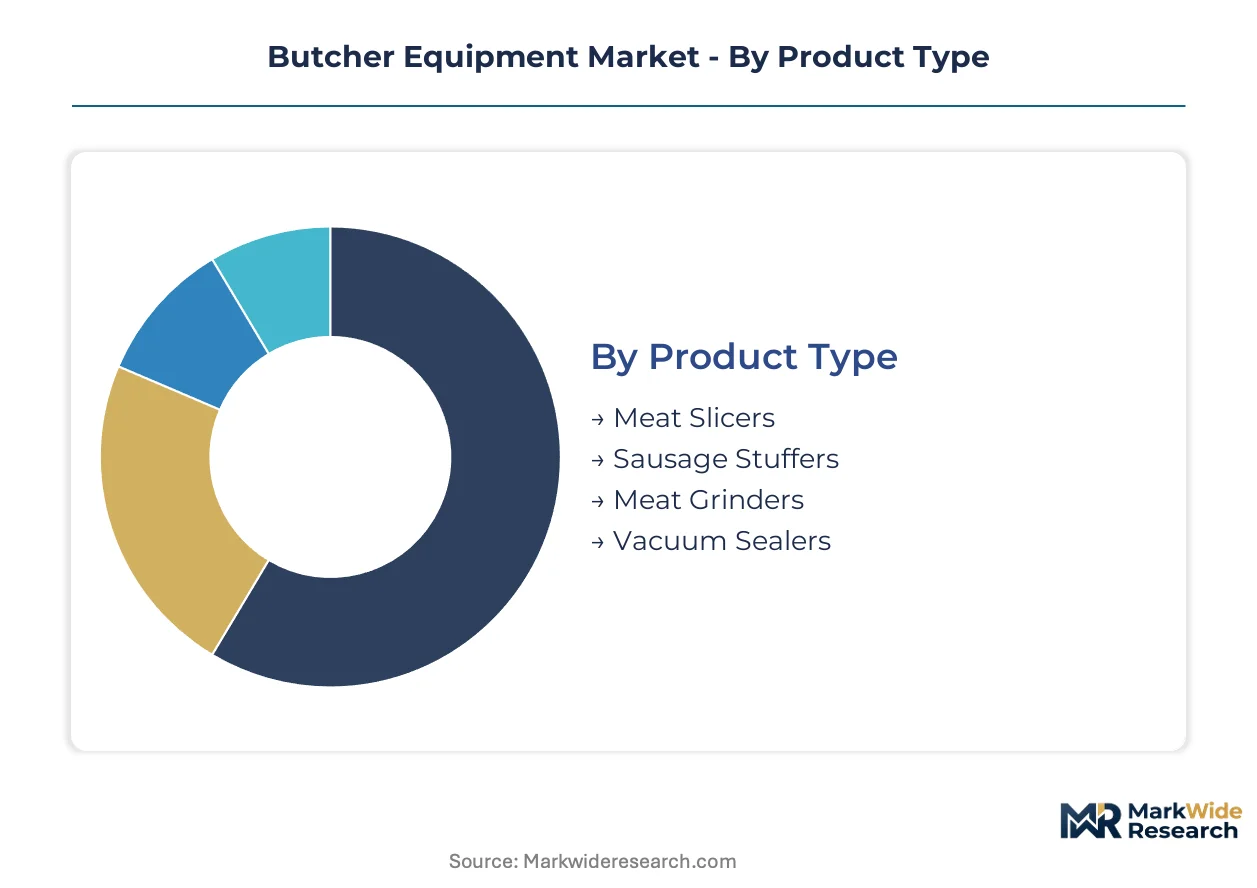
Butcher equipment segmentation reflects divergent capital intensity and labor substitution priorities across food retail and industrial processing. Equipment specification varies sharply between low-volume artisan operations and continuous-flow supermarket portioning lines.
Product Type:
Maturity spans from commoditized sealing technology to precision-engineered cutting systems with extended blade life cycles.
- Meat Slicers:Blade hardness exceeding 55 HRC delivers sustained edge retention in continuous commercial operations. Demand concentrates in German supermarket chains where portion consistency specifications exceed 0.5mm thickness tolerance.
- Sausage Stuffers:Piston-driven and vacuum-filling architectures handle emulsion density variations across pork, beef, and poultry formulations. Food processing plants in the US Great Plains are standardizing on 300+ kg/hour throughput units to match grinder line speeds.
- Meat Grinders:Auger designs with replaceable worm gears dominate mid-volume operations.
- Vacuum Sealers:Chamber-style units with 90-second cycle times anchor retail butcher shop replacement demand.
Meat slicers handle the majority of throughput; fully automatic stuffing systems are expanding most quickly on share.
Application:
Customer scale determines automation tier, with capital deployment ranging from single-unit purchases to integrated line investments.
- Supermarkets:Automated portioning-sealing-stuffing lines reduce labor costs while enforcing gram-scale weight consistency across beef, pork, and poultry SKUs. German food retail networks are specifying IP65 washdown ratings as mandatory procurement criteria.
- Food Processing Plants:Continuous-operation grinders and slicers with servo-driven blade positioning serve 10,000+ kg daily throughput requirements. Facilities in Minas Gerais and São Paulo processing corridors are bridging manual and automatic tiers with semi-automatic primal breaking systems.
- Retail Butcher Shops:Compact slicers and manual stuffers dominate equipment floorspace.
- Catering Services:Portability and rapid sanitation cycles drive specification priorities.
Food processing plants absorb the heaviest equipment volume; supermarket automation lines are gaining share fastest.
End User:
Procurement authority sits with distinct decision-makers across distributor networks and direct-operated kitchens.
- Meat Distributors:Breaking and portioning equipment with integrated weighing and labeling serves 50+ outlet delivery networks. Operations in the Texas protein corridor are piloting vision-guided robotic systems for sub-gram consistency.
- Commercial Kitchens:Compact slicers and grinders with NSF certification dominate hospital, hotel, and institutional procurement. California Title 24 energy efficiency mandates are reshaping thermal processing equipment specifications.
- Restaurants:Tabletop slicers with blade guards address liability and sanitation requirements.
- Online Retailers:Vacuum sealing throughput scales with fulfillment center meat subscription volumes.
Meat distributors deploy the largest equipment footprints; commercial kitchen energy-compliant thermal systems are climbing fastest.
Technology:
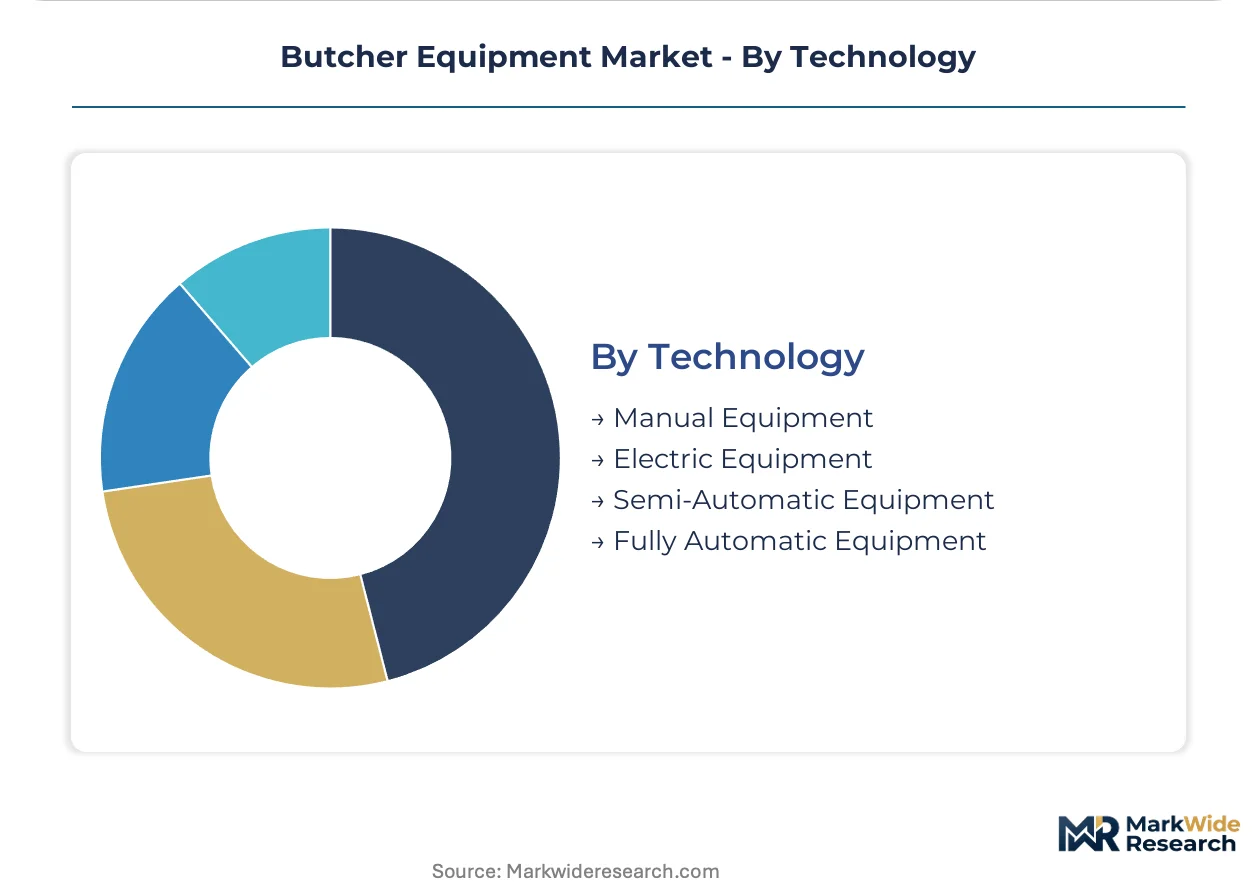
Automation intensity correlates with labor scarcity pressure and regulatory compliance burdens in licensed facilities.
- Fully Automatic Equipment:Vision-guided robotics with pneumatic blade actuation deliver sub-gram weight consistency in high-speed beef and pork breaking. FDA Food Safety Modernization Act sanitary design mandates are disqualifying legacy aluminum machinery and accelerating replacement cycles.
- Electric Equipment:Motor-driven grinders and slicers with thermal overload protection dominate volume sales where throughput exceeds manual capacity. German precision engineering clusters in Baden-Württemberg supply servo motors and drive systems for premium positioning.
- Semi-Automatic Equipment:Operator-fed portioning with automated blade cycling bridges labor availability gaps.
- Manual Equipment:Handheld precision cutting tools retain niche positioning in high-volume beef and pork operations requiring tactile feedback.
Electric equipment moves the largest unit volumes; fully automatic systems are the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon accounting requirements are reshaping procurement criteria across food retail networks, while FDA sanitary design mandates accelerate equipment replacement cycles in licensed facilities. National regulations and industrial clustering patterns create divergent demand profiles across major processing corridors.
United States
California Title 24 energy efficiency mandates and Texas protein processing corridor expansion drive demand for heat-recovery thermal systems. FDA Food Safety Modernization Act requirements disqualify legacy aluminum machinery from USDA-inspected facilities. The Great Plains region pilots vision-guided robotic portioning systems at mid-sized processors bridging manual and automatic tiers.
Germany
Baden-Württemberg precision engineering clusters supply servo motors and drive systems for premium equipment positioning. EU Machinery Directive 2006/42/EC conformity assessments and EN ISO 14159 hygiene standards create technical barriers for market access. Dense food retail networks in the Ruhr corridor specify IP65 washdown ratings as mandatory procurement criteria for automated portioning lines.
Brazil
Minas Gerais and São Paulo processing corridors seek semi-automatic primal breaking systems that bridge manual and fully automatic throughput tiers. ANVISA sanitary regulations align with Mercosur technical standards for equipment certification. Export modernization programs target underpenetrated automation in beef processing facilities serving international supermarket supply chains.
China
Dual carbon goals and GB standards for food machinery energy efficiency reshape equipment specification criteria in coastal processing zones. SAMR market surveillance protocols enforce stainless steel material compliance in licensed facilities. Yangtze River Delta protein processing clusters prioritize electric grinders and slicers with thermal overload protection for volume operations.
Japan
METI industrial efficiency programs and JIS hygiene standards for food processing equipment drive replacement demand in aging facilities. Aging workforce demographics intensify automation pressure in meatpacking corridors. Kanto region supermarket networks specify sub-gram weight consistency in high-speed beef and pork breaking operations.
Butcher Equipment Market Competitive Environment
On the supply side, the industry is consolidating around integrated software-hardware platforms that bundle portioning, sealing, and traceability functions. Equipment fabricators cluster into three strategic archetypes: precision engineering specialists, industrial automation conglomerates, and regional stainless steel fabricators. Dominant competitive moves include equipment-as-a-service contracting that transfers operational risk to OEM balance sheets, and geographic expansion into underpenetrated Brazilian and Southeast Asian processing corridors.
Among precision-engineering specialists, Marel and Bettcher Industries exemplify divergent positioning strategies within the premium tier. Marel anchors integrated system architecture spanning vision-guided robotics through blockchain traceability platforms. Bettcher Industries occupies handheld precision cutting tool specialization for high-volume beef and pork operations requiring tactile feedback. JBT Corporation represents thermal processing know-how extension into complementary smoking and cooking equipment lines.
| Leading Market Players |
|---|
| Marel |
| JBT Corporation |
| GEA Group |
| Bizerba |
| The Middleby Corporation |
| Bettcher Industries |
| Sirman |
| Baader Group |
| Heat and Control |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese stainless steel fabrication is compressing margin buffers for mid-tier equipment assemblers while simultaneously enabling aggressive pricing postures among premium German and Japanese OEMs seeking to defend positioning.
Pricing Analysis
Certification level creates the primary spread between FDA-grade stainless steel systems and standard CE-marked alternatives, with IP65 washdown ratings commanding substantial premia over IP54 configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies according to blade hardness specifications and servo motor sourcing from Baden-Württemberg clusters. Cost compression in economy-tier electric grinders is intensifying because Indonesian nickel export quotas have destabilized austenitic steel input costs. Food processing plants in high-throughput corridors exhibit the lowest price sensitivity, while independent retail butcher shops defer replacement cycles during margin stress.
Supply Chain Analysis
Export control regimes limiting servo motor and precision drive technology flows from Germany and Japan are constraining equipment upgrade pathways for Brazilian and Southeast Asian fabricators seeking CE access. Component sourcing centers on Baden-Württemberg for drive systems, Yangtze River Delta for electric motor assemblies, and Italian Emilia-Romagna for vacuum pump subsystems. Single-source vulnerability concentrates in high-specification drive networks, with tariff exposure mounting on steel inputs subject to Indonesian ore policy shifts. Distribution runs through regional equipment distributors serving supermarket procurement committees and direct OEM relationships with multinational protein processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are compressing as cyclical recovery in protein processing capital expenditure follows post-pandemic labor scarcity normalization and regulatory mandate deadlines.
For Market Incumbents:Entrench positioning through backward integration into blade hardening facilities and captive supply of servo drive components from Baden-Württemberg supplier networks. Threat from Asian fabricators with cost-advantaged stainless steel sourcing demands accelerated certification investment to maintain FDA and EU Machinery Directive compliance moats. Channel control through equipment-as-a-service contracting transfers operational risk and locks in multi-year revenue visibility.
For New Entrants and Emerging Players:Build out semi-automatic primal breaking systems targeting Minas Gerais and São Paulo processing corridors where automation penetration remains below North American benchmarks. White-space concentrates in mid-tier throughput equipment bridging manual and fully automatic tiers for Brazilian beef export modernization. Go-to-market leverage through ANVISA certification partnerships with established regional distributors accelerates market access without direct regulatory navigation.
For Investors and Strategic Acquirers:Long-term, this sits as a consolidation play because equipment-as-a-service contracting concentrates recurring revenue with OEMs possessing integrated software-hardware platforms and balance sheet capacity to absorb operational risk. Acquisition targets with vision-guided robotics capabilities and blockchain traceability integration command positioning premia in QSR supply contracts. Signal to watch is California Title 24 thermal processing equipment mandate adoption rates as proxy for regulatory-driven replacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Transfers operational risk to OEM balance sheets while securing multi-year revenue visibility from protein processors. |
| Vision-Guided Robotics Integration | Enables sub-gram portion consistency specifications demanded by German supermarket supply chains. |
| CE Marking Acceleration | Reduces 14-18 month conformity assessment delays that freeze first-mover advantage in European retail networks. |
| Heat-Recovery Thermal Systems | Addresses EU Green Deal carbon accounting and California Title 24 energy efficiency procurement criteria. |
| Blade Hardening Facility Acquisition | Secures captive supply of 55+ HRC cutting components against nickel price volatility and import quota risk. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at protein processing facilities, procurement directors at supermarket chains, maintenance heads at foodservice distributors, and aftermarket service managers at OEM networks. Secondary validation drew from FDA Food Safety Modernization Act filings, EU Machinery Directive conformity assessment databases, SEC 10-K equipment segment disclosures, and customs trade data on stainless steel machinery imports. Bottom-up equipment unit deployment estimates triangulated against top-down protein processing capacity expansion projections across the analysis window.
Calibration against historical replacement cycle patterns and regulatory mandate implementation timelines anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include automation tier, application scale, end-user procurement authority, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories correlated with protein processing employment data and energy efficiency compliance deadlines. Industry-specific inputs encompassed blade hardness specification adoption curves and servo motor supply lead times from German precision engineering clusters.
Practitioners should monitor Indonesian nickel export policy shifts, EU F-Gas refrigerant phase-down schedules, and FDA sanitary design enforcement intensity for early signals requiring forecast revision. Cross-checking against protein processing capital expenditure surveys and supermarket automation investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Pizza Scissors Market