
 Commercial Beverage Blender Market | 2026-2036
Commercial Beverage Blender Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Beverage Blender Market Analysis
Commercial kitchen technician shortages across North America and Western Europe is reorganizing how manufacturers design serviceability and remote diagnostics into blending equipment. Vita-Mix Corporation leverages its Cleveland-based production footprint to sustain domestic parts availability and faster turnaround on commercial warranties. Electrolux Professional AB anchors its European installed base through factory-authorized service networks spanning Stockholm to Milan. Blendtec Inc. differentiates via in-house motor production and proprietary blunt-blade engineering that reduces sharpening maintenance cycles.
A commercial beverage blender is a motorized food preparation appliance engineered to liquefy, emulsify, or puree drink ingredients at speeds typically exceeding 20,000 RPM, with stainless steel or BPA-free pitcher assemblies rated for continuous-duty cycles in professional kitchens. Its primary commercial purpose centers on producing consistent texture and volume at speed for high-margin beverage categories including smoothies, frozen cocktails, and freshly pressed juices. Countertop blenders occupy the dominant revenue position due to versatility across smoothie shops and full-service restaurants, while smart blending technology with programmable recipes and IoT-enabled usage tracking represents the fastest-expanding segment as operators seek labor substitution and portion control. Immersion blenders serve a mature niche in catering and back-of-house sauce preparation where space constraints override throughput requirements.
The FDA Food Code and NSF International sanitation standards govern equipment design and cleanability requirements across the United States foodservice sector, while the EU Machinery Directive and CE marking framework dictate electrical safety and electromagnetic compatibility for products sold across European member states. China's SAMR enforces GB standards for appliance safety and energy efficiency that foreign manufacturers must satisfy for market access. Stakeholders should monitor how evolving energy-efficiency mandates and right-to-repair legislation across multiple jurisdictions reshape total cost-of-ownership calculations and aftermarket service strategies.
Market Dynamics
Specialty coffee chains and bubble tea operators are compressing blending cycles from minutes to seconds, forcing equipment redesign around thermal management and programmable consistency protocols.
Growth Catalysts
- NSF International sanitation standards:The FDA Food Code's updated equipment cleanability mandates are accelerating replacement cycles in US foodservice operations as operators seek certified models to pass health inspections.
- IoT-enabled recipe programming:Smart blending systems with usage tracking and portion control are penetrating high-volume smoothie chains seeking labor substitution.
- Shanghai and Beijing bubble tea proliferation:China's tier-one cities are driving demand for high-throughput units capable of processing tapioca pearls and frozen fruit simultaneously.
Market Restraints
- Copper and rare-earth magnet volatility:Motor core materials face price swings that compress manufacturer margins on mid-tier product lines.
- Guangdong Province component concentration:PCB and power electronics sourcing clusters in southern China create single-point vulnerability for global supply continuity.
- Blade fatigue and pitcher degradation:Continuous-duty cycles in commercial environments accelerate wear-part replacement costs that operators underestimate.
Strategic Opportunities
- India's organized foodservice expansion:FSSAI certification requirements and quick-service restaurant growth in Mumbai and Bangalore create first-mover advantage for compliant equipment entrants.
- Cloud-connected predictive maintenance:Convergence of vibration sensors and SaaS diagnostics platforms enables subscription revenue streams from installed base monetization.
- German energy-efficiency mandates:The EU Ecodesign Directive's tightening motor efficiency standards favor brushless DC motor platforms over legacy AC induction designs.
Industry Challenges
- Commercial kitchen technician scarcity:North American and Western European service workforce gaps extend mean-time-to-repair and strain manufacturer warranty obligations.
- Multi-jurisdiction certification complexity:Simultaneous FDA, NSF, CE marking, and GB standard compliance extends product development timelines and testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Beverage Blender Market |
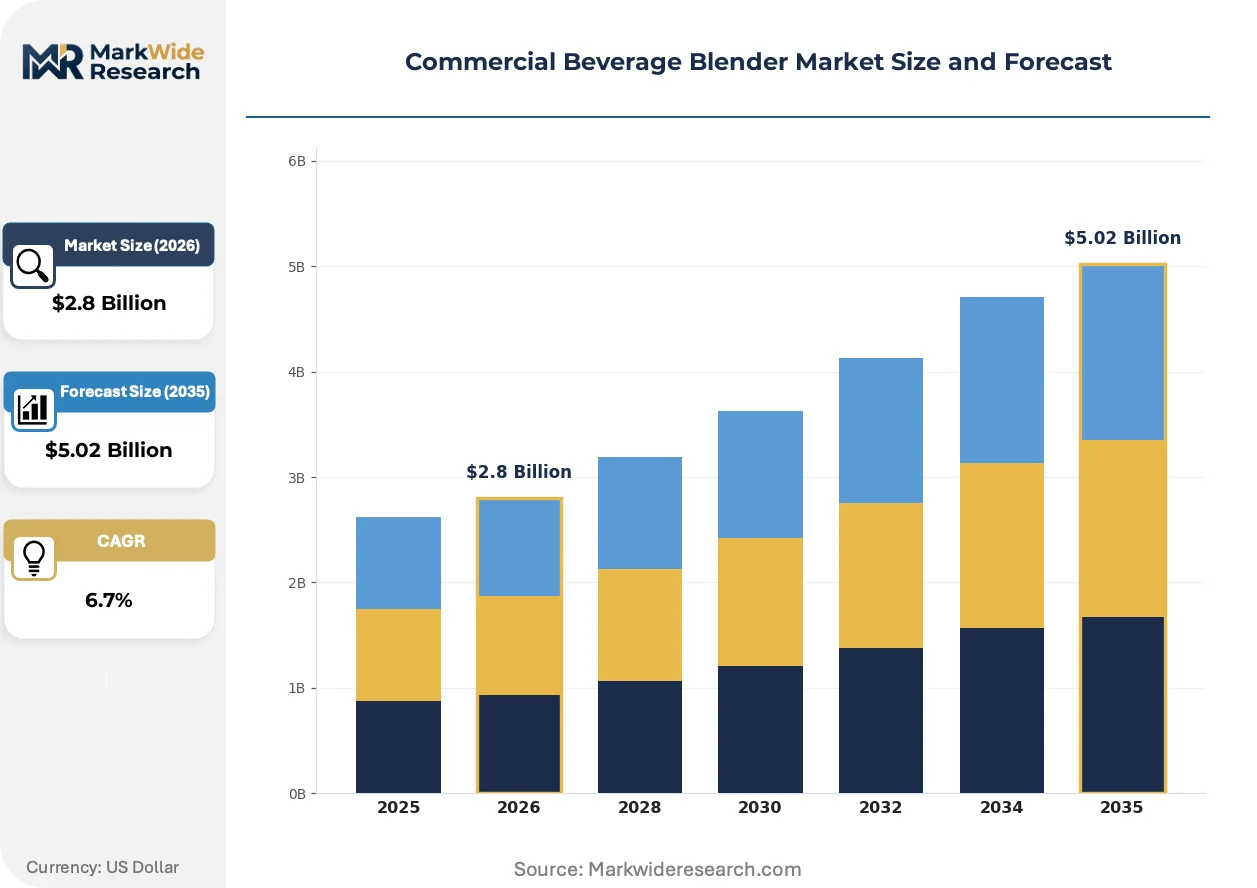
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Blenders, Immersion Blenders, Commercial Juicers, Smoothie Makers Application: Restaurants, Cafés, Bars, Smoothie Shops End User: Food Service Providers, Hospitality Industry, Catering Services, Retail Outlets Technology: High-Speed Blending, Smart Blending, Multi-Function Blenders, Eco-Friendly Models |
| Companies Covered | Breville Group Limited, Electrolux Professional AB, Vita-Mix Corporation, Koninklijke Philips NV, ROBOT COUPE SNC., Blendtec Inc., Waring Commercial, Smeg S.p.a., Hamilton Beach Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Beverage Blender Market Emerging Trajectories
Equipment intelligence and sanitation automation are redefining competitive differentiation as operators prioritize uptime guarantees over upfront capital expenditure.
Brushless DC motor platforms with integrated variable frequency drives are replacing traditional AC induction systems in premium commercial units. High-volume smoothie chains in California and Texas are specifying these systems for 30% energy reduction and reduced heat generation during back-to-back blending cycles. The technology is bifurcating the market between efficiency-focused premium tiers and cost-driven standard equipment.
The EU Machinery Directive's updated electromagnetic compatibility requirements are forcing redesign of control electronics for European market access. Manufacturers serving Stockholm and Milan must now demonstrate immunity to industrial kitchen interference patterns. This regulatory pressure is compressing product lifecycles as older platforms face technical obsolescence.
After-sales service unbundling is spreading as operators reject bundled warranty premiums in favor of pay-per-incident technician dispatch. Full-service restaurants in New York and Chicago are driving this shift through direct negotiation with factory-authorized networks. The model is most visible in independent smoothie shops lacking corporate service contracts.
Commercial Beverage Blender Market Segmentation
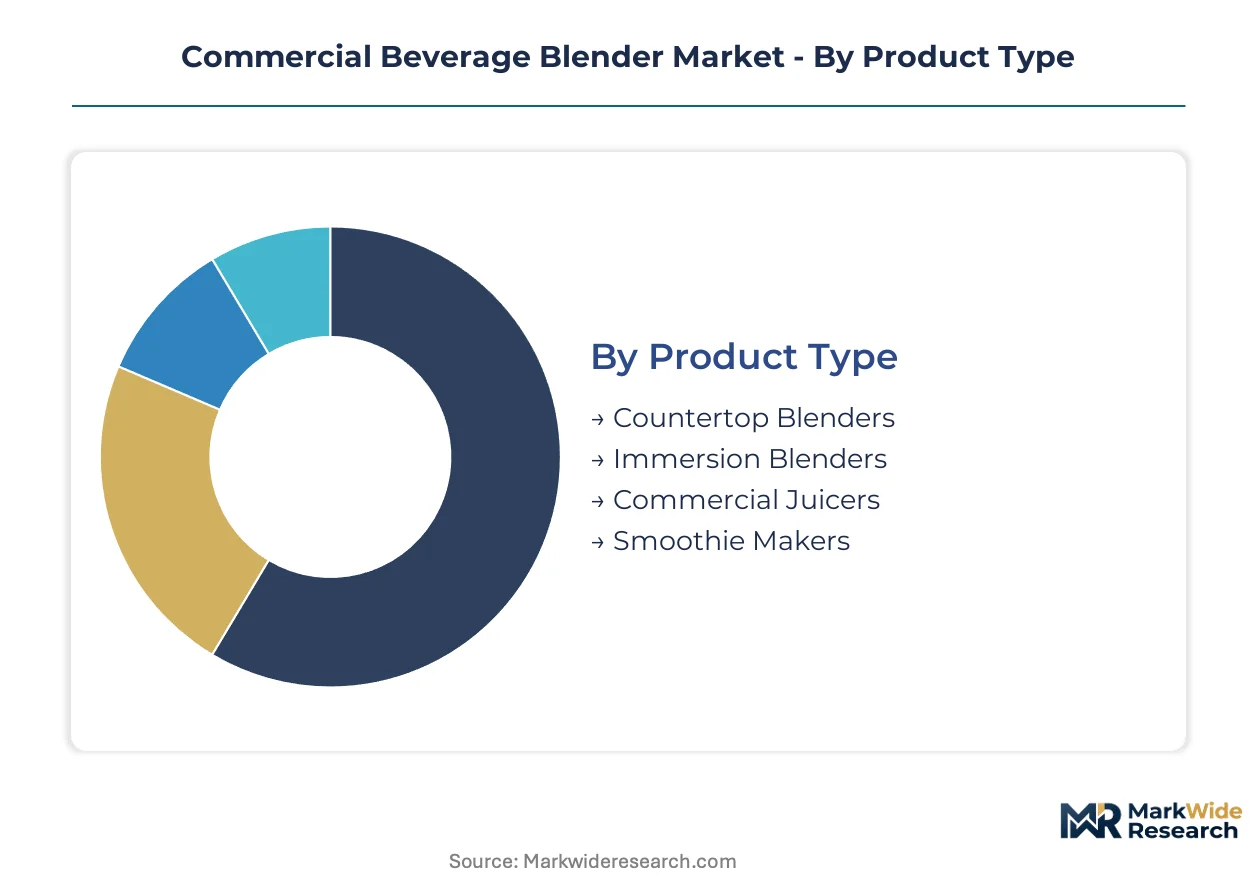
Equipment specification varies sharply across commercial beverage blender deployments. Product configuration, end-use intensity, and technology integration determine procurement patterns and lifecycle economics for operators.
Product Type:
Countertop blenders dominate domestic manufacturing footprints in the United States and Germany, while immersion blender assembly concentrates in export-oriented facilities across Guangdong Province.
- Countertop Blenders:Stationary base units with pitcher assemblies rated for 20,000+ RPM continuous operation. Demand concentrates in California and Texas smoothie chains seeking programmable consistency protocols for labor substitution.
- Immersion Blenders:Handheld shaft-mounted motors for direct-container processing. Back-of-house adoption in Paris and Milan catering operations prioritizes space efficiency over throughput.
- Commercial Juicers:Dedicated extraction systems for citrus and cold-press applications. Juice bars in São Paulo specify these for single-purpose volume.
- Smoothie Makers:Integrated frozen fruit and liquid processing platforms. Bubble tea operators in Shanghai and Beijing drive specification for tapioca pearl compatibility.
Countertop blenders command the established base. The steepest expansion runs through smart-enabled smoothie maker configurations.
Application:
Volume throughput requirements separate high-cycle smoothie shop specifications from intermittent-use bar installations, with cost tiers reflecting duty cycle intensity.
- Restaurants:Full-service kitchens require versatile units handling sauces, soups, and beverages. Chains in New York and Chicago prioritize NSF-certified cleanability for health inspection compliance.
- Cafés:Specialty coffee operators in Stockholm and Milan specify compact footprints for front-counter visibility. Brushless DC motor platforms reduce heat generation during compressed service windows.
- Bars:Frozen cocktail production demands rapid ice pulverization. Miami and Las Vegas venues specify sound-dampening enclosures for customer environment management.
- Smoothie Shops:Dedicated high-throughput concepts in California and Texas specify IoT-enabled recipe programming for portion control and labor reduction.
Smoothie shops lead technology adoption velocity. Restaurant procurement represents the largest installed base by unit count.
End User:
Corporate contract structures differentiate food service provider purchasing from independent retail outlet procurement, with warranty terms and service networks driving selection criteria.
- Food Service Providers:Contract management companies operating institutional cafeterias and corporate dining. Procurement in the United States emphasizes FDA Food Code compliance and factory-authorized service coverage.
- Hospitality Industry:Hotel and resort operations requiring 24-hour durability ratings. Dubai and Singapore properties specify premium tiers for guest-facing beverage programs.
- Catering Services:Mobile and event-based operators prioritizing transport durability. European caterers face EU Machinery Directive electromagnetic compatibility requirements for generator-powered setups.
- Retail Outlets:Supermarket juice bars and convenience store installations. India's organized retail expansion in Mumbai and Bangalore creates specification demand for FSSAI-certified equipment.
Food service providers concentrate volume purchasing power. Retail outlets are gaining share fastest as grocery channels expand fresh beverage offerings.
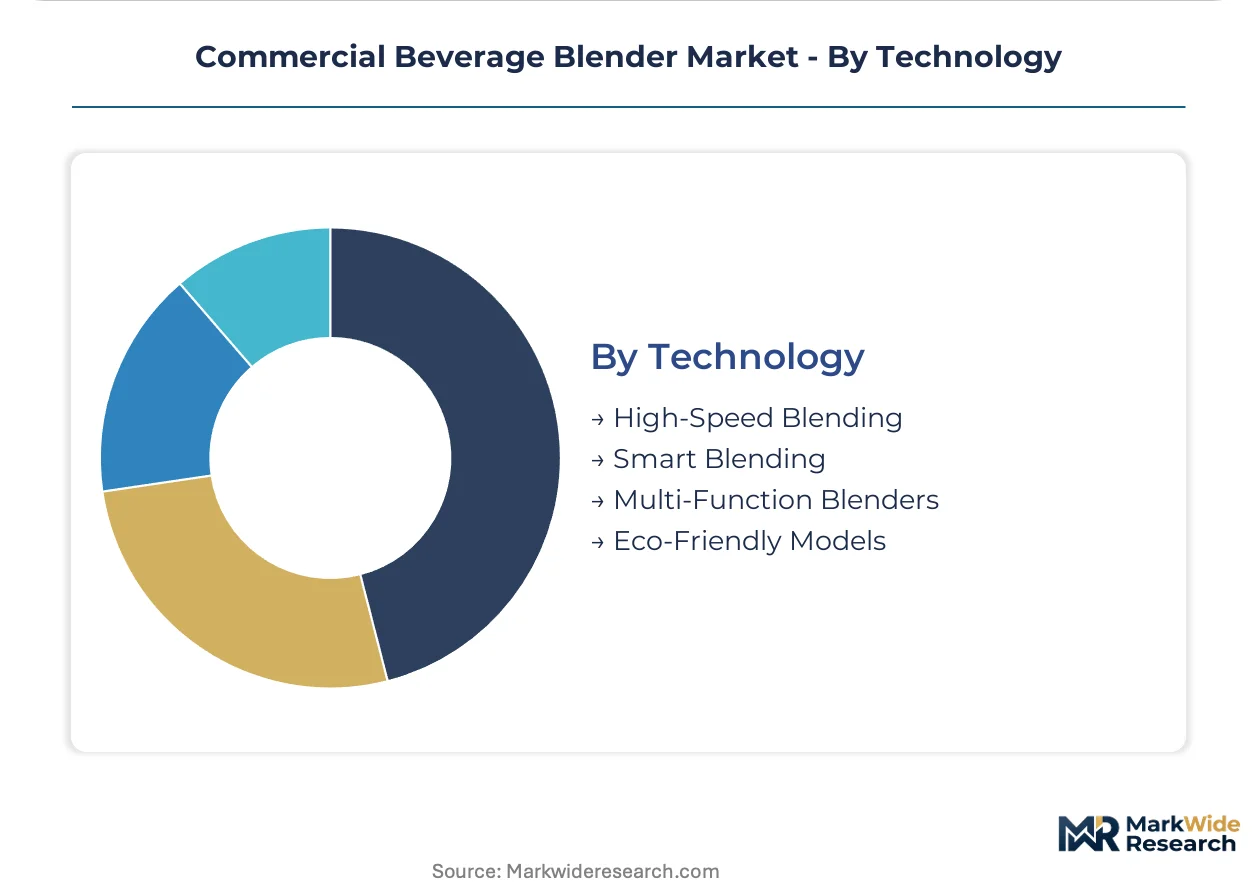
Technology:
Motor architecture and control intelligence separate premium efficiency tiers from standard equipment, with regulatory pressure accelerating platform transitions.
- High-Speed Blending:Conventional AC induction motor systems exceeding 20,000 RPM. Legacy installed base in North America faces replacement pressure from energy-efficiency mandates.
- Smart Blending:IoT-enabled platforms with programmable recipes, usage tracking, and cloud diagnostics. California smoothie chains specify these for labor substitution and predictive maintenance integration.
- Multi-Function Blenders:Modular attachments for processing diversity across hot and cold applications. German commercial kitchens favor these under tightening EU Ecodesign Directive efficiency standards.
- Eco-Friendly Models:Reduced energy consumption and recyclable component designs. Stockholm and Milan operators specify these for sustainability reporting alignment.
High-speed blending retains the largest installed base. Smart blending platforms are climbing the fastest as operators prioritize uptime guarantees over upfront capital expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Food Code updates on equipment sanitation standards are reshaping procurement criteria for foodservice operators across the United States. Specialty coffee chains are scaling high-throughput blending operations. Demand is concentrating in China's tier-one cities where bubble tea and fresh juice concepts are proliferating.
United States
Specialty coffee chains in California and Texas are compressing blending cycles from minutes to seconds. The FDA's Food Code mandates NSF-certified cleanability for health inspection compliance. Cleveland-based production footprints sustain domestic parts availability and faster turnaround on commercial warranties.
China
Bubble tea and fresh juice concepts in Shanghai and Beijing are driving demand for high-throughput units capable of processing tapioca pearls and frozen fruit simultaneously. SAMR enforces GB standards for appliance safety and energy efficiency that foreign manufacturers must satisfy for market access. Guangdong Province PCB and power electronics sourcing clusters create single-point vulnerability for global supply continuity.
Germany
Commercial kitchens favor modular multi-function blenders under tightening EU Ecodesign Directive efficiency standards. The EU Machinery Directive and CE marking framework dictate electrical safety and electromagnetic compatibility for products sold across European member states. Factory-authorized service networks spanning Stockholm to Milan anchor the European installed base.
India
Quick-service restaurant growth in Mumbai and Bangalore creates first-mover advantage for compliant equipment entrants. FSSAI certification requirements govern equipment design and cleanability requirements across the organized foodservice sector. Organized retail expansion in metropolitan areas creates specification demand for certified equipment in supermarket juice bars.
Sweden
Stockholm and Milan operators specify eco-friendly models for sustainability reporting alignment. The EU Green Deal's tightening motor efficiency standards favor brushless DC motor platforms over legacy AC induction designs. Compact footprint specifications for front-counter visibility drive café procurement patterns.
Commercial Beverage Blender Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the commercial beverage blender market. The structure separates premium efficiency-focused manufacturers from cost-driven standard equipment producers. Three archetypes dominate: vertically integrated motor producers, factory-authorized service network operators, and smart-enabled IoT platform developers. Competitive moves center on backward integration into motor core production and geographic expansion through factory-authorized service networks.
Within the integrated leader tier, Vita-Mix Corporation and Electrolux Professional AB exemplify contrasting geographic anchoring strategies. Blendtec Inc. occupies a position emphasizing in-house production capabilities. Hamilton Beach Brands Inc. represents the scale-driven mass-market archetype. These named entities illustrate how competitive positioning separates premium-tier efficiency specialists from volume-oriented standard equipment suppliers.
| Leading Market Players |
|---|
| Breville Group Limited |
| Electrolux Professional AB |
| Vita-Mix Corporation |
| Koninklijke Philips NV |
| ROBOT COUPE SNC. |
| Blendtec Inc. |
| Waring Commercial |
| Smeg S.p.a. |
| Hamilton Beach Brands Inc. |
| Others |
Supply Flow & Price Mechanics
NSF International sanitation certification gates both supplier qualification and price differentiation simultaneously, separating certified premium tiers from uncertified economy alternatives while compressing margins on mid-tier lines that lack either cost leadership or compliance differentiation.
Pricing Analysis
California smoothie chains pay 40-60% premiums over Texas independent operators for identical base hardware, reflecting bundled IoT diagnostics and factory-authorized service coverage. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor architecture efficiency and after-sales warranty terms. Cost compression in mid-tier AC induction platforms is intensifying because brushless DC migration shifts R&D investment toward premium tiers. Independent bubble tea shops in Guangdong Province exhibit highest price sensitivity, while Dubai hospitality properties demonstrate lowest sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Inventory lead times for brushless DC motor cores have extended from standard procurement cycles as rare-earth magnet sourcing concentrates in Chinese processing facilities. Guangdong Province, Germany, and the United States anchor final assembly, with motor laminations drawing from Japanese steel mills and power electronics resting on South Korean semiconductor foundries. Single-source vulnerability concentrates in Guangdong PCB clusters where tariff exposure threatens component cost stability. Distribution runs through factory-authorized service networks for premium tiers and third-party foodservice distributors for standard equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected predictive maintenance subscriptions are expanding faster than hardware unit sales, transforming commercial beverage blender economics from capital expenditure toward recurring service revenue models.
For Market Incumbents: Fortify factory-authorized service network density in tier-one Chinese cities before local competitors replicate Vita-Mix's Cleveland-based parts availability model. Deepen backward integration into motor core production to offset copper and rare-earth magnet volatility compressing mid-tier margins. Electrolux Professional AB's Stockholm-to-Milan coverage demonstrates how geographic service anchoring defends installed base against emerging IoT-enabled challengers. For New Entrants and Emerging Players: FSSAI certification fast-track for Mumbai and Bangalore quick-service restaurant procurement creates first-mover positioning ahead of organized retail expansion. Target India's supermarket juice bar segment where specification demand outpaces compliant supply. Cloud-native SaaS diagnostics platforms offer lower customer acquisition cost than hardware-first entry against entrenched service networks. For Investors and Strategic Acquirers: EU Ecodesign Directive motor efficiency mandates reshape the acquisition landscape toward brushless DC platform owners and away from legacy AC induction specialists facing technical obsolescence. Five-to-ten year viability favors vertically integrated motor producers with captive rare-earth magnet supply agreements. Watch for SAMR enforcement tightening on GB energy efficiency standards as signal for Chinese market access barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Core Production | Captive rare-earth magnet supply insulates margin from commodity volatility affecting Guangdong-assembled competitors. |
| Cloud-Connected Predictive Maintenance Launch | Vibration sensor integration with SaaS platforms enables subscription revenue from California smoothie chain installed base. |
| Factory-Authorized Service Network Expansion | Direct technician dispatch in Shanghai and Beijing reduces mean-time-to-repair for bubble tea operator uptime guarantees. |
| Brushless DC Motor Platform Transition | EU Ecodesign Directive compliance positions premium tiers ahead of AC induction obsolescence across European member states. |
| FSSAI Certification Fast-Track Investment | Organized foodservice compliance unlocks Mumbai and Bangalore quick-service restaurant procurement ahead of retail outlet expansion. |
Methodological Framework
Operator-level perspectives from commercial kitchen maintenance directors, foodservice procurement managers, bubble tea franchise operators, and factory-authorized service technicians anchored the qualitative base. Secondary validation drew from FDA Food Code documentation, NSF International certification registries, SAMR GB standard filings, EU Machinery Directive technical documentation, and foodservice equipment customs records. Bottom-up unit economics triangulated against top-down market sizing across product type, application intensity, and technology tier segmentation dimensions.
Sensitivity analysis tested forecast robustness across copper price volatility scenarios, brushless DC adoption speed variations, and regional regulatory enforcement intensity assumptions. The analytical framework modeled countertop, immersion, and smart-enabled configurations against end-use intensity tiers spanning intermittent bar service through continuous-duty smoothie shop operation. CAGRs derived from installed base replacement cycles, new outlet formation rates, and technology substitution elasticities rather than extrapolated trend lines.
Decision-makers should treat outputs as directional under assumptions of sustained FDA Food Code enforcement, stable rare-earth magnet supply continuity, and gradual EU Ecodesign Directive phase-in schedules; material deviation in any assumption would warrant model refresh. Forecasts reflect these base conditions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Food Sorting Machines Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Tube Ice Machine Market