
 Ice Cream Machine Market | 2026-2036
Ice Cream Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Machine Market Intelligence
Stainless steel drum assemblies is recalibrating cost structures across mid-range equipment tiers. Taylor Company leverages captive foundry relationships to anchor North American production economics. Carpigiani sustains Italian manufacturing heritage while competing aggressively in Asian export channels. Electro Freeze differentiates through proprietary refrigeration control systems that extend equipment lifespan in high-cycle environments.
An ice cream machine is a thermodynamic processing unit that freezes and aerates dairy or non-dairy base mixtures through continuous or batch cooling cycles, typically operating between -6°C and -12°C discharge temperatures to achieve overrun targets of 30–60 percent depending on product category. Soft serve machines command the largest installed base across quick service restaurant chains, while gelato machines concentrate margin pools in artisanal dessert shops where output precision justifies premium pricing. Fully automatic technology is displacing manual configurations in institutional kitchens where labor scarcity drives capital substitution.
The US FDA Food Code and NSF/ANSI standards govern sanitary design requirements for commercial ice cream equipment sold in American foodservice channels. The EU F-Gas Regulation and REACH directives constrain refrigerant selection and material composition for machines distributed across European member states. Stakeholders must monitor refrigerant phase-down schedules and energy labeling expansions when configuring regional product portfolios.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choices across commercial ice cream equipment portfolios, forcing manufacturers to redesign thermal architectures around lower-GWP alternatives while maintaining discharge temperature precision.
Growth Catalysts
- Quick service restaurant expansion:Chained dessert concepts in China's tier-one cities are scaling frozen beverage programs, driving installed base growth for high-capacity soft serve systems.
- F-Gas phase-down mandates:The EU F-Gas Regulation is accelerating R&D investment in hydrocarbon and CO2 refrigeration circuits for European-bound equipment.
- Labor substitution economics:Fully automatic batch freezers are penetrating institutional kitchens where kitchen staff scarcity justifies capital expenditure on reduced-touch operation.
Market Restraints
- Stainless steel input volatility:Drum assembly fabrication depends on 304-grade stainless pricing, which fluctuates with nickel ore supply concentrated in Indonesian and Philippine mining corridors.
- Refrigerant supply concentration:Lower-GWP alternative production clusters in Chinese and German chemical manufacturing, creating single-source vulnerability for compliant machine configurations.
- Technical limitation in precision:Gelato overrun control below 20 percent remains difficult to automate, constraining volume growth in artisanal premium segments.
Strategic Opportunities
- Underpenetrated Southeast Asian food courts:Indonesian and Vietnamese shopping mall dessert kiosks currently rely on imported used equipment, creating first-mover potential for certified-new distribution partnerships.
- Regulatory tailwind from EU energy labeling:The expansion of commercial refrigeration efficiency grades is creating procurement preference for machines exceeding A-class thresholds in public sector tenders.
- Technology convergence:IoT-enabled predictive maintenance modules are integrating with existing HACCP logging systems, enabling subscription-based service revenue streams.
Industry Challenges
- Refrigeration technician scarcity:Qualified service personnel for low-GWP system repair remain concentrated in Northern European and North American urban centers, extending mean-time-to-repair in emerging markets.
- NSF/ANSI certification timelines:Sanitary design validation for new drum geometries currently requires 14-18 month approval cycles, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Machine Market |
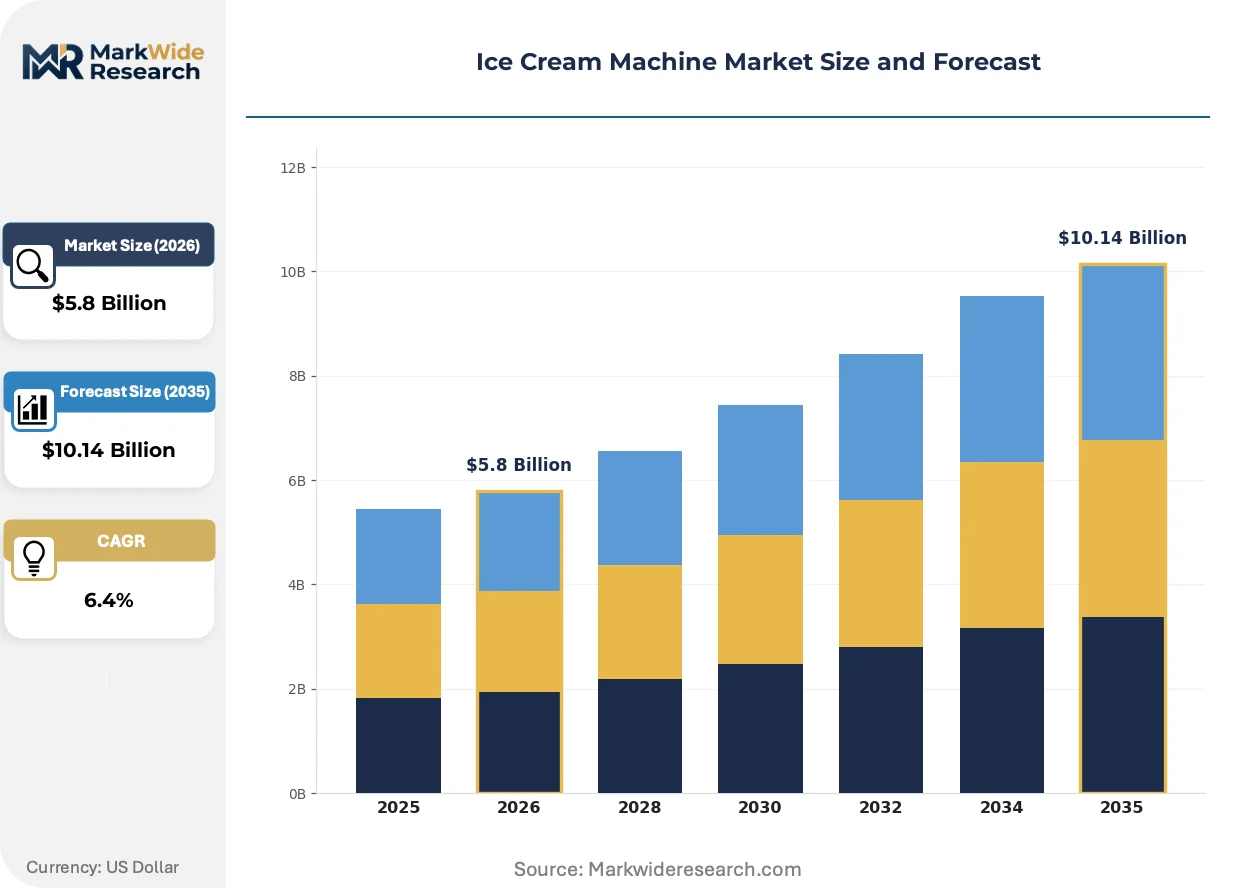
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Serve Machine, Batch Freezer, Gelato Machine, Hard Ice Cream Maker, Frozen Yogurt Machine Technology: Manual, Semi-Automatic, Fully Automatic, Countertop, Floor Standing Application: Restaurants, Cafés, Food Trucks, Event Catering, Dessert Shops End User: Quick Service Restaurants, Confectioneries, Hospitality Chains, Institutional Kitchens, Retail Outlets |
| Companies Covered | Taylor Company, Carpigiani, Electro Freeze, Stoelting, Nissei, Spaceman, ICETRO, Donper, Gram Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Machine Market Strategic Shifts & Innovations
Equipment intelligence and refrigerant chemistry are the twin vectors reshaping competitive differentiation, with connectivity features and thermal architecture redesigns commanding parallel development resources.
Modular refrigeration units with swappable compressor packs are decentralizing service economics for high-cycle QSR operators. Chains with 500-plus store footprints in Texas and Florida are piloting field-replaceable cooling modules that reduce technician dispatch frequency. This architecture is decentralizing aftermarket revenue from authorized service networks toward component suppliers with logistics scale.
The EU F-Gas Regulation's quota allocation mechanism is tightening hydrofluorocarbon availability for equipment classes above 150 grams charge size. Manufacturers serving German and French distribution channels are accelerating CO2 transcritical and propane circuit qualification programs. Gelato equipment with sub-150 gram charges is gaining share in Italian artisanal export configurations.
Leasing-based equipment access is displacing outright purchase in UK and Australian dessert franchise rollouts. Private equity-backed multi-unit operators prefer operational expenditure treatment for store-fit depreciation. This shift is most visible in London and Sydney metropolitan clusters where property cost inflation already strains capital allocation flexibility.
Ice Cream Machine Market Segmentation
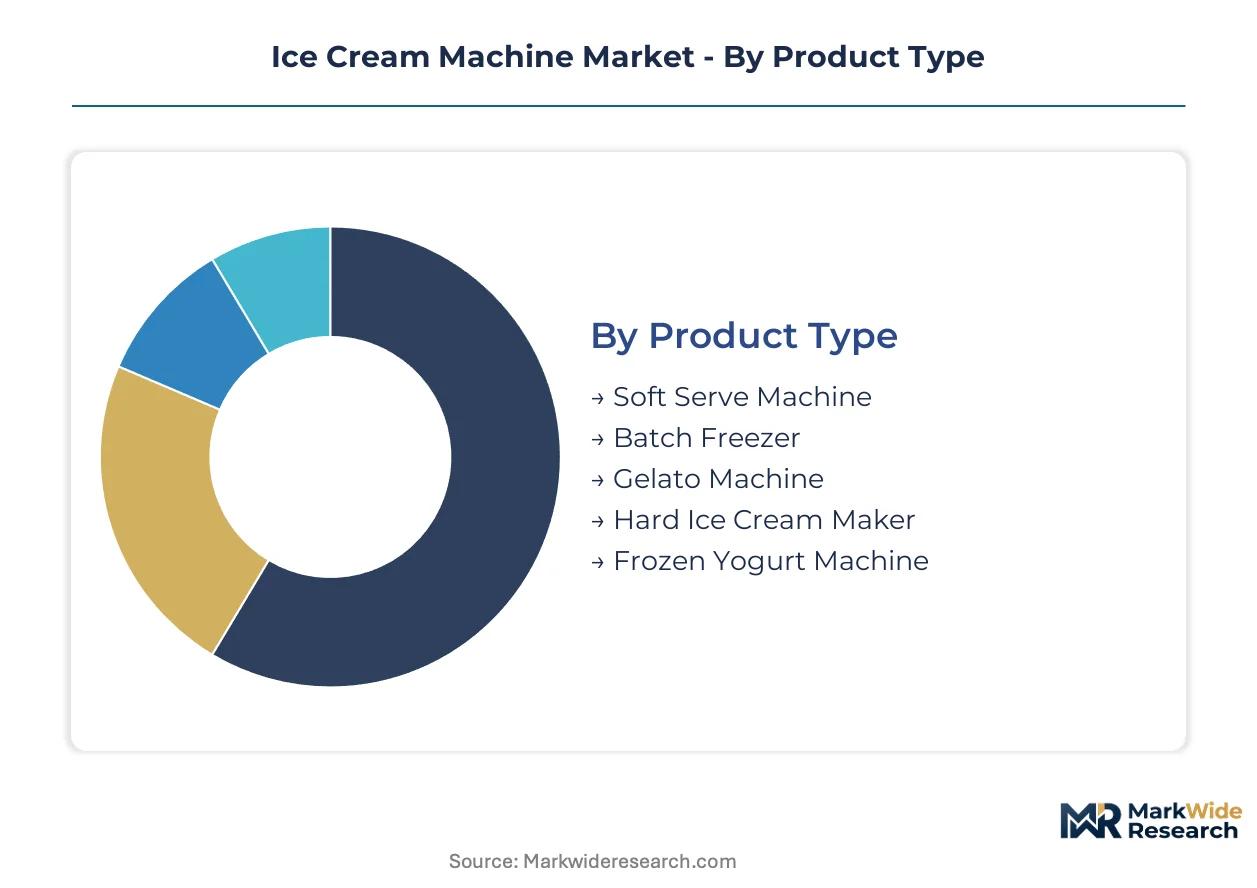
Ice cream machine segmentation reveals distinct thermal architectures and operational models that align with specific service velocities and labor constraints. Product type and technology choices cascade into divergent margin structures and aftermarket service requirements.
Product Type:
Thermal processing architectures define output characteristics, overrun precision, and capital recovery timelines across commercial deployments.
- Soft Serve Machine:Continuous freezing systems with pressurized hopper feeds achieve 35-50% overrun through integrated air injection pumps. Quick service restaurant chains in China's tier-one cities concentrate demand for twin-twist configurations that reduce flavor changeover downtime.
- Batch Freezer:Cylindrical horizontal drums with scraper blades process 5-40 liter charges in discrete cycles, enabling artisanal texture control. Institutional kitchens in US school districts and hospital systems are automating these units to offset line cook staffing gaps.
- Gelato Machine:Slow-churn horizontal cylinders operate at higher temperatures (-8°C to -12°C) with lower overrun targets (20-30%) for dense mouthfeel. Italian artisanal export channels sustain premium pricing despite constrained automation potential.
- Hard Ice Cream Maker:Blast freezing tunnels or contact plate systems solidify pre-frozen base for retail packaging applications. North American dairy processors deploy these for private-label supermarket programs.
- Frozen Yogurt Machine:Modified soft serve architectures with acidified base tolerance and self-serve dispensing interfaces. US West Coast self-serve chains drove installed base expansion during frozen yogurt's 2010s resurgence.
Soft serve machines lead on scale; gelato machines lead on momentum through Asian dessert concept proliferation.
Technology:
Automation intensity and physical footprint determine labor substitution economics and real estate compatibility across venue types.
- Manual:Hand-cranked or paddle-operated units requiring continuous operator attention for freezing cycle management. Surviving demand concentrates in Italian gelato training academies and museum demonstration kitchens where process visibility matters.
- Semi-Automatic:Motorized scraper systems with timed cycle controls but manual ingredient loading and extraction. Southeast Asian food courts in Jakarta and Ho Chi Minh City favor these for capital efficiency amid equipment import tariffs.
- Fully Automatic:Programmable logic controllers manage hopper levels, viscosity sensing, and self-cleaning sequences without operator intervention. US and UK institutional kitchens facing 20%+ kitchen staff vacancy rates are accelerating replacement schedules.
- Countertop:Compact vertical configurations under 60cm width for front-of-house placement in space-constrained cafés. London and Sydney metropolitan dessert franchises prioritize these for lease economics.
- Floor Standing:High-capacity twin-barrel systems with 50+ liter hopper capacity for peak-hour throughput. Texas and Florida QSR pilots with 500-plus store networks are testing swappable compressor modules in these formats.
Fully automatic configurations are climbing the fastest on labor substitution economics; countertop units gain share fastest through leasing penetration in high-rent districts.
Application:
Service velocity requirements and peak demand patterns shape equipment specification priorities across venue archetypes.
- Restaurants:Post-meal dessert programs requiring low-volume, high-margin output with minimal kitchen footprint. Full-service chains in France and Germany specify under-counter batch freezers for à la minute plating.
- Cafés:Beverage-anchored operations with frozen drink cross-utilization driving soft serve and granita hybrid specifications. Australian café culture has normalized affogato and cold brew float menus.
- Food Trucks:Mobile power constraints and vibration tolerance prioritize sealed refrigeration circuits and generator-compatible electrical draws. Los Angeles and Austin food truck clusters sustain specialized equipment refurbishment channels.
- Event Catering:Rental-oriented demand for rapid deployment and breakdown with NSF/ANSI sanitary validation for temporary food permits. UK wedding and festival circuits drive seasonal demand spikes.
- Dessert Shops:Single-category focus justifying premium equipment spend for product differentiation through texture precision. Shanghai and Beijing tier-one mall concepts compete on visual theater and Instagram-optimized presentation.
Dessert shops lead on equipment specification intensity; food trucks are expanding most quickly through regulatory liberalization in US secondary cities.
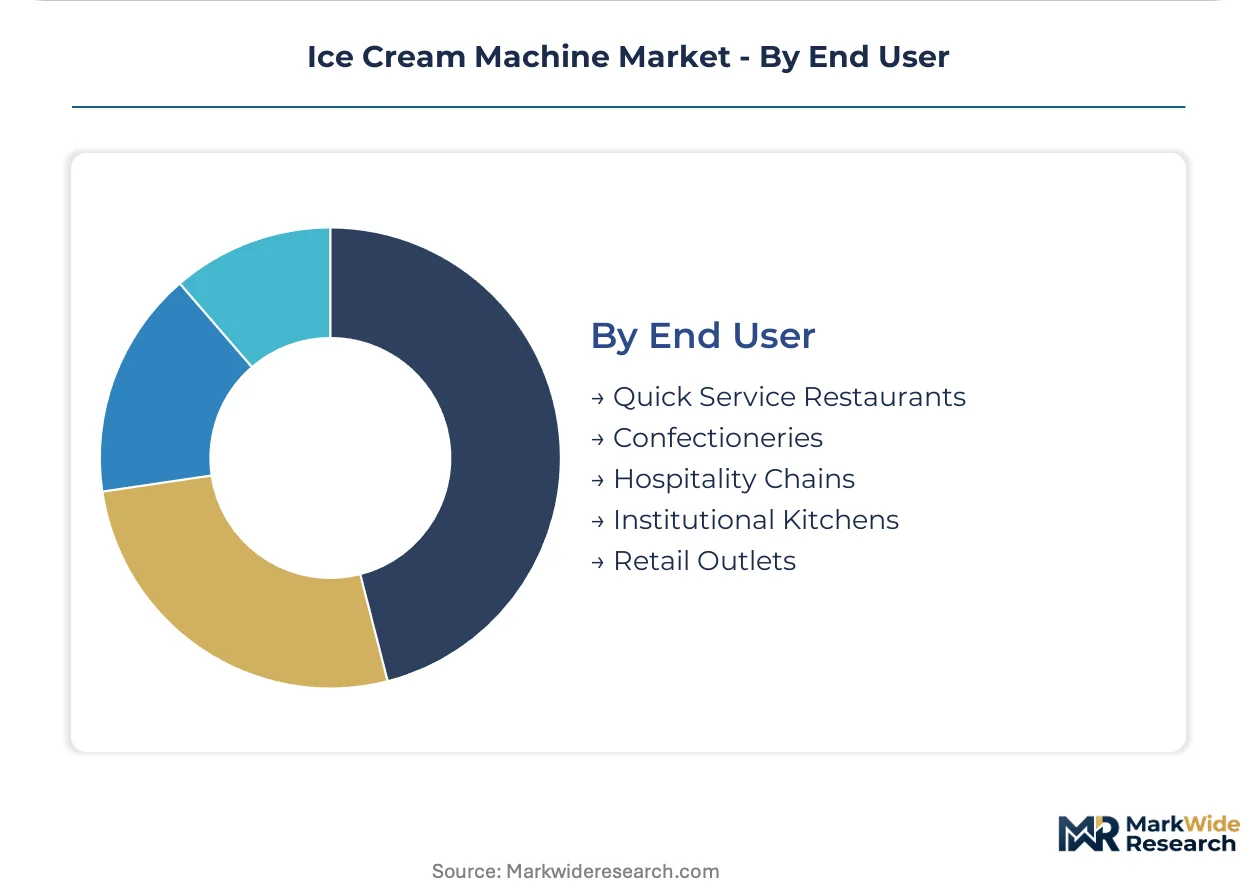
End User:
Procurement scale and standardization pressure create divergent vendor relationship models and service contract structures.
- Quick Service Restaurants:Centralized procurement with 10,000-plus unit networks dictating custom specifications and exclusive service agreements. Yum Brands and McDonald's franchisee cooperatives negotiate multi-year equipment refresh cycles.
- Confectioneries:Chocolate and pastry specialists adding frozen lines with equipment selected for visual merchandising compatibility. Belgian and Swiss chocolatiers emphasize brass and copper aesthetic finishes.
- Hospitality Chains:Hotel F&B operations balancing breakfast buffet automation with lobby café dessert theater. Marriott and Hilton specification committees standardize on NSF-certified units with HACCP logging integration.
- Institutional Kitchens:School districts, prisons, and military mess halls prioritizing USDA nutritional compliance and reduced-touch operation. US K-12 procurement aggregates through cooperative purchasing alliances.
- Retail Outlets:Supermarket in-store dessert counters and convenience store frozen treat programs. Japanese konbini chains have pioneered compact soft serve modules with 30-second service targets.
Quick service restaurants anchor volume concentration; institutional kitchens show steepest expansion trajectory through federal labor substitution incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities concentrate frozen dessert equipment procurement as chained concepts proliferate in Shanghai and Beijing shopping districts. The EU F-Gas Regulation is compressing refrigerant architecture choices for manufacturers serving European distribution channels. Quick service restaurant expansion across Asia-Pacific markets is redistributing demand geography.
United States
Quick service restaurant chains with 500-plus store networks in Texas and Florida are piloting modular refrigeration architectures to reduce service dispatch frequency. The FDA Food Code and NSF/ANSI standards govern sanitary design requirements for commercial equipment sold through American foodservice channels. Los Angeles and Austin food truck clusters sustain specialized refurbishment channels for mobile power-constrained configurations.
China
Tier-one city dessert concepts in Shanghai and Beijing are scaling frozen beverage programs, driving installed base growth for high-capacity soft serve systems. The country's national standards administration constrains refrigerant selection through dual carbon goals and environmental ministry directives. Zhengzhou-based fabricators supply domestic food court operators while competing in Southeast Asian export channels.
Germany
Artisanal gelato equipment manufacturers face compressed hydrofluorocarbon availability under the EU F-Gas Regulation's quota allocation mechanism for charge sizes above 150 grams. The ECHA REACH directives constrain material composition for machines distributed across European member states. Bavarian engineering clusters are accelerating CO2 transcritical and propane circuit qualification programs for compliant export configurations.
United Kingdom
Private equity-backed multi-unit operators in London metropolitan clusters prefer operational expenditure treatment for store-fit depreciation through leasing-based equipment access. The country's national food safety regulator mandates HACCP logging integration for public sector tenders. UK wedding and festival circuits drive seasonal demand spikes for rental-oriented rapid deployment configurations.
Australia
Café culture in Sydney has normalized affogato and cold brew float menus, driving soft serve and granita hybrid specifications. The country's national standards body governs electrical safety and energy efficiency labeling for commercial refrigeration equipment. Metropolitan dessert franchises prioritize countertop configurations under 60cm width for lease economics in high-rent districts.
Ice Cream Machine Market Key Industry Players
Global majors compete with regional champions across thermal architecture specialization and aftermarket service network density. The vendor base stratifies between captive foundry operators, Italian manufacturing heritage houses, and refrigeration control system specialists. Three archetypes dominate: vertically integrated North American producers, European precision engineering houses, and Asian scale fabricators. Competitive moves concentrate on strategic partnerships for compressor pack distribution and geographic expansion through certified-new distribution partnerships in underpenetrated Southeast Asian markets.
Among North American incumbents, Taylor Company anchors production economics through captive supply relationships. Carpigiani exemplifies European manufacturing heritage positioning while competing aggressively in Asian export channels. Electro Freeze occupies a position within the control systems specialization tier. These three represent distinct competitive vectors: scale-driven foundry integration, artisanal precision heritage, and proprietary refrigeration intelligence.
| Leading Market Players |
|---|
| Taylor Company |
| Carpigiani |
| Electro Freeze |
| Stoelting |
| Nissei |
| Spaceman |
| ICETRO |
| Donper |
| Gram Equipment |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up dessert franchise operators in London and Sydney metropolitan clusters are compressing capital expenditure cycles into operational expenditure structures, tightening pricing discipline on equipment vendors while demanding extended service bundling. This financing pattern concentrates procurement leverage among fewer buyer entities, forcing manufacturers to absorb stainless steel input volatility through fixed-rate leasing contracts rather than pass-through mechanisms.
Pricing Analysis
Input-cost pass-through from 304-grade stainless steel and lower-GWP refrigerant chemistry is reshaping margin structures across equipment tiers. Pricing stratifies across premium artisanal configurations, standard QSR-grade systems, and economy countertop units, with differentiation anchored in NSF/ANSI certification grade and compressor modularity. Cost compression in mid-range tiers is intensifying because Indonesian nickel ore supply volatility feeds directly into drum assembly fabrication economics. Institutional kitchens exhibit highest price sensitivity due to cooperative purchasing alliance aggregation, while artisanal dessert shops in Italian export channels show lowest sensitivity given texture precision premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from quick service restaurant chains with 10,000-plus unit networks, while authorized distributor networks serve fragmented dessert shop and café segments. Manufacturing concentrates in Italy for artisanal gelato equipment, the United States for soft serve systems with captive foundry integration, and China for domestic food court supply and Southeast Asian export channels. Component sourcing draws from German and Chinese chemical manufacturers for lower-GWP refrigerant alternatives, Japanese compressor specialists, and Indonesian nickel processing for stainless inputs. Single-source vulnerability in compliant refrigerant production creates supply chain risk. Distribution runs through equipment leasing platforms in UK and Australian markets alongside traditional capital purchase channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a regulatory compounder, with its quota allocation mechanism for charge sizes above 150 grams forcing equipment redesigns that accelerate replacement demand across European distribution channels.
For Market Incumbents: Deploy captive foundry relationships to anchor production economics against stainless steel input volatility. Taylor Company and comparable vertically integrated North American producers should expand modular refrigeration architectures with swappable compressor packs to defend service revenue streams against component supplier encroachment. Accelerate CO2 transcritical and propane circuit qualification programs ahead of hydrofluorocarbon phase-down deadlines to preempt competitor compliance positioning. For New Entrants and Emerging Players: Enter via certified-new distribution partnerships in Indonesian and Vietnamese shopping mall dessert kiosks currently reliant on imported used equipment. Target Southeast Asian food court segments for first-mover positioning, leveraging capital-efficient semi-automatic configurations that navigate equipment import tariffs. Pursue go-to-market angles through IoT-enabled predictive maintenance modules that integrate with existing HACCP logging systems, enabling subscription-based service revenue differentiation against established vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional scale fabricators with underdeveloped aftermarket service networks but established Southeast Asian distribution relationships. Long-term viability over the coming decade hinges on regulatory compliance capability across multiple jurisdictions rather than pure manufacturing scale. Acquisition targets should demonstrate qualified service personnel density for low-GWP system repair or clear pathways to technician training partnerships. Watch refrigerant phase-down schedule acceleration as the critical inflection signal for equipment replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Lower-GWP Refrigerant Architecture Transition | EU F-Gas Regulation compliance secures market access across German and French distribution channels. |
| Modular Compressor Pack Development | Field-replaceable cooling modules reduce technician dispatch frequency for Texas and Florida QSR pilots. |
| IoT Predictive Maintenance Integration | HACCP logging compatibility enables subscription revenue streams from institutional kitchen accounts. |
| Southeast Asian Distribution Partnership | Certified-new equipment penetration displaces imported used units in Jakarta and Ho Chi Minh City food courts. |
| Leasing-Based Equipment Access Expansion | Operational expenditure treatment appeals to private equity-backed operators in London and Sydney metropolitan clusters. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with equipment manufacturer product managers, quick service restaurant procurement directors, commercial refrigeration technicians, and foodservice distributor account executives informed demand-side and supply-side perspectives. Secondary sources include EU F-Gas Regulation quota allocation filings, NSF/ANSI sanitary design certification records, customs trade data for stainless steel component flows, and EPA refrigerant phase-down schedules. Bottom-up equipment shipment analysis triangulates against top-down foodservice capital expenditure surveys.
Granularity-level modeling disaggregates volume and value outputs across product type, automation technology, application venue, and end-user procurement scale throughout the forecast period. Soft serve, batch freezer, and gelato thermal architectures were modeled separately given divergent margin structures and replacement cycle dynamics. CAGRs derive from regression analysis against chained dessert concept expansion rates, labor substitution economics in institutional kitchens, and regulatory compliance-driven replacement demand. Industry-specific inputs include refrigerant charge size distributions and NSF/ANSI certification timeline assumptions.
Inputs from equipment manufacturer shipment disclosures and foodservice operator capital expenditure surveys were available through the study window; gaps in real-time refrigerant pricing transparency and technician wage data by metropolitan market introduce uncertainty bands around service cost projections. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement consistency and stainless steel input price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Reach-In Freezers Market