
 Pasty Products Filling Machine Market | 2026-2036
Pasty Products Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pasty Products Filling Machine Market Analytics
Sanitary-grade stainless steel construction is rotating through the installed base as processors replace legacy carbon-steel equipment. IMA S.p.A. leverages its pharmaceutical-grade clean-design heritage to cross-sell into premium food applications. Syntegon Technology GmbH anchors European demand with modular platforms that reduce changeover downtime. ProMach Inc. competes across North America through distributed service networks that shorten spare-part lead times.
A pasty products filling machine is an automated dispensing system engineered to handle non-Newtonian, high-viscosity substances—typically employing positive-displacement pumps or servo-driven pistons with tolerance thresholds of ±0.5% by volume—designed for hygienic transfer into rigid or flexible primary packaging. Servo fillers command the technology tier where precision and recipe traceability justify capital outlay, while pneumatic systems retain share in cost-sensitive emerging markets. Contract packaging represents the fastest-growing end-user channel as brand owners outsource capital-intensive filling operations to third-party operators.
EU MDR and FDA cGMP frameworks enforce validated clean-in-place protocols that disqualify non-compliant equipment from pharmaceutical and cosmetic lines. REACH restrictions on certain seal elastomers push OEMs toward fluoropolymer alternatives that extend maintenance intervals. Stakeholders must weigh upgrade cycles against evolving material compliance lists and energy-efficiency benchmarks that now figure into total cost of ownership calculations.
Market Dynamics
Servo-driven piston architectures are displacing pneumatic systems across European dairy and confectionery lines as EU MDR hygiene mandates harden compliance thresholds for clean-in-place validation.
Growth Catalysts
- EU MDR alignment:Food processors in Germany and Italy are retrofitting filling lines to meet pharmaceutical-grade hygiene benchmarks, creating replacement demand for stainless-steel servo equipment.
- PLI-linked capital subsidies:Contract packaging firms in India are expanding installed capacity under production-linked incentive schemes that offset 20-30 percent of equipment acquisition costs.
- Fluoropolymer seal adoption:REACH restrictions on nitrile and EPDM elastomers are accelerating migration to perfluoroelastomer seals that extend maintenance intervals in high-temperature paste applications.
Market Restraints
- Stainless steel input volatility:Grade 316L sheet pricing swings are compressing OEM margins and delaying quotation validity windows to 30 days.
- Precision component concentration:High-tolerance servo motors and harmonic drives concentrate supply among Japanese and German specialists, exposing lead time risk.
- Pneumatic system persistence:Cost-sensitive processors in Southeast Asia continue specifying air-driven fillers, capping premium equipment penetration rates.
Strategic Opportunities
- Clean-label dairy expansion:Greek yogurt and plant-based dessert producers in North America are specifying isolated filling zones to prevent cross-contamination between allergen and non-allergen SKUs.
- Modular platform architecture:OEMs offering tool-free changeover systems are capturing share from monolithic legacy designs as contract packagers run shorter production campaigns.
- FSSAI harmonization:India's alignment of food equipment standards with Codex Alimentarius is reducing certification duplication costs for exporters targeting Middle Eastern markets.
Industry Challenges
- Servo commissioning expertise:Shortage of technicians trained in motion control tuning is extending installation timelines and inflating field service costs.
- Legacy line integration:Retrofitting servo fillers into 1990s-era packaging halls requires custom mechanical interfaces that erode project margins.
- cGMP documentation burden:FDA validation protocols for pharmaceutical-cosmetic hybrid facilities are stretching qualification phases to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pasty Products Filling Machine Market |
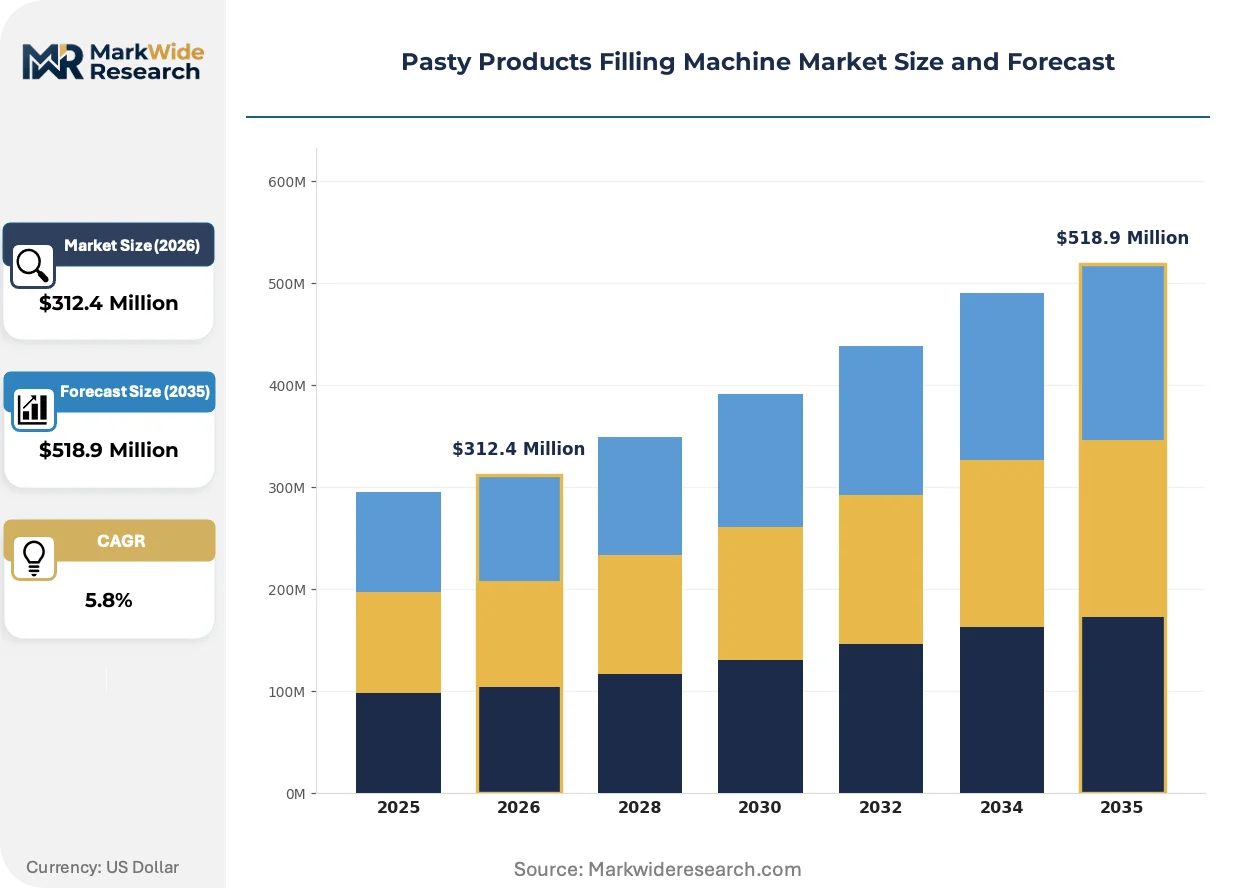
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Fillers, Pneumatic Fillers, Servo Fillers, Pump Fillers Technology: Volumetric, Weighing, Pressure, Vacuum End User: Food Manufacturing, Cosmetics, Pharmaceuticals, Contract Packaging Application: Bottling, Canning, Pouch Filling, Tub Filling |
| Companies Covered | IMA S.p.A., Syntegon Technology GmbH, Coesia S.p.A., JBT Corporation, ProMach Inc., FMT, Jornen Machinery, Accutek Packaging Equipment Companies, MECAPLASTIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pasty Products Filling Machine Market Evolving Landscape
Digital twin simulation and closed-loop weight verification are converging to compress commissioning cycles and reduce giveaway in high-value paste applications.
Single-use product-contact kits are supplanting fixed stainless-steel pistons and cylinders in multi-allergen facilities. Contract packagers operating nut-free, dairy-free, and gluten-free campaigns on shared lines are adopting disposable dosing chambers to eliminate CIP validation documentation between changeovers. This architecture is compressing equipment utilization rates for traditional clean-in-place systems.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing seal manufacturers to accelerate fluoropolymer alternatives with equivalent chemical resistance. European OEMs are qualifying FFKM and PTFE-compound seals ahead of 2025 enforcement windows. Dairy processors in France and the Netherlands are front-loading replacement purchases to avoid supply disruption.
Equipment-as-a-service contracting is displacing outright purchase in mid-scale food manufacturing. Brand owners in the United States are transferring capital risk to OEM finance arms in exchange for per-unit throughput fees. This model concentrates most visibly in private-label sauce and condiment operations where volume volatility complicates depreciation schedules.
Pasty Products Filling Machine Market Segmentation
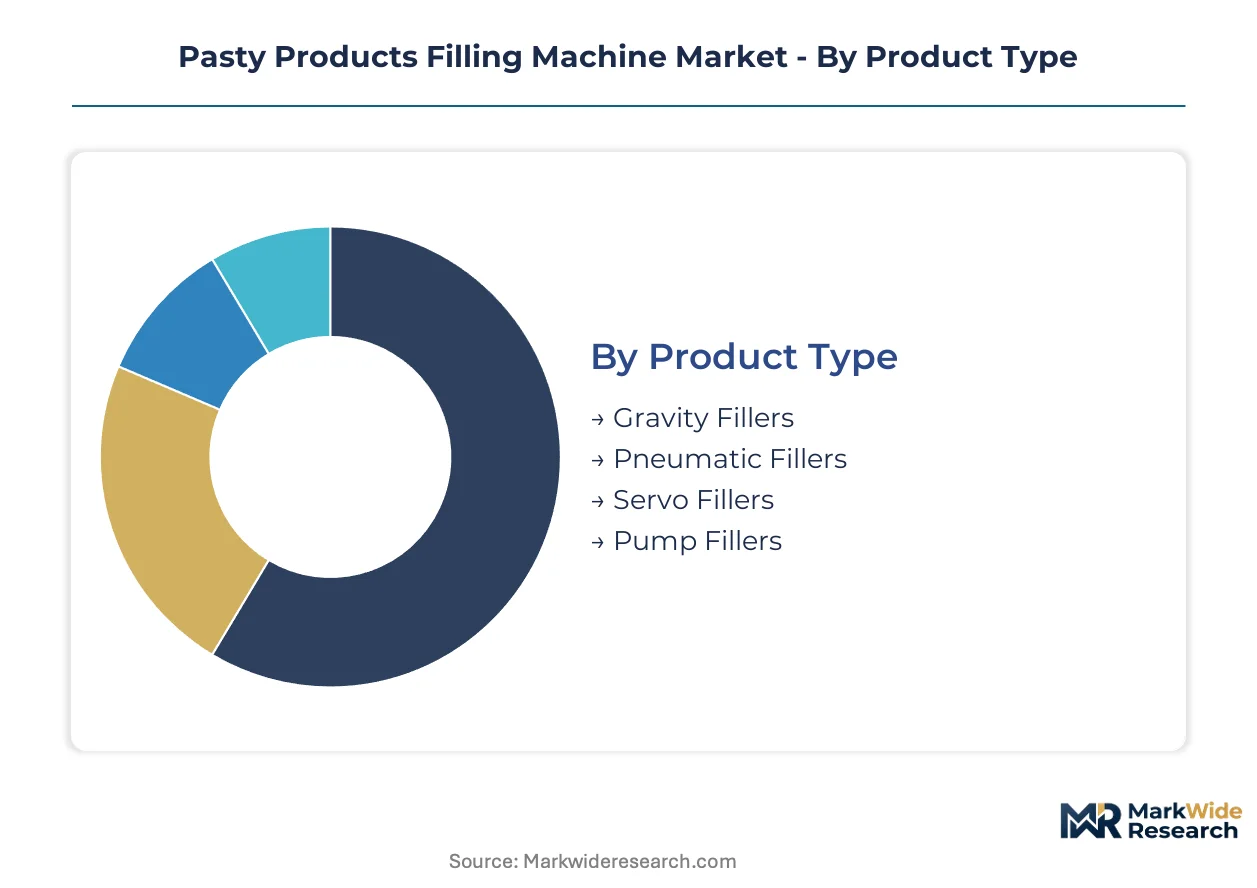
Pasty product filling machines serve distinct operational profiles across viscosity ranges, hygiene tiers, and packaging formats. Equipment selection hinges on shear sensitivity, throughput requirements, and changeover frequency rather than capital cost alone.
Product Type:
Channel flow splits sharply between OEM direct sales for high-specification servo systems and distributor networks for standardized pneumatic units.
- Servo Fillers:Closed-loop motor control achieves ±0.5% volumetric tolerance through programmable piston acceleration curves. German dairy processors specify these for high-value dessert applications where giveaway reduction justifies capital intensity.
- Pneumatic Fillers:Compressed-air piston drives dominate Southeast Asian sauce manufacturing where utility costs remain low and precision requirements moderate. Indian contract packagers under PLI schemes favor these for volume-scale condiment operations.
- Gravity Fillers:Open-channel flow suits low-viscosity dressings with minimal thixotropic behavior.
- Pump Fillers:Positive-displacement rotary or lobe configurations handle abrasive particulate suspensions in prepared meals.
Pneumatic equipment dominates installed base. Servo fillers are where expansion concentrates.
Technology:
Cost tier stratification separates premium closed-loop systems from economy open-loop alternatives.
- Volumetric:Fixed-displacement dosing via piston or cylinder delivers consistent fill volumes independent of product density variation. European confectionery lines specify these for fondant and praline applications where temperature-induced density shifts would corrupt weight-based systems.
- Weighing:In-line load cells with feedback correction target high-value pharmaceutical pastes. North American compounding pharmacies specify gravimetric verification for FDA cGMP compliance in topical ointment production.
- Pressure:Constant-head systems suit continuous-flow operations with minimal aeration sensitivity.
- Vacuum:Negative-pressure assist enables clean filling of viscous products into narrow-neck containers.
Volumetric systems anchor legacy infrastructure. Weighing technology is climbing the fastest among upgrade cycles.
End User:
Customer type determines service intensity and financing structure across the installed base.
- Contract Packaging:Third-party operators running multi-SKU campaigns demand tool-free changeover and disposable product-contact kits. US private-label sauce manufacturers outsource filling to these operators to avoid capital deployment on volatile volume forecasts.
- Food Manufacturing:Integrated processors prioritize line integration and ERP connectivity over flexibility. French dairy cooperatives specify isolated filling zones for allergen segregation in clean-label yogurt production.
- Cosmetics:Batch-scale operations with frequent formulation changes drive demand for rapid CIP validation.
- Pharmaceuticals:cGMP documentation requirements extend qualification timelines and favor established OEM relationships.
Food manufacturing commands the largest installed base. Contract packaging represents the steepest expansion trajectory.
Application:
Packaging format dictates mechanical interface geometry and downstream handling integration.
- Pouch Filling:Horizontal and vertical form-fill-seal integration requires precise dosing synchronization with film transport. Indian spice paste producers specify these for flexible retail formats targeting price-sensitive consumers.
- Bottling:Rigid container handling with screw-cap or snap-cap closure dominates condiment and sauce segments. Italian tomato paste processors retrofit legacy glass lines with servo piston retrofits to meet EU MDR hygiene benchmarks.
- Canning:Metal container filling with vacuum seamers suits shelf-stable prepared meals.
- Tub Filling:Wide-mouth plastic or paperboard tubs accommodate spreadable dairy and plant-based alternatives.
Bottling retains the deepest installed base. Pouch filling is gaining share fastest among emerging market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in Southeast Asia sustains pneumatic filler dominance, while German and Italian processors absorb servo-system premiums to meet EU MDR hygiene mandates. Demand elasticity thus splits sharply between regulatory-driven replacement markets and cost-optimized capacity expansion.
Germany
Dairy and confectionery processors in Bavaria and Baden-Württemberg are retrofitting legacy filling lines with servo-driven stainless-steel equipment. The EU MDR framework enforces pharmaceutical-grade clean-in-place validation that disqualifies carbon-steel machinery from pharmaceutical-cosmetic hybrid facilities. Stuttgart-based OEMs are cross-selling pharmaceutical heritage into premium food applications.
India
Contract packaging firms in Maharashtra and Gujarat are scaling capacity under PLI-linked capital subsidy schemes that offset equipment acquisition costs. FSSAI harmonization with Codex Alimentarius is reducing certification duplication for exporters targeting Middle Eastern markets. Mumbai and Ahmedabad clusters concentrate spice paste and condiment filling operations.
United States
Private-label sauce manufacturers in the Midwest and Southeast are outsourcing filling operations to third-party operators to avoid capital deployment on volatile volume forecasts. FDA cGMP documentation requirements for pharmaceutical-cosmetic hybrid facilities extend qualification timelines. Equipment-as-a-service contracting is displacing outright purchase in mid-scale food manufacturing.
Italy
Tomato paste processors in Emilia-Romagna are retrofitting legacy glass bottling lines with servo piston systems to meet EU MDR hygiene benchmarks. REACH restrictions on nitrile and EPDM elastomers are accelerating migration to perfluoroelastomer seals. Parma and Modena industrial districts anchor premium sauce and condiment production.
France
Dairy cooperatives in Brittany and the Pays de la Loire are specifying isolated filling zones for allergen segregation in clean-label yogurt production. ECHA enforcement of REACH Annex XVII restrictions on per- and polyfluoroalkyl substances is front-loading seal replacement purchases. Rennes and Nantes clusters concentrate plant-based dessert filling operations.
Pasty Products Filling Machine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. German and Italian precision-engineering specialists dominate servo-driven premium segments, while Chinese and Southeast Asian fabricators anchor pneumatic system supply for cost-sensitive emerging markets. Three archetypes define competitive positioning: pharmaceutical-grade heritage players leveraging clean-design credentials, modular platform specialists optimizing changeover downtime, and distributed service networks competing on spare-part velocity. Consolidation through vertical integration into precision component supply and geographic expansion via distributor partnerships represent the dominant competitive moves.
Within the pharmaceutical-grade heritage tier, IMA S.p.A. and Syntegon Technology GmbH exemplify cross-sector positioning, with the Bologna-based S.p.A. and German GmbH occupying positions that bridge pharmaceutical validation standards and food-grade applications. ProMach Inc. represents the distributed service network archetype, with the Cincinnati-based corporation anchoring North American aftermarket competitiveness through regional spare-part logistics. These three entities collectively illustrate how regulatory proximity and service density shape competitive differentiation.
| Leading Market Players |
|---|
| IMA S.p.A. |
| Syntegon Technology GmbH |
| Coesia S.p.A. |
| JBT Corporation |
| ProMach Inc. |
| FMT |
| Jornen Machinery |
| Accutek Packaging Equipment Companies |
| MECAPLASTIC |
| Others |
Value Network & Pricing Analysis
EU MDR validation protocols gate both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb pharmaceutical-grade documentation costs while processors pay premiums for compliant stainless-steel servo architectures.
Pricing Analysis
Aftermarket service contracts and spare-part subscriptions now drive lifetime value capture across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade servo systems from modular food-grade platforms and pneumatic units for emerging markets. Price differentiation rests on certification tier and geographic service density, with EU MDR-aligned equipment commanding substantial premiums over legacy carbon-steel alternatives. Cost compression in pneumatic segments is intensifying because Indian contract packagers under PLI schemes prioritize capital efficiency over precision specifications. Southeast Asian sauce manufacturers exhibit highest price sensitivity, while North American dairy processors show lowest sensitivity due to giveaway reduction economics.
Supply Chain Analysis
Precision servo motor and harmonic drive procurement from Japanese and German specialists creates a single-source vulnerability for European and North American OEMs. Component supply concentrates in Japan, Germany, and China, with high-tolerance motion control systems drawing from Tokyo and Stuttgart specialists while pneumatic assemblies source from Shenzhen and Guangzhou fabricators. Raw material dependencies span Grade 316L stainless steel sheet, perfluoroelastomer seal compounds, and rare-earth servo magnets. Tariff exposure on Japanese precision components is accelerating dual-sourcing qualification timelines. Distribution runs through OEM direct channels for high-specification systems and regional distributor networks for standardized pneumatic units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting represents a substitution threat that incumbents must navigate, as brand owners transfer capital risk to OEM finance arms and compress traditional equipment sales margins.
For Market Incumbents: Compound aftermarket service density to defend against equipment-as-a-service displacement. Establish captive spare-part logistics in Midwest and Southeast US clusters to match ProMach's regional velocity. Deepen backward integration into precision servo component supply to reduce lead-time exposure from Japanese specialists. Prioritize EU MDR documentation libraries as a retention moat against modular platform competitors. For New Entrants and Emerging Players: Servo commissioning expertise scarcity in Southeast Asia opens white-space opportunity for technical training and field service bundling. Target Indian contract packaging clusters in Maharashtra and Gujarat with PLI-compliant pneumatic platforms paired with localized spare-part inventory. Penetrate through equipment-as-a-service financing structures that match brand-owner risk-transfer preferences without requiring incumbent-scale balance sheets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-as-a-service contracting as OEMs retain asset ownership. Five-to-ten year viability favors platform specialists with modular architecture and pharmaceutical-grade validation heritage over monolithic legacy fabricators. Monitor FSSAI harmonization progress with Codex Alimentarius as inflection signal for Indian exporter consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive supply of harmonic drives from German specialists reduces lead-time risk for servo system OEMs. |
| Equipment-as-a-Service Contracting | Per-unit throughput fees transfer capital risk from Midwest sauce manufacturers to OEM finance arms. |
| EU MDR Validation Library Investment | Pharmaceutical-grade documentation accelerates qualification timelines for dairy-cosmetic hybrid facilities. |
| Regional Spare-Part Logistics Expansion | Southeast US distribution nodes compress field service response times for private-label condiment operators. |
| Modular Platform Architecture Development | Tool-free changeover systems capture contract packaging volume from monolithic legacy designs. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at dairy and confectionery processors, aftermarket service heads at OEMs, procurement leads at contract packaging firms, and regulatory affairs specialists at pharmaceutical-cosmetic hybrid facilities, and refined through secondary validation across EU MDR guidance documents, FDA cGMP filings, FSSAI equipment standards, REACH Annex XVII restriction timelines, and customs trade data on stainless steel sheet imports, with bottom-up equipment shipment tallies triangulated against top-down processor capital expenditure surveys.
Variance decomposition across the projection horizon isolates volume drivers by technology tier, end-user channel, and application format, with segmentation dimensions spanning servo versus pneumatic versus gravity versus pump filler architectures, volumetric versus weighing versus pressure versus vacuum dosing technologies, contract packaging versus integrated food manufacturing versus cosmetics versus pharmaceutical end-user categories, and pouch versus bottling versus canning versus tub filling applications. CAGRs were derived from installed base replacement cycles and capacity expansion pipelines, with industry-specific inputs including PLI scheme uptake rates in India and EU MDR retrofit timelines in Germany and Italy.
Underlying assumptions cover stainless steel price stabilization, REACH enforcement schedules, and servo component supply normalization, with deviation risk concentrated in Grade 316L input volatility and precision motor lead-time extensions. Practitioners should keep alternative scenarios live as FSSAI harmonization progress and equipment-as-a-service penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Cookie Dropper Machine Market