
 Europe Flowers and Ornamental Plants Market | 2026-2036
Europe Flowers and Ornamental Plants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flowers and Ornamental Plants Market Foresight
Hospitality procurement is shifting from weekly cut-flower deliveries toward long-term living plant contracts. Syngenta Flowers leverages its breeding pipeline to supply climate-adapted varieties suited for indoor longevity. Royal FloraHolland anchors the Dutch auction system, controlling price discovery for roughly half of Europe's traded floriculture volume. Dümmen Orange specializes in potted orchid genetics, extending shelf life for retail and commercial accounts.
Europe flowers and ornamental plants encompass live botanical products cultivated for aesthetic, ceremonial, and environmental enhancement rather than food or pharmaceutical use, with critical quality parameters including vase life, bloom uniformity, root ball integrity, and phytosanitary certification under EU Plant Health Regulation 2016/2031. Cut flowers still generate the largest revenue pool, though margin compression at auction pushes growers toward potted plants where branding and varietal exclusivity protect returns. Online retail is the fastest-growing distribution channel, yet florists retain the highest margin capture through bespoke arrangement services and event contracts.
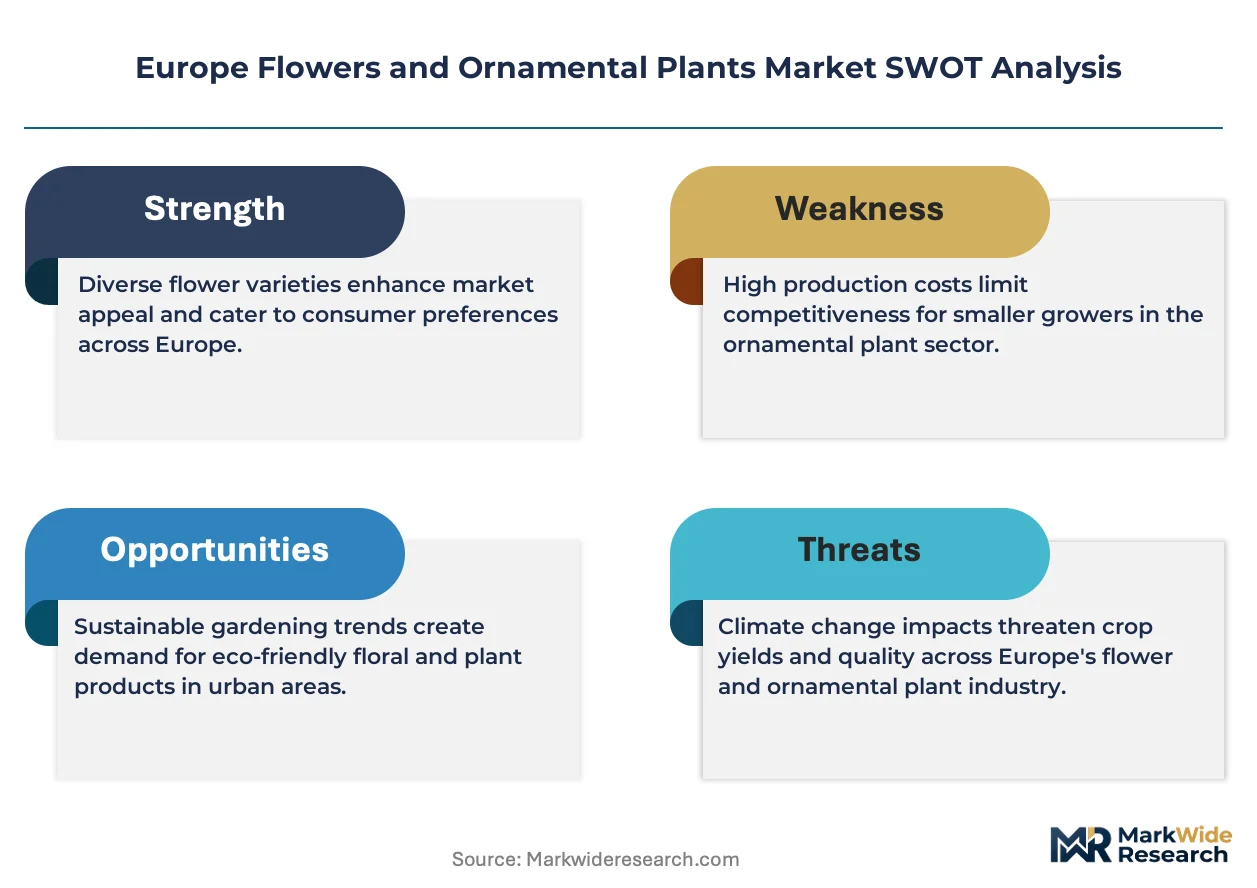
EMA and national plant health agencies enforce the EU Plant Health Regulation, restricting imports of high-risk propagation material and reshaping sourcing geography for nurseries. REACH and the EU Green Deal pressure substrate and agrochemical inputs, forcing investment in biological pest management and peat alternatives. Stakeholders must decide whether to absorb compliance costs or reposition toward premium certified segments where buyers accept price premiums for verified sustainable production.
Market Dynamics
The Dutch auction system concentrates price discovery power while EU Green Deal mandates force substrate and irrigation overhauls across the production base. Royal FloraHolland's infrastructure dominance and REACH-driven input restrictions together reshape grower economics and sourcing geography.
Growth Catalysts
- Corporate interior styling pivot:Hospitality and office managers now favor living plant installations over disposable cut arrangements. Long-term service contracts generate recurring revenue streams for specialized growers.
- EU Green Deal substrate mandates:National carbon accounting rules pressure growers toward peat-free growing media. Early adopters capture premium positioning in sustainability-certified retail channels.
- Netherlands auction infrastructure:Royal FloraHolland's centralized trading platform reduces transaction friction for premium orchids and succulents. Varietal R&D clusters in Westland accelerate new cultivar commercialization.
Market Restraints
- Peat substitution cost inflation:Coconut coir and wood fiber alternatives trade at 15-40% premiums versus traditional substrates. Margin compression hits mid-scale operations unable to pass input costs downstream.
- Dutch auction dependency:Roughly half of Europe's traded floriculture volume flows through Aalsmeer and Naaldwijk. Single-point concentration creates vulnerability to logistics disruptions or platform fee increases.
- Phytosanitary import friction:EU Plant Health Regulation 2016/2031 restricts high-risk propagation material from non-EU origins. Breeding programs face extended varietal development timelines.
Strategic Opportunities
- Poland and Romania greenhouse expansion:Lower land and labor costs attract Dutch capital for orchid and potted plant production. Proximity to growing Central European retail demand shortens cold-chain distances.
- Closed-loop irrigation technology:Water recirculation systems cut input costs 30-50% while satisfying national discharge permits. Integration with biological pest management reduces agrochemical residues.
- Online direct-to-consumer channels:Subscription plant services bypass auction fees and wholesale markups. Berlin and Paris urban markets show strongest trial rates for curated monthly deliveries.
Industry Challenges
- Biological pest management expertise scarcity:Integrated pest management protocols demand entomology and microbiology skills rare in conventional operations. Training programs at Wageningen University cannot supply sufficient graduates.
- Peat-free substrate performance variability:Batch inconsistency in alternative media disrupts irrigation scheduling and root development. Growers sacrifice yield stability during multi-year substrate transition periods.
- EU Plant Health Regulation certification timelines:Novel cultivar registration requires 18-36 months of phytosanitary testing. Breeding pipelines face revenue recognition delays that strain R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flowers and Ornamental Plants Market |
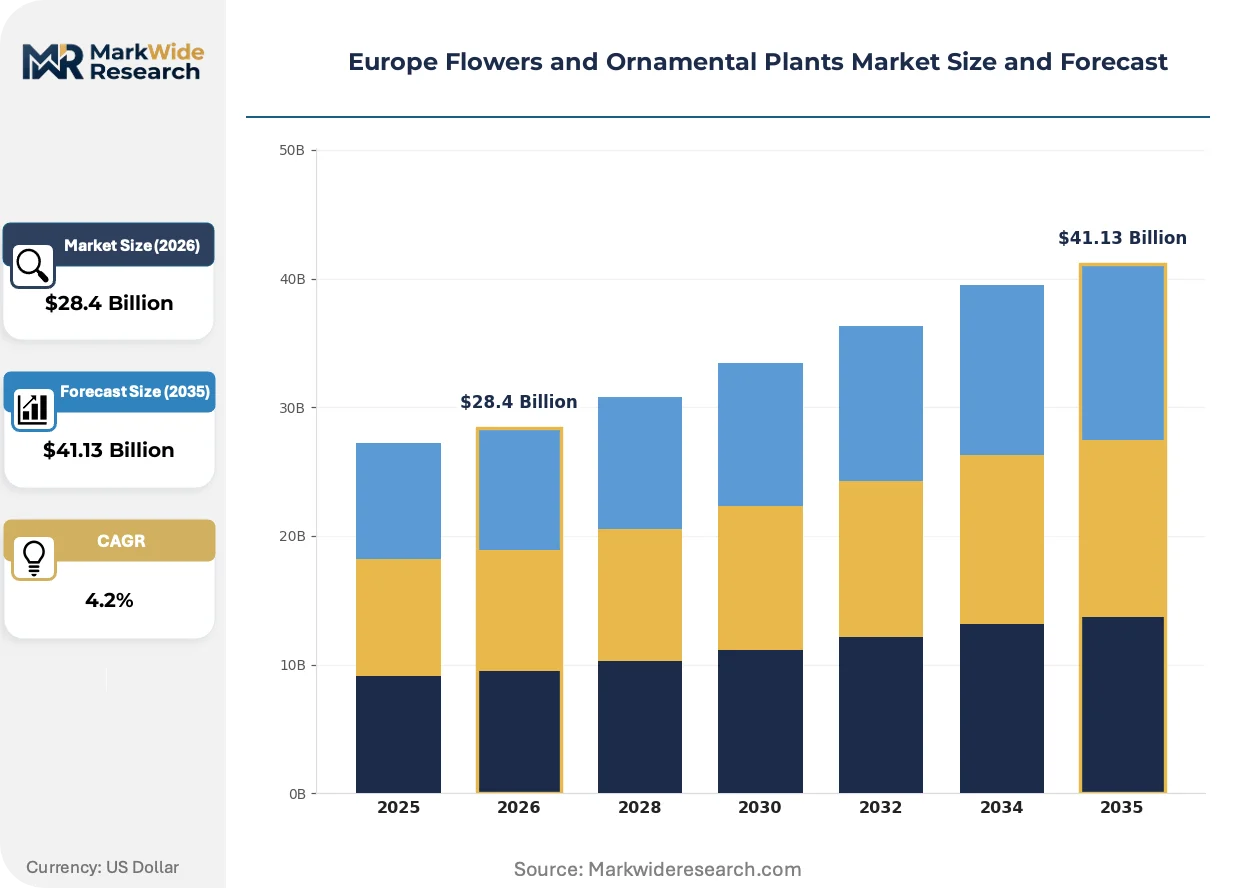
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $41.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cut Flowers, Potted Plants, Bedding Plants, Flower Seeds Distribution Channel: Online Retail, Supermarkets, Wholesalers, Florists End Use: Residential, Commercial, Event Planning, Landscaping Plant Variety: Annuals, Perennials, Succulents, Orchids |
| Companies Covered | Syngenta Flowers, Queens Group, Royal FloraHolland, Finlays, Selecta One, Dutch Flower Group, Beekenkamp, Washington Bulb, Dümmen Orange, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flowers and Ornamental Plants Market Shifts & Advancements
Biological cultivation methods and digital trading platforms are restructuring how ornamental plants move from propagation to end-use. Three developments merit particular attention for their near-term competitive implications.
LED supplemental lighting is overtaking high-pressure sodium systems in Dutch greenhouse operations. The technology enables spectral tuning for specific growth stages and cuts energy consumption substantially. Large-scale Westland growers now deploy tunable LED arrays for year-round rose and chrysanthemum production, compressing the payback period for climate-controlled infrastructure.
REACH substrate restrictions are mandating peat-phaseout timelines across member states. The regulation forces reformulation of growing media and accelerates R&D investment in wood fiber and composted bark alternatives. German and Belgian growers face the steepest compliance curves due to earlier national implementation schedules.
Living plant service contracts are displacing traditional cut-flower procurement in corporate and hospitality accounts. Facility managers now source multi-year interior landscaping agreements with guaranteed replacement clauses. London and Amsterdam office districts show the fastest contract conversion rates, driven by ESG reporting requirements for biophilic design credits.
Europe Flowers and Ornamental Plants Market Segmentation
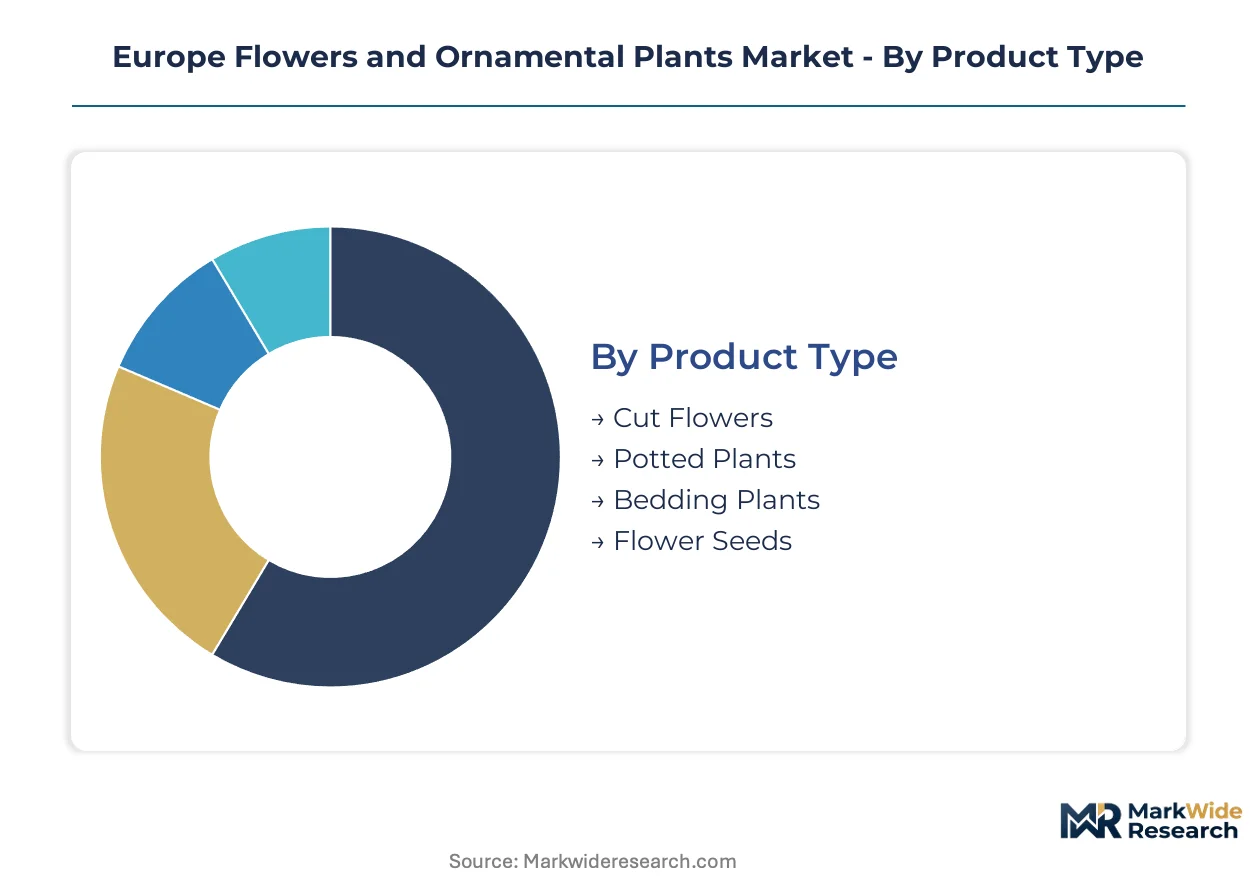
Segmentation in European floriculture reveals how supply chain configuration and buyer behavior split value capture across distinct channels. Understanding these divisions helps growers and distributors align production investments with margin-protected segments.
Product Type:
Production gravity concentrates in segments where Dutch auction infrastructure and varietal R&D clusters create competitive moats.
- Cut Flowers:Fresh-harvested blooms sold without root systems for immediate display. Dutch rose and chrysanthemum growers at Aalsmeer dominate volume, though margin compression at auction pushes consolidation toward branded varietal exclusivity.
- Potted Plants:Container-grown specimens with intact root balls enabling extended shelf life and repeat blooming cycles. Corporate interior styling contracts in London and Amsterdam favor orchids and succulents for biophilic design credits under ESG reporting frameworks.
- Bedding Plants:Seasonal annuals and perennials cultivated for outdoor garden installation. German and Belgian retail chains drive volume through spring promotional cycles tied to national peat-free substrate mandates.
- Flower Seeds:Propagation material for amateur and professional cultivation. Online direct-to-consumer channels in Berlin and Paris urban markets show strongest trial rates for curated monthly subscription services.
Cut flowers absorb the bulk of installed capacity; potted plants are expanding most quickly.
Distribution Channel:
Margin capture varies sharply by channel control over last-mile presentation and buyer relationship depth.
- Online Retail:Digital platforms enabling direct farm-to-consumer fulfillment. Subscription plant services bypass Royal FloraHolland auction fees and wholesale markups, with strongest penetration in metropolitan France and Germany.
- Supermarkets:Mass-market retail chains moving high-volume standardized SKUs. Centralized procurement teams at Ahold Delhaize and Carrefour negotiate long-term supply agreements with Dutch potted plant specialists.
- Wholesalers:Intermediary aggregators supplying florists and event planners. Royal FloraHolland's infrastructure dominance concentrates roughly half of Europe's traded floriculture volume through Aalsmeer and Naaldwijk.
- Florists:Independent artisans and chains providing bespoke arrangement services. Highest margin capture persists here through event contracts and guaranteed replacement clauses for corporate accounts.
Wholesalers handle the greatest transaction volume; online retail shows the steepest expansion trajectory.
End Use:
Demand fragmentation across buyer types creates divergent requirements for longevity, scale, and service integration.
- Residential:Individual consumers purchasing for home decoration and gifting. Polish and Romanian greenhouse expansion targets this segment with lower-cost orchid production positioned for Central European retail demand.
- Commercial:Office, hospitality, and retail property managers sourcing interior landscaping. Living plant service contracts with multi-year terms are displacing traditional cut-flower procurement in London and Amsterdam districts.
- Event Planning:Temporary installations for weddings, corporate functions, and ceremonial occasions. Florists retain pricing power here through bespoke design capabilities and last-mile logistics coordination.
- Landscaping:Large-scale outdoor projects by municipal and private developers. Bedding plants dominate this segment with seasonal procurement cycles tied to construction timelines and climate windows.
Commercial applications command the highest contract values; residential channels are climbing the fastest.
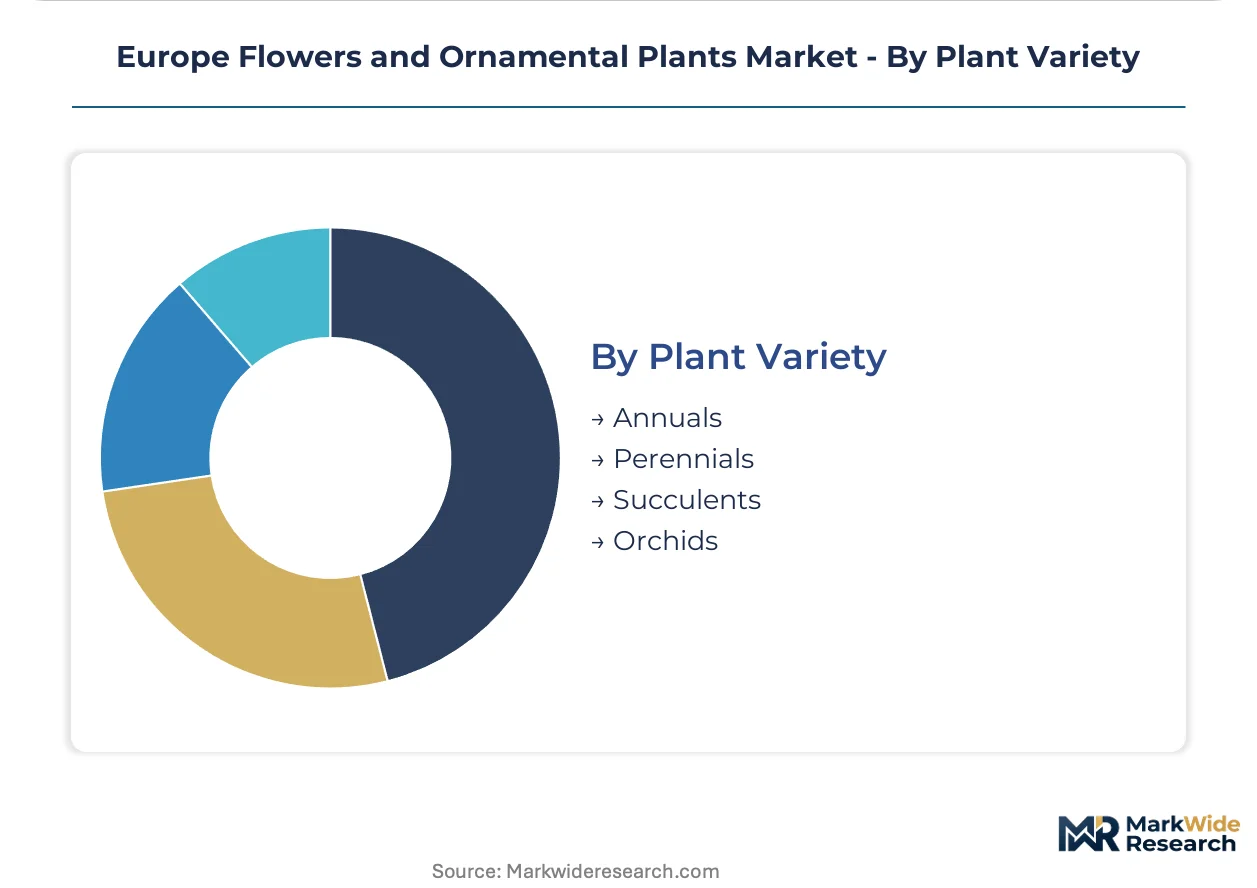
Plant Variety:
Biological characteristics determine suitability for indoor longevity, climate adaptability, and cultivation automation.
- Annuals:Single-season flowering species requiring yearly replanting. German and Belgian growers face compressed margins here due to REACH-driven substrate reformulation costs and peat-phaseout timelines.
- Perennials:Multi-year specimens returning seasonally from established rootstock. Landscaping demand concentrates this segment with municipal procurement favoring low-maintenance varieties for public spaces.
- Succulents:Water-storing desert-adapted plants suited to arid indoor conditions. Corporate interior styling pivots toward these for reduced irrigation requirements and extended service contract intervals.
- Orchids:Epiphytic tropical species with complex cultivation protocols. Dümmen Orange's genetics pipeline and Westland R&D clusters accelerate new cultivar commercialization for premium retail and commercial accounts.
Orchids capture the greatest revenue per square meter of greenhouse space; succulents are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Westland's greenhouse corridor functions as Europe's primary tax-advantaged floriculture zone, concentrating varietal R&D and auction infrastructure within a 40-kilometer radius. Dutch special economic zones for agricultural innovation channel capital into climate-controlled production. National carbon accounting frameworks now reshape investment flows toward lower-emission cultivation clusters.
Netherlands
Aalsmeer and Naaldwijk host Royal FloraHolland's auction infrastructure, processing roughly half of Europe's traded floriculture volume. The EU Green Deal's peat-phaseout timeline accelerates substrate reformulation investments across Westland greenhouses. Wageningen University's research corridor anchors breeding pipelines for climate-adapted orchids and succulents.
Germany
Berlin and Munich urban markets drive subscription plant service adoption, with metropolitan consumers showing strongest trial rates for curated monthly deliveries. REACH implementation schedules here run ahead of EU minimums, forcing earlier peat substitution in growing media. Lower Saxony's nursery belt concentrates bedding plant production for spring retail cycles.
United Kingdom
London's office districts convert fastest to living plant service contracts, driven by ESG reporting requirements for biophilic design credits. Defra enforces EU Plant Health Regulation 2016/2031 with additional national propagation material restrictions. Kent and Sussex greenhouse operations supply premium potted varieties direct to corporate accounts.
Poland
Warsaw and Krakow retail demand pulls orchid production eastward from Dutch sources. Lower land and labor costs attract Dutch capital for greenhouse expansion targeting Central European markets. Mazovia province clusters new climate-controlled facilities within 300-kilometer distribution radius of major cities.
Belgium
Flemish growers face compressed margins from accelerated national peat-phaseout schedules under REACH. Ghent's logistics hub coordinates cross-border distribution to French and German retail chains. East Flanders concentrates chrysanthemum propagation facilities serving EU-wide bedding plant demand.
Europe Flowers and Ornamental Plants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with varietal exclusivity commanding premium positioning in potted plants while cut flowers consolidate around auction volume. The vendor base organizes into three archetypes: integrated breeders with proprietary genetics, auction-platform operators controlling price discovery, and regional greenhouse specialists serving local retail chains. M&A activity concentrates on varietal portfolio acquisition and backward integration into propagation material. Capacity expansion targets Poland and Romania for cost-advantaged orchid production.
Within the integrated breeding tier, Syngenta Flowers and Dümmen Orange occupy positions anchored to varietal R&D pipelines and climate-adapted cultivar development. Royal FloraHolland exemplifies the auction-platform archetype, concentrating price discovery infrastructure at Aalsmeer and Naaldwijk. Among regional greenhouse operators, Dutch Flower Group and Beekenkamp represent scale-driven specialists with concentrated Westland production bases.
| Leading Market Players |
|---|
| Syngenta Flowers |
| Queens Group |
| Royal FloraHolland |
| Finlays |
| Selecta One |
| Dutch Flower Group |
| Beekenkamp |
| Washington Bulb |
| Dümmen Orange |
| Others |
Supply & Pricing Matrix
Peat substrate costs cascade through three pricing tiers as REACH-driven reformulation expenses compress margins at Dutch auction houses while premium-certified growers pass input premiums to ESG-motivated corporate buyers in London and Amsterdam.
Pricing Analysis
Short lead-time premiums command substantial markups for event florists fulfilling same-day corporate contracts, while spot inventory at Aalsmeer auctions trades at discounts during seasonal oversupply windows. Three-tier pricing structure across premium certified, standard auction-grade, and economy retail tiers separates growers with EU Green Deal verification from conventional operations. Pricing pressure stems from coconut coir and wood fiber substrate premiums that mid-scale Polish greenhouse operators struggle to pass downstream. Residential subscription buyers exhibit highest price sensitivity, whereas hospitality procurement managers prioritize longevity guarantees over unit cost.
Supply Chain Analysis
Seasonal labor availability in Romanian and Polish greenhouse zones constrains expansion timelines for Dutch capital deploying orchid production eastward. Supply concentrates in Netherlands, Poland, and Belgium, with propagation material drawing from Westland R&D clusters and Central European expansion zones. Coconut coir, peat alternatives, and specialized orchid genetics constitute critical input dependencies. Single-source vulnerability runs through Royal FloraHolland's auction infrastructure controlling half of European volume. Distribution runs through wholesale auction platforms, direct retail contracts, and emerging subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Plant Health Regulation 2016/2031 erects a compliance moat where early-certified nurseries capture pricing power while laggards face 18-36 month registration delays that strand R&D investment.
For Market Incumbents: Lock in varietal exclusivity through accelerated phytosanitary certification pipelines before regulatory backlogs extend. Secure long-term service contracts with London and Amsterdam corporate accounts to defend against subscription-channel disintermediation. Backward integration into peat-free substrate production insulates margin compression from REACH-mandated input cost inflation. For New Entrants and Emerging Players: Subscription plant services represent the most penetrable channel, with Berlin and Paris metropolitan consumers showing strongest trial rates for curated monthly deliveries. Target Polish greenhouse expansion zones where lower land and labor costs enable cost-advantaged orchid production for Central European retail demand. Partner with direct-to-consumer logistics platforms to bypass Royal FloraHolland auction fees. For Investors and Strategic Acquirers: Distressed-cycle entries favor varietal-specialist breeders in Netherlands Westland corridor facing temporary margin compression from substrate transition costs. Five-to-ten year viability hinges on intellectual property depth in climate-adapted cultivars. Watch for EU Green Deal implementation acceleration as inflection signal for premium-certified segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Peat-Free Substrate Transition | REACH compliance investment secures access to German and Belgian retail channels ahead of phaseout deadlines. |
| Closed-Loop Irrigation Deployment | Water recirculation systems cut input costs while satisfying Dutch national discharge permit requirements. |
| Living Plant Service Contracts | Multi-year corporate agreements with guaranteed replacement clauses displace cut-flower procurement in London districts. |
| Poland Greenhouse Expansion | Proximity to Warsaw and Krakow retail demand shortens cold-chain distances for orchid and succulent volume. |
| Biological Pest Management Integration | Wageningen-trained entomology expertise reduces agrochemical residues for EU Green Deal certification tiers. |
Research Methodology
Multi-period observation of auction price indices, substrate cost trajectories, and corporate contract conversion rates anchored the trend analysis, supplemented by interviews with Dutch greenhouse operators, Royal FloraHolland trading desk managers, German retail category buyers, Polish nursery expansion directors, and hospitality facility managers. Secondary validation drew from EU customs trade databases, ECHA REACH implementation reports, Royal FloraHolland transaction records, and national carbon accounting disclosures. Bottom-up cultivation cost modeling and top-down retail channel revenue triangulation converged on segment sizing.
Input-output matrices mapped propagation material flows through greenhouse production to distribution channel endpoints across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-use application, and plant variety biological characteristics. CAGRs were derived from installed capacity expansion schedules, auction volume trends, and corporate contract pipeline visibility. Forecast inputs incorporated LED lighting adoption curves and peat substitution timelines.
Caveats apply where EU Plant Health Regulation enforcement intensity, REACH substrate mandate acceleration, or logistics disruption at Aalsmeer could materially shift the outlook. Forecasts reflect assumptions around labor mobility in Central European greenhouse zones and corporate ESG reporting adoption rates. A small set of regulatory implementation triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Global Indoor Plant Market
Vegetables
Butternut Squash Market
Vegetables
United States Microgreens Market
Vegetables
UAE Tomato Market
Vegetables
Sweet Potatoes Market
Vegetables
North America Peas Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Global Mushroom Market
Vegetables
South America Peas Market
Vegetables
Dry Onion Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Europe Pea Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Dried Mushroom Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Vegetable Grader Market