
 Vegetable Grader Market | 2026-2036
Vegetable Grader Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Grader Market Analytics
EU Green Deal sustainability benchmarks are hardening the cost-of-entry calculus for vegetable grading equipment across European packhouses. TOMRA Systems leverages its optical sorting heritage to sustain premium positioning in automated potato and carrot lines. Bühler AG anchors its competitive stance through deep backward integration into sensor hardware and software stacks. Satake Corporation competes on rice-optics portability, extending its color-sorting expertise into leafy vegetable applications.
A vegetable grader is a post-harvest processing machine that sorts produce by size, weight, color, shape, and internal or external defect using mechanical screens, camera arrays, near-infrared spectroscopy, or robotic pickers operating at throughputs exceeding 15 tons per hour. Its primary commercial purpose is to reduce labor cost, minimize food waste, and ensure batch uniformity for retail shelf compliance and export phytosanitary standards. Optical graders now lead capital deployment as packhouses replace legacy mechanical units with camera-based systems capable of detecting bruising and rot below the skin surface. Robotics represents the fastest-expanding technology segment, though AI Integration captures the deepest margin pools through software licensing and predictive maintenance contracts. Agriculture Cooperatives remain the dominant end-user channel by installed base, while Exporters drive replacement cycles as destination markets tighten cosmetic grade specifications.
EMA food-contact material rules, EU Green Deal farm-to-fork traceability mandates, and CE marking for electromechanical safety collectively shape equipment design, software auditability, and market access for suppliers serving European buyers. FDA hazard analysis requirements for U.S.-bound exports further constrain grader sanitation protocols and wash-down ratings. Stakeholders must monitor how divergent phytosanitary data standards between the EU and major Asian import authorities reshape software localization and service attach rates.
Market Dynamics
Optical grading systems are displacing mechanical sorters as packhouses face EU Green Deal traceability mandates and retailer consolidation pressures demanding higher throughputs with defect detection below the skin surface.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:Traceability rules force packhouses to upgrade optical systems capable of batch-level digital logging for export compliance.
- Food retail consolidation in Germany:Supermarket chain mergers demand standardized cosmetic grades, pushing cooperatives toward automated lines exceeding 15 tons per hour.
- Near-infrared spectroscopy penetration:Camera arrays detecting internal bruising and rot now anchor replacement cycles in high-volume tomato and potato operations.
Market Restraints
- Sensor hardware cost volatility:Specialized CMOS and InGaAs detector prices fluctuate with semiconductor foundry capacity, compressing OEM margins on mid-tier graders.
- Technical limitation in leafy produce:Curved surfaces and moisture variability degrade color-sorting accuracy for spinach and lettuce varieties versus root vegetables.
- Regulatory friction from FDA-EMA divergence:Conflicting wash-down rating requirements for U.S.-bound exports force dual-specification engineering, raising unit costs.
Strategic Opportunities
- Robotic pick-and-place integration:Delta robots combined with AI defect classification open premium pricing in soft-fruit handling where mechanical damage risk is acute.
- Exporters in the Netherlands:Rotterdam-Antwerp port cluster investments in optical capacity create service attach-rate expansion for predictive maintenance contracts.
- EU AI Act compliance software:Auditability modules for algorithmic decision-making in grading decisions represent recurring revenue pools beyond hardware sales.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of camera-laser-robot integrated lines requires skills spanning optics, pneumatics, and Python-based diagnostics that agricultural labor pools lack.
- Legacy mechanical system integration:Retrofitting optical arrays onto existing roller tables without line shutdowns demands custom mechanical interfaces that extend deployment timelines.
- CE marking timeline compression:Electromechanical safety certification for new AI-enabled graders faces backlog at notified bodies, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Grader Market |
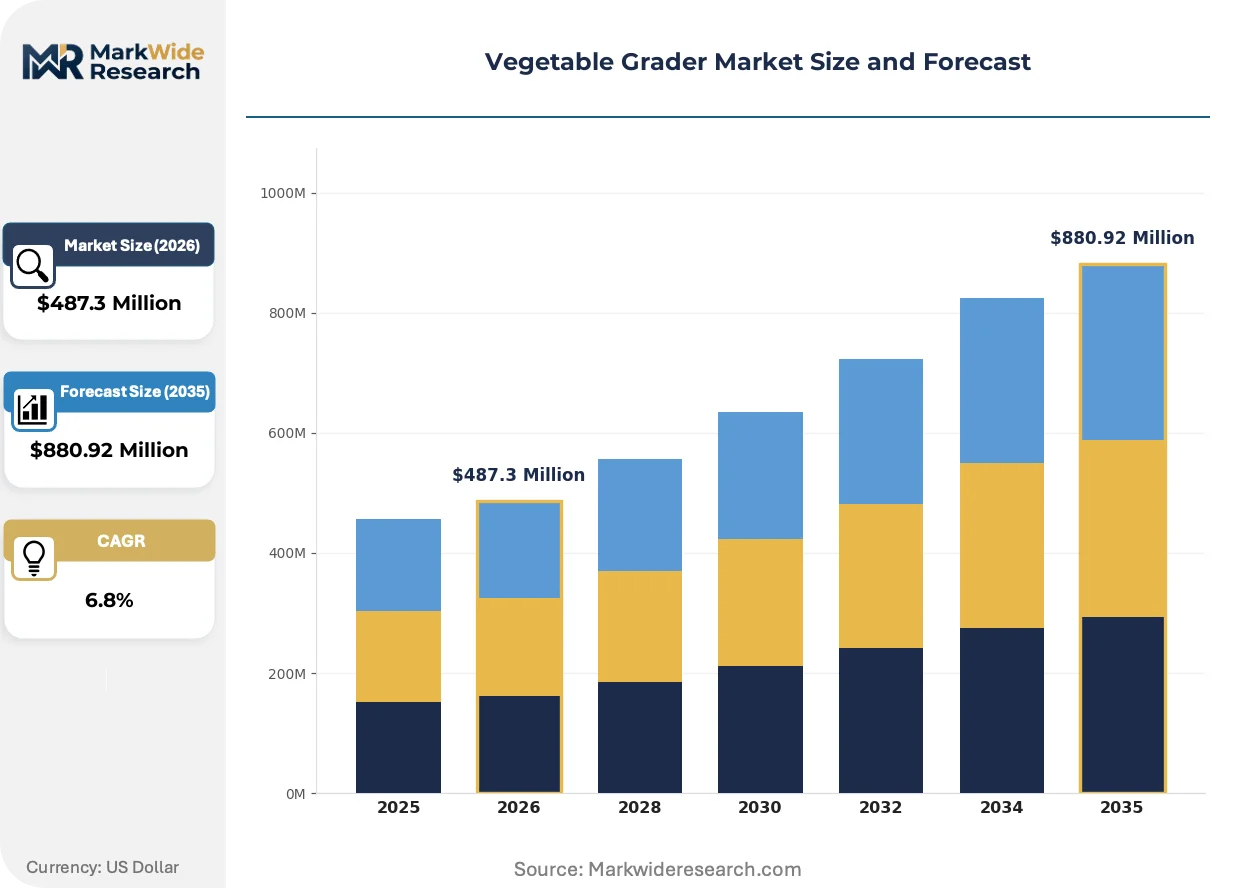
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
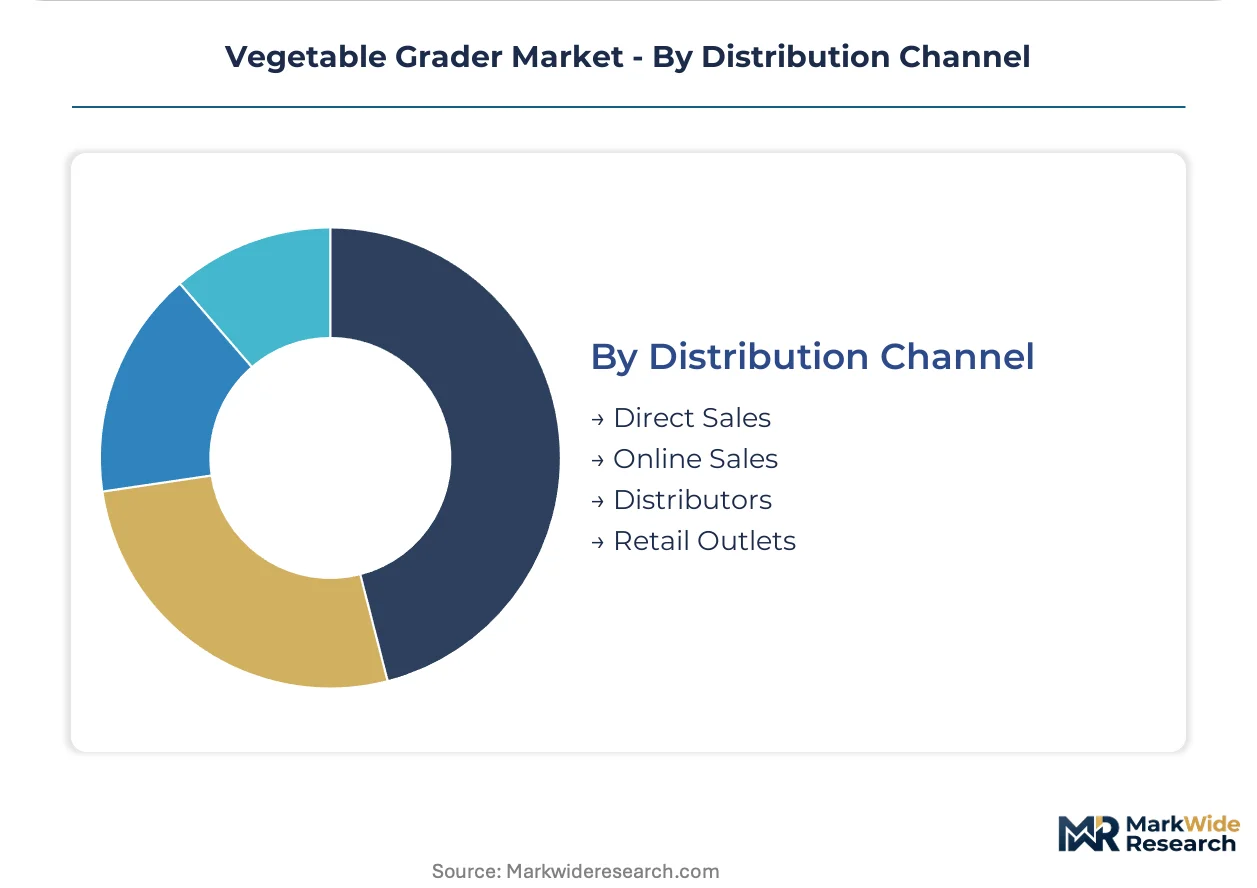
| Segmentation | Product Type: Mechanical Graders, Optical Graders, Manual Graders, Automated Graders Technology: Image Processing, Weight Sensors, Robotics, AI Integration End User: Agriculture Cooperatives, Sorting Facilities, Retail Chains, Exporters Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Outlets |
| Companies Covered | TOMRA Systems, Bühler AG, Satake Corporation, Key Technology, Inc., STEINERT, GREEFA, Newtec A/S, Sesotec GmbH, Raytec Vision S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Grader Market Evolving Landscape
Camera-based inspection architectures are fragmenting into configurable subsystems, allowing packhouses to upgrade resolution or add spectral channels without full line replacement. This modularity is compressing capital commitment cycles and reshaping vendor-customer relationships.
Hyperspectral imaging hardware is modularizing across potato and carrot processing lines, enabling packhouses to swap sensor heads between visible-NIR and SWIR configurations based on seasonal crop profiles. Mid-sized agricultural cooperatives in Germany and the Netherlands are adopting this flexibility to avoid stranded assets when cosmetic specifications tighten. The technology is modularizing competitive positioning, forcing pure-play optical vendors toward software and service bundling to defend margins.
EMA food-contact material rules now require full material traceability for conveyor belts and optical windows touching produce, adding documentation burdens to equipment sourcing. Manufacturers serving European packhouses must maintain substance databases spanning REACH SVHC lists and migration test protocols. Exporters targeting EU retail channels bear the heaviest compliance load, with Dutch packhouses already demanding supplier certifications as contract preconditions.
Cooperative procurement patterns are fragmenting as member-owned packhouses bypass traditional distributor networks for direct OEM relationships. German Raiffeisen-affiliated facilities now negotiate sensor-level service contracts separately from mechanical maintenance, unbundling historical full-line agreements. This disintermediation is most visible in North Rhine-Westphalia, where food retail consolidation has concentrated buying power among fewer packhouse decision-makers seeking price transparency.
Vegetable Grader Market Segmentation
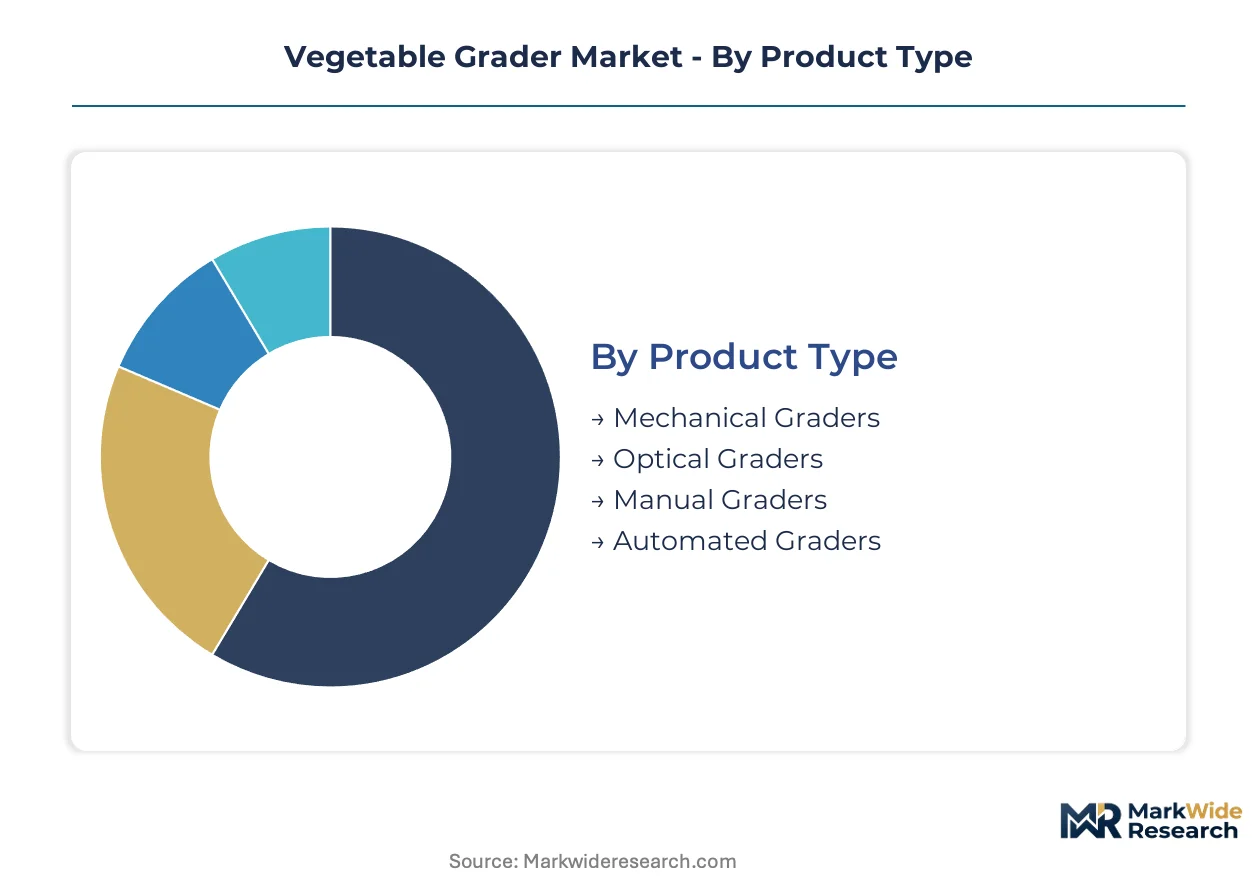
Grader procurement decisions hinge on crop type, throughput requirements, and compliance burdens. Packhouses segment their capital deployment across mechanical legacy lines, optical upgrades, and emerging robotic architectures based on labor cost trajectories and export destination rules.
Product Type:
Technology sophistication defines the capital expenditure tier and operational capability of each grader category.
- Mechanical Graders:Roller tables and mesh screens sort by dimensional thresholds using gravity and vibration. German potato cooperatives retain these for starch-grade processing where cosmetic defects carry no price penalty. Maintenance simplicity sustains installed base longevity in regions with limited technician availability.
- Optical Graders:Camera arrays paired with LED illumination detect surface blemishes, color variation, and shape irregularities at throughputs exceeding 15 tons per hour. Dutch fresh produce exporters deploy these to satisfy EU Green Deal batch traceability mandates for retail-bound consignments.
- Manual Graders:Human-operated inspection belts with manual ejection remain prevalent in smallholder cooperatives handling heritage varieties with irregular sizing. Low capital barriers preserve niche relevance where labor arbitrage still outweighs automation economics.
- Automated Graders:Fully integrated lines combining optical inspection with robotic handling and autonomous packaging. These systems command premium positioning in North Rhine-Westphalia packhouses serving consolidated supermarket chains with zero-defect cosmetic specifications.
Mature deployment sits with Mechanical Graders. Newer deployment is concentrated in Optical Graders.
Technology:
Sensor and software architectures determine detection depth, line speed, and predictive maintenance attach rates.
- Image Processing:Visible-spectrum camera systems with FPGA-based real-time analysis dominate surface defect detection in tomato and pepper operations. Dutch packhouses standardize on 5-micron resolution arrays to capture stem-end cracking invisible to mechanical sorters.
- Weight Sensors:Load-cell integration with reject mechanisms ensures batch uniformity for pre-pack retail formats. German carrot processors deploy these for fixed-weight bagging compliance with retailer private-label specifications.
- Robotics:Delta robots with vacuum end-effectors handle soft-fruit grading where mechanical contact risks bruising. These installations are expanding most quickly in Netherlands-based exporters targeting premium Asian market segments.
- AI Integration:Machine learning models trained on defect libraries enable predictive sorting accuracy improvements and anomaly detection for novel disease signatures. Software licensing and maintenance contracts generate recurring revenue streams beyond hardware margins.
Image Processing captures the deepest installed base. AI Integration commands the steepest expansion trajectory.
End User:
Procurement scale and specification stringency vary sharply across buyer categories.
- Agriculture Cooperatives:Member-owned packhouses with seasonal throughput volatility favor modular optical systems with lease financing. German Raiffeisen-affiliated facilities now unbundle sensor service contracts from mechanical maintenance agreements.
- Sorting Facilities:Dedicated third-party grading operations serving multiple grower clients demand line reconfigurability across crop types. Hyperspectral sensor head swapping capability supports seasonal transitions between root vegetables and leafy produce.
- Retail Chains:Direct procurement by supermarket groups concentrates buying power and standardizes cosmetic grade thresholds. Consolidated German chains now mandate digital traceability integration as a contract precondition.
- Exporters:Rotterdam-Antwerp port cluster operations face the tightest phytosanitary and cosmetic specifications. These buyers drive replacement cycles as destination markets harden import requirements.
Agriculture Cooperatives anchor historical volume. Exporters generate the fastest replacement demand.
Distribution Channel:
Channel selection reflects equipment complexity, service requirements, and buyer sophistication.
- Direct Sales:OEM field engineers handle specification, installation, and commissioning for integrated robotic lines. Large Dutch exporters negotiate direct relationships to secure predictive maintenance commitments and software upgrade schedules.
- Online Sales:Spare parts, sensor modules, and documentation flow through vendor portals. German cooperatives increasingly procure consumables and replacement cameras through digital channels for price transparency.
- Distributors:Regional equipment dealers provide local language support and financing arrangements for mid-tier optical graders. Historical full-line agreements are fragmenting as buyers seek component-level sourcing flexibility.
- Retail Outlets:Limited relevance for capital equipment; confined to small-scale manual grader sales for garden center and farm shop segments.
Direct Sales dominates high-complexity transactions. Online Sales is gaining share fastest in aftermarket components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in European packhouses facing EU Green Deal traceability mandates, with German retail consolidation and Dutch export hubs driving replacement cycles. Asian markets follow as destination specifications harden.
Germany
Food retail consolidation forces Raiffeisen-affiliated cooperatives toward automated lines exceeding 15 tons per hour. CE marking requirements for electromechanical safety shape equipment design timelines. North Rhine-Westphalia packhouses serving consolidated supermarket chains now mandate digital traceability integration as contract preconditions.
Netherlands
Rotterdam-Antwerp port cluster investments in optical capacity accelerate service attach-rate expansion for predictive maintenance contracts. EU Green Deal farm-to-fork traceability rules harden phytosanitary documentation burdens. Dutch fresh produce exporters deploy camera arrays capable of batch-level digital logging for retail-bound consignments.
United States
FDA hazard analysis requirements for vegetable grading equipment constrain sanitation protocols and wash-down ratings for export-bound lines. Divergent standards with EMA force dual-specification engineering on OEMs. California Central Valley packhouses handling tomato and potato volumes anchor domestic optical system deployment.
China
Domestic food safety modernization drives camera-based inspection adoption in Shandong and Hebei vegetable processing clusters. GB standards for food-contact materials add compliance layers to conveyor belt sourcing. Yangtze River Delta packhouses increasingly specify modular optical subsystems for seasonal crop flexibility.
India
FSSAI food safety regulations tighten cosmetic grade specifications for organized retail channels. Agricultural cooperatives in Maharashtra and Gujarat favor lease financing for modular optical systems with seasonal throughput volatility. Nashik and Indore packhouse clusters show fastest uptake of weight-sensor integration for fixed-weight retail packaging.
Vegetable Grader Market Competitive Landscape
German and Swiss producers anchor one tier; Japanese and Danish specialists hold differentiated positions in optical and robotic subsystems. The vendor base splits between consolidated electromechanical conglomerates with captive sensor production and focused optical technology boutiques. Three archetypes dominate: diversified industrial technology groups with backward integration into sensor hardware, pure-play sorting specialists leveraging software licensing, and regional fabricators competing on local service density. Competitive moves center on predictive maintenance contract expansion and hyperspectral sensor head modularity for seasonal crop reconfiguration.
Within the diversified technology tier, TOMRA Systems and Bühler AG exemplify integrated positioning through captive optical sorting heritage and deep sensor hardware stacks. Satake Corporation occupies a distinct geography-first position, extending color-sorting expertise from rice applications into leafy vegetable grading. These three anchors illustrate how competitive differentiation increasingly flows from software auditability and service attach rates rather than mechanical throughput specifications alone.
| Leading Market Players |
|---|
| TOMRA Systems |
| Bühler AG |
| Satake Corporation |
| Key Technology, Inc. |
| STEINERT |
| GREEFA |
| Newtec A/S |
| Sesotec GmbH |
| Raytec Vision S.p.A. |
| Others |
Value Network & Pricing Analysis
EU Green Deal traceability mandates are compressing procurement timelines for optical grading systems, forcing OEMs to absorb sensor hardware cost volatility while packhouses demand fixed-price service contracts spanning predictive maintenance and software auditability modules.
Pricing Analysis
High-volume throughput lines capture thin hardware margins while software licensing and service attach rates yield the deepest profitability pools. Three-tier pricing structure across premium robotic-integrated systems, standard optical arrays, and economy mechanical units differentiates based on detection depth and line speed specifications. Pricing pressure stems from semiconductor foundry capacity constraints affecting specialized CMOS and InGaAs detector supply. Agriculture cooperatives exhibit the highest price sensitivity due to seasonal throughput volatility, whereas Rotterdam-Antwerp exporters accept premium positioning for compliance-certain batch traceability.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss sensor hardware suppliers dominating high-precision optical component fabrication. Specialized LED illumination arrays, FPGA processing units, and food-grade conveyor materials draw from concentrated European and East Asian manufacturing bases. Tariff exposure on semiconductor-grade silicon substrates and rare-earth phosphors for spectral calibration presents structural risk to OEM margin stability. Distribution runs through direct OEM relationships for integrated robotic lines, with regional distributors handling mid-tier optical grader commissioning and aftermarket spare parts fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as EU AI Act compliance costs and CE marking backlogs force sub-scale optical vendors toward acquisition or exit.
For Market Incumbents: To counter hyperspectral sensor head modularity eroding hardware differentiation, TOMRA Systems and Bühler AG should deepen backward integration into captive InGaAs detector production while expanding predictive maintenance contract penetration among Dutch export packhouses. Certification preloading for FDA-EMA dual-specification engineering will defend positioning in transatlantic supply chains. For New Entrants and Emerging Players: Capture white-space opportunity in lease-financed modular optical subsystems for German Raiffeisen-affiliated cooperatives facing seasonal throughput volatility. Target Maharashtra and Gujarat agricultural clusters in India where FSSAI cosmetic grade tightening outpaces local OEM service density. Lead with software-first positioning emphasizing EU AI Act auditability modules rather than hardware throughput specifications. For Investors and Strategic Acquirers: The window for entry favors mid-cap optical technology boutiques with established sensor hardware stacks and installed base relationships in Netherlands port cluster operations. Long-term viability hinges on recurring revenue attach rates exceeding hardware depreciation cycles. Watch for inflection when notified body CE marking backlogs clear and AI-enabled grader deployment accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Sensor Modularity | Enables seasonal crop reconfiguration without full line replacement, defending margins against stranded asset risk. |
| Predictive Maintenance Contract Expansion | Captures recurring revenue from Rotterdam-Antwerp exporters facing EU Green Deal uptime requirements. |
| EU AI Act Compliance Software Preloading | Accelerates market entry by eliminating notified body audit delays for algorithmic decision documentation. |
| Backward Integration into Detector Fabrication | Insulates margin stability from semiconductor foundry capacity volatility affecting InGaAs supply. |
| Direct OEM Relationship Cultivation | Bypasses distributor fragmentation to secure specification control with consolidated German retail chain suppliers. |
Research Methodology
Multi-period observation of optical grader deployment rates, CE marking approval timelines, and service contract attach rates anchored the trend analysis, supplemented by interviews with packhouse operations directors, OEM product managers, agricultural cooperative procurement leads, and notified body certification specialists. Secondary validation drew from EU Green Deal regulatory filings, FDA hazard analysis guidance documents, customs trade data on food processing machinery, and SEC disclosures from listed sorting technology suppliers. Bottom-up equipment shipment tracking and top-down agricultural processing capacity estimates were triangulated to cross-verify market sizing.
Input-output matrix modeling linked grader technology penetration curves to crop-specific processing volumes, segmentation dimensions spanning product type, technology architecture, end-user category, and distribution channel across the analysis window. CAGRs were derived from fitted growth trajectories applied to base-year installed base estimates and replacement cycle assumptions. Industry-specific forecast inputs included EU AI Act implementation timelines and phytosanitary standard convergence patterns between EMA and major Asian import authorities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply chain disruptions, regulatory divergence on wash-down specifications, and technician labor pool constraints affecting maintenance service scalability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Tomato Market
Vegetables
Dried Vegetable Market
Vegetables
Sprouts Market
Vegetables
South America Peas Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Vegetable Chutney Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Potato Market
Vegetables
Fresh Vegetables Market
Vegetables
Roselle Market
Vegetables
Europe Pea Market
Vegetables
Yams Market
Vegetables
IQF Vegetables Market
Vegetables
Dry Onion Market
Vegetables
UAE Tomato Market