
 Italy Greenhouse Horticulture Market | 2026-2036
Italy Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Greenhouse Horticulture Market Insights
Italian protected-crop acreage is expanding across the Veneto and Sicily belts as domestic producers respond to supermarket chain procurement mandates for year-round local supply. Priva sustains its technology leadership through advanced climate-computer installations in the Bergamo and Brescia clusters. Signify NV dominates LED horticultural lighting deployment across large-scale tomato and pepper operations in Puglia. Certhon specializes in turnkey greenhouse engineering for Mediterranean climate adaptations, anchoring its project pipeline in the Ragusa province.
Greenhouse horticulture denotes the cultivation of plants within enclosed or semi-enclosed structures where temperature, humidity, light spectra, and CO2 levels are actively managed to optimize photosynthetic efficiency and yield consistency. These systems typically employ glass or polymer cladding with thermal screens, drip fertigation, and integrated heating to maintain growing environments between 18°C and 26°C for vegetable crops. Vegetables command the dominant product position due to sustained retail demand for tomatoes, peppers, and leafy greens from Po Valley operations. Hydroponics represents the fastest-expanding technology segment as water-stressed regions in southern Italy adopt recirculating nutrient-film systems to reduce consumption. Commercial growers concentrate margin pools through long-term supply agreements with organized retail chains, while home gardeners remain a fragmented, price-sensitive channel.
Italy's greenhouse sector operates under EU REACH chemical safety rules for crop protection inputs, the EU F-Gas Regulation governing refrigeration and climate-control equipment, and national CEA standards administered through regional agricultural agencies in Lombardy and Emilia-Romagna. These frameworks elevate capital requirements for new entrants while rewarding operators that invest in closed-loop water systems and biological pest management protocols. Stakeholders must track how upcoming EU CSRD sustainability disclosure mandates will reshape lender risk assessments and buyer qualification criteria for protected-crop suppliers.
Market Dynamics
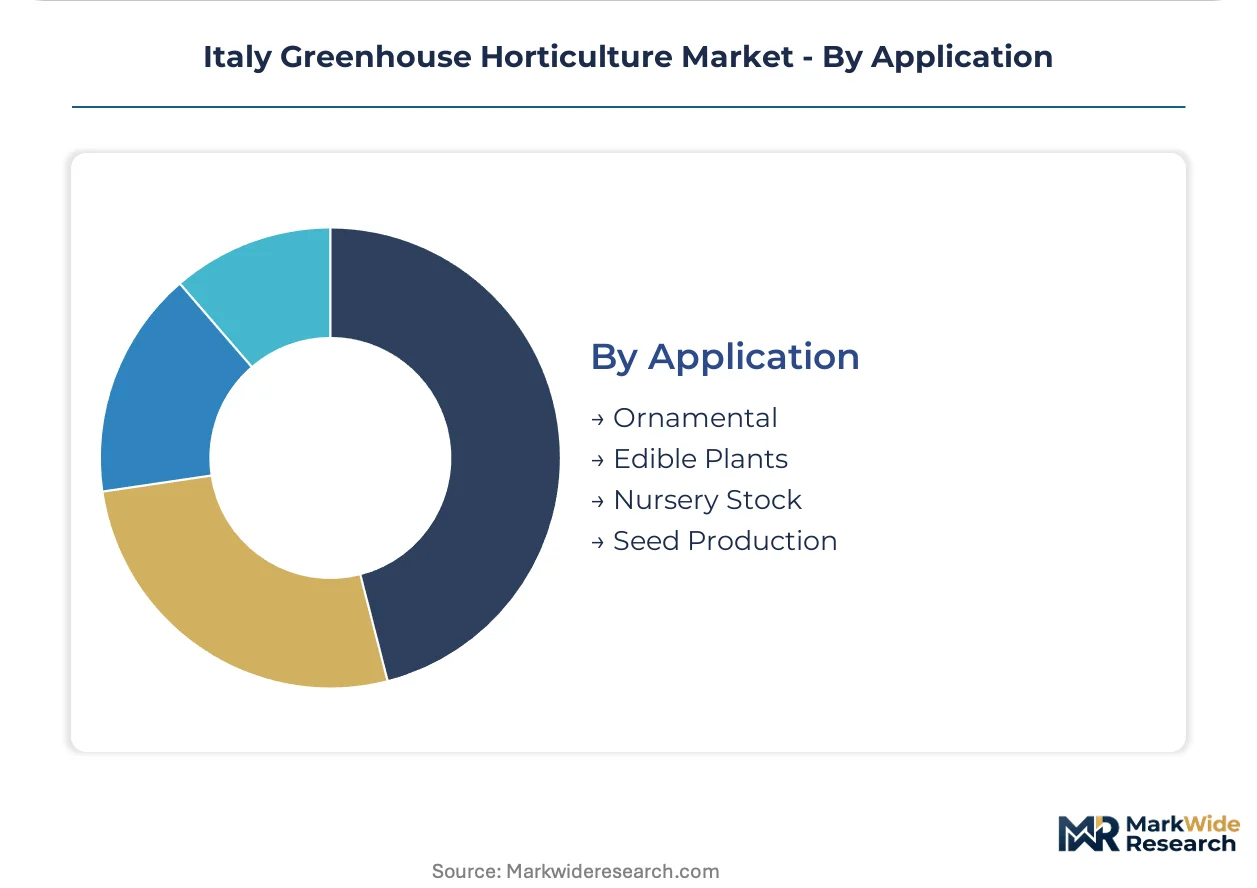
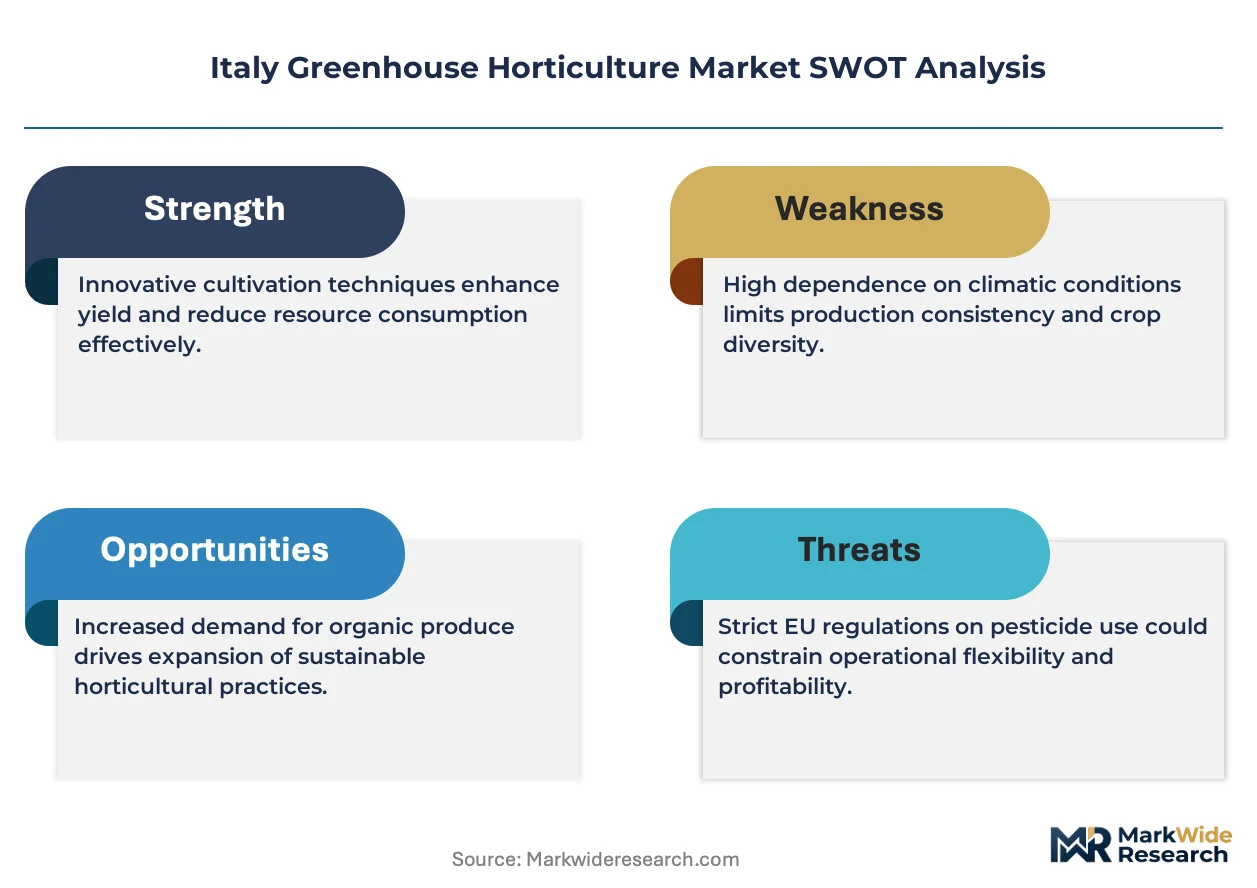
Italian protected-crop operators face intensifying margin compression as energy costs for climate control and EU F-Gas compliance obligations reshape capital allocation priorities across the Po Valley corridor.
Growth Catalysts
- EU Green Deal capital flows:Italy's National Recovery and Resilience Plan channels public funding into climate-smart greenhouse infrastructure, lowering debt service burdens for operators modernizing heating and irrigation systems.
- Organized retail procurement mandates:Supermarket chains across Lombardy and Veneto now require year-round local supply contracts, pulling acreage expansion toward soilless production methods.
- Hydroponic water efficiency:Nutrient-film recirculation systems cut consumption in water-stressed southern regions, enabling cultivation in Ragusa and Puglia zones previously deemed unsuitable for intensive horticulture.
Market Restraints
- Natural gas price volatility:Thermal energy constitutes the dominant operating cost input for Veneto and Lombardy glasshouse operations, exposing margins to wholesale commodity swings.
- Equipment import concentration:Climate computers, LED arrays, and precision irrigation hardware concentrate sourcing from Dutch and German suppliers, creating forex and lead-time vulnerabilities.
- EU REACH compliance burden:Crop protection input registration timelines extend 18-24 months, slowing biological pest management adoption relative to conventional chemical alternatives.
Strategic Opportunities
- Sicily acreage white space:Ragusa province offers unexploited solar irradiance advantages for winter tomato production, with logistics connectivity improving through Catania port upgrades.
- CSRD disclosure readiness:Early alignment with EU Corporate Sustainability Reporting Directive standards qualifies operators for preferential green-lending terms from Italian agricultural credit consortia.
- Direct-to-foodservice channels:Restaurant groups and institutional caterers in Milan and Bologna seek bypass procurement from certified greenhouse operators, escaping conventional wholesale markups.
Industry Challenges
- Climate-control technician scarcity:Bergamo and Brescia clusters compete for limited talent pools capable of maintaining Priva and comparable environmental computer installations.
- Legacy glasshouse retrofit timelines:Converting 1980s-era soil-based structures to hydroponic substrate systems demands 24-36 month capital deployment cycles with uncertain yield guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Greenhouse Horticulture Market |
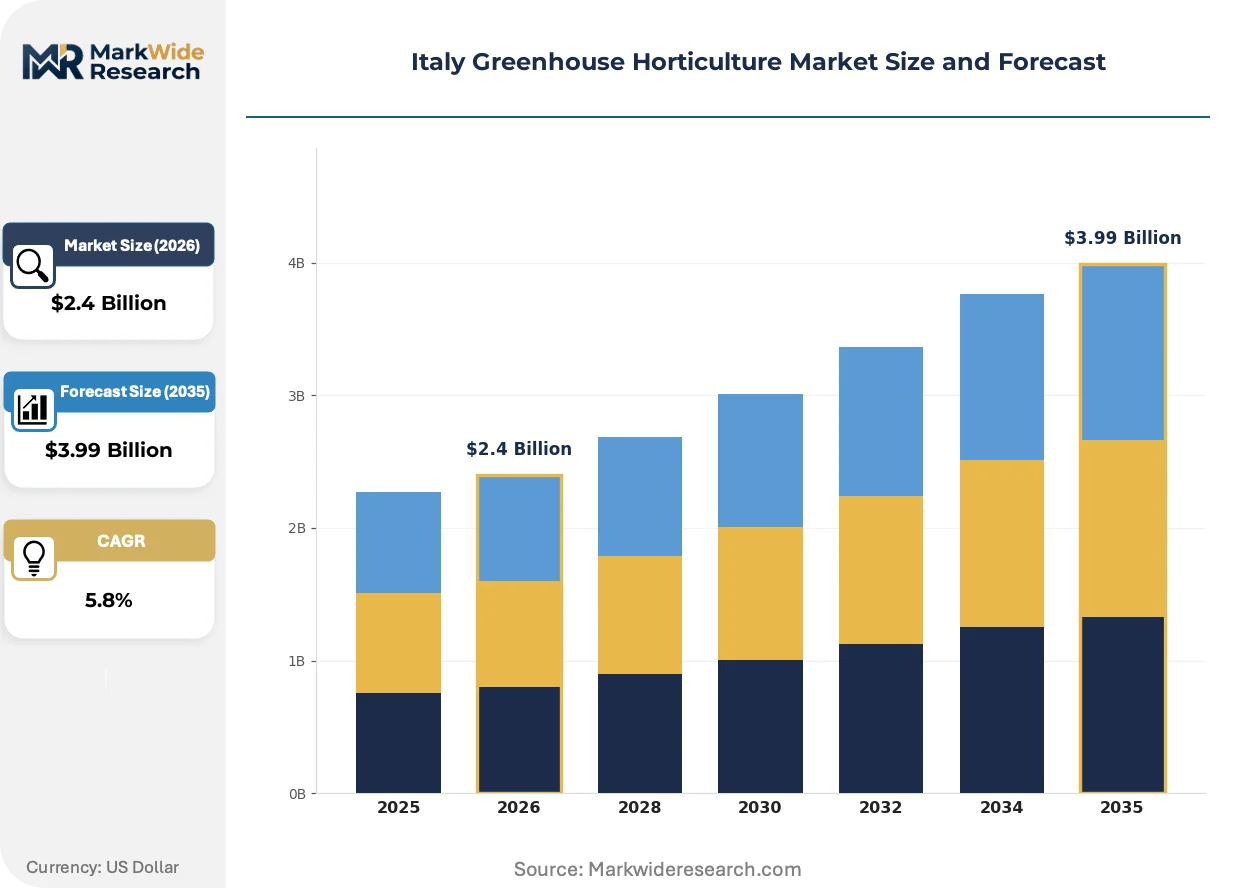
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Flowers, Herbs, Fruits Technology: Hydroponics, Aeroponics, Soil-Based, Integrated Pest Management End User: Commercial Growers, Research Institutions, Home Gardeners, Wholesalers Application: Ornamental, Edible Plants, Nursery Stock, Seed Production |
| Companies Covered | Hoogendoorn Growth Management, Richel Group, Priva, Signify NV, NETAFIM, Certhon, Ridder Group, Greenyard NV, Dalsem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Greenhouse Horticulture Market Trends and Innovations
Italian greenhouse horticulture is experiencing a technology-led productivity transition as digital climate management converges with biological cultivation methods and retail-driven traceability requirements.
Spectral-tunable LED arrays are rewriting the economics of year-round pepper and tomato production in Puglia operations. Large-scale growers are retrofitting high-wire glasshouses with dynamic light recipes that optimize photomorphogenic responses across growth stages. This compression of vegetative cycle variability enables synchronized harvest windows that match just-in-time supermarket replenishment schedules.
EU F-Gas Regulation phase-down mandates are accelerating heat-pump adoption across Emilia-Romagna protected-crop facilities. The industrial consequence is a wholesale shift from fossil-fuel boiler dependency toward electric climate control with thermal battery storage. Tomato operations in the Po Valley corridor face the steepest retrofit urgency given their heating load intensity and proximity to urban air-quality monitoring zones.
Cooperative procurement consortia among independent growers are displacing individual supply negotiations with organized retail buyers. These aggregation structures concentrate volume leverage for Bergamo-area leaf-greens producers seeking shelf-space commitments from northern Italian supermarket banners. The model is most visible in Lombardy, where producer organizations now handle logistics, quality certification, and price benchmarking for member farms.
Italy Greenhouse Horticulture Market Segmentation
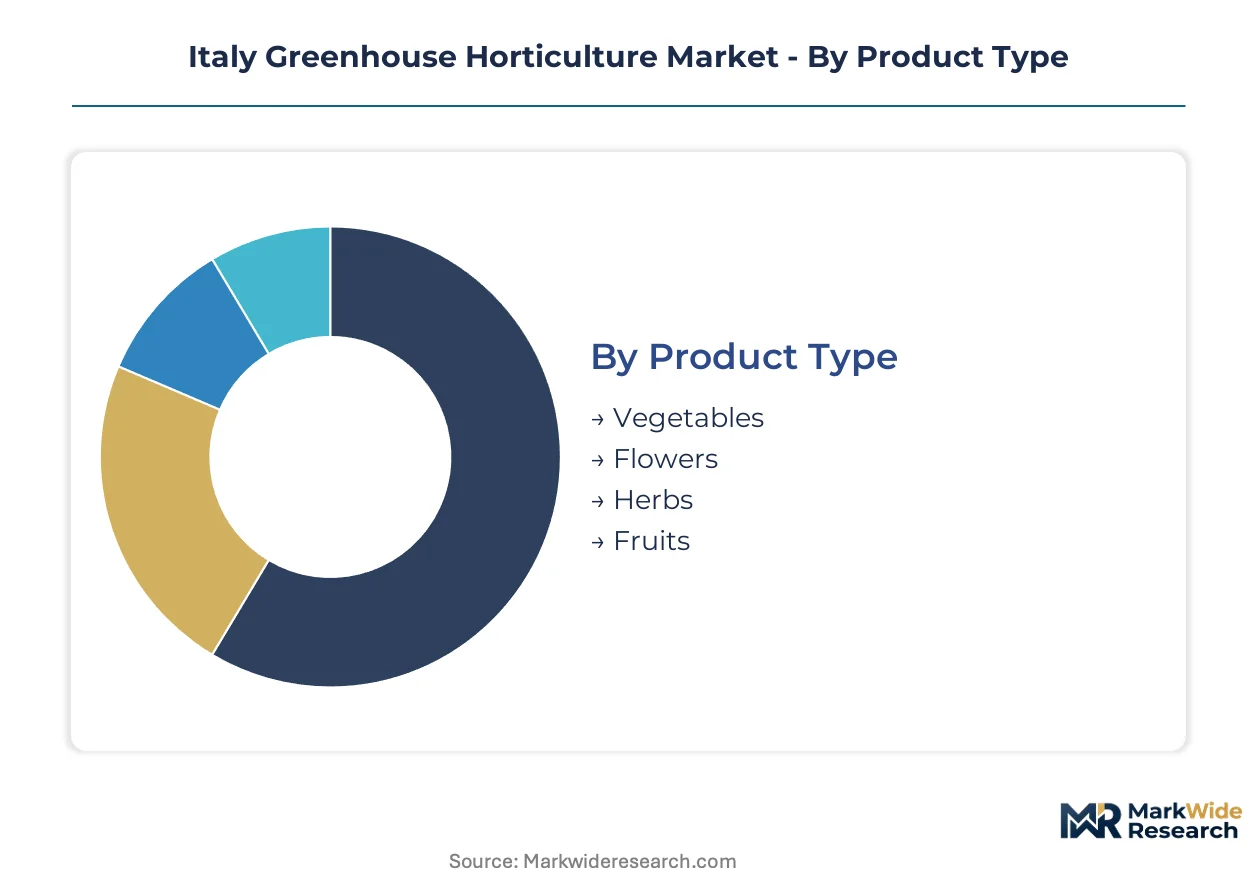
Italian greenhouse horticulture segments along production purpose, cultivation method, buyer category, and output destination. Each axis shapes capital intensity, margin structure, and regulatory exposure for operators across the Po Valley and southern belts.
Product Type:
Vegetable cultivation commands the dominant share of protected acreage, with tomato, pepper, and leafy green operations concentrated in Lombardy and Veneto glasshouse clusters. Flower production concentrates margin pools through varietal specialization in Ligurian and Tuscan export-oriented facilities.
- Vegetables:Tomato and pepper operations dominate Po Valley acreage, utilizing high-wire hydroponic systems to meet year-round procurement mandates from organized retail chains across Milan and Bologna. Heating intensity and CO2 supplementation requirements elevate capital barriers for new entrants in this segment.
- Flowers:Ornamental production clusters in Liguria and Tuscany, serving export corridors into France and Germany through specialized varietal breeding programs. Margin stability depends on phytosanitary certification alignment with EU plant passport regulations.
- Herbs:Basil and oregano operations concentrate in Sicily and Puglia, exploiting solar irradiance advantages for aromatic oil concentration.
- Fruits:Strawberry and melon protected cultivation remains niche, limited by pollination management complexity and perishability constraints in domestic distribution.
Vegetables lead on scale; herbs lead on momentum.
Technology:
Cultivation method selection determines water efficiency, labor requirements, and input standardization for Italian operators navigating southern water stress and northern energy cost pressures.
- Hydroponics:Nutrient-film and deep-water recirculation systems now dominate new greenhouse construction in Ragusa and Puglia, cutting water consumption versus soil-based alternatives. Adoption accelerates where EU Green Deal funding subsidizes infrastructure conversion.
- Soil-Based:Legacy substrate operations persist across Emilia-Romagna, constrained by longer crop rotation cycles and higher fumigation compliance burdens under EU REACH protocols.
- Aeroponics:Root-mist systems remain experimental, confined to research station demonstrations and high-value herb propagation.
- Integrated Pest Management:Biological control protocols utilizing beneficial insects and pheromone disruption expand fastest in organic-certified Veneto leaf-greens operations.
Hydroponics leads on scale; integrated pest management leads on momentum.
End User:
Buyer category shapes contract structure, volume predictability, and price discovery mechanisms across Italian protected-crop supply chains.
- Commercial Growers:Large-scale operators in Bergamo and Brescia clusters supply supermarket banners through multi-year volume agreements with indexed pricing. Cooperative procurement consortia now aggregate negotiating leverage for independent producers.
- Wholesalers:Traditional market intermediaries in Milan and Rome wholesale halls face margin compression as direct retail contracts displace spot market transactions.
- Research Institutions:University and CREA facilities drive varietal trialing and climate-control optimization, transferring proven protocols to commercial adoption.
- Home Gardeners:Fragmented hobbyist demand concentrates in garden center retail, price-sensitive and seasonal.
Commercial growers lead on scale; research institutions lead on momentum.
Application:
Output destination determines quality specifications, traceability requirements, and shelf-life engineering priorities for Italian greenhouse operators.
- Edible Plants:Food-grade production dominates acreage allocation, with GLOBALG.A.P. and GRASP certification now mandatory for supply into Coop and Conad banners. Post-harvest cold chain integration shapes regional competitiveness.
- Ornamental:Decorative plant output serves garden center and municipal landscaping channels, with cyclical demand tied to spring planting seasons.
- Nursery Stock:Young plant propagation supplies regional open-field transplant operations, requiring virus-indexing protocols under EU plant health regulations.
- Seed Production:Hybrid seed multiplication remains specialized, concentrated in isolated Sicilian facilities to prevent cross-pollination contamination.
Edible plants lead on scale; nursery stock leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian greenhouse operators exploit regulatory-arbitrage opportunities as southern regions absorb production migrating from northern energy-cost pressures. The EU Green Deal's asymmetric implementation creates compliance-cost gaps between member states, redirecting investment toward Mediterranean solar-advantaged zones.
Lombardy
Bergamo and Brescia clusters dominate high-wire tomato and leafy green operations supplying Milan supermarket banners. The region's National Recovery and Resilience Plan allocations subsidize climate-computer retrofits and thermal screen installations. Priva maintains technology leadership through advanced environmental control deployments across the Po Valley glasshouse belt.
Veneto
Year-round procurement mandates from organized retail chains pull acreage expansion toward soilless production in the Verona and Padua corridors. EU F-Gas Regulation phase-down timelines accelerate heat-pump adoption across protected-crop facilities. Cooperative procurement consortia now aggregate negotiating leverage for independent leaf-greens producers seeking shelf-space commitments.
Emilia-Romagna
Bologna-area operators face the steepest retrofit urgency given heating load intensity and urban air-quality monitoring zone proximity. The region's agricultural credit consortia offer preferential green-lending terms for CSRD disclosure-ready operators. Tomato operations concentrate margin pools through long-term supply agreements with organized retail chains.
Sicily
Ragusa province offers unexploited solar irradiance advantages for winter tomato production, with logistics connectivity improving through Catania port upgrades. Hydroponic nutrient-film recirculation systems cut water consumption in this historically water-stressed zone. Certhon anchors its turnkey greenhouse engineering pipeline in Mediterranean climate adaptations across the province.
Puglia
Large-scale pepper and tomato operations deploy spectral-tunable LED arrays to compress vegetative cycle variability for synchronized harvest windows. Signify NV dominates horticultural lighting deployment across these facilities. The region's adoption of dynamic light recipes enables just-in-time supermarket replenishment schedule matching.
Italy Greenhouse Horticulture Market Competitive Landscape
Dutch technology providers anchor one tier; Italian and Belgian operators hold cultivation-integration positions. The vendor base concentrates around climate-control hardware, irrigation engineering, and lighting systems rather than crop production itself. Three archetypes dominate: greenhouse technology integrators, precision agriculture hardware specialists, and horticultural lighting manufacturers. Consolidation pressure manifests through strategic partnerships between equipment vendors and regional grower cooperatives, plus technology licensing arrangements that transfer Dutch cultivation protocols to Mediterranean operators.
Within the technology-integrator tier, Hoogendoorn Growth Management and Ridder Group exemplify Dutch environmental-computer leadership, while Certhon occupies a position in turnkey greenhouse engineering for climate-adapted Mediterranean installations. Priva represents the climate-control specialist archetype with established presence across northern Italian glasshouse clusters. Signify NV anchors the horticultural lighting segment through large-scale LED deployments in southern Italian vegetable operations. Greenyard NV sits within the integrated cultivation-and-distribution model, connecting protected-crop production with organized retail channels.
| Leading Market Players |
|---|
| Hoogendoorn Growth Management |
| Richel Group |
| Priva |
| Signify NV |
| NETAFIM |
| Certhon |
| Ridder Group |
| Greenyard NV |
| Dalsem |
| Others |
Pricing and Supply Chain Analysis
Organized retail procurement concentration across Lombardy and Veneto anchors contract-based pricing structures where supermarket banners dictate indexed volume agreements with soilless growers. This buyer dominance compresses margin pools for independent operators while rewarding cooperative consortia with shelf-space leverage and price stability.
Pricing Analysis
Retailer markup layers dominate downstream value capture, with direct-to-foodservice channels offering 15-20 point margin premiums over wholesale hall transactions. Price differentiation stratifies across GLOBALG.A.P. certification tiers, organic compliance levels, and volume scale commitments. Cost compression in thermal energy inputs is intensifying because natural gas price volatility exposes Veneto glasshouse operations to margin erosion. Home gardeners exhibit highest price sensitivity, while institutional caterers in Milan demonstrate lowest sensitivity due to traceability premiums.
Supply Chain Analysis
Refurbishment flows for climate-control hardware concentrate in Dutch engineering hubs, with used Priva environmental computers re-entering Italian operations through secondary dealer networks. Geographic supply concentration draws from the Netherlands for automation systems, Germany for precision irrigation hardware, and China for LED component substrates. Raw material dependencies rest on aluminum extrusions for greenhouse structures, semiconductor chips for climate computers, and phosphor substrates for horticultural lighting. Single-source vulnerability characterizes Dutch climate-computer sourcing. Distribution runs through cooperative procurement consortia aggregating Bergamo-area leaf-greens for northern Italian supermarket banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian greenhouse horticulture functions as a stable compounder where EU Green Deal capital flows provide durable infrastructure funding tailwinds across the Po Valley corridor.
For Market Incumbents: Lock in long-term supply agreements with Conad and Coop banners before CSRD disclosure mandates reshape buyer qualification criteria. Deepen backward integration into captive substrate production to offset fertilizer input volatility. Prioritize heat-pump retrofits in Emilia-Romagna facilities to secure preferential green-lending terms from agricultural credit consortia.
For New Entrants and Emerging Players: The premium-economy price-point gap in certified organic leaf-greens offers white-space entry through cooperative consortia aggregation models. Target Sicily's Ragusa province for unexploited solar irradiance advantages in winter tomato production. Pursue direct-to-foodservice channels in Milan and Bologna to bypass wholesale markup compression.
For Investors and Strategic Acquirers: Agricultural technology integrators are the most active acquirer in this space, consolidating climate-control hardware vendors with regional grower cooperatives. Five-to-ten year viability rests on water-stressed southern expansion and biological pest management adoption velocity. Acquisition target archetypes include Certhon-engineered turnkey operators with Mediterranean climate adaptation IP. Monitor EU F-Gas Regulation phase-down timelines as inflection indicator for heat-pump retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Retrofit Program | EU F-Gas Regulation compliance secures preferential lending from Emilia-Romagna agricultural credit consortia. |
| Cooperative Procurement Consortium Formation | Volume aggregation enables Bergamo leaf-greens producers to negotiate shelf-space commitments from Conad. |
| CSRD Disclosure Alignment | Early sustainability reporting qualification opens green-lending terms and retail buyer preferential status. |
| Hydroponic Substrate Conversion | Nutrient-film recirculation systems cut water consumption for Ragusa province expansion into water-stressed zones. |
| Direct-to-Foodservice Channel Development | Bypass procurement from Milan restaurant groups escapes conventional wholesale margin compression. |
Research Methodology
Direct dialogue with greenhouse operators, agricultural credit consortium officers, supermarket category buyers, climate-control technicians, and EU regulatory affairs specialists grounded qualitative insights. Secondary validation drew from EU Green Deal implementation documents, National Recovery and Resilience Plan allocation disclosures, F-Gas Regulation compliance filings, and CREA agricultural research publications. Bottom-up acreage and yield estimates triangulated against top-down capital flow tracking across the analysis window.
Segment-level projections incorporated cultivation method adoption curves, technology penetration rates by region, and buyer category contract structures across the projection horizon. The analytical framework modeled product type, technology, end user, and application dimensions alongside regional regulatory cluster variations. CAGRs were derived from capital deployment trajectories and procurement mandate enforcement timelines. Key inputs included EU Green Deal funding disbursement schedules and organized retail local sourcing commitment trajectories.
Caveats apply where natural gas price volatility, Dutch equipment import lead-time disruptions, or EU REACH registration delays could materially shift the outlook. Forecasts reflect assumptions around subsidy continuity and retail procurement mandate adherence. Practitioners should monitor EU CSRD disclosure rollout pace and F-Gas phase-down enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Europe Christmas Tree Market
Vegetables
Yams Market
Vegetables
Fresh Vegetables Market
Vegetables
North America Sweet Potatoes Market
Vegetables
Garden Cress Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
UAE Tomato Market
Vegetables
Sprouts Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
United States Microgreens Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
North America Christmas Tree Market