
 Asparagus Market | 2026-2036
Asparagus Market Size, Share, and Industry Trends Forecast 2026-2036
Asparagus Market Intelligence
Food processors is rotating toward frozen asparagus as a core ingredient in prepared meals and convenience foods. Dole plc leverages its integrated supply chain from Peruvian growing regions to North American retail freezers. Fresh Del Monte Produce Inc. anchors its competitive stance through year-round sourcing from multiple hemispheres. Greenyard N.V. specializes in value-added frozen and canned formats for European private-label customers.
Asparagus comprises the young shoots of Asparagus officinalis, a perennial flowering plant species whose spears are harvested at 15-25 centimeters for optimal tenderness and sugar content before lignification hardens the stalk. The vegetable serves as a premium fresh produce item, a blanched frozen ingredient, and a thermally processed canned good across retail and foodservice channels. Fresh asparagus commands the highest margin pool in supermarket produce sections, while frozen formats capture growing demand from food processors seeking consistent year-round supply. Canned asparagus retains stable volume in institutional foodservice, though it faces substitution pressure from fresher alternatives in retail.
The USDA enforces phytosanitary import standards that condition market access for Peruvian and Mexican asparagus entering the United States. The EU Green Deal and REACH frameworks impose escalating sustainability and chemical residue requirements on asparagus sold within European supermarkets. California's agricultural labor regulations under OSHA and state-level standards shape production costs for domestic US growers. Stakeholders must monitor how evolving phytosanitary protocols and carbon-border adjustments will reroute trade flows between established suppliers and emerging growing regions.
Market Dynamics
The asparagus market's competitive structure hinges on Peru's dominance as a year-round supplier to temperate-zone retail channels, creating dependency risks for North American and European buyers while concentrating margin capture among vertically integrated Peruvian exporters.
Growth Catalysts
- EU Green Deal sustainability mandates:European supermarkets now require carbon-footprint disclosures and reduced chemical residues, favoring certified Peruvian growers who invested early in integrated pest management and water-efficient drip irrigation.
- Food processor format migration:Frozen asparagus demand from ready-meal manufacturers is accelerating as blanching and IQF technologies preserve texture parity with fresh spears across extended supply chains.
- Peruvian coastal valley concentration:The Ica and La Libertad regions maintain 12-month production cycles through controlled irrigation from the Andes, securing shelf space in US and EU retail freezers during northern hemisphere winter gaps.
Market Restraints
- Input cost volatility:Peruvian asparagus farming depends on imported urea and potassium fertilizers, with prices tracking volatile natural gas benchmarks and Russian supply disruptions.
- USDA phytosanitary friction:Asparagus imports from Mexico and Peru face inspection bottlenecks at US southern border ports, creating spoilage risk for fresh consignments and favoring frozen alternatives.
- Fresh-to-frozen substitution pressure:Canned asparagus volumes in US institutional foodservice are compressing as K-12 and healthcare operators upgrade to frozen spears for improved plate appearance and nutrient retention.
Strategic Opportunities
- Chinese domestic premiumization:Urban tier-one supermarkets in Shanghai and Beijing are expanding imported fresh asparagus sections for middle-class consumers seeking Western dietary patterns.
- Controlled-environment agriculture convergence:Greenhouse asparagus production using LED supplemental lighting and hydroponic substrates is enabling northern European growers to capture premium local-origin pricing during import gaps.
- Indian cold-chain infrastructure expansion:Government PLI scheme investments in refrigerated transport and packhouse capacity are opening export-quality asparagus cultivation in Maharashtra and Karnataka for Gulf and Southeast Asian markets.
Industry Challenges
- Perishable logistics coordination:Fresh asparagus requires continuous cold chain maintenance at 0-2°C from field to retail shelf, with temperature excursions causing lignification and sugar loss within 48 hours.
- REACH compliance documentation:EU importers must maintain exhaustive chemical residue testing records across multiple pesticide categories, with non-compliance triggering rapid alert system notifications and shipment rejections.
- Harvest labor availability:Hand-cutting asparagus spears at precise 15-25 centimeter lengths demands skilled seasonal workers, with California's escalating agricultural wage regulations and immigration enforcement compressing domestic US supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asparagus Market |
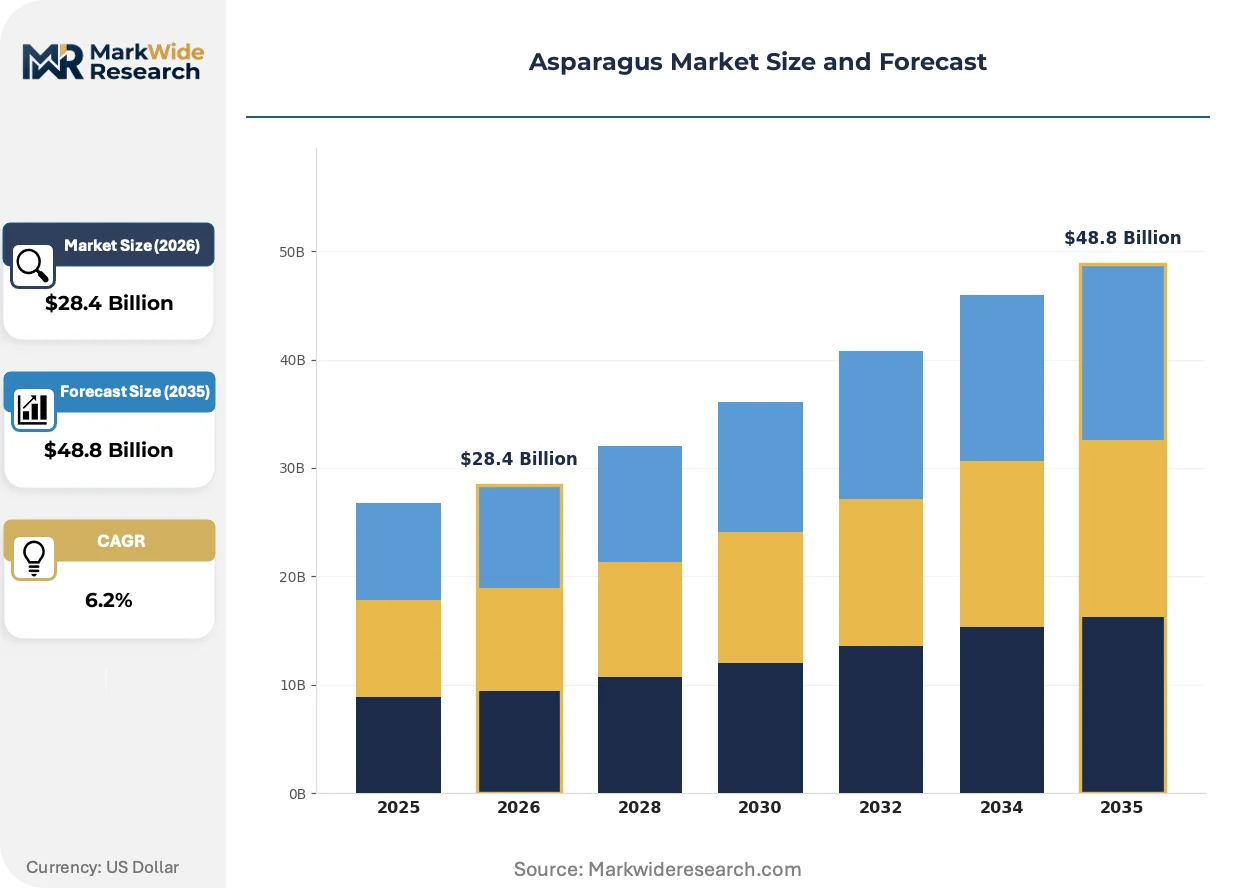
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $48.8 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Canned, Frozen, Dried End User: Households, Restaurants, Food Processors, Retailers Distribution Channel: Supermarkets, Online Stores, Farmer's Markets, Wholesalers Packaging Type: Plastic Bags, Cardboard Boxes, Bulk Containers, Jars |
| Companies Covered | B&G Foods, Inc., Fresh Del Monte Produce Inc., Dole plc, Teboza Asparagus, Greenyard N.V., Camposol S.A., Altar Produce LLC, Maf Roda Group, Danper Trujillo S.A.C., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asparagus Market Strategic Shifts & Innovations
Processing technology and regulatory frameworks are actively fragmenting how asparagus moves from field to consumer, with frozen formats gaining manufacturing share while fresh positioning narrows toward premium retail channels.
Individual quick freezing combined with optical sorting is bifurcating the processed asparagus segment. Food manufacturers adopting IQF lines with camera-based defect detection can source lower-grade fresh spears while delivering consistent finished product appearance. This technology compression is enabling frozen asparagus to displace canned formats in institutional channels and capture prepared-meal ingredient slots previously reserved for fresh.
The EU Green Deal's Farm-to-Fork strategy is tightening maximum residue limits for pesticides across imported produce. Asparagus exporters to European markets must now demonstrate compliance with EFSA-reviewed active substances and accelerated withdrawal intervals. Peruvian growers with early GLOBALG.A.P. certification are securing preferential listing terms with German and Dutch retail chains, while uncertified competitors face delisting risk.
Retail procurement patterns are consolidating around year-round supply guarantees rather than seasonal spot purchasing. North American supermarket chains are awarding multi-year frozen asparagus contracts to Peruvian exporters with integrated cold storage at destination ports. This contract concentration is visible most acutely in US Midwest and Northeast markets, where retailers prioritize inventory predictability over origin flexibility.
Asparagus Market Segmentation
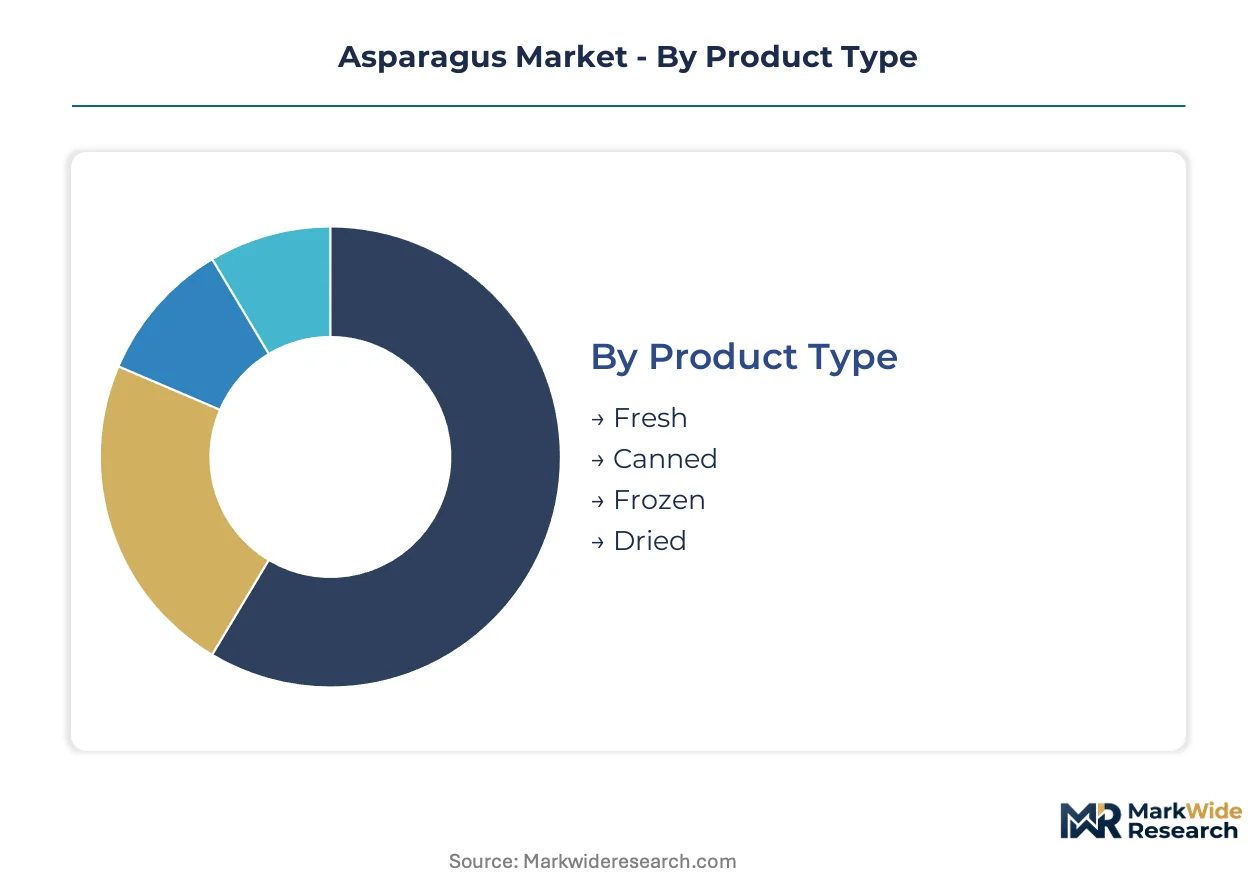
Asparagus supply chains fragment across preservation states and buyer specifications, with each segment carrying distinct regulatory burdens and margin profiles. Understanding how product formats, end-user requirements, and distribution pathways intersect determines procurement strategy and compliance investment priorities.
Product Type:
REACH and EU Green Deal residue limits apply differentially across preservation states, with fresh formats facing the strictest phytosanitary scrutiny at European ports.
- Fresh:Spears harvested at 15-25 centimeters maintain cellular integrity through hydrocooling and continuous 0-2°C cold chains. German and Dutch retail chains now mandate carbon-footprint disclosures alongside EFSA-reviewed pesticide documentation, favoring Peruvian growers with GLOBALG.A.P. certification.
- Frozen:Individual quick freezing combined with optical sorting enables food processors to source lower-grade fresh spears while delivering consistent finished product appearance. Blanching and IQF technologies preserve texture parity with fresh spears across extended supply chains, accelerating displacement of canned formats in institutional channels.
- Canned:Thermally processed spears in brine retain stable volume in US institutional foodservice despite substitution pressure from frozen alternatives. K-12 and healthcare operators increasingly upgrade to frozen spears for improved plate appearance.
- Dried:Dehydrated asparagus products serve niche applications in snack formulations and powdered ingredient blends, with limited commercial scale compared to wet-preserved alternatives.
Established volume favors fresh spears in premium retail; emerging adoption favors frozen formats in prepared-meal manufacturing.
End User:
Cost tier differentiation separates commodity procurement from specification-driven sourcing, with food processors optimizing for year-round price stability while households trade freshness for convenience.
- Households:Direct consumer purchases concentrate in supermarket produce sections during spring harvest windows, with Peruvian imports extending availability through northern hemisphere winter gaps.
- Restaurants:Foodservice operators demand consistent spear diameter and color grading for plate presentation, sourcing through specialized produce distributors with quality-controlled supply agreements.
- Food Processors:Ready-meal manufacturers drive the steepest expansion trajectory in frozen asparagus procurement, prioritizing IQF formats that integrate into automated production lines without thaw variability.
- Retailers:Supermarket chains award multi-year frozen asparagus contracts to Peruvian exporters with integrated cold storage at destination ports, prioritizing inventory predictability over origin flexibility.
Volume concentration sits with retailers; margin expansion sits with food processors.
Distribution Channel:
Customer type determines channel selection, with institutional buyers routing through wholesalers while quality-sensitive consumers bypass intermediaries at farmer's markets.
- Supermarkets:Chain retailers dominate fresh asparagus volume through direct contracts with Peruvian exporters, leveraging centralized distribution networks to maintain cold chain integrity from port to shelf.
- Online Stores:E-commerce platforms capture growing subscription-box demand for specialty asparagus varieties, though perishability constraints limit geographic reach without refrigerated last-mile infrastructure.
- Farmer's Markets:Local growers in California and Michigan sell direct to consumers during domestic harvest windows, commanding premium pricing for same-day harvested spears.
- Wholesalers:Terminal market distributors aggregate volume from multiple origins for redistribution to independent grocers and foodservice operators, absorbing spoilage risk in their margin structure.
Scale economies favor supermarket centralization; premium capture favors farmer's market disintermediation.
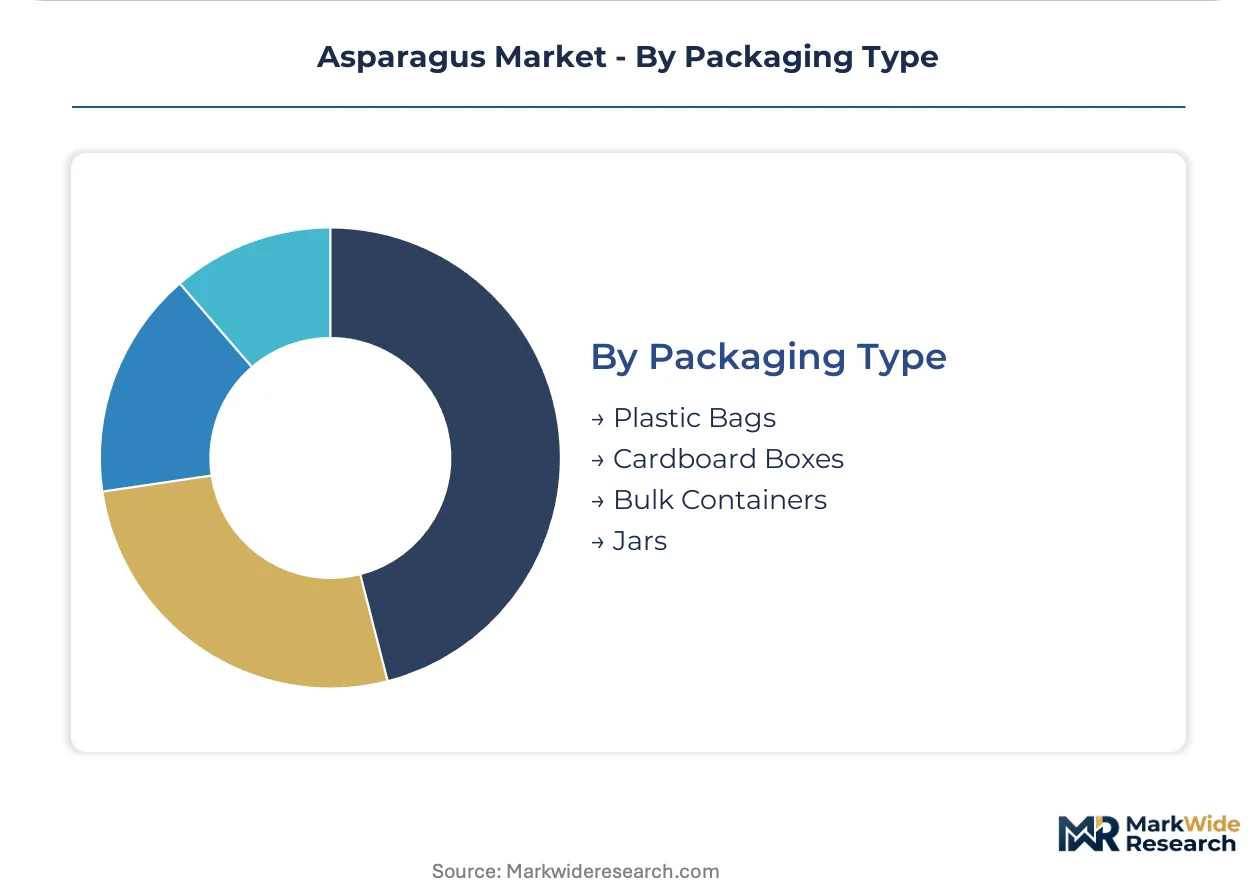
Packaging Type:
Supply concentration in Peruvian export corridors shapes packaging standardization, with ocean freight efficiency driving bulk container adoption for frozen formats.
- Plastic Bags:Perforated polyethylene pouches dominate fresh retail packs, balancing moisture retention with gas exchange to delay lignification during shelf display.
- Cardboard Boxes:Corrugated containers with modified atmosphere lining protect fresh spears through international air freight, meeting supermarket specifications for arrival condition.
- Bulk Containers:Frozen asparagus moves in palletized totes from Peruvian processing plants to North American cold storage facilities, minimizing handling points that compromise temperature control.
- Jars:Glass packaging for premium marinated asparagus products serves gift and specialty retail channels with extended ambient shelf stability.
Operational efficiency favors bulk containers; brand differentiation favors jar presentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru ships year-round harvests to refrigerated distribution centers across the United States and Germany, filling seasonal gaps in temperate-zone production calendars. Mexican growers supply fresh spears through expedited truck corridors into Texas and California retail networks. Chinese cultivation clusters serve expanding domestic premium segments while piloting export-grade cold-chain protocols.
United States
Supermarket chains in the Midwest and Northeast award multi-year frozen asparagus contracts to secure inventory predictability through winter months. USDA phytosanitary inspections at southern border ports create spoilage risk for fresh Mexican consignments. California's Central Valley hosts domestic spring harvest operations constrained by escalating agricultural wage regulations under state OSHA standards.
Germany
German retail chains now mandate carbon-footprint disclosures alongside EFSA-reviewed pesticide documentation for all imported fresh produce. The EU Green Deal's Farm-to-Fork strategy tightens maximum residue limits, favoring certified Peruvian suppliers with GLOBALG.A.P. certification. The Hamburg port cluster serves as the primary European entry point for refrigerated container vessels from South American growing regions.
Peru
The Ica and La Libertad coastal valleys maintain 12-month production cycles through controlled irrigation from Andean water sources. Peruvian exporters with integrated cold storage at destination ports capture multi-year supply agreements with North American retailers. Vertically integrated growers in these regions invested early in integrated pest management and drip irrigation systems to meet EU sustainability mandates.
China
Urban tier-one supermarkets in Shanghai and Beijing expand imported fresh asparagus sections for middle-class consumers adopting Western dietary patterns. The country's national agricultural regulator enforces escalating chemical residue standards for domestic production. Shandong Province cultivation clusters pilot greenhouse asparagus production using LED supplemental lighting to capture premium local-origin pricing.
India
Government PLI scheme investments in refrigerated transport and packhouse capacity enable export-quality asparagus cultivation in Maharashtra and Karnataka. Domestic cold-chain infrastructure expansion targets Gulf and Southeast Asian market access for premium fresh spears. The Food Safety and Standards Authority of India enforces residue testing protocols aligned with EFSA-reviewed substance lists for export-bound production.
Asparagus Market Key Industry Players
Player mix skews toward vertically integrated South American growers with captive cold-chain assets and North American produce conglomerates with multi-origin sourcing networks. The competitive structure concentrates margin capture among Peruvian exporters controlling year-round supply to temperate-zone retail channels. Two strategic archetypes dominate: integrated growing-to-retail operators with destination-port cold storage, and branded produce marketers with hemisphere-diversified sourcing. Capacity expansion and strategic partnerships represent the dominant competitive moves as retailers prioritize supply guarantee contracts over spot purchasing.
Within the integrated South American tier, Camposol S.A. and Danper Trujillo S.A.C. exemplify vertically structured operators with Andean valley production bases and refrigerated logistics infrastructure. Among North American produce marketers, Dole plc and Fresh Del Monte Produce Inc. occupy positions as multi-commodity distributors with established retail freezer penetration. Greenyard N.V. represents the European private-label specialist archetype, focusing on value-added frozen and canned formats for supermarket chain customers.
| Leading Market Players |
|---|
| B&G Foods, Inc. |
| Fresh Del Monte Produce Inc. |
| Dole plc |
| Teboza Asparagus |
| Greenyard N.V. |
| Camposol S.A. |
| Altar Produce LLC |
| Maf Roda Group |
| Danper Trujillo S.A.C. |
| Others |
Cost & Logistics Intelligence
Multi-year offtake agreements between Peruvian exporters and North American supermarket chains lock in both supply access and price visibility through northern hemisphere winter gaps, insulating buyers from spot-market volatility while securing margin capture for vertically integrated growers with destination-port cold storage.
Pricing Analysis
Fresh-versus-frozen format pricing gaps structure buyer procurement calculus across the asparagus market. Three-tier pricing stratification separates GLOBALG.A.P.-certified premium spears from standard-grade fresh and economy frozen lots, with certification tier and volume scale as primary differentiation drivers. Cost compression in economy frozen lots is intensifying because food processors demand consistent year-round supply without origin flexibility. Retail chains exhibit the highest price sensitivity, while prepared-meal manufacturers prioritize specification stability over unit cost.
Supply Chain Analysis
Inventory lead times stretch from Andean field harvest through 14-21 day ocean transit to North American cold storage, compressing fresh-format windows and accelerating frozen-format migration. Supply concentrates in Peru, Mexico, and the United States, with Peruvian coastal valleys anchoring year-round volume. Farming operations draw from imported urea and potassium fertilizers, with Russian supply disruptions and natural gas price volatility feeding input cost uncertainty. Distribution runs through vertically integrated exporters with captive port-side refrigeration, bypassing traditional terminal market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asparagus supply fragmentation creates white-space opportunities as EU Green Deal mandates splinter procurement requirements across certification tiers, enabling specialist growers to capture premium niches unavailable to undifferentiated volume players.
For Market Incumbents: Consolidate backward integration into Andean irrigation infrastructure and destination-port cold storage to defend against emerging greenhouse operators in northern Europe. Secure GLOBALG.A.P. certification ahead of EFSA-reviewed substance withdrawals to maintain German and Dutch retail listings. Capacity addition in Peru's La Libertad region anchors supply guarantee contracts against Mexican competitors facing USDA phytosanitary friction. For New Entrants and Emerging Players: Differentiate on controlled-environment agriculture with LED supplemental lighting to capture premium local-origin pricing during import gaps in Germany and the Netherlands. Target greenhouse asparagus production in Shandong Province for Chinese tier-one supermarkets seeking reduced chemical residue profiles. Pursue direct-to-processor sales of IQF formats bypassing retail intermediary margins. For Investors and Strategic Acquirers: Capital is best deployed toward vertically structured Peruvian exporters with integrated logistics assets and multi-year contract backlogs, as these operators capture margin concentration from year-round supply dependency. Long-term viability hinges on water-rights security in Ica and La Libertad valleys amid Andean glacial retreat. Watch EU carbon-border adjustment implementation timing as inflection indicator for certified versus uncertified supplier valuation spreads.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigation Infrastructure | Andean water rights secure 12-month production cycles against climate-driven supply interruption. |
| Destination-Port Cold Storage Expansion | Peruvian exporters with US Gulf Coast refrigeration capture multi-year retailer contracts. |
| GLOBALG.A.P. Certification Investment | Early compliance with EU Green Deal residue limits prevents German retail delisting risk. |
| IQF Processing Line Addition | Optical sorting technology enables food processor contracts with lower-grade fresh input. |
| Greenhouse Production Pilot | LED-supplemented hydroponic systems capture premium pricing in northern European import gaps. |
Research Approach
A spread of perspectives from Peruvian export operations managers, German retail category buyers, US food processor procurement directors, and EU regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from USDA phytosanitary filings, EFSA residue limit databases, EU Green Deal implementation guidance, and Peruvian agricultural ministry export statistics. Bottom-up volume triangulation across preservation formats and end-use segments was cross-checked against top-down trade flow analysis.
Segmentation dimensions modeled include product preservation state, end-user category, distribution channel type, and packaging format across the analysis window. CAGRs were derived from trend extrapolation of historical trade volumes adjusted for regulatory implementation schedules and technology adoption curves. Forecast inputs incorporated EU Farm-to-Fork pesticide withdrawal timelines and food processor automation investment patterns.
Material uncertainties — fertilizer price volatility, phytosanitary inspection bottlenecks, and carbon-border adjustment implementation — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Air Dried Vegetables Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Dried Peas Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Sprouts Market
Vegetables
Global Indoor Plant Market
Vegetables
Squash Market
Vegetables
Yarrow Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Microgreens Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
Field Peas Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
South America Peas Market